
 Toy Dog Market | 2026-2036
Toy Dog Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Dog Market Analytics
Modular toy-and-treat bundling is shifting buyer choice toward curated monthly boxes that pair breed-specific play items with consumables. KONG Company leverages its rubber compound expertise to anchor premium durability positioning. Benebone competes through nylon chew specialization that targets aggressive small-breed chewers. West Paw differentiates via domestic manufacturing and closed-loop recycling of its Zogoflex material.
A toy dog denotes companion canines typically weighing under twenty pounds, bred for domestic cohabitation rather than working function, with skeletal miniaturization achieved through selective breeding across multiple generations. The category serves residential pet keepers seeking animals adapted to confined indoor spaces with reduced exercise requirements. Chihuahua and Yorkshire Terrier segments dominate transaction volume due to established breeder networks and recognizable breed standards. Subscription Service payment models represent the fastest-expanding revenue channel as direct-to-consumer platforms capture recurring spend from digitally native owners. Online Retail distribution leads value capture, though Pet Stores sustain margin pools through impulse accessory attachment and immediate product validation.
The American Kennel Club maintains breed conformation standards that govern show eligibility and shape commercial breeding priorities. The USDA Animal Welfare Act and state-level puppy lemon laws regulate interstate commerce and consumer protection, respectively. The FDA Center for Veterinary Medicine oversees nutritional claims on treat-inclusive toy bundles. Stakeholders must monitor evolving municipal breed restrictions and import quarantine protocols that could alter regional supply accessibility.
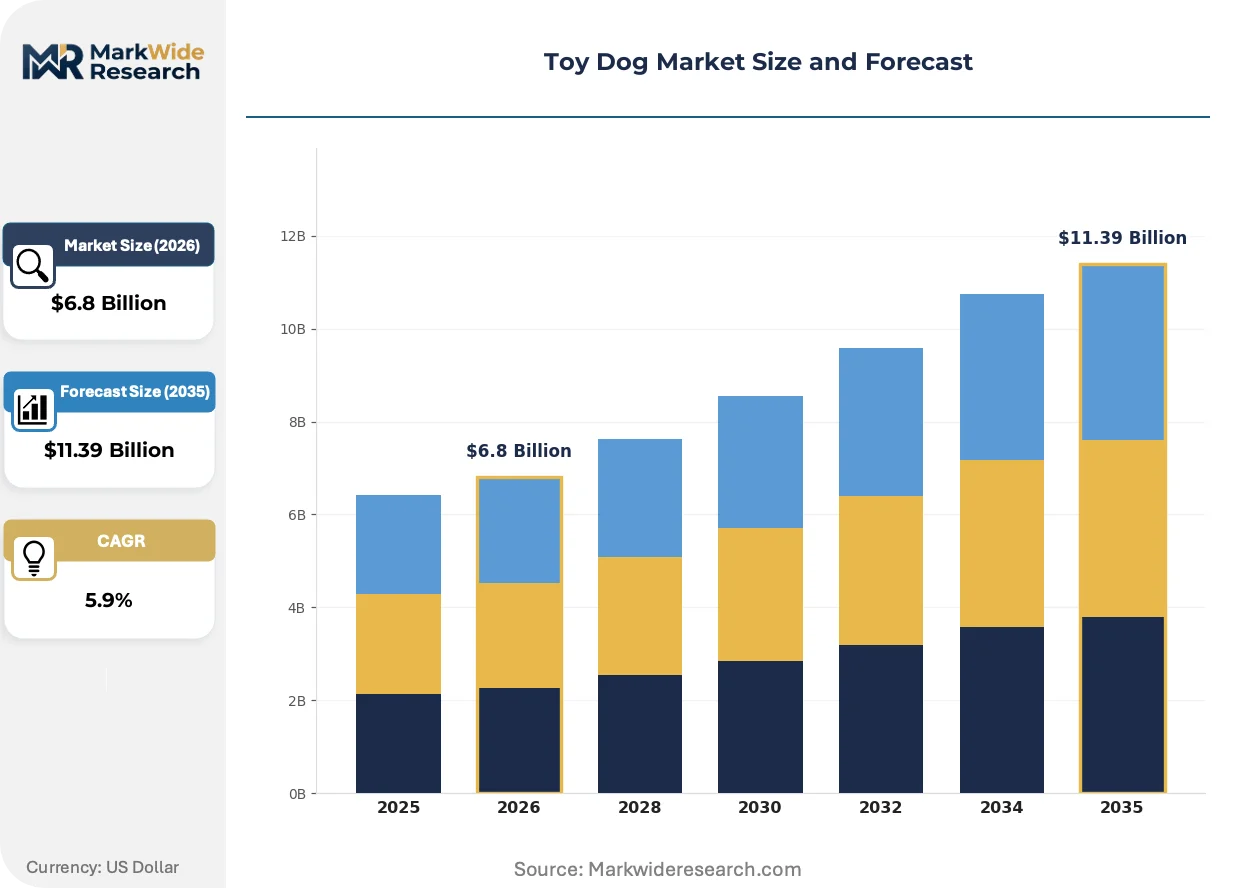
Market Dynamics
Subscription bundling of breed-specific toys and consumables is compressing traditional retail margins while capturing recurring revenue from digitally native pet owners across urban markets.
Growth Catalysts
- USDA Animal Welfare Act:Interstate commerce regulations standardize breeder certification, expanding the pool of compliant commercial suppliers eligible for retail partnerships.
- Closed-loop recycling:Domestic manufacturing with recyclable Zogoflex material appeals to sustainability-motivated buyers in premium urban segments.
- Japan's METI pet industry guidelines:National standards for companion animal welfare elevate consumer trust and transaction velocity in East Asian markets.
Market Restraints
- Veterinary genetic testing costs:Mandatory health protocol compliance raises breeder operational expenses, compressing margins for small-scale operations.
- Municipal breed restrictions:Local ordinances in major US metropolitan areas limit addressable demand for specific toy breeds.
- Import quarantine protocols:Extended isolation requirements for live animal transport create supply bottlenecks from established European breeder networks.
Strategic Opportunities
- United Kingdom urban clusters:High-density London and Manchester residential markets show underpenetrated subscription service adoption relative to US benchmarks.
- FDA nutritional claim pathways:Treat-inclusive bundle positioning leverages veterinary diet regulations to justify premium pricing tiers.
- Direct-to-consumer platforms:Recurring payment models bypass pet store intermediaries, capturing full margin on digitally engaged owner cohorts.
Industry Challenges
- AKC conformation standard updates:Breeder networks face re-certification timelines when show eligibility criteria shift, disrupting inventory planning cycles.
- Genetic health protocol integration:Veterinary screening requirements demand capital investment in diagnostic partnerships or in-house testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Dog Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Breed Type: Chihuahua, Pomeranian, Pekingese, Yorkshire Terrier Age Group: Puppy, Adult, Senior, Mixed Age Payment Model: One-time Purchase, Subscription Service, Payment Plan, Auction Distribution Channel: Online Retail, Pet Stores, Breeders, Adoption Centers |
| Companies Covered | GoughNuts, Benebone, KONG Company, ZippyPaws, Chuckit!, West Paw, Jolly Pets, Outward Hound, Petmate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Dog Market Evolving Landscape
Digital platforms are fragmenting traditional distribution hierarchies while material science advances and regulatory transparency mandates reshape product development cycles.
Smart dispensing systems embedded with portion-control algorithms are decentralizing feeding routine management from owner memory to automated monitoring. Urban apartment dwellers with irregular schedules adopt these devices at accelerating rates. This technology is decentralizing brand loyalty from legacy food manufacturers to hardware-software integrated ecosystems.
EU REACH chemical safety standards now govern synthetic rubber compounds in chew toy manufacturing, compelling reformulation of legacy product lines. Industrial consequence includes accelerated R&D expenditure for non-phthalate plasticizer alternatives. Premium durability positioning faces maximum compliance pressure in German and French retail channels.
Monthly curation services disaggregate the single-transaction purchase into recurring micro-commitments, fragmenting traditional seasonal sales concentration. Pet store foot traffic yields to algorithmic preference matching in direct channels. This behavioral pivot concentrates in US coastal metropolitan markets with highest digital payment penetration.
Toy Dog Market Segmentation
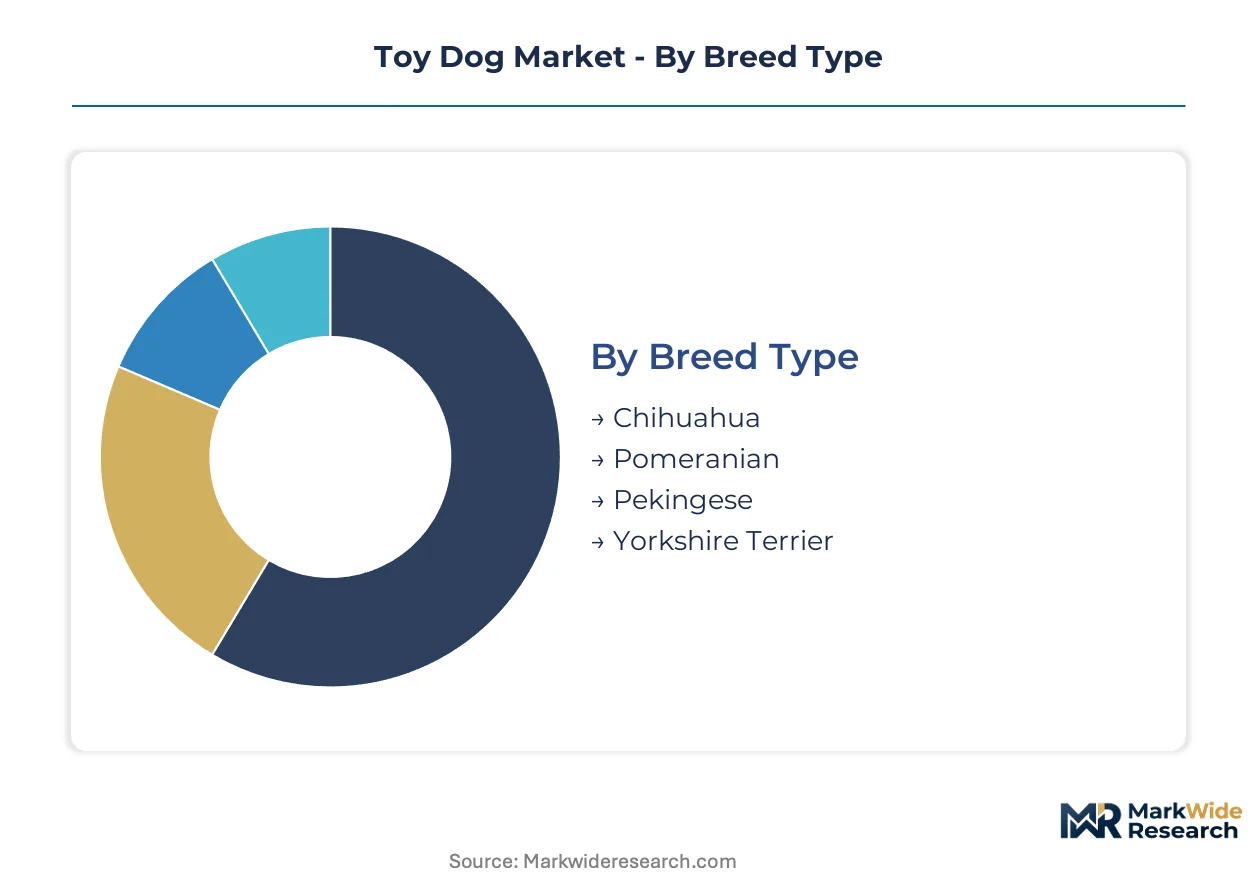
Segmentation in the Toy Dog Market separates volume-driven transaction flows from premium capture opportunities. Breed type and age group classifications determine veterinary protocol intensity and accessory bundling potential. Payment model and distribution channel splits reveal where recurring revenue concentrates versus where margin pools remain trapped in legacy intermediaries.
Breed Type:
Volume concentration versus premium positioning splits sharply across this category, with established breeder networks dictating regional availability and price tiering.
- Chihuahua:Skeletal miniaturization through selective breeding produces the smallest viable companion canine, with adult weights typically under six pounds. Demand concentrates in United States urban apartment markets where size restrictions and portability requirements dominate owner preferences. Mexican and Southwestern US breeder networks supply the bulk of commercial transactions.
- Yorkshire Terrier:Silky coat genetics and terrier lineage create distinct grooming service attachment and premium consumable bundling opportunities. United Kingdom and Northeastern US metropolitan clusters show highest ownership density, with London and Manchester residential markets sustaining above-average subscription service penetration for breed-specific accessories.
- Pomeranian:Arctic spitz heritage produces dense double-coat maintenance requirements that drive recurring grooming spend.
- Pekingese:Brachycephalic respiratory structure limits exercise tolerance and concentrates demand among elderly owners in Japan and United Kingdom urban centers.
Mature deployment sits with Chihuahua networks. Newer deployment is concentrated in Yorkshire Terrier premium positioning.
Age Group:
Life-stage segmentation determines veterinary intervention intensity and the duration of owner commitment cycles.
- Puppy:Neonatal to twelve-month developmental window demands intensive vaccination protocols, microchipping, and initial training service bundling. United States and Japanese markets show highest puppy transaction velocity through breeder direct channels, with AKC registration requirements shaping documentation standards.
- Adult:Stabilized health profiles and established behavioral patterns reduce owner time investment while sustaining routine consumable expenditure. Urban apartment dwellers in United Kingdom and United States coastal metros favor adult acquisitions to bypass housetraining complexity.
- Senior:Geriatric veterinary protocols and mobility accommodation drive premium service attachment in Japan's aging demographic markets.
- Mixed Age:Shelter and rescue channel supply dominates, with adoption centers in United States metropolitan areas processing the bulk of transactions.
Revenue concentration peaks with Adult acquisitions. Steepest expansion trajectory belongs to Senior segments in aging developed economies.
Payment Model:
Transaction structure determines margin capture and customer lifetime value accumulation.
- Subscription Service:Monthly curation of breed-specific toys and consumables converts single-transaction buyers into recurring revenue streams. United States digital-native owner cohorts in coastal metropolitan markets show highest adoption, with direct-to-consumer platforms bypassing pet store intermediaries.
- One-time Purchase:Traditional transaction structure dominates breeder and pet store channels, capturing immediate margin but forfeiting ongoing relationship economics.
- Payment Plan:Installment structures spread acquisition costs across high-value purebred transactions, concentrated in United Kingdom and United States premium breeder networks.
- Auction:Show-quality and rare color variant sales occur through specialized events governed by AKC and Kennel Club (UK) standards.
Legacy dominance rests with One-time Purchase. Digital disruption is concentrating fastest in Subscription Service models.
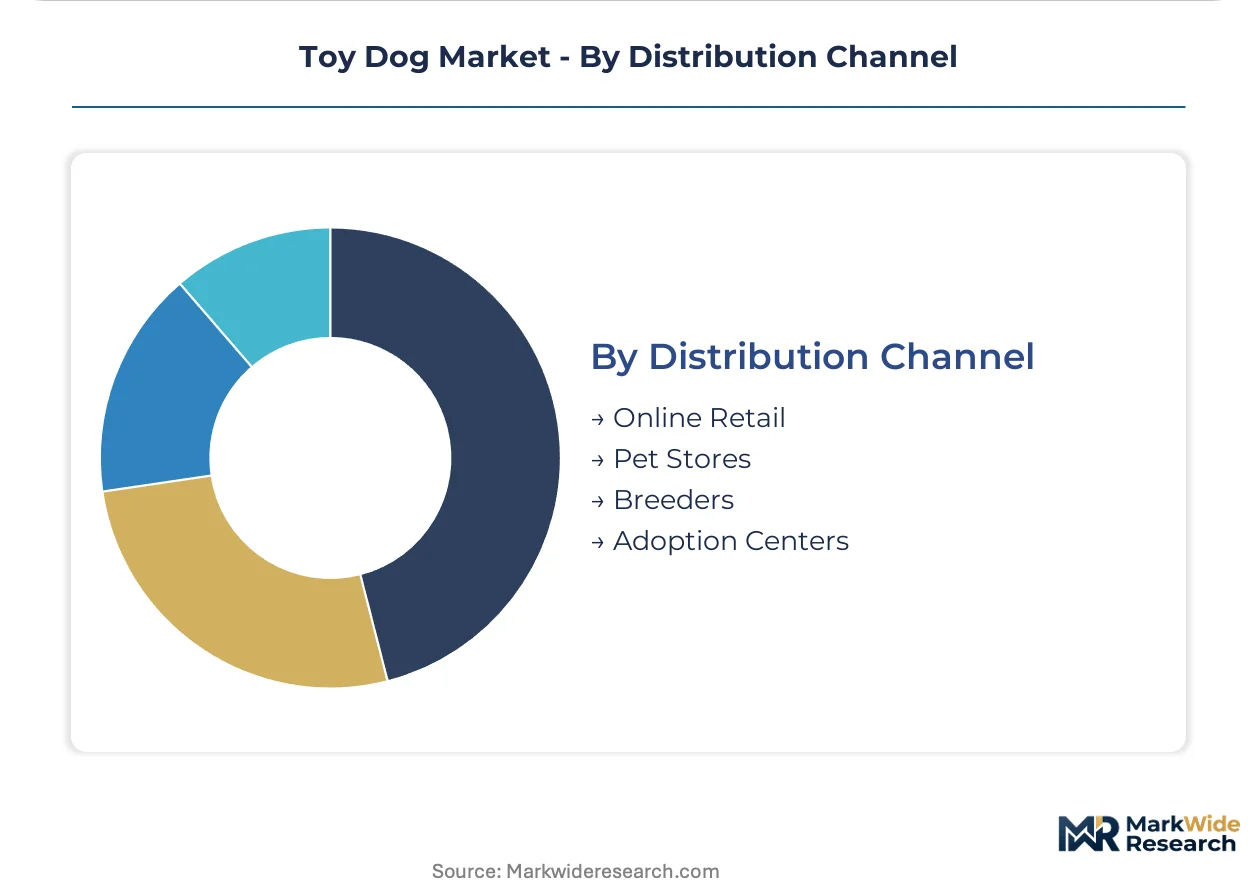
Distribution Channel:
Channel selection determines immediacy of product validation versus algorithmic convenience tradeoffs.
- Online Retail:Algorithmic preference matching and doorstep delivery capture time-constrained urban owners across United States, United Kingdom, and Japanese markets. Platform economics concentrate transaction data for predictive bundling.
- Pet Stores:Impulse accessory attachment and tactile product validation sustain margin pools in United States suburban and small-metro locations where immediate gratification outweighs digital convenience.
- Breeders:Direct acquisition channels dominate purebred transactions, with USDA Animal Welfare Act compliance certification required for interstate commerce eligibility.
- Adoption Centers:Nonprofit and municipal shelter networks supply Mixed Age segments, with United States urban clusters processing highest volumes.
Physical infrastructure anchors with Pet Stores. Digital migration is accelerating fastest through Online Retail platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate pet product re-export activity, creating a tax-advantaged hub for Middle East distribution. This regulatory architecture shapes regional supply chain configuration across three continents.
United States
Urban apartment dwellers in New York and Los Angeles drive Chihuahua and Yorkshire Terrier acquisitions, with size restrictions and portability requirements dominating owner preferences. The USDA Animal Welfare Act standardizes interstate breeder certification, expanding compliant commercial supplier pools. Subscription service penetration concentrates in coastal metropolitan markets where digital payment infrastructure supports recurring micro-commitments.
Japan
Aging demographics in Tokyo and Osaka elevate demand for Pekingese and low-exercise companion breeds among elderly owners. METI pet industry guidelines establish national welfare standards that elevate consumer trust and transaction velocity. Geriatric veterinary protocols drive premium service attachment in Kanto and Kansai urban clusters.
United Kingdom
London and Manchester residential markets sustain above-average Yorkshire Terrier ownership density with established grooming service attachment. The Kennel Club maintains breed conformation standards that govern show eligibility and commercial breeding priorities. Underpenetrated subscription service adoption relative to US benchmarks presents expansion opportunity in high-density urban segments.
Germany
EU REACH chemical safety standards govern synthetic rubber compounds in chew toy manufacturing, compelling reformulation of legacy product lines. Premium durability positioning faces maximum compliance pressure in German retail channels. Industrial R&D expenditure accelerates for non-phthalate plasticizer alternatives serving sustainability-motivated buyer segments.
Toy Dog Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material science, distribution channel, and sustainability positioning vectors. The vendor base organizes into three strategic archetypes: rubber compound specialists leveraging durability expertise, domestic manufacturers emphasizing closed-loop recycling, and nylon chew fabricators targeting aggressive small-breed behavior. M&A activity concentrates on direct-to-consumer platform acquisition, while capacity expansion favors automated injection molding for Zogoflex and comparable recyclable polymers.
Within the durability-specialist tier, KONG Company and Benebone occupy anchor positions representing divergent material approaches. West Paw exemplifies the domestic-manufacturing archetype through its Montana-based Zogoflex recycling infrastructure. These three entities collectively illustrate how material science investment and geographic production choices differentiate competitive positioning in premium toy segments.
| Leading Market Players |
|---|
| GoughNuts |
| Benebone |
| KONG Company |
| ZippyPaws |
| Chuckit! |
| West Paw |
| Jolly Pets |
| Outward Hound |
| Petmate |
| Others |
Value Network & Pricing Analysis
EU REACH chemical safety standards governing synthetic rubber compounds gate qualified supply for premium chew toy manufacturers while simultaneously justifying tiered pricing access for compliant producers in German and French retail channels. Buyers seeking durability positioning must source from reformulation-capable suppliers, compressing margin pools for legacy compound manufacturers unable to absorb accelerated R&D expenditure.
Pricing Analysis
Margin tightening in mid-tier consumables reflects veterinary genetic testing cost pass-through from breeder networks. Three-tier pricing structure across premium, standard, and economy levels differentiates by USDA Animal Welfare Act certification status and domestic manufacturing origin. Cost-down pressure on economy-tier imports accelerates because municipal breed restrictions in major US metropolitan areas reduce addressable demand for specific toy breeds. Urban apartment dwellers in coastal markets show lowest price sensitivity, while suburban pet store channels retain highest sensitivity due to impulse-driven purchase behavior.
Supply Chain Analysis
Dual-sourcing requirements for Zogoflex and comparable recyclable polymers mandate multi-supplier qualification across domestic Montana-based facilities and selected Asian compound specialists. Raw material dependencies center on non-phthalate plasticizer alternatives, FDA-compliant rubber formulations, and breed-specific textile inputs for accessory bundling. Single-source vulnerability concentrates in closed-loop recycling infrastructure for premium durability positioning. Distribution runs through direct-to-consumer platforms for subscription service capture, with pet store intermediaries sustaining residual volume in immediate-validation buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Toy Dog Market represents a consolidation play as veterinary genetic health protocol integration forces capital-constrained breeders and small-scale toy manufacturers toward exit or acquisition. Margin compression from compliance costs and subscription service disruption will accelerate this consolidation trajectory.
For Market Incumbents: Acquire direct-to-consumer platform capabilities to capture recurring revenue streams from digitally native owner cohorts before emerging pure-play specialists dominate algorithmic preference matching. Defend position by deepening backward integration into Zogoflex recycling infrastructure and securing USDA Animal Welfare Act certification lock-in across breeder network partnerships. Channel control through subscription bundling represents the critical defensive lever against retail margin erosion.
For New Entrants and Emerging Players: Smart dispensing systems with portion-control algorithms offer technology-first wedge into hardware-software integrated ecosystems currently underserved by legacy food manufacturers. Target underpenetrated United Kingdom urban clusters where London and Manchester residential markets show subscription service adoption gaps relative to US benchmarks. Go-to-market angle should emphasize algorithmic convenience for time-constrained metropolitan owners bypassing traditional pet store validation requirements.
For Investors and Strategic Acquirers: FDA nutritional claim pathway approvals for treat-inclusive bundles are the leading indicator that premium pricing tiers will sustain through regulatory differentiation. Long-term viability over the coming decade rests on material science capabilities and domestic manufacturing positioning rather than brand heritage alone. Acquisition target archetype: mid-cap specialists with closed-loop recycling infrastructure and compliant breeder network relationships. Signal to monitor: METI guideline adoption velocity across East Asian markets as proxy for regulatory transparency premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Acquisition | Captures recurring subscription revenue from coastal metropolitan digital-native owner cohorts. |
| Closed-Loop Recycling Infrastructure Expansion | Secures sustainability-motivated buyer access in premium German and French retail channels. |
| USDA Animal Welfare Act Certification Investment | Unlocks interstate commerce eligibility for compliant breeder network partnerships. |
| Smart Dispensing System Development | Decentralizes feeding management from owner memory to automated hardware-software ecosystems. |
| FDA Nutritional Claim Pathway Navigation | Leverages veterinary diet regulations to justify premium pricing for treat-inclusive bundles. |
Research Methodology
Independent corroboration across breeder network interviews, pet retail procurement leads, and veterinary diagnostic specialists underwrites the qualitative findings in this study. Primary fieldwork engaged commercial breeding operations, subscription service platform operators, and synthetic rubber compound manufacturers across United States, United Kingdom, and Japanese markets. Secondary validation drew from AKC registration databases, USDA Animal Welfare Act compliance records, FDA Center for Veterinary Medicine nutritional claim filings, and METI pet industry guideline documentation. Bottom-up transaction volume estimates triangulate against top-down breeder capacity assessments.
Comparable-period anchoring to historical AKC registration trends and subscription service penetration benchmarks established the forecast window baseline. The analytical framework segments by breed type, age group, payment model, and distribution channel across the projection horizon, with CAGRs derived from regression analysis against urban apartment dweller growth and digital payment infrastructure expansion. Industry-specific inputs include municipal breed restriction ordinance tracking and EU REACH chemical safety standard implementation timelines.
Several conditions sit outside the modeled scope, including sudden shifts in import quarantine protocols, unanticipated AKC conformation standard updates, and disruptive synthetic material substitutions. Forecasts reflect documented assumptions about regulatory stability and consumer preference continuity. Deviation in municipal breed restriction enforcement intensity or FDA nutritional claim approval velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Cage Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
US Pet Food Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
UK Pet Treats Market