
 Sustainable Fashion Market | 2026-2036
Sustainable Fashion Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Fashion Market Insights
Italy is fragmenting as domestic artisan workshops compete with scaled-up Portuguese cut-and-sew operations for European brand contracts. Patagonia anchors its position through in-house repair infrastructure and Worn Wear resale platforms. Stella McCartney differentiates via supply chain transparency tools and persistent lobbying for the EU Green Deal textile provisions. Reformation leverages deadstock fabric sourcing and localized Los Angeles production to occupy the premium contemporary segment.
Sustainable fashion encompasses garments, footwear, and accessories engineered from lower-impact fibers such as organic cotton, recycled polyester, Tencel, and hemp, produced through closed-loop water systems or mechanical recycling processes that reduce chemical discharge and carbon intensity relative to conventional textile manufacturing. Clothing commands the largest revenue pool within product type segmentation, though activewear posts the steepest trajectory as performance brands integrate bio-based elastane and regenerated nylon. Online retail and direct-to-consumer channels now capture margin previously absorbed by wholesale markups, while specialty stores sustain relevance through repair services and take-back schemes that deepen customer retention.
The EU Green Deal textile strategy, California's SB 657 disclosure requirements, and France's AGEC anti-waste law collectively mandate fiber traceability, extended producer responsibility, and restricted substance lists that reshape product design and supplier qualification across the value chain. ECHA's REACH restrictions on per- and polyfluoroalkyl substances directly eliminate durable water repellent chemistries still common in outerwear, forcing reformulation investments. Stakeholders must monitor how pending EU digital product passport rules will redefine competitive advantage through data infrastructure rather than marketing claims alone.
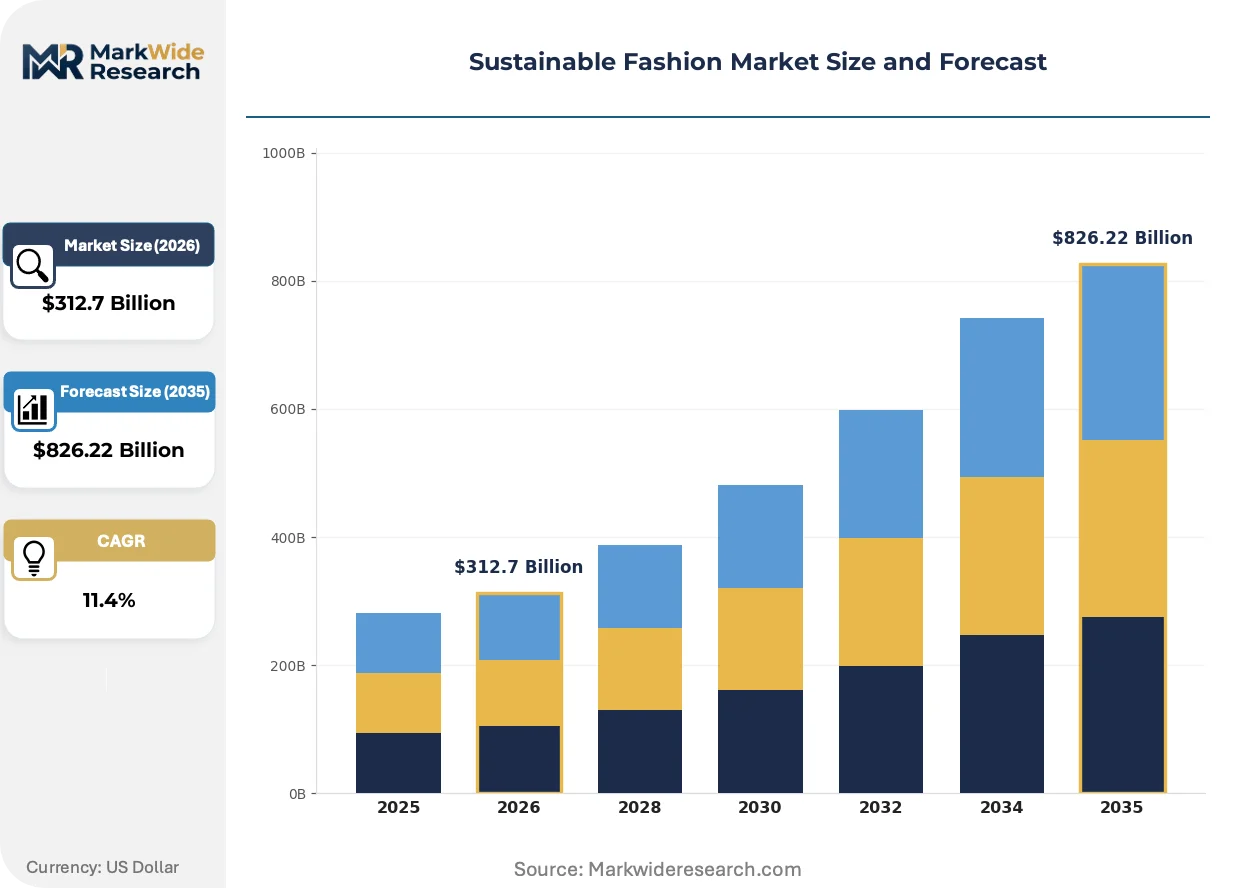
Market Dynamics
Regulatory mandates from the EU Green Deal and California's SB 657 are forcing simultaneous supply chain reconfiguration and data infrastructure investment across apparel value chains. Brands must now embed traceability systems before product passports become mandatory.
Growth Catalysts
- EU Green Deal textile strategy:Extended producer responsibility rules accelerate investment in closed-loop recycling infrastructure and fiber-to-fiber regeneration capacity.
- Scandinavian consumer willingness:Nordic markets demonstrate proven price acceptance for certified organic and recycled materials, validating premium positioning models.
- Mechanical recycling advances:Chemical-free fiber regeneration processes reduce water intensity and eliminate hazardous discharge, attracting ESG-mandated institutional capital.
Market Restraints
- Organic cotton supply concentration:Production clusters in India and Turkey create weather-dependent input volatility and quality inconsistency for premium positioning.
- REACH substance restrictions:ECHA's PFAS elimination mandates force immediate reformulation of durable water repellent chemistries without drop-in replacements at scale.
- Recycled polyester feedstock limits:Bottle-to-fiber competition with packaging sectors constrains rPET availability for textile applications.
Strategic Opportunities
- Digital product passport readiness:Early compliance with pending EU data infrastructure rules creates competitive moats through verified supply chain transparency.
- Repair and resale platform integration:Take-back schemes and refurbishment services open recurring revenue streams beyond initial garment sales.
- Bio-based elastane development:Fermentation-derived stretch fibers address performance gaps in activewear while satisfying renewable content mandates.
Industry Challenges
- Traceability data architecture:Mapping multi-tier supplier networks requires interoperable systems that few brands have operationalized at garment-level granularity.
- Certification timeline compression:OEKO-TEX, GOTS, and B Corp audits face 12-18 month backlogs, delaying market entry for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Fashion Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Footwear, Accessories, Activewear Material: Organic Cotton, Recycled Polyester, Tencel, Hemp Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct-to-Consumer Customer Type: Eco-Conscious Consumers, Luxury Shoppers, Athletes, Trendsetters |
| Companies Covered | Eileen Fisher, Reformation, Patagonia, Gucci, Puma, Stella McCartney, Outerknown, Nudie Jeans, Everlane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Fashion Market Trends and Innovations
Material science breakthroughs and regulatory data mandates are converging to reshape how garments are designed, traced, and valued. Three forces dominate the current transformation window.
Blockchain-enabled fiber provenance tracking is collapsing the information asymmetry between brands and consumers. Luxury and premium contemporary labels now embed scannable credentials linking cotton bales to finished garments. This transparency compression eliminates greenwashing exposure while enabling dynamic pricing tied to verified impact metrics.
France's AGEC anti-waste law and the EU's forthcoming digital product passport requirements are mandating standardized disclosure formats across member states. Apparel brands must restructure supplier contracts to capture chemical composition, water usage, and carbon intensity at production facility level. Outerwear and footwear categories face the steepest compliance curves due to complex multi-material construction.
Millennial and Gen Z buyers are consolidating purchases around resale-integrated direct-to-consumer channels. Specialty retailers with embedded repair infrastructure now capture lifetime value through subscription maintenance models. This behavior shift concentrates most visibly in urban North American and Northern European markets where take-back logistics density supports operational viability.
Sustainable Fashion Market Segmentation
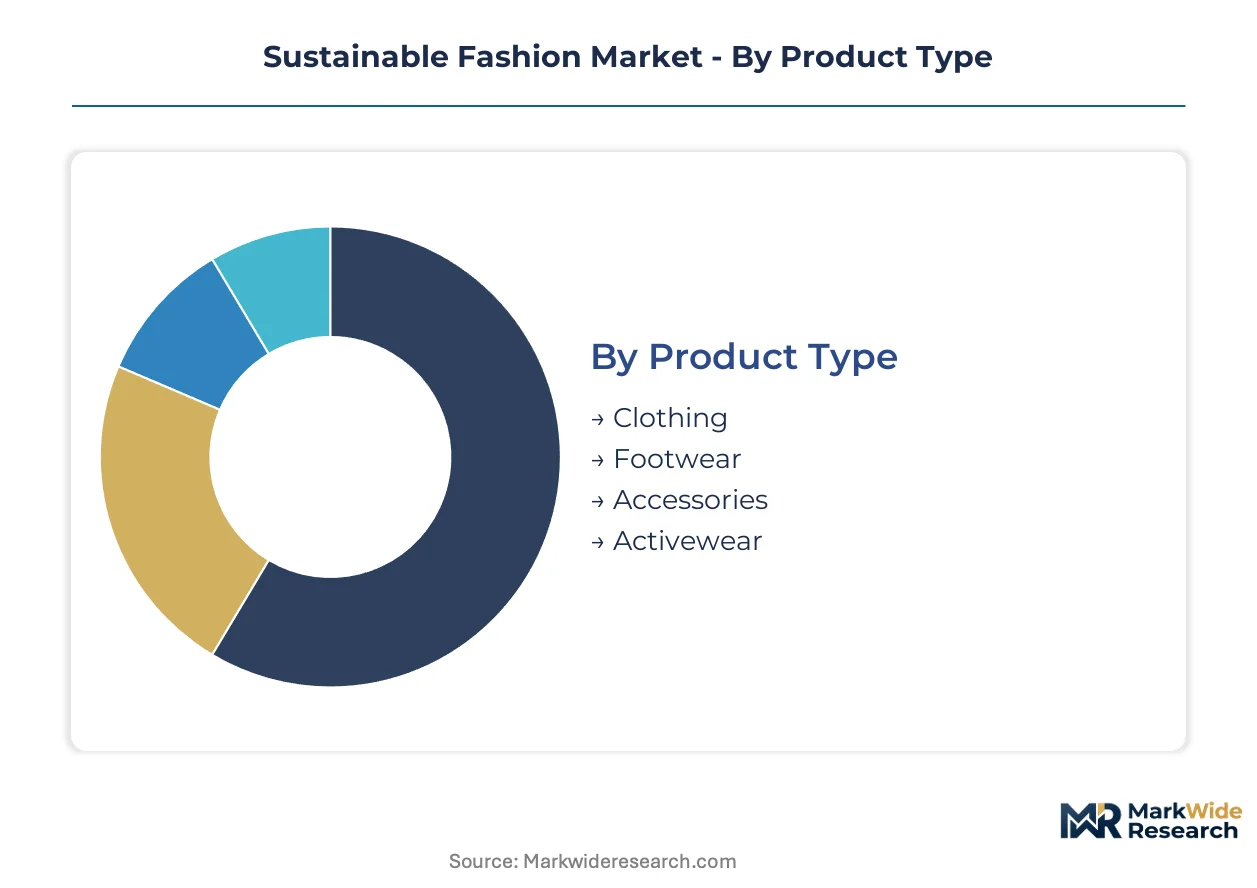
Sustainable fashion segmentation reveals divergent velocity profiles across categories. Clothing cycles fastest through resale channels while accessories command longer replacement intervals. Material certification tiers and distribution channel economics further stratify margin capture across buyer archetypes.
Product Type:
Clothing turns inventory fastest through take-back and resale platforms, while activewear posts the steepest replacement frequency due to performance degradation. Accessories and footwear operate on slower rotation cycles tied to durability positioning.
- Clothing:Garments engineered from lower-impact fibers such as organic cotton, Tencel, and hemp dominate unit volumes. Demand concentrates in Scandinavian markets where regulatory frameworks and consumer willingness to pay premiums for certified materials have matured fastest, though repair infrastructure investments now extend garment lifecycles and compress replacement rates.
- Activewear:Performance apparel integrates bio-based elastane and regenerated nylon to address stretch and recovery requirements. Athletes and fitness enthusiasts in urban North American markets drive the steepest trajectory as brands reformulate moisture-wicking chemistries to comply with ECHA REACH substance restrictions.
- Footwear:Sneakers and boots incorporating recycled rubber outsoles and water-based adhesives serve durability-focused buyers with slower replacement cadences.
- Accessories:Bags, belts, and jewelry utilizing deadstock fabrics and reclaimed metals occupy premium positioning with extended ownership horizons.
Clothing anchors the volume base while activewear gains share at the steepest rate.
Material:
Cost tiers separate commodity recycled inputs from certified agricultural fibers with traceability premiums. Supply concentration and certification backlogs create divergent availability timelines across material classes.
- Recycled Polyester:Post-consumer PET flake conversion into textile-grade fiber reduces virgin petroleum dependency. Bottle-to-fiber competition with packaging sectors constrains rPET availability, forcing brands to secure long-term feedstock contracts or absorb price volatility.
- Organic Cotton:GOTS-certified fiber cultivated without synthetic pesticides commands substantial premiums in EU and North American markets. Production clusters in India and Turkey create weather-dependent input volatility and quality inconsistency that disrupts premium positioning strategies.
- Tencel:Lyocell fiber produced through closed-loop solvent recovery systems offers drape and breathability comparable to conventional viscose without hazardous discharge.
- Hemp:Bast fiber requiring minimal irrigation and no pesticides serves workwear and outerwear applications with coarse handfeel limitations.
Recycled polyester supplies the largest volume base while organic cotton climbs the fastest on certification-driven premiumization.
Distribution Channel:
Margin structures invert between wholesale-dependent legacy retail and direct-to-consumer platforms capturing lifetime value through subscription and repair integration.
- Direct-to-Consumer:Brand-operated e-commerce and flagship stores embed digital product passport readiness and take-back logistics. Millennial and Gen Z buyers in North America and Europe consolidate purchases through these channels, enabling dynamic pricing tied to verified impact metrics.
- Online Retail:Third-party marketplaces aggregate sustainable assortments from multiple labels, though authentication and greenwashing exposure remain unresolved friction points.
- Specialty Stores:Curated boutiques with embedded repair infrastructure and resale partnerships deepen customer retention through service revenue beyond initial garment sales.
- Department Stores:Legacy wholesale accounts face margin compression as brands divert inventory to higher-yielding direct channels.
Direct-to-Consumer captures margin expansion fastest while specialty stores defend relevance through service differentiation.
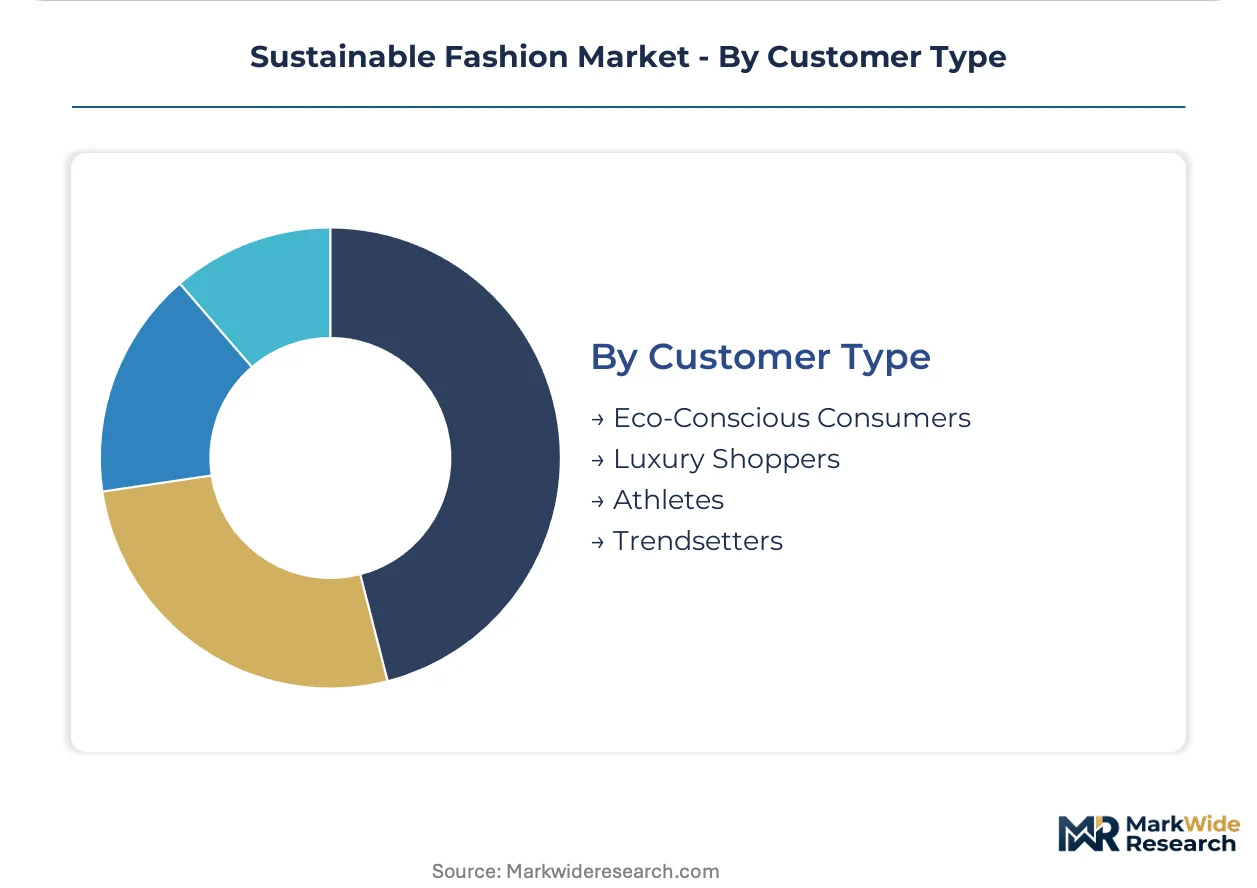
Customer Type:
Price acceptance and purchase frequency stratify across motivation profiles, from values-driven consistency to occasion-driven experimentation.
- Eco-Conscious Consumers:Values-aligned buyers prioritizing certified materials and supply chain transparency demonstrate proven willingness to absorb premiums. This segment concentrates in Nordic markets where regulatory frameworks have normalized sustainability as a baseline expectation.
- Luxury Shoppers:High-net-worth individuals seeking exclusivity through limited artisan production and blockchain-enabled provenance tracking.
- Athletes:Performance-demanding users requiring bio-based elastane and regenerated nylon with validated durability under stress.
- Trendsetters:Fashion-forward adopters cycling through resale-integrated platforms for novelty without accumulation.
Eco-Conscious Consumers provide the stable demand foundation while Athletes expand most quickly on technical material innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA anchors European regulatory momentum through REACH substance restrictions that eliminate PFAS chemistries from outerwear production. France, Germany, and Italy concentrate the continent's certified fiber processing and artisan manufacturing capacity. Scandinavian markets demonstrate the strongest consumer price acceptance for verified sustainable materials.
France
Paris-based luxury houses and Lyon silk manufacturers drive demand for blockchain-enabled provenance tracking. The AGEC anti-waste law mandates standardized disclosure formats for chemical composition and carbon intensity. The Île-de-France region concentrates headquarters functions while Auvergne-Rhône-Alpes hosts mechanical recycling pilot facilities scaling fiber-to-fiber regeneration.
Germany
Berlin's direct-to-consumer brands and Munich sportswear specialists absorb premiums for GOTS-certified organic cotton. The national implementation of EU Green Deal extended producer responsibility rules accelerates closed-loop infrastructure investment. The North Rhine-Westphalia textile belt reconfigures dye houses around water-free CO2 processing technologies.
Italy
Milan's design studios and Florence leather workshops compete with scaled-up Portuguese operations for European brand contracts. EU digital product passport readiness requirements force supplier contract restructuring across the Veneto and Lombardy manufacturing clusters. Prato's regenerated wool processors expand capacity to meet circularity mandates.
United States
California's SB 657 supply chain transparency mandates compel brands to overhaul sourcing practices and embed traceability systems. Los Angeles hosts Reformation's localized production while the Pacific Northwest anchors Patagonia's repair infrastructure. New York Metro's resale platforms capture Millennial and Gen Z consolidation around take-back integrated channels.
Sweden
Stockholm's consumer base demonstrates mature willingness to pay premiums for certified materials that validates premium positioning models. The national chemical agency enforces REACH-aligned substance restrictions ahead of EU minimums. The Gothenburg port cluster handles Nordic inbound flows of organic cotton from Indian and Turkish production origins.
Sustainable Fashion Market Competitive Landscape
Capability concentration sits with heritage artisan workshops and closed-loop material innovators; scale advantage sits with vertically integrated sportswear conglomerates and luxury groups with captive retail networks. The market structures around three archetypes: repair-integrated outdoor specialists, transparency-led contemporary labels, and heritage luxury houses retrofitting supply chains. Dominant competitive moves include strategic partnerships with mechanical recycling technology providers and selective acquisition of deadstock fabric aggregators.
Within the repair-integrated tier, Patagonia exemplifies infrastructure-heavy positioning through in-house lifetime garment maintenance. Reformation and Stella McCartney occupy the transparency-led vector, with the former representing localized production archetypes and the latter anchoring EU regulatory lobbying influence. These three entities demonstrate how divergent capability bets—resale platform depth, supply chain data infrastructure, and policy engagement—create defensible positioning against commodity recycled fiber competition.
| Leading Market Players |
|---|
| Eileen Fisher |
| Reformation |
| Patagonia |
| Gucci |
| Puma |
| Stella McCartney |
| Outerknown |
| Nudie Jeans |
| Everlane |
| Others |
Pricing and Supply Chain Analysis
Indian and Turkish organic cotton clusters anchor premium fiber availability, concentrating margin capture with GOTS-certified spinners and dye houses serving EU and North American brands. This upstream bottleneck forces downstream players to absorb certification premiums or reformulate around lower-cost recycled alternatives.
Pricing Analysis
Scandinavian markets absorb 15-40% premiums for verified sustainable materials while Southern European buyers resist comparable markups. Three-tier pricing structure across certified organic, recycled standard, and uncertified economy levels stratifies buyer segments. Cost compression in mid-tier recycled polyester intensifies as packaging sector competition constrains rPET feedstock. Price-sensitive mass-market retailers in Southern Europe and Asia-Pacific drive volume, while Nordic eco-conscious consumers prove least sensitive to premium positioning.
Supply Chain Analysis
EU REACH substance restrictions on PFAS chemistries limit durable water repellent inputs from fluorinated polymer suppliers in Belgium and Germany. Fiber production draws from India, Turkey, and Portugal for organic cotton, regenerated wool, and cut-and-sew assembly respectively. Single-source vulnerability concentrates in GOTS-certified ginning operations clustered in Gujarat and Aegean regions. Distribution runs through direct-to-consumer brand platforms and specialty retail with embedded repair infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable fashion market is a high-growth disruption propelled by EU digital product passport mandates that will restructure competitive advantage around data infrastructure rather than marketing claims alone.
For Market Incumbents: Pre-empt emerging transparency-led entrants by accelerating blockchain-enabled fiber provenance deployment before passport rules harden. Lock in multi-year organic cotton offtake contracts with Indian and Turkish suppliers to defend against feedstock volatility. Capture repair and resale platform depth as Patagonia has demonstrated, converting single-transaction customers into lifetime value relationships. For New Entrants and Emerging Players: Southern European markets present underpenetrated white space where price resistance has slowed incumbent premium positioning. Target deadstock fabric aggregation and localized micro-factory production in Spain and Italy to bypass certification backlogs blocking Asian competitors. Deploy subscription-based garment maintenance models through urban specialty retail partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward mechanical recycling technology providers with fiber-to-fiber regeneration capabilities and repair-integrated direct-to-consumer brands with proven retention metrics. Long-term viability hinges on compliance infrastructure rather than marketing differentiation. Watch for EU digital product passport implementation timelines as the inflection signal separating compliant from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | Patagonia and Stella McCartney embed scannable credentials eliminating greenwashing exposure. |
| Repair Infrastructure Buildout | Worn Wear and Nudie Jeans convert maintenance services into recurring revenue streams. |
| Deadstock Fabric Aggregation | Reformation sources remnant materials bypassing virgin fiber certification delays. |
| Mechanical Recycling Partnership | Prato's regenerated wool processors expand capacity meeting EU circularity mandates. |
| Direct-to-Consumer Channel Shift | Specialty retailers with take-back logistics capture margin previously absorbed by wholesale markups. |
Research Methodology
The analysis maps organic fiber cultivation, mechanical recycling, cut-and-sew manufacturing, and resale platform operations, each validated through brand sustainability officers, textile mill procurement leads, certification body auditors, and specialty retail buyers. Primary interviews with these stakeholders combined with secondary validation from GOTS certification databases, ECHA REACH substance restriction filings, EU Green Deal policy documents, and customs trade data. Bottom-up fiber volume estimates and top-down apparel market sizing were triangulated to reconcile divergent data sources.
Assumptions held EU digital product passport implementation and ECHA PFAS elimination timelines fixed while varying organic cotton yield volatility and recycled polyester feedstock competition scenarios. Segmentation dimensions modeled include product type, material certification tier, distribution channel, and customer motivation profile across the projection horizon. CAGRs derived from fiber price trajectory analysis and replacement frequency elasticity estimates, incorporating ESG-mandated institutional capital flows and regulatory compliance cost pass-through assumptions.
Practitioners should monitor EU digital product passport rule finalization and ECHA substance restriction expansion for early signals requiring forecast revision. Material shifts in GOTS certification backlogs, mechanical recycling yield rates, or Scandinavian consumer price acceptance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Hair Scrunchies Market