
 Decorative Accessories Market | 2026-2036
Decorative Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Accessories Market Analysis
Market Context
Recycled glass is rebalancing cost structures across decorative accessories as manufacturers substitute virgin silica with post-consumer cullet. Mohawk Industries leverages its flooring-to-décor vertical network to control material flows. Wayfair dominates online decorative accessories distribution through algorithmic curation and direct-to-consumer logistics. Williams Sonoma differentiates via artisan sourcing partnerships and private-label craftsmanship positioning.
Technical Definition and Segment Structure
Decorative accessories comprise non-structural objects designed to enhance interior aesthetics, including vessels, textiles, wall-mounted pieces, and floor coverings typically specified by dimensions, material composition, and finish durability. Wall art and cushions command mature volume pools, while hospitality application is accelerating fastest as hotel chains renovate properties with locally sourced decorative programs. Fabric and glass materials carry premium margin concentration due to artisan production constraints and import tariff exposure.
Regulatory Frame
EPA oversees volatile organic compound emissions from decorative coatings and adhesives entering the United States, while REACH restricts hazardous substances in European decorative imports. California's Proposition 65 labeling requirements shape product formulation decisions for manufacturers selling into the United States. Stakeholders must monitor evolving chemical disclosure mandates and supply chain transparency expectations across multiple jurisdictions.
Market Dynamics
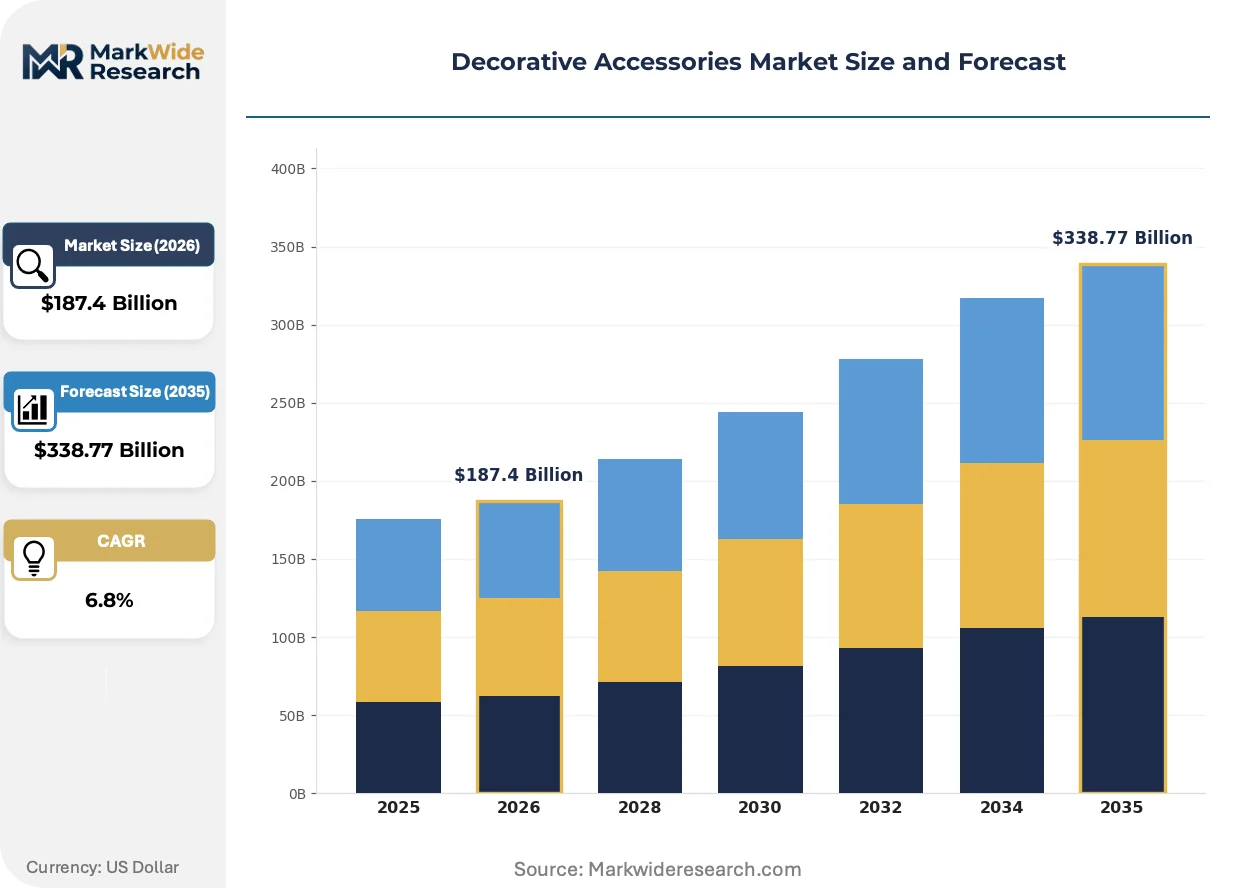
Recycled glass substitution is compressing virgin silica demand while REACH and EPA compliance costs are forcing material reformulation across the decorative accessories supply base.
Growth Catalysts
- Urban middle-class expansion:India's metropolitan households and hospitality operators are scaling procurement of curated decorative objects for residential and commercial interiors.
- REACH chemical restrictions:European hazardous substance limits are accelerating certified material sourcing and transparency investments among import-dependent suppliers.
- Algorithmic curation:Direct-to-consumer platforms are compressing traditional wholesale layers and enabling real-time demand signal capture from end buyers.
Market Restraints
- Artisan production bottlenecks:Fabric and glass decorative lines face constrained output from handcraft-dependent supply clusters in South Asia and Southern Europe.
- Import tariff exposure:Finished decorative goods from concentrated manufacturing geographies carry elevated duty burdens into North American and European markets.
- Volatile silica energy costs:Virgin glass feedstock pricing fluctuates with natural gas and electricity input volatility, pressuring margin stability for non-recycled product lines.
Strategic Opportunities
- Hospitality renovation cycles:Hotel chain property refreshes are creating demand for locally sourced decorative programs that differentiate guest experiences.
- California Proposition 65 compliance:Early formulation alignment with the state's labeling requirements opens preferential access to United States distribution channels.
- Digital-native wholesale platforms:B2B marketplaces are disintermediating traditional showroom-based procurement for interior designers and commercial specifiers.
Industry Challenges
- Multi-jurisdiction chemical disclosure:Manufacturers must maintain parallel compliance documentation for EPA, REACH, and emerging state-level transparency mandates.
- Artisan skill succession:Traditional craft techniques in glassblowing and textile weaving face generational transfer gaps in key production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Accessories Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cushions, Vases, Wall Art, Rugs Material: Wood, Metal, Glass, Fabric Style: Contemporary, Vintage, Rustic, Minimalist Application: Residential, Commercial, Hospitality, Events |
| Companies Covered | Amazon.com Inc., Ashley Furniture Industries, Williams Sonoma Inc., Wayfair Inc., Inter IKEA Systems B.V., Walmart Inc., Home Depot Inc., Target Corp., Mohawk Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Accessories Market Emerging Trajectories
Material traceability systems and automated production methods are compressing artisan-to-industrial cost gaps while regulatory disclosure requirements reshape competitive positioning across decorative accessories.
Digital printing on ceramic and textile substrates is automating pattern customization for small-batch decorative production. Hospitality procurement teams and residential interior designers are adopting these capabilities for rapid sample-to-production cycles. This technology is automating the traditional hand-painted and hand-woven premium tier, compressing lead times from weeks to days for customized decorative runs.
REACH substance restrictions and evolving EPA volatile organic compound standards are mandating water-based adhesive and coating formulations for wall-mounted decorative pieces. Manufacturers serving European and United States markets must reformulate product lines or face import exclusion. Fabric-wrapped decorative accessories and coated metal wall art categories are absorbing the highest compliance investment burden.
Designer-buyer procurement is consolidating through vertical platform accounts that bundle specification tools with direct fulfillment. Traditional showroom and rep-based channels are losing share to algorithmic curation interfaces that aggregate artisan and industrial supplier catalogs. United States interior design studios and hospitality procurement departments are leading this channel migration, compressing intermediary margin pools.
Decorative Accessories Market Segmentation
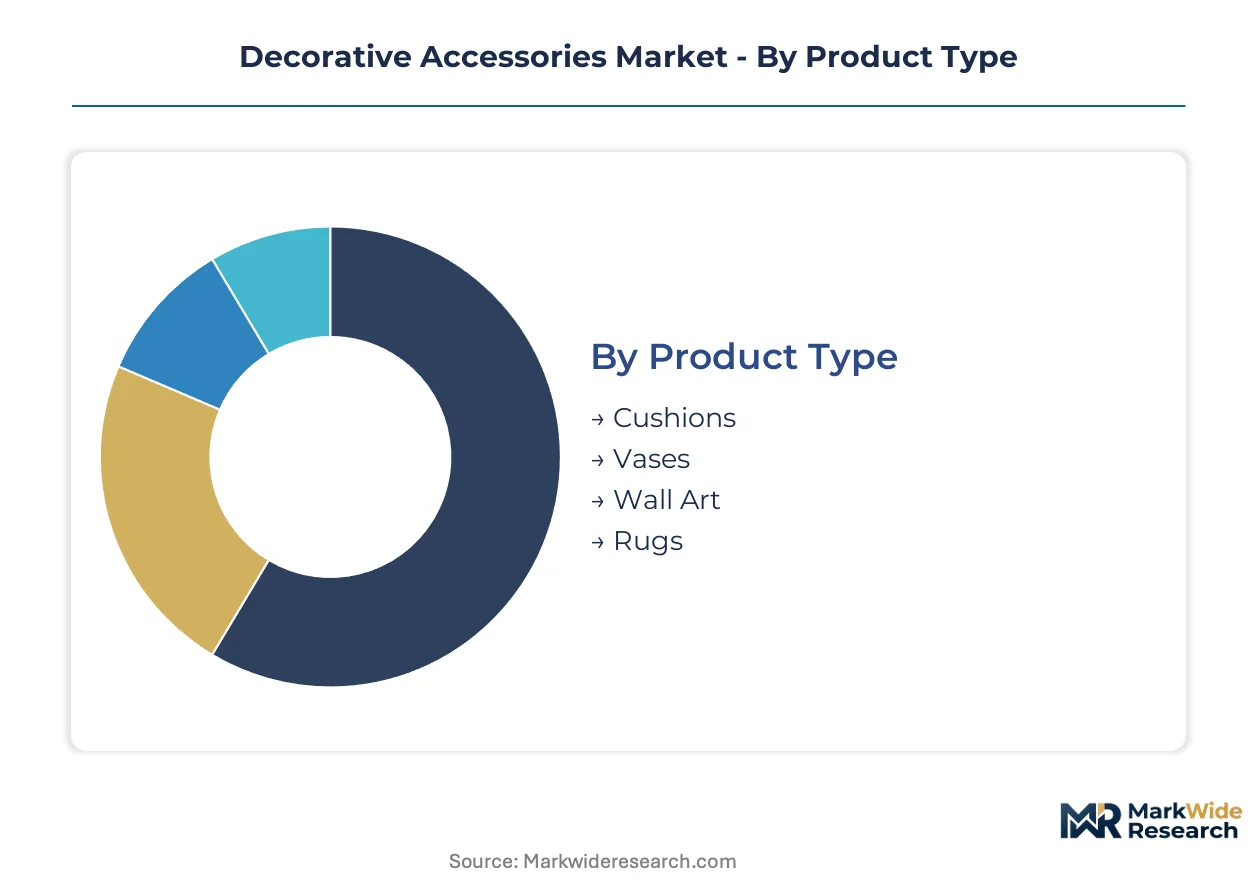
Segmentation in decorative accessories reveals how procurement priorities diverge between mass-market retailers and curated hospitality programs. Understanding these splits enables suppliers to align material investments and certification strategies with buyer willingness to pay for compliance and craftsmanship.
Product Type:
Buyers differentiate by durability requirements and replacement frequency rather than aesthetic preference alone.
- Cushions:Upholstered textile forms with foam or feather fill, specified by thread count and seam reinforcement. Residential buyers in India prioritize machine-washable covers for urban apartments with limited dry-cleaning access.
- Vases:Vessel forms in ceramic, glass, or composite materials, dimensioned by mouth diameter and base stability. Hospitality procurement teams specify weighted bases for high-traffic lobbies and restaurant tabletops.
- Wall Art:Framed prints, canvas, and dimensional pieces requiring hanging hardware and UV-resistant coatings.
- Rugs:Floor coverings with pile height and knot density specifications, ranging from hand-tufted wool to machine-woven synthetics.
Wall Art leads volumes today; Hospitality-specified Vases are gaining share fastest.
Material:
Cost tier and regulatory exposure separate buyers, with REACH compliance costs concentrated in coated and dyed inputs.
- Wood:Solid timber and engineered substrates finished with stains or veneers. EPA volatile organic compound limits on coatings constrain imported wooden wall art and decorative boxes into United States distribution.
- Metal:Cast, forged, or sheet-formed pieces with powder-coated or plated finishes. California Proposition 65 disclosure requirements for nickel and cadmium content shape sourcing decisions for metal decorative lines.
- Glass:Blown, cast, or cut crystal with recycled cullet substitution reducing energy costs. Artisan clusters in Southern Europe face generational skill gaps constraining output.
- Fabric:Woven, knitted, or embroidered textiles with dye sublimation or screen-printed patterns. REACH restricted substance lists drive reformulation of flame-retardant treatments for European-bound decorative pillows and wall hangings.
Fabric commands the broadest SKU breadth; Glass carries the steepest expansion trajectory as recycled content ratios climb.
Style:
Channel strategy varies by style segment, with digital-native platforms dominating contemporary and minimalist while showrooms retain vintage and rustic.
- Contemporary:Clean-lined forms with neutral palettes and geometric patterns. Wayfair's algorithmic curation drives volume concentration here through rapid sample-to-production digital printing.
- Vintage:Reproduction or authentically aged pieces with patina finishes and period motifs. Sourcing depends on artisan networks in Rajasthan and Andalusia with limited scalability.
- Rustic:Distressed wood, forged iron, and natural fiber constructions emphasizing hand-hewn irregularity.
- Minimalist:Reduced-form objects with monochromatic finishes and negative space emphasis. Japanese and Scandinavian design studios specify this segment for hospitality projects.
Contemporary absorbs the highest absolute demand; Minimalist is climbing the fastest among premium hospitality programs.
Application:
Volume scale and customization tolerance separate end-use buyers, with residential accepting longer lead times and hospitality demanding rapid refresh cycles.
- Residential:Individual household procurement through retail or designer channels. Indian metropolitan middle-class buyers are scaling curated object purchases for apartment personalization.
- Commercial:Office and retail space specification through facilities management and design-build contractors. Budget constraints favor standardized product lines with bulk pricing.
- Hospitality:Hotel, restaurant, and cruise line procurement with brand-standard customization requirements. Property renovation cycles in United States and Indian markets are accelerating specification frequency.
- Events:Temporary installation for weddings, corporate functions, and exhibitions with rental or single-use economics.
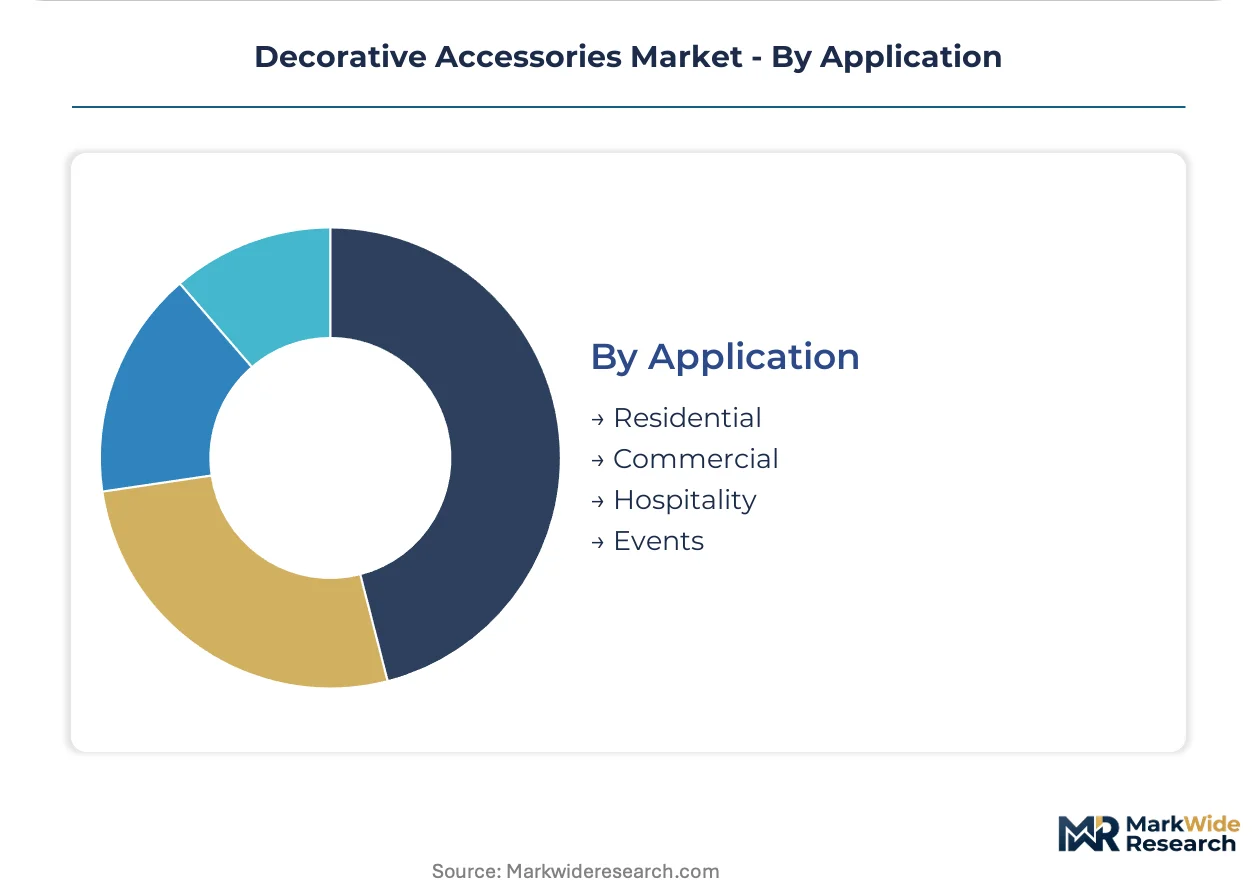
Residential maintains volume leadership; Hospitality is expanding most quickly as chain renovation programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Murano glass artisans anchor the European decorative accessories cluster, while Indian textile weavers and Chinese ceramic manufacturers supply volume production for residential and hospitality buyers worldwide.
United States
Hotel chain renovation programs and residential interior designer procurement drive demand for locally sourced decorative objects. EPA volatile organic compound standards constrain imported wooden wall art and coated metal finishes. Los Angeles design studios and hospitality procurement teams in Miami are consolidating purchasing through algorithmic curation platforms.
Germany
REACH chemical restrictions accelerate certified material sourcing investments among import-dependent retailers. ECHA substance restrictions drive reformulation of fabric-wrapped accessories and coated decorative pieces. Stuttgart and Munich house specialist distributors serving hospitality renovation projects across Central Europe.
India
Urban middle-class households and hospitality operators scale procurement of curated decorative objects for apartment personalization and hotel fit-outs. BIS standards and DGFT import policies shape sourcing decisions for finished goods. Jaipur and Rajasthan artisan clusters face generational skill gaps in hand-block printing and metalwork techniques.
China
Ceramic and glass manufacturers supply volume production for global retail and hospitality distribution networks. MIIT standards and evolving environmental regulations from MEE constrain energy-intensive kiln operations. Foshan and Jingdezhen ceramic production centers are automating pattern customization through digital printing technologies.
Italy
Artisan glassblowing and ceramic traditions command premium positioning in hospitality and luxury residential specification. REACH compliance costs concentrate in coated and dyed decorative inputs from Southern European suppliers. Murano and Tuscany clusters face constrained output from handcraft-dependent production methods.
Decorative Accessories Market Vendor Landscape
Global majors compete with regional champions across distribution channel control and material sourcing capabilities. The vendor base separates into mass-market retailers with captive logistics networks, specialty retailers with artisan sourcing partnerships, and digital-native platforms with algorithmic curation engines. Dominant competitive moves include backward integration into material flows and strategic partnerships with hospitality procurement departments.
Within the mass-market retail tier, Amazon.com Inc. and Walmart Inc. occupy positions defined by fulfillment infrastructure scale and private-label decorative line expansion. Wayfair Inc. and Williams Sonoma Inc. exemplify the digital-native and specialty-retail archetypes respectively, with the former anchoring algorithmic demand capture and the latter representing artisan craftsmanship positioning. Mohawk Industries Inc. sits within the vertical manufacturing tier, leveraging flooring-to-décor material flow control.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Ashley Furniture Industries |
| Williams Sonoma Inc. |
| Wayfair Inc. |
| Inter IKEA Systems B.V. |
| Walmart Inc. |
| Home Depot Inc. |
| Target Corp. |
| Mohawk Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Artisan glassblowers in Murano and hand-block printers in Jaipur anchor cost structures across decorative accessories, with labor-cost differentials between these heritage clusters and automated Chinese ceramic centers widening spreads between premium craftsmanship and mass-market tiers.
Pricing Analysis
Input-cost pass-through from volatile natural gas and electricity pricing runs through virgin glass product lines, while recycled cullet substitution compresses margins for non-certified producers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant artisan pieces from digitally printed mass-market runs and private-label retail imports. Pricing pressure stems from import tariff exposure on finished decorative goods entering North American distribution. Hospitality procurement teams show lowest price sensitivity, prioritizing brand-standard customization and compliance certification over unit cost.
Supply Chain Analysis
Virgin silica feedstock draws from concentrated natural gas corridors in the United States and Middle East, while artisan glassblowing clusters in Italy and textile weaving networks in India supply premium decorative tiers. Raw material dependencies span post-consumer cullet streams, water-based coating formulations, and certified flame-retardant fabric treatments. Single-source vulnerability concentrates in Southern European artisan clusters facing generational skill gaps. Distribution runs through algorithmic curation platforms for residential buyers and direct specification relationships for hospitality procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decorative accessories function as a stable compounder, with recurring hospitality renovation cycles and residential refresh demand providing predictable revenue baselines resistant to cyclical disruption.
For Market Incumbents: Lock in artisan sourcing partnerships in Rajasthan and Murano before generational transfer gaps eliminate scalable handcraft output. Secure backward integration into recycled glass cullet streams to insulate margin structures from virgin silica energy volatility. Channel control through proprietary B2B specification platforms defends against algorithmic curation disintermediation.
For New Entrants and Emerging Players: Capture white-space in California Proposition 65 pre-compliant product lines, where early formulation alignment opens preferential United States distribution access. India's hospitality fit-out market offers the most penetrable geography, with hotel chain renovation programs multiplying specification frequency. A direct-to-designer digital platform with rapid sample-to-production cycles provides the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Private equity firms with consumer goods portfolios are the most active acquirer in this space, targeting artisan-brand aggregators with hospitality relationships. Long-term viability over a five-to-ten year window rests on compliance infrastructure and digital specification tool adoption. Watch REACH substance list expansions and EPA volatile organic compound standard tightening as inflection indicators for material reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Sourcing Partnerships | Murano and Rajasthan clusters provide irreplaceable craftsmanship differentiation for hospitality specification. |
| Recycled Content Integration | Post-consumer cullet substitution reduces energy cost exposure and satisfies emerging buyer sustainability mandates. |
| Compliance-First Formulation | REACH and Proposition 65 alignment opens preferential access to European and California distribution channels. |
| Digital Specification Platform | Algorithmic curation tools compress traditional showroom layers and capture real-time demand signals from designers. |
| Hospitality Procurement Integration | Direct relationships with hotel chain renovation teams secure recurring refresh cycle revenue. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with decorative accessories category managers, hospitality procurement directors, interior design studio principals, and artisan cooperative leaders with secondary validation against customs trade records, EPA regulatory filings, ECHA substance restriction updates, and hospitality industry renovation databases. Bottom-up demand modeling across product type, material, and application segments triangulated against top-down market sizing from retail and hospitality spending patterns.
Comparable historical periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, material composition, style category, and end-use application. CAGRs derived from trend extrapolation adjusted for regulatory compliance cost absorption and channel shift velocities. Forecast inputs incorporated hospitality renovation cycle timing, artisan output constraints, and recycled material adoption curves.
Regulatory expansion, artisan labor availability, and energy input volatility are the dominant revision risks to projection assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Hair Scrunchies Market