
 Europe Fashion Accessories Market | 2026-2036
Europe Fashion Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fashion Accessories Market Foresight
The EU Green Deal is repositioning how European fashion houses source raw materials and certify product lifecycles. Kering SA leverages its in-house Material Innovation Lab to pilot bio-based alternatives to conventional tanning processes. Richemont SA anchors its accessories division through vertically controlled distribution across Geneva and Paris flagship networks. Hermès International SCA dominates the ultra-premium leather goods segment with artisan craft constraints that limit annual output growth.
Europe Fashion Accessories encompass wearable items including bags, belts, jewelry, and sunglasses, typically manufactured from leather, metal, fabric, or synthetic compounds through techniques ranging from hand-stitching to precision injection molding, serving both functional utility and status-signaling purposes. The leather material segment sustains the highest margin pools due to scarcity of certified tanneries and extended production cycles. Jewelry competes through precious metal content and hallmark compliance, while sunglasses differentiate via UV-protection ratings and optical lens technology. The women's end-user category occupies the largest revenue share, though unisex positioning is accelerating across younger demographics.
REACH regulations govern chemical inputs across metal plating and synthetic dye processes, while the EU Green Deal's extended producer responsibility mandates are forcing redesign of packaging and end-of-life collection systems. ECHA substance restrictions on chromium VI in leather tanning directly reshape supplier qualification requirements for brands selling into Germany and France. Stakeholders must monitor how CSRD disclosure rules will expose supply chain environmental performance to institutional investors and luxury goods purchasers.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing wholesale redesign of material sourcing, tanning chemistry, and end-of-life collection infrastructure across European fashion houses.
Growth Catalysts
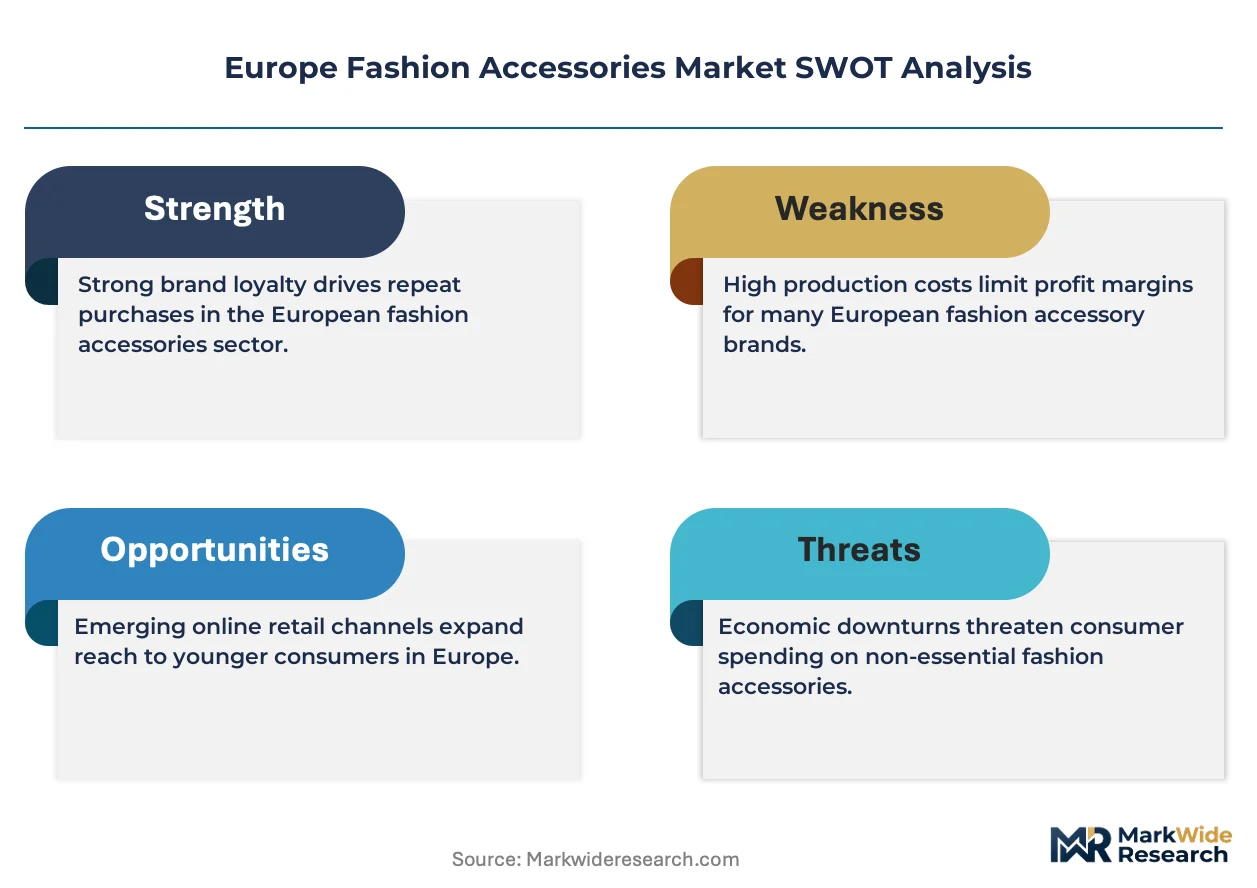
- REACH chemical compliance:Stricter ECHA substance restrictions on chromium VI in leather tanning are accelerating supplier consolidation toward certified tanneries in Italy and France, concentrating premium production capacity among qualified vendors.
- Aspirational millennial demand:Younger buyers in Germany and Spain are prioritizing heritage craftsmanship signals and limited artisan output, pulling volume toward ultra-premium leather goods with documented provenance.
- Bio-based material innovation:Mycelium leather and plant-derived tanning agents are reducing water intensity in accessory manufacturing, attracting sustainability-focused investment from institutional capital.
Market Restraints
- Certified tannery scarcity:Fewer than twelve Italian tanneries meet combined REACH and EU Green Deal standards, creating supply bottlenecks for chromium-free leather finishing.
- Artisan labor constraints:Hand-stitching capacity in Florence and Milan clusters cannot scale beyond single-digit annual growth regardless of demand pressure.
- Synthetic substitute encroachment:Precision-molded polyurethane bags from Turkish manufacturers are capturing price-sensitive segments in Eastern European markets.
Strategic Opportunities
- CSRD disclosure tailwind:Mandatory supply chain environmental reporting is creating first-mover advantage for brands with pre-audited Italian manufacturing partners and blockchain-tracked material provenance.
- Poland and Romania penetration:Underdeveloped luxury accessory retail density in Warsaw and Bucharest offers whitespace for flagship network expansion ahead of competitor saturation.
- Circular service unbundling:Subscription-based accessory rental and certified resale platforms are unlocking recurring revenue from Gen Z buyers in Amsterdam and Copenhagen who reject permanent ownership.
Industry Challenges
- Master craftsperson pipeline collapse:Leatherworking apprenticeship programs in Tuscany report 40% enrollment declines over the past decade, threatening generational knowledge transfer for saddle-stitch techniques.
- Dual certification timeline compression:Simultaneous EU Green Deal compliance and CSRD audit preparation is straining mid-tier brand finance and legal functions without dedicated sustainability teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fashion Accessories Market |
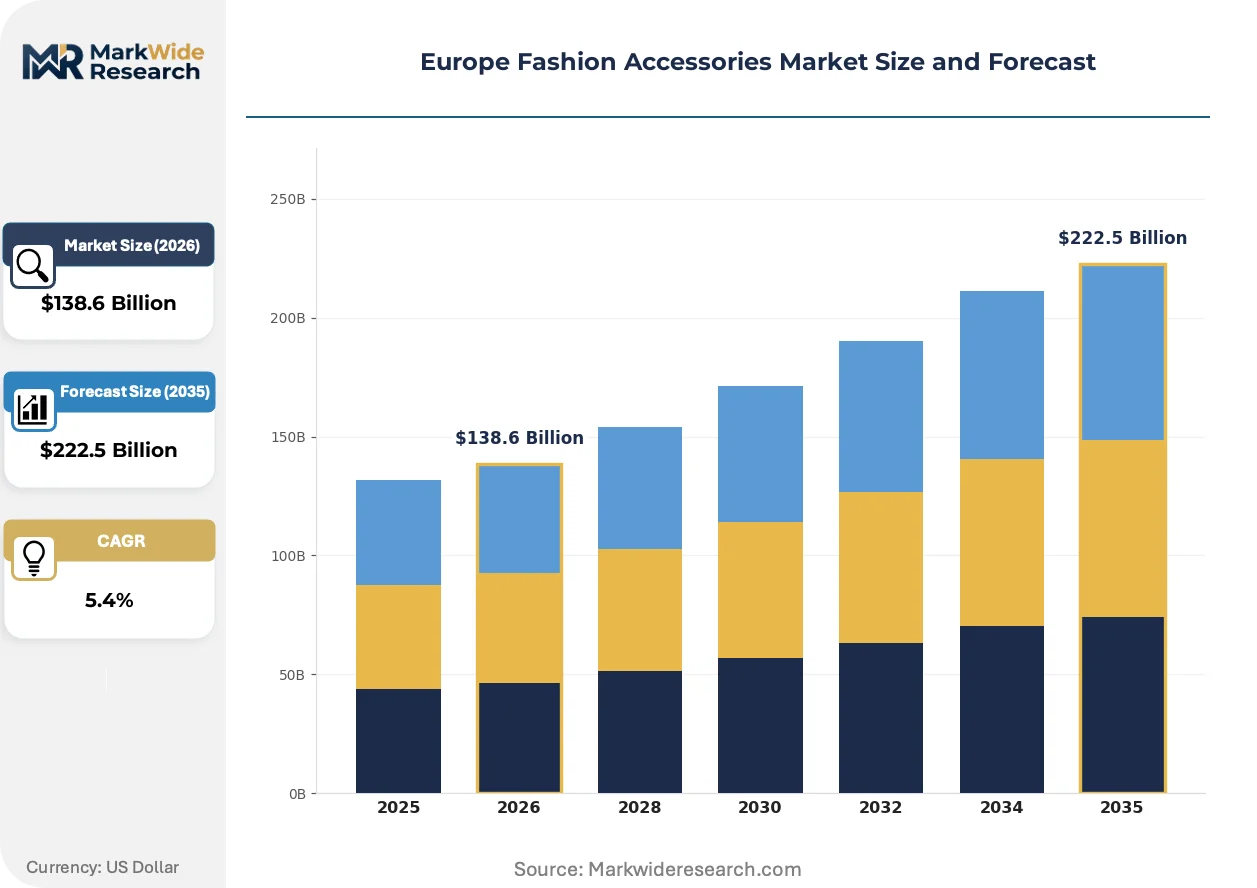
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $222.5 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Belts, Jewelry, Sunglasses Material: Leather, Metal, Plastic, Fabric End User: Women, Men, Children, Unisex Distribution Channel: Online, Department Stores, Boutiques, Supermarkets |
| Companies Covered | Richemont SA, Hermès International SCA, LVMH Moët Hennessy Louis Vuitton SE, Prada SpA, Burberry Group PLC, Kering SA, Chanel SA, Adidas AG, Inditex SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fashion Accessories Market Shifts & Advancements
European fashion accessories are converging around three vectors: material chemistry transformation, regulatory disclosure as competitive weapon, and ownership models that decouple status signaling from physical possession.
Mycelium-based leather alternatives grown from agricultural waste substrates are modularizing how brands prototype and scale accessory collections. Kering's Material Innovation Lab and smaller biotech suppliers in the Netherlands are deploying these materials for handbag linings and small leather goods within 18-month development cycles. This compression is collapsing traditional multi-year tanning partnerships and enabling rapid seasonal experimentation without tannery minimum order constraints.
The EU Green Deal's textile sustainability requirements are mandating lifecycle assessment documentation for all accessories sold into France and Germany from 2026. Brands must now account for water use, chemical inputs, and end-of-life collection infrastructure in product labeling. The leather goods segment faces the steepest compliance burden due to tanning chemistry complexity, driving consolidation toward vertically controlled Italian supply chains with pre-existing audit trails.
Rental and resale platforms are displacing primary purchase occasions among urban professionals aged 25-34 in Berlin, Stockholm, and Milan. These buyers prioritize access to rotating heritage pieces over permanent ownership, compressing traditional replacement cycles and forcing brands to develop authentication and refurbishment capabilities. The shift is most visible in handbags and jewelry, where provenance verification technology enables trust in secondary transactions.
Europe Fashion Accessories Market Segmentation
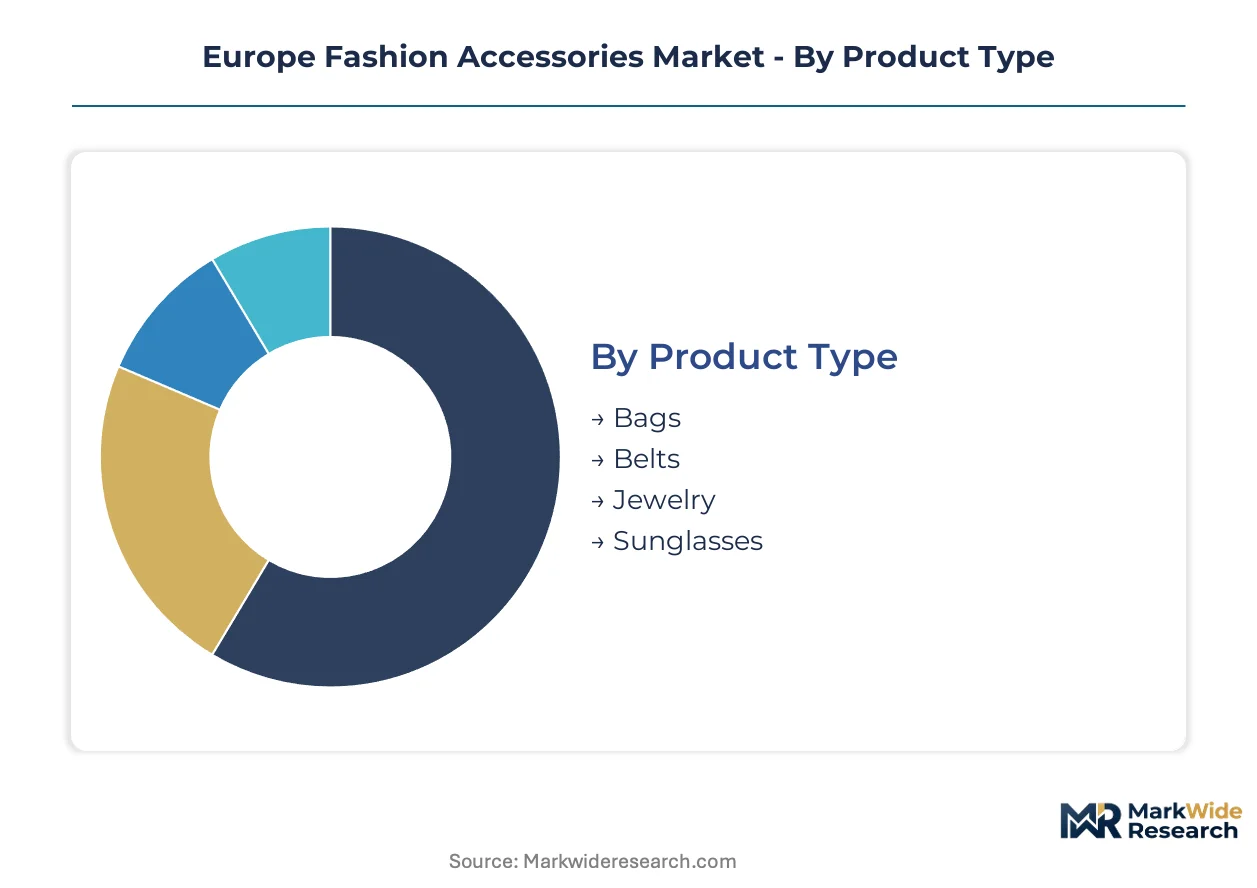
Accessories replacement cycles vary dramatically across product types and user demographics, with leather goods commanding extended intervals while fast-fashion jewelry turns over seasonally. Material sourcing constraints and distribution channel evolution further fragment how brands calibrate inventory and margin strategies.
Product Type:
Upgrade cycles diverge sharply: handbags justify investment-grade positioning with decade-long utility horizons, while sunglasses and jewelry respond to trend velocity.
- Bags:Structured silhouettes in full-grain leather dominate Italian artisan output, with Florence and Milan workshops limiting annual production growth regardless of demand pressure. Women's professional segments in Germany and France drive heritage craftsmanship signals and documented provenance requirements.
- Jewelry:Precious metal content and hallmark compliance differentiate positioning, with Amsterdam and Copenhagen buyers accelerating rental and resale participation over permanent ownership. Hallmark verification technology enables trust in secondary transactions among urban professionals aged 25-34.
- Belts:Functional accessories with narrower margin pools, concentrated in standard-width leather and reversible metal-buckle configurations.
- Sunglasses:UV-protection ratings and optical lens technology compete for seasonal replacement occasions, with Eastern European price sensitivity capturing polyurethane-molded alternatives.
Volume placements concentrate in bags; the faster expansion belongs to jewelry.
Material:
Cost tiers stratify around certification burden and supply scarcity, with REACH-compliant inputs commanding premium positioning.
- Leather:Chromium-free tanning under ECHA restrictions consolidates supply toward fewer than twelve certified Italian tanneries, creating bottlenecks for EU Green Deal-compliant finishing. Water intensity and extended production cycles sustain the highest margin pools.
- Metal:Precious alloys for jewelry and hardware face dual pressure from hallmark compliance and plating chemistry governed by REACH substance restrictions.
- Plastic:Precision-molded polyurethane from Turkish manufacturers captures price-sensitive segments in Poland and Romania.
- Fabric:Canvas and woven textiles for seasonal collections enable rapid prototyping without tannery minimum order constraints.
Revenue concentrates in leather; bio-based alternatives are climbing the fastest.
End User:
Customer type dictates design language and distribution channel selection, with unisex positioning accelerating across younger demographics.
- Women:The largest revenue share, spanning investment handbags, precious jewelry, and seasonal accessories with heritage craftsmanship signals.
- Men:Narrower SKU counts concentrated in leather goods and functional belts, with aspirational millennial buyers in Spain pulling toward artisan output.
- Children:Safety-compliant sizing and material restrictions limit margin expansion, with volume concentrated in mass-market distribution.
- Unisex:Gen Z buyers in Berlin and Stockholm reject gendered categorization, compressing traditional segmentation frameworks.
Women's placement dominates current volume; unisex is gaining share fastest.
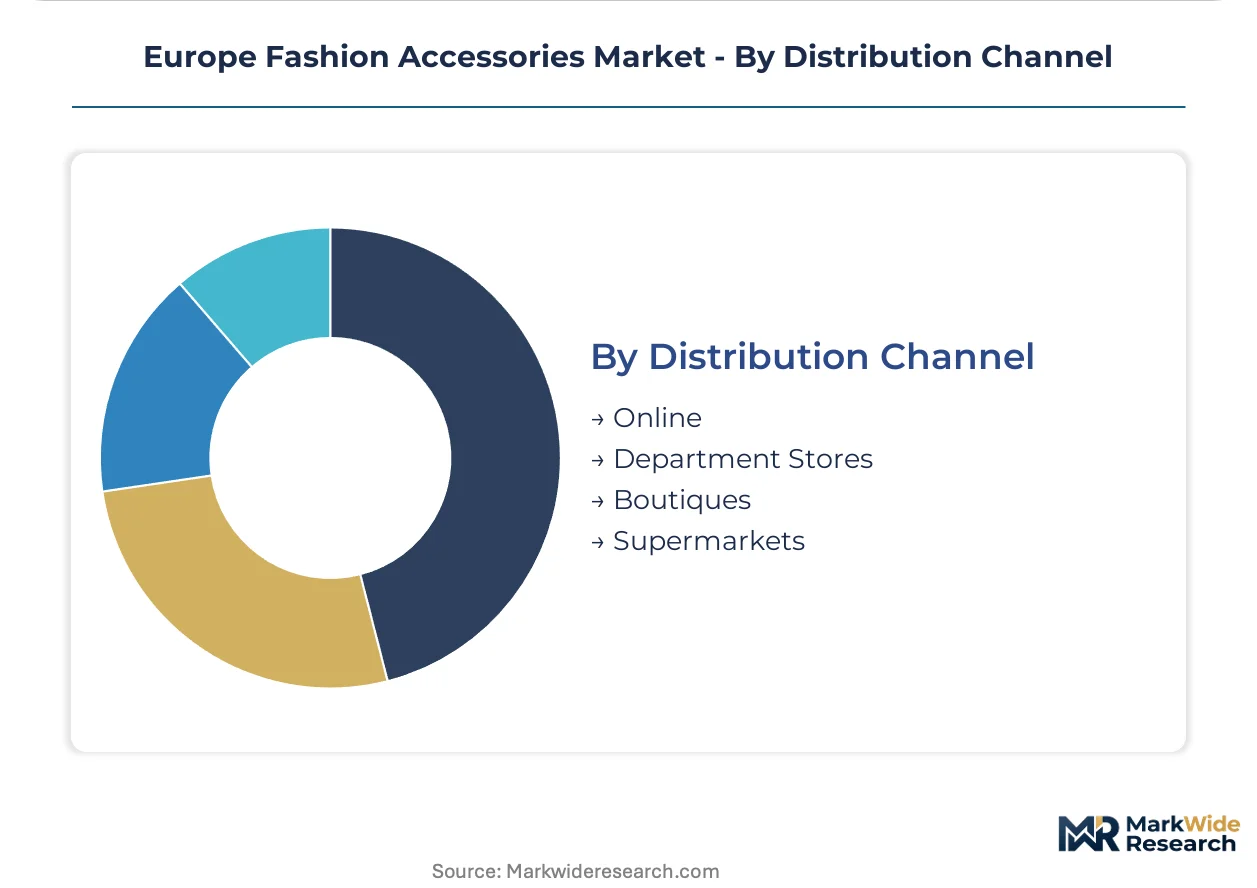
Distribution Channel:
Channel economics reshape margin capture and brand control, with flagship networks anchoring premium positioning.
- Online:Direct-to-consumer platforms enable authentication and refurbishment capabilities for resale participation, with blockchain-tracked provenance supporting secondary market trust.
- Boutiques:Vertically controlled flagship networks in Geneva and Paris anchor ultra-premium leather goods distribution with limited artisan output.
- Department Stores:Mid-tier brand presence faces compression from simultaneous EU Green Deal compliance and CSRD audit preparation costs.
- Supermarkets:Price-sensitive volume in Eastern European markets, vulnerable to synthetic substitute encroachment.
Transaction volume concentrates in boutiques; steepest expansion trajectory belongs to online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florence and Milan anchor Europe's artisan manufacturing clusters, concentrating premium leather goods capacity that supplies aspirational demand across Germany, France, and Spain. Italian tanneries in Tuscany face REACH and EU Green Deal compliance pressures that reshape supplier qualification across the value chain.
Italy
Heritage craftsmanship signals from Florence workshops pull German and French buyers toward limited artisan output with documented provenance. ECHA substance restrictions on chromium VI consolidate supply toward fewer than twelve certified tanneries in Tuscany. Milan's vertically controlled flagship networks anchor ultra-premium distribution with production growth capped by hand-stitching capacity constraints.
Germany
Millennial buyers in Berlin prioritize access over ownership, accelerating rental and resale platform participation for heritage handbags and jewelry. CSRD disclosure rules expose supply chain environmental performance to institutional investors purchasing luxury goods. Frankfurt's financial sector concentrates procurement decision-making for corporate gifting and executive accessory programs.
France
Paris flagship networks control distribution for ultra-premium leather goods with deliberate output limitations that sustain scarcity positioning. EU Green Deal extended producer responsibility mandates force redesign of packaging and end-of-life collection infrastructure for accessories sold into the domestic market. Lyon-based precious metal suppliers face dual pressure from hallmark compliance and REACH plating chemistry restrictions.
Spain
Aspirational millennial demand in Barcelona and Madrid pulls volume toward artisan leather goods with provenance documentation, mirroring Italian positioning strategies. The country's national consumer protection authority enforces labeling requirements for bio-based material claims in accessory marketing. Valencia's textile clusters enable rapid seasonal prototyping without tannery minimum order constraints.
Poland
Underdeveloped luxury accessory retail density in Warsaw creates whitespace for flagship network expansion ahead of competitor saturation. Turkish precision-molded polyurethane manufacturers capture price-sensitive segments through mass-market distribution channels. Krakow's emerging design studios experiment with mycelium leather alternatives for small goods prototyping.
Europe Fashion Accessories Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification burden and artisan labor scarcity, with vertically integrated Italian houses commanding pricing power unavailable to synthetic-dependent competitors. The vendor base stratifies into heritage ateliers with multi-decade tannery partnerships, conglomerate-owned maisons with captive material innovation labs, and fast-fashion retailers scaling polyurethane alternatives. Three archetypes dominate: scarcity-engineered ultra-premium houses, sustainability-marketed mid-tier brands, and volume-driven synthetic specialists. Consolidation pressures concentrate among mid-tier players facing simultaneous EU Green Deal compliance and CSRD audit preparation costs without dedicated sustainability infrastructure.
Within the conglomerate-owned tier, Richemont SA and Kering SA exemplify divergent approaches to material innovation and distribution control. Richemont SA anchors accessories through vertically controlled Geneva and Paris flagship networks, while Kering SA leverages its in-house Material Innovation Lab to pilot bio-based alternatives to conventional tanning processes. Hermès International SCA occupies a distinct scarcity-engineered position where artisan craft constraints deliberately limit annual output growth regardless of demand pressure, sustaining ultra-premium pricing power unavailable to competitors with scalable production models.
| Leading Market Players |
|---|
| Richemont SA |
| Hermès International SCA |
| LVMH Moët Hennessy Louis Vuitton SE |
| Prada SpA |
| Burberry Group PLC |
| Kering SA |
| Chanel SA |
| Adidas AG |
| Inditex SA |
| Others |
Supply & Pricing Matrix
Captive supply of certified Italian tanneries anchors both the sourcing position and the pricing power of ultra-premium leather goods houses, creating a structural moat that synthetic-dependent competitors cannot replicate. This backward integration into Tuscany's artisan clusters concentrates margin capture among heritage maisons while forcing mid-tier brands toward price-sensitive polyurethane alternatives.
Pricing Analysis
Value-based pricing anchored to scarcity-engineered output sustains ultra-premium positioning for heritage leather goods with documented provenance. Three-tier pricing structure across artisan-certified, mid-tier branded, and mass-market synthetic levels separates buyers by certification grade and craft documentation. Cost compression in the mid-tier is intensifying because simultaneous EU Green Deal compliance and CSRD audit preparation strain finance functions without dedicated sustainability teams. Eastern European buyers exhibit highest price sensitivity, while German and French professionals prioritize heritage signals over unit economics.
Supply Chain Analysis
Direct-to-flagship channels handle ultra-premium buyer demand through vertically controlled Geneva and Paris networks with deliberate output limitations. Raw material flows draw from fewer than twelve REACH-certified Italian tanneries, mycelium biotech suppliers in the Netherlands, and Turkish precision-molding facilities for synthetic alternatives. Single-source vulnerability concentrates in Tuscany's chromium-free tanning capacity, where artisan labor constraints cap annual production growth regardless of demand pressure. Distribution runs through boutique flagships for premium positioning, online direct-to-consumer for authentication-enabled resale, and mass-market retail for price-sensitive Eastern European volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Fashion Accessories Market sits in a material-chemistry transition phase, with bio-based mycelium alternatives displacing conventional chrome-tanned leather across prototyping and small-goods categories.
For Market Incumbents: Deploy blockchain-tracked provenance systems to defend heritage positioning against synthetic substitute encroachment from Turkish manufacturers. Accelerate captive supply partnerships with certified Italian tanneries before REACH consolidation eliminates alternative qualified vendors. Build in-house refurbishment and authentication capabilities to capture recurring revenue from rental and resale platform participation among Berlin and Stockholm urban professionals. For New Entrants and Emerging Players: Mycelium leather prototyping capabilities offer a technology-first wedge into the small leather goods segment without tannery minimum order constraints. Target Warsaw and Bucharest flagship whitespace before competitor saturation eliminates underpenetrated luxury retail density. Pursue direct-to-consumer online launch with subscription-based rental positioning to bypass capital-intensive boutique network buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate acquisition of mid-tier brands with pre-audited Italian manufacturing partners and CSRD-ready disclosure infrastructure. Long-term viability favors vertically integrated houses with captive tannery relationships and artisan apprenticeship pipelines that sustain generational knowledge transfer. Watch enrollment trends in Tuscany leatherworking programs as an inflection indicator for craft capacity constraints that determine scarcity-engineered pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Material Innovation Lab Investment | Kering's bio-based tanning pilots reduce water intensity and collapse traditional multi-year tannery partnership timelines. |
| Blockchain Provenance Implementation | Secondary market trust enabled by distributed ledger verification supports rental and resale platform revenue models. |
| Artisan Apprenticeship Pipeline Expansion | Tuscany leatherworking programs face 40% enrollment declines that threaten saddle-stitch technique generational transfer. |
| Flagship Network Expansion | Warsaw and Bucharest underdeveloped retail density offers whitespace ahead of competitor saturation. |
| Circular Service Unbundling | Subscription-based accessory rental unlocks recurring revenue from Gen Z buyers who reject permanent ownership. |
Research Methodology
Independent corroboration across primary interviews with brand sustainability officers, Italian tannery procurement leads, luxury retail channel heads, and biotech material suppliers underwrites the qualitative findings. Secondary validation draws from ECHA substance restriction filings, EU Green Deal textile sustainability documentation, CSRD disclosure draft guidance, and customs records tracking leather goods trade flows. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the European luxury goods sector.
Comparable-period anchoring to historical artisan output constraints and certified tannery capacity utilization rates shapes the projection horizon. The analytical framework segments by material chemistry tier, end-user demographic, distribution channel control level, and regional regulatory cluster. CAGRs derive from demand elasticity modeling against supply-side bottlenecks, with forecast inputs including REACH compliance timeline acceleration and millennial buyer preference shifts toward access-over-ownership models.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA substance ban acceleration or master craftsperson pipeline collapse scenarios. Periodic stress-testing of base assumptions regarding bio-based material scale-up timelines and CSRD audit preparation costs is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Decorative Accessories Market