
 Global Handbags Market | 2026-2036
Global Handbags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Handbags Market Foresight
Corporate professionals and fashion enthusiasts is collapsing as the primary growth vector while budget-conscious buyers recede in relative importance. LVMH Moët Hennessy Louis Vuitton SE leverages its vertical control over tanneries and ateliers to command premium positioning across leather goods. Kering SA anchors its portfolio through specialized craftsmanship narratives at Gucci and Saint Laurent. Hermès International SA dominates the ultra-luxury tier through deliberate scarcity and wait-list mechanics.
A handbag constitutes a portable container constructed from leather, canvas, synthetic polymers, or woven textiles, designed with specified dimensions, closure mechanisms, and strap configurations for personal item transport and aesthetic expression. Manufacturing employs cut-and-sew assembly, edge finishing, and hardware attachment with precision tolerances for load-bearing stress. Crossbody and backpack formats lead volume growth among urban commuters prioritizing hands-free mobility, while tote and satchel categories capture margin concentration in professional contexts. Leather sustains its premium price architecture despite accelerating synthetic and canvas substitution driven by animal-welfare positioning.
REACH in Europe restricts chromium tanning agents and mandates chemical disclosure across leather supply chains, elevating compliance costs for EU-facing producers. China's SAMR enforces labeling standards and counterfeiting penalties that shape market access for foreign houses. The EU Green Deal's due diligence requirements press brands toward traceable sourcing decisions. Stakeholders must monitor regulatory divergence between European chemical frameworks and emerging Asian sustainability mandates to calibrate material strategies and supplier qualification protocols.
Market Dynamics
REACH compliance and the EU Green Deal are forcing leather tanneries and synthetic polymer suppliers to reconfigure chemical inventories and traceability systems, compressing margins for EU-facing producers while creating certification premiums for early adopters.
Growth Catalysts
- China's SAMR enforcement:Stricter labeling standards and counterfeiting penalties protect brand equity for foreign houses entering domestic retail channels.
- Urban commuter mobility:Crossbody and backpack formats gain volume as professionals prioritize hands-free transit across dense metropolitan clusters.
- Plant-based leather chemistry:Mycelium and pineapple fiber alternatives attract animal-welfare-positioned buyers seeking performance parity with traditional hides.
Market Restraints
- Chromium tanning restrictions:REACH limits on hexavalent chromium elevate processing costs for EU-bound leather goods by 15-25%.
- Italian tannery concentration:Premium hide finishing clusters in Tuscany and Veneto create single-source vulnerability for luxury supply chains.
- Canvas substitution ceiling:Natural fiber durability gaps limit penetration in professional satchel and structured tote categories.
Strategic Opportunities
- India's duty-free manufacturing:PLI scheme incentives for leather goods exports attract brand-owned production facilities away from coastal China.
- Blockchain provenance:Distributed ledger verification of hide origin and tanning chemistry commands retail premiums in European and North American markets.
- Repair and resale channels:Authentication services and refurbishment ateliers extend product lifecycles while capturing margin from secondary circulation.
Industry Challenges
- Artisan succession gaps:Specialized hand-stitching and edge-painting skills concentrate among aging workforces in France and Italy.
- Dual carbon audit complexity:Scope 3 emissions tracking across multi-tier suppliers strains data infrastructure for mid-sized houses.
- Hardware lead times:Custom zamak and brass fittings from Asian die-casters face 12-16 week procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Handbags Market |
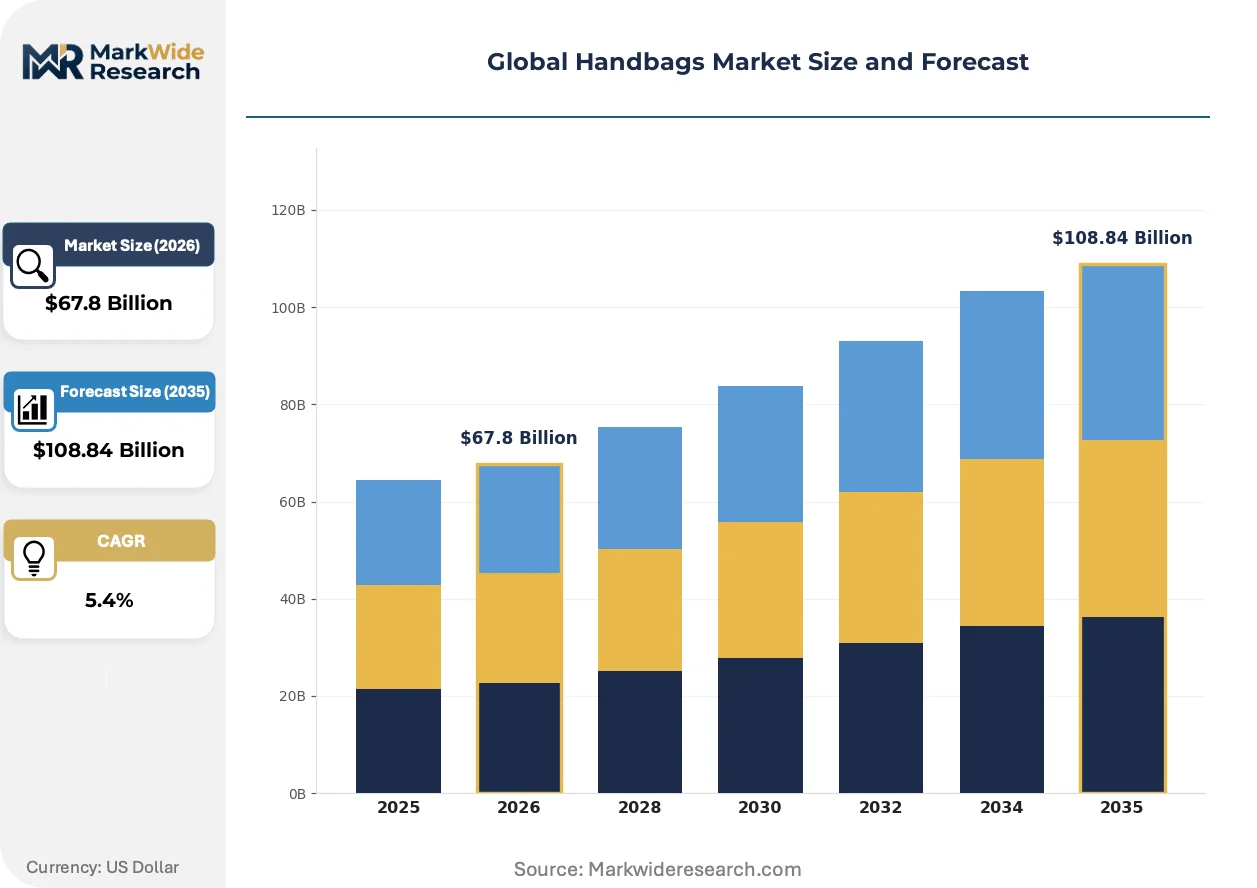
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $108.84 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tote, Satchel, Clutch, Crossbody, Backpack, Bucket Material: Leather, Canvas, Synthetic, Suede, Nylon, Raffia Distribution Channel: Department Stores, Online Retailers, Specialty Stores, Boutiques, Direct-to-Consumer, Pop-up Shops Consumer Segment: Luxury Buyers, Mid-tier Shoppers, Budget-conscious Buyers, Fashion Enthusiasts, Corporate Professionals, Students |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Hermès International SA, Kering SA, Chanel SA, Prada SpA, Burberry Group PLC, Tapestry Inc., Michael Kors LLC, Guccio Gucci SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Handbags Market Shifts & Advancements
Material science advances and regulatory chemistry mandates are compressing traditional leather dominance while enabling new performance categories. Digital verification tools and circular service models reshape how value is captured across product lifecycles.
Biomimetic polymer engineering is fragmenting the performance hierarchy between synthetic and natural materials. Polyurethane microfiber structures now replicate collagen fiber alignment, delivering abrasion resistance within 10% of full-grain leather. Athletic and commuter brands adopt these materials fastest, compressing the historical price premium commanded by hide-based construction in sub-premium tiers.
REACH Annex XVII restrictions on chromium VI compounds force tanneries toward vegetable and synthetic tanning agents. Italian and Spanish processors invest in quebracho and mimosa extract infrastructure, while German chemical suppliers commercialize aldehyde-free alternatives. The transition elevates working capital requirements for small-batch tanneries serving heritage houses.
Authentication-driven resale is displacing traditional gift and outlet channels for pre-owned luxury goods. Japanese and South Korean marketplaces deploy AI-powered condition grading and NFC chip verification, attracting collectors seeking discontinued models. This behavior concentrates in East Asian urban centers where digital-native buyers treat handbags as liquid assets rather than durable goods.
Global Handbags Market Segmentation
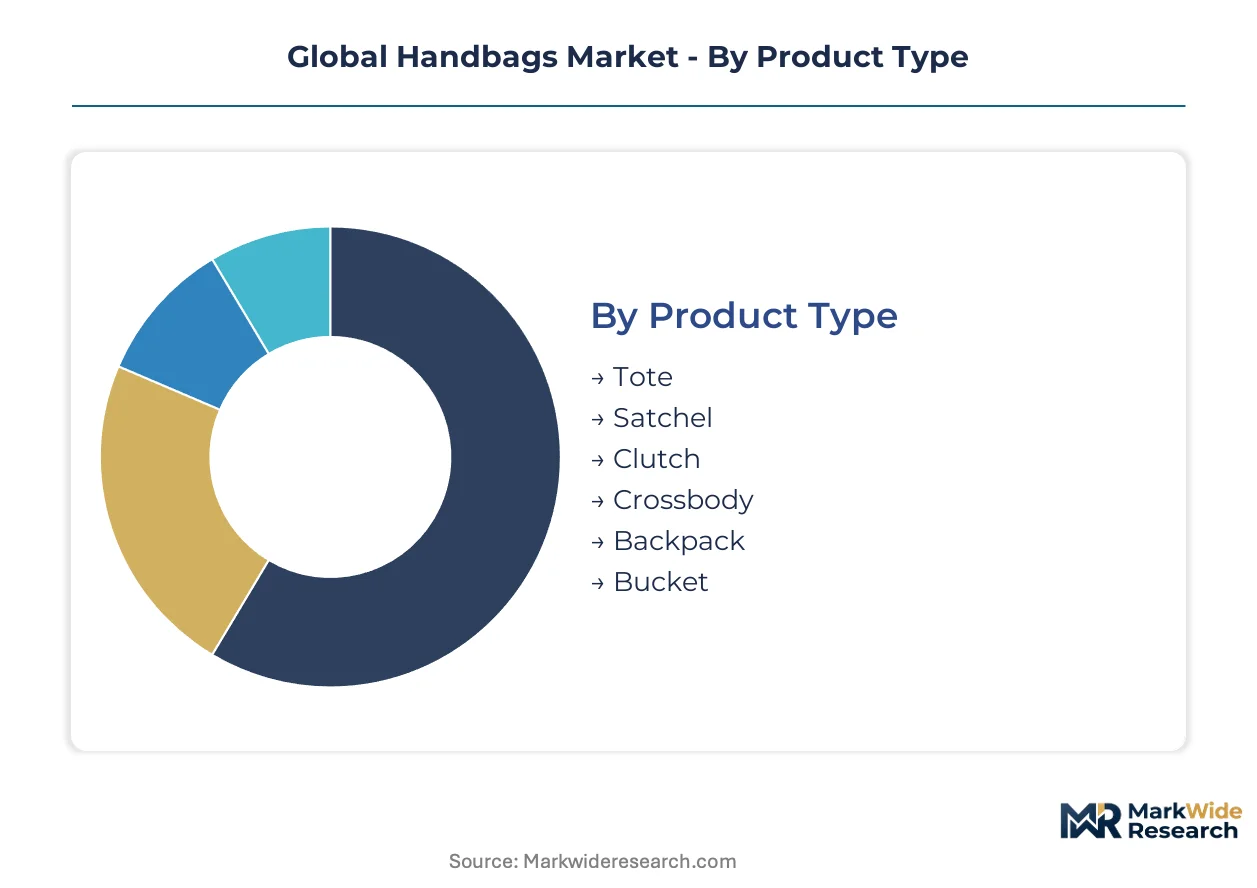
Segmentation in the handbags market reveals how format preferences, material chemistry, and channel economics fragment purchasing behavior across distinct buyer cohorts. Understanding these divides exposes where margin concentrates versus where volume scales.
Product Type:
Channel mix varies sharply by format: totes and satchels flow predominantly through department stores and specialty retailers, while crossbody and backpack formats concentrate in online channels and direct-to-consumer platforms targeting commuter convenience.
- Tote:Open-top rectangular construction with parallel handles, engineered for 5-15 liter capacity and unstructured collapse. Demand clusters among corporate professionals in Shanghai and New York seeking laptop-compatible daily carry. REACH-compliant vegetable-tanned variants command shelf-space premiums in EU department stores.
- Crossbody:Compact rectangular or saddle-profile chassis with adjustable strap geometry enabling diagonal torso carry. Urban commuters in Seoul and São Paulo drive fastest volume expansion as hands-free transit becomes non-negotiable across dense metropolitan clusters.
- Satchel:Structured flap-closure design with top handle and optional shoulder strap, historically associated with legal and financial services.
- Clutch:Handheld or under-arm format without straps, typically 15-25cm width, dominating evening and ceremonial occasions.
- Backpack:Dual-strap load distribution system with zippered main compartment, gaining professional acceptance beyond student demographics.
- Bucket:Drawstring-closure cylindrical body with single shoulder strap, trending in resort and casual contexts.
Tote dominates installed base across professional wardrobes. Crossbody is where expansion concentrates.
Material:
Cost tier stratification runs deepest in this category: leather anchors premium positioning, synthetics capture mid-tier scale, while canvas and raffia serve entry-level and seasonal fashion cycles with compressed margin structures.
- Leather:Collagen-based hide substrate processed through chromium, vegetable, or synthetic tanning sequences, delivering tensile strength exceeding 20 MPa and abrasion resistance above 50,000 Martindale cycles. Ultra-luxury houses in France and Italy maintain captive tannery relationships to secure full-grain supply for structured silhouettes. REACH Annex XVII restrictions on hexavalent chromium are forcing tannery reconfiguration across Veneto and Tuscany clusters.
- Synthetic:Polyurethane microfiber or PVC constructions engineered to replicate collagen fiber alignment, achieving abrasion resistance within 10% of full-grain leather at 40-60% lower unit cost. Athletic and commuter brands in Germany and Japan adopt these materials fastest, compressing historical price premiums in sub-premium tiers.
- Canvas:Woven cotton or linen substrate with waxed or coated finishing, limited in structured applications by tensile modulus gaps versus leather.
- Suede:Split-grain leather with napped surface, requiring specialized care and vulnerable to moisture damage.
- Nylon:Polyamide 6,6 filament constructions delivering tear resistance and weatherproofing for performance-oriented formats.
- Raffia:Woven palm fiber harvested from Madagascar and East Africa, seasonal in application and constrained by supply seasonality.
Leather dominates installed base across heritage house portfolios. Synthetic is climbing the fastest as performance engineering narrows quality gaps.
Distribution Channel:
Volume concentration tilts toward digital platforms, while margin capture remains anchored in physical touchpoints where tactile material evaluation drives conversion for premium tiers.
- Department Stores:Multi-brand curated environments with dedicated accessories floors, historically dominant in Japan and South Korea. Isetan and Lotte deploy personal shopping services and private appointment rooms to defend leather goods traffic against digital erosion.
- Online Retailers:Marketplace platforms and brand.com sites with AI-powered visualization and virtual try-on, expanding most quickly in China where Tmall and JD.com handbag categories grew through live-stream commerce integration.
- Specialty Stores:Leather goods-focused retailers with repair and personalization ateliers, concentrated in Italian urban centers.
- Boutiques:Single-brand flagship environments with architectural investment and experiential programming.
- Direct-to-Consumer:Brand-owned digital and physical channels bypassing wholesale margin extraction.
- Pop-up Shops:Temporary retail installations for collection launches and market testing, prevalent in fashion week circuits.
Department stores dominate installed base across mature Asian markets. Online retailers are gaining share fastest as authentication technology reduces purchase risk.
Consumer Segment:
Application context separates segments: professional use demands durability and capacity, fashion-forward purchasing prioritizes seasonal novelty and brand signaling, while price-sensitive selection emphasizes unit economics over longevity.
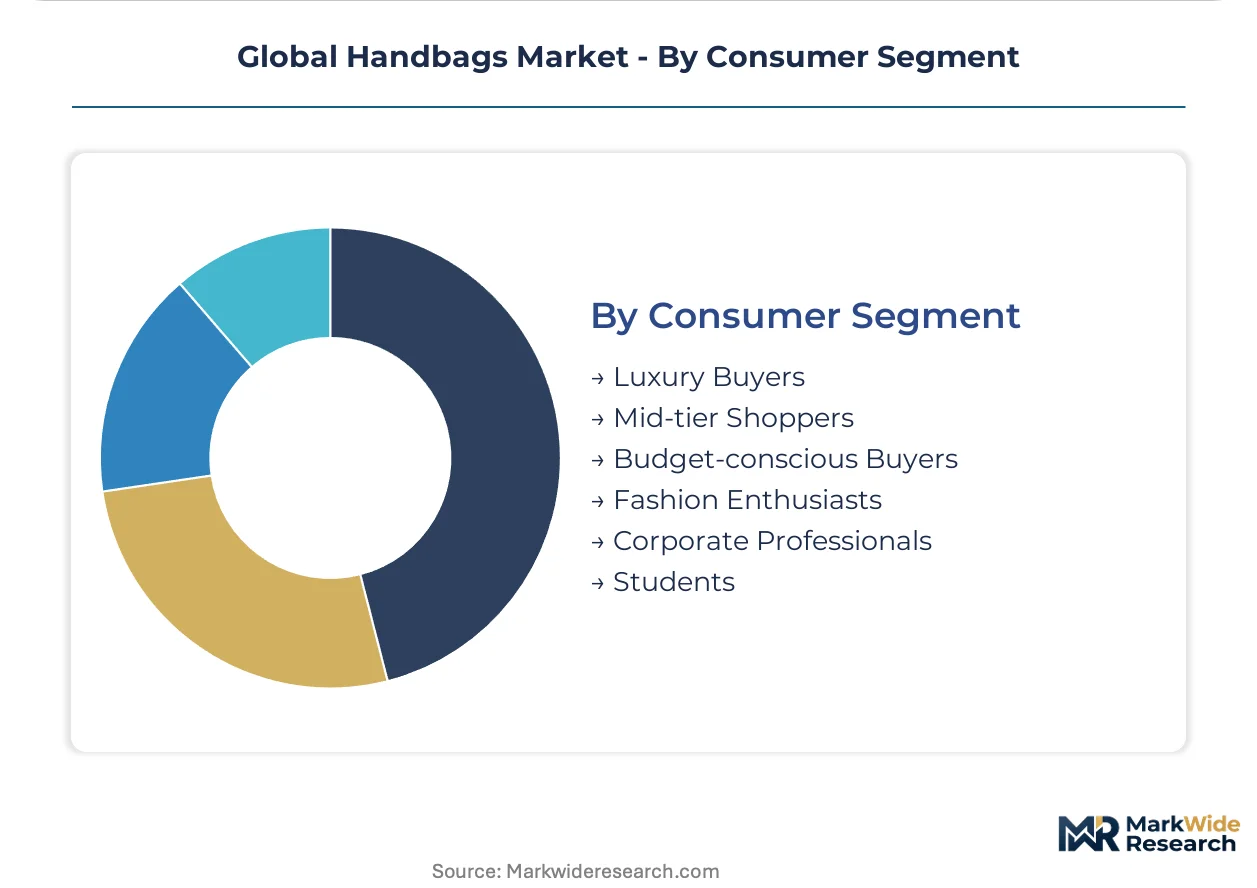
- Luxury Buyers:Households with annual discretionary spend exceeding $150,000, purchasing primarily for collection and investment purposes with low price elasticity. This cohort concentrates in Beijing, Shanghai, and Shenzhen, where SAMR enforcement of anti-counterfeiting penalties has bolstered confidence in domestic retail channels for foreign houses.
- Corporate Professionals:White-collar workers requiring daily laptop and document transport, prioritizing structured formats with organizational interiors. Demand clusters in London, Singapore, and Dubai financial districts where dress codes mandate polished accessory presentation.
- Fashion Enthusiasts:Trend-responsive purchasers with high social media engagement, driving seasonal color and silhouette cycles.
- Mid-tier Shoppers:Quality-conscious buyers seeking brand recognition at accessible price points.
- Budget-conscious Buyers:Price-optimized purchasers prioritizing function over material prestige.
- Students:Younger demographic with high digital native fluency, receptive to resale and rental access models.
Luxury buyers dominate installed base across heritage house revenue. Corporate professionals are expanding most quickly as hybrid work normalization sustains daily carry requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury buyers in China and corporate professionals in Germany anchor demand concentration, while artisan clusters in France and Italy supply heritage craftsmanship to global distribution networks.
China
Fashion enthusiasts and corporate professionals in Shanghai and Beijing drive premium handbag consumption through domestic retail channels. SAMR enforcement of labeling standards and counterfeiting penalties protects brand equity for foreign houses entering these markets. The Yangtze River Delta manufacturing belt supplies synthetic and canvas components to both domestic brands and international licensees.
France
Ultra-luxury collectors in Paris and Lyon sustain demand for scarcity-positioned leather goods with deliberate wait-list mechanics. EU Green Deal due diligence requirements press heritage houses toward traceable sourcing decisions. The Marais and Faubourg Saint-Antoine districts concentrate specialized ateliers where hand-stitching and edge-painting skills face aging workforce succession gaps.
Italy
Corporate professionals in Milan and Rome favor structured satchels for financial and legal services dress codes. REACH Annex XVII restrictions on hexavalent chromium force tanneries in Tuscany and Veneto toward vegetable and synthetic tanning agents. Florence and Vicenza host premium hide finishing clusters that create single-source vulnerability for luxury supply chains serving EU-facing producers.
United States
Urban commuters in New York and Los Angeles prioritize crossbody and backpack formats for hands-free transit across dense metropolitan clusters. FTC guidelines on environmental marketing claims shape how brands communicate material sourcing to domestic consumers. The Garment District in Manhattan and emerging design studios in Brooklyn concentrate independent leather goods specialists targeting mid-tier positioning.
Japan
Digital-native collectors in Tokyo and Osaka treat handbags as liquid assets through authentication-driven resale platforms. METI guidelines on circular economy implementation encourage repair and refurbishment service expansion. The Ginza and Omotesando retail corridors host flagship environments where experiential programming defends leather goods traffic against digital erosion.
Global Handbags Market Competitive Landscape
Player mix skews toward vertically integrated heritage houses with captive tannery relationships and multi-brand luxury conglomerates with portfolio diversification strategies. Structure concentrates around three archetypes: ultra-luxury specialists commanding scarcity premiums, diversified luxury groups leveraging cross-brand synergies, and accessible-premium houses scaling through direct-to-consumer channels. Dominant competitive moves include backward integration into raw material supply and geographic expansion through flagship retail networks.
Within the ultra-luxury tier, Hermès International SA exemplifies deliberate scarcity mechanics and wait-list positioning. LVMH Moët Hennessy Louis Vuitton SE and Kering SA occupy positions as diversified luxury groups with vertical control over leather supply chains and multi-brand portfolio architectures. These three anchors represent distinct strategic approaches to margin capture across premium price architecture.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Hermès International SA |
| Kering SA |
| Chanel SA |
| Prada SpA |
| Burberry Group PLC |
| Tapestry Inc. |
| Michael Kors LLC |
| Guccio Gucci SpA |
| Others |
Supply & Pricing Matrix
REACH Annex XVII compliance gates both supplier qualification and price differentiation simultaneously, as tanneries investing in vegetable-tanning infrastructure capture certification premiums while legacy chromium processors face margin compression from elevated working capital requirements.
Pricing Analysis
Legacy full-grain construction commands sustained premiums against next-generation mycelium alternatives and prior-generation bonded leather, with three-tier pricing structure across premium, standard, and economy levels separating heritage atelier output from mid-tier synthetic engineering and entry-level canvas formats. Price differentiation rests on certification grade and brand provenance, with EU-compliant vegetable-tanned variants securing shelf-space premiums. Cost compression in synthetic tiers is intensifying because biomimetic polymer engineering narrows performance gaps. Budget-conscious buyers exhibit highest price sensitivity, while ultra-luxury collectors show near-zero elasticity.
Supply Chain Analysis
Italian tannery clusters in Tuscany and Veneto underwrite premium hide finishing capacity for heritage houses, creating single-source vulnerability when REACH restrictions force chemical reconfiguration. Raw material flows draw from French calf farms, Brazilian steer hides, and Zimbabwean crocodile ranches. Supply chain risk centers on artisan succession gaps as hand-stitching skills concentrate among aging workforces in Paris and Florence. Distribution runs through department store concessions in Tokyo and Seoul, direct-to-consumer flagships in Shanghai, and authenticated resale platforms in Osaka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized craftsmanship capabilities are becoming the binding constraint, as hand-finishing expertise concentrates among diminishing cohorts in European atelier districts while demand for scarcity-positioned leather goods expands across Asian collector markets.
For Market Incumbents: Secure captive tannery relationships in Veneto and Tuscany before REACH compliance costs further consolidate supplier tiers, while investing in blockchain provenance infrastructure to defend against authentication-driven resale platforms eroding primary channel margins. Backward integration into vegetable-tanning chemistry and in-house training academies addresses artisan succession gaps threatening production continuity. For New Entrants and Emerging Players: EU Green Deal certification fast-tracks market access for mycelium and pineapple-fiber alternatives, enabling penetration of animal-welfare-positioned segments in German and Japanese urban centers where performance parity justifies premium positioning. Target India's PLI-supported manufacturing zones for cost-competitive export capacity, leveraging direct-to-consumer digital channels to bypass wholesale margin extraction. For Investors and Strategic Acquirers: SAMR enforcement milestones reshape the acquisition landscape by validating brand equity protection mechanisms in Chinese retail channels, extending viable holding periods for heritage houses with established domestic footprints. Mid-sized houses with captive Italian tannery relationships and underdeveloped Asian retail networks represent the most attractive target archetype. Monitor mycelium production scale-up announcements as the signal indicating when synthetic substitution pressure will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tannery Acquisition | Secures full-grain supply for structured silhouettes against REACH-driven consolidation. |
| Blockchain Provenance Deployment | Commands retail premiums in European markets through distributed ledger verification. |
| Mycelium Material Partnership | Captures animal-welfare-positioned buyers seeking performance parity with traditional hides. |
| India Manufacturing Facility | Exploits PLI scheme incentives to diversify production away from coastal China. |
| Authentication-Driven Resale Platform | Extends product lifecycles while capturing margin from secondary circulation in Tokyo. |
Research Methodology
Cross-validation between executive interviews and customs trade data anchors the qualitative findings, combining primary conversations with leather goods brand managers, tannery procurement directors, department store category buyers, and resale platform authentication specialists with secondary validation from EU ECHA chemical filings, Italian industrial association reports, and Chinese SAMR enforcement records. Bottom-up demand modeling and top-down supply capacity assessments triangulate volume estimates.
Sensitivity analysis across material substitution scenarios and regulatory implementation timelines shapes the analytical framework, with segmentation dimensions spanning product format, material chemistry, distribution channel, and buyer archetype across the analysis window. CAGRs derive from fitted growth curves calibrated against historical luxury goods adoption patterns and emerging market wealth expansion trajectories, incorporating hide price volatility and artisan wage inflation as industry-specific inputs.
Decision-makers should treat outputs as directional under sustained China demand growth and REACH enforcement continuity assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as mycelium production economics and Indian manufacturing scale-up evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Couture Millinery Market