
 Middle East and Africa Leather Goods Market | 2026-2036
Middle East and Africa Leather Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Leather Goods Market Foresight
Luxury hospitality procurement in Dubai and Riyadh is repositioning supplier relationships toward regional tanneries with long-term offtake agreements. Chalhoub Group leverages its Gulf retail network to dominate high-end handbag distribution across duty-free and mall channels. Saudi Leather Industries Company anchors domestic production capacity with integrated tanning and finishing operations in Riyadh. LVMH Moët Hennessy Louis Vuitton SE competes through controlled boutique expansion and localized leather craftsmanship training programs in the UAE.
Leather goods encompass finished articles crafted from animal hides through tanning, dyeing, and stitching processes where chromium-based mineral tanning achieves water resistance and structural durability for commercial applications. These products serve fashion accessorization, professional utility, and status signaling across consumer and business contexts. Footwear and handbags generate the deepest margin pools within product type segments, while full grain material commands premium positioning due to unaltered fiber structure and patina development. The online distribution channel grows fastest among end-user pathways as Gulf e-commerce infrastructure matures and social commerce penetrates younger demographics.
South Africa's Department of Trade, Industry and Competition enforces local content requirements that shape leather component sourcing decisions for automotive and industrial buyers. The UAE's Emirates Authority for Standardization and Metrology governs product labeling and chemical content limits for imported leather articles entering Dubai and Abu Dhabi retail channels. REACH-equivalent frameworks under Gulf Cooperation Council harmonization talks will determine future market access conditions for European tanneries. Stakeholders must monitor regulatory divergence between GCC standardization and South Africa's independent conformity assessment regime when configuring regional supply architectures.
Market Dynamics
Luxury hospitality procurement in Dubai and Riyadh is forcing tannery relationships toward long-term offtake structures, compressing spot-market flexibility for finished leather supply. This concentration of buyer power is restructuring how regional producers secure hide inputs and price finished goods.
Growth Catalysts
- Local content mandates:South Africa's Department of Trade, Industry and Competition enforces domestic sourcing requirements under automotive programs, redirecting leather component procurement toward domestic tanneries.
- E-commerce infrastructure maturation:Gulf digital payment rails and last-mile logistics expansion unlock direct-to-consumer channels for handbag and accessory brands.
- Chromium tanning dominance:Water-resistant mineral tanning processes enable durable footwear and luggage production suited to regional climate conditions.
Market Restraints
- Hide supply volatility:Livestock disease cycles in East Africa create raw material input instability for Ethiopian and Kenyan tannery clusters.
- REACH-equivalent uncertainty:Gulf Cooperation Council chemical content harmonization talks remain unresolved, delaying European tannery market access clarity.
- Synthetic leather substitution:Polyurethane and plant-based alternatives capture price-sensitive segments in mass-market footwear.
Strategic Opportunities
- Underpenetrated East African manufacturing:Ethiopia's industrial park infrastructure and duty-free export access to US and EU markets attract cut-make-trim investment.
- Social commerce penetration:Instagram and TikTok shopping integrations capture younger demographics in Saudi Arabia and UAE luxury accessory segments.
- Automotive leather specification:Premium vehicle interior programs in South Africa and Morocco create certified upholstery demand pools.
Industry Challenges
- Artisan skill scarcity:Hand-stitching and edge-finishing craft traditions face generational transfer gaps in Moroccan and Tunisian production centers.
- Multi-jurisdiction compliance:Divergent labeling requirements between UAE's Emirates Authority for Standardization and Metrology and South Africa's independent conformity regime fragment quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Leather Goods Market |
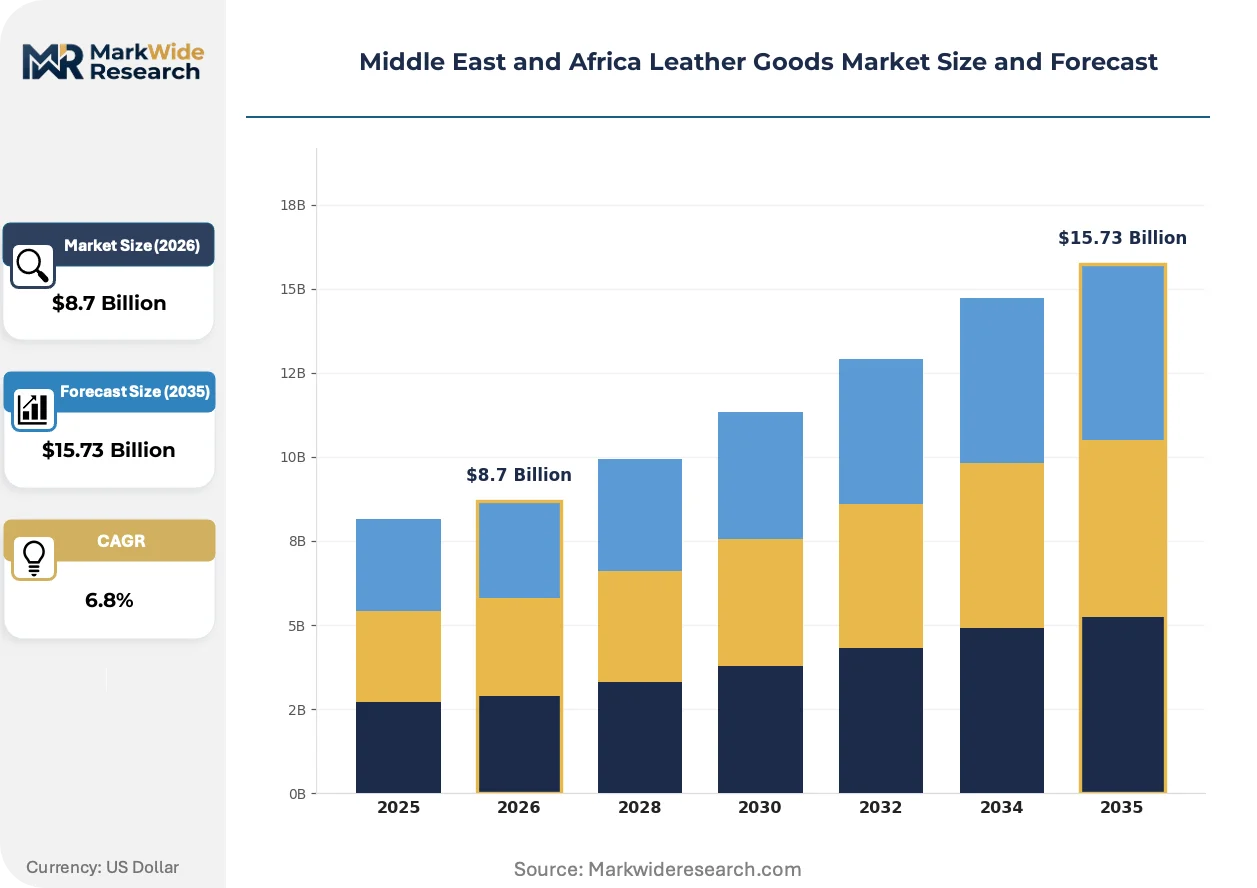
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handbags, Belts, Wallets, Footwear Material: Full Grain, Top Grain, Suede, Faux Leather End User: Men, Women, Children, Businesses Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Nike Inc., Chalhoub Group, LVMH Moët Hennessy Louis Vuitton SE, Saudi Leather Industries Company, Azadea Group, Kering SA, Puma SE, Alina Leather, Hermès International S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Leather Goods Market Shifts & Advancements
Digital traceability systems and bio-based material science are actively rewiring how leather goods are sourced, certified, and sold across Middle East and Africa channels. These shifts compress traditional opaque supply chains while opening premium positioning opportunities.
Blockchain-enabled hide-to-handbag tracking is rewriting provenance verification standards for Gulf luxury retail. Emirates Authority for Standardization and Metrology-aligned retailers now demand batch-level transparency for high-value accessories. This compression of information asymmetry enables direct farmer-to-brand contracting in East African supply zones.
REACH-equivalent frameworks under Gulf Cooperation Council harmonization talks are reshaping chemical compliance obligations for European and Asian tannery suppliers. The industrial consequence is pre-certification investment ahead of formal adoption. Small and mid-scale finishing operations in UAE free zones face the steepest adaptation timelines.
Social commerce penetration among Gulf consumers under twenty-five is fragmenting traditional duty-free and mall channel dominance. Influencer-led discovery replaces boutique foot traffic for initial brand contact. This behavioral rotation is most visible in Saudi Arabia's Riyadh and Jeddah metropolitan corridors where smartphone purchasing exceeds desktop transactions.
Middle East and Africa Leather Goods Market Segmentation
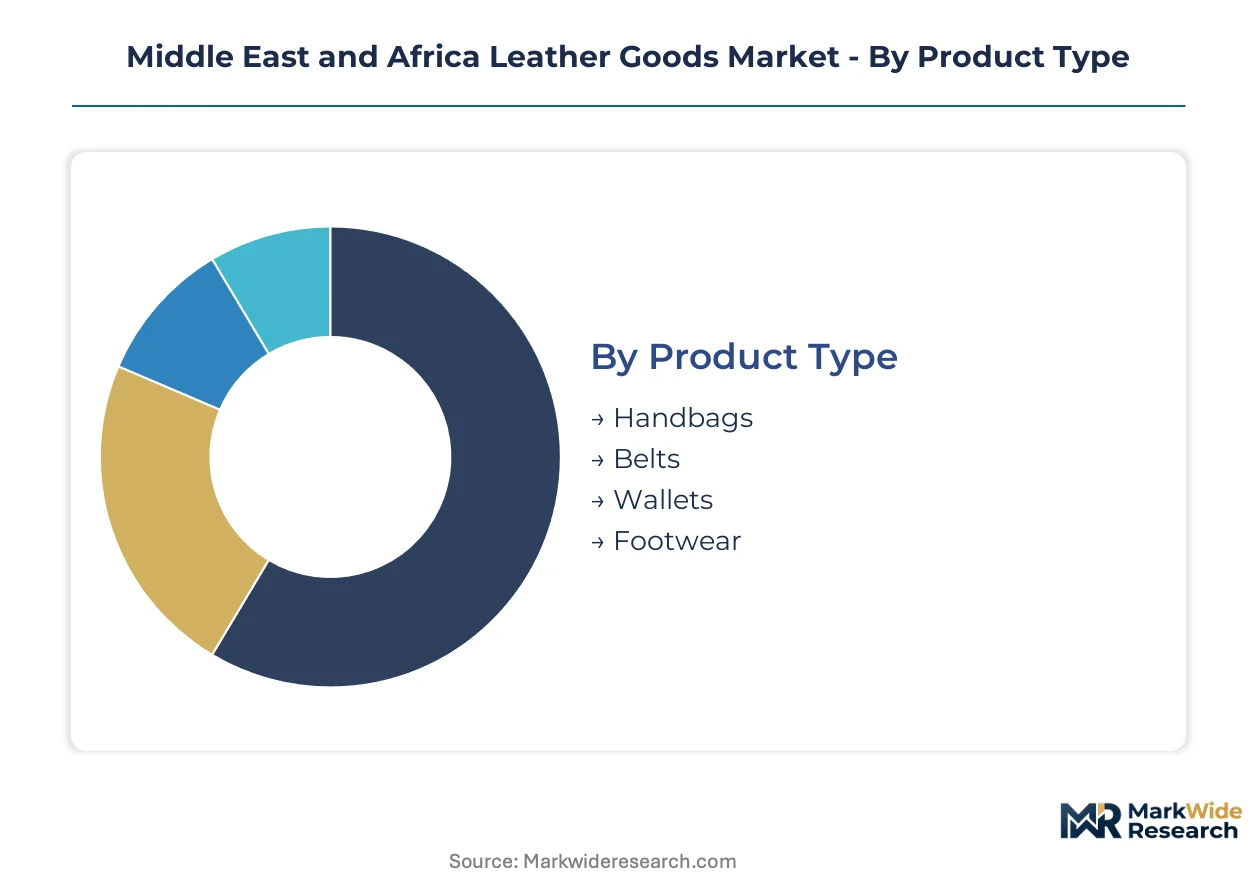
Leather goods segmentation across the Middle East and Africa reveals how material specifications, gender-based purchasing patterns, and channel infrastructure determine margin capture. Manufacturers configure production lines around chromium-tanned durability requirements for Gulf climate conditions while navigating divergent compliance regimes between South Africa's DTIC mandates and UAE's ESMA labeling standards.
Product Type:
Construction complexity and finishing labor intensity separate margin tiers across finished goods categories.
- Handbags:Structured designs require edge-finishing craftsmanship and hardware integration that commands premium positioning in Dubai Mall and Yas Mall retail corridors. Chalhoub Group distribution networks concentrate demand for luxury silhouettes with regional tannery leather sourcing.
- Footwear:Chromium-based mineral tanning achieves water resistance essential for durability across Saudi Arabia and UAE climate exposure. Saudi Leather Industries Company anchors domestic production capacity with integrated finishing operations serving this segment.
- Belts:Smaller surface area reduces hide input costs while buckle hardware determines price tier placement.
- Wallets:Compact dimensions favor automated cutting processes and standardized stitching patterns for volume production.
Mature deployment sits with Footwear. Newer deployment is concentrated in Handbags as social commerce penetration fragments traditional mall channel dominance.
Material:
Hide processing depth and fiber structure integrity create distinct performance and price positioning tiers.
- Full Grain:Unaltered fiber structure retains natural markings and develops distinctive patina over time, commanding premium placement in luxury hospitality procurement programs across Riyadh and Dubai. Long-term offtake agreements with regional tanneries secure input supply for this grade.
- Top Grain:Sanded and finished surface delivers consistent appearance suited to mass-market accessory lines with price-sensitive positioning. Ethiopian and Kenyan tannery clusters supply this grade despite livestock disease cycle volatility in East Africa.
- Suede:Split leather construction creates napped surface texture requiring specialized finishing equipment and climate-controlled storage.
- Faux Leather:Polyurethane and plant-based alternatives capture substitution demand in price-driven footwear segments as synthetic material science advances.
Production gravity centers on Full Grain for prestige positioning. Volume scaling concentrates in Top Grain as automotive leather specification programs in South Africa and Morocco expand certified upholstery demand.
End User:
Purchasing authority and occasion-based usage patterns shape design specifications and channel strategy.
- Women:Accessory rotation frequency and status signaling intensity drive handbag and wallet category depth in UAE luxury retail corridors. Instagram and TikTok shopping integrations capture discovery-to-purchase journeys among under-twenty-five demographics in Riyadh and Jeddah.
- Men:Professional utility focus concentrates belt and footwear procurement in business districts with durability specifications prioritized over fashion cycle responsiveness.
- Children:Growth-stage replacement cycles and abrasion resistance requirements favor synthetic leather substitution at entry price points.
- Businesses:Corporate gifting programs and uniform accessory standardization create bulk procurement channels with customization requirements.
Revenue concentration aligns with Women. Fastest expansion trajectory belongs to Businesses as corporate procurement formalizes leather goods into employee benefit and client relationship programs.
Distribution Channel:
Customer acquisition cost and inventory velocity trade-offs determine channel mix optimization.
- Online:Gulf digital payment rails and last-mile logistics maturation enable direct-to-consumer penetration with influencer-led discovery replacing boutique foot traffic. Smartphone purchasing exceeds desktop transactions across Saudi metropolitan corridors.
- Retail Stores:Controlled boutique expansion by LVMH and Chalhoub Group network dominance maintain tactile evaluation importance for high-value handbag transactions in duty-free and mall channels.
- Wholesalers:Aggregated volume purchasing serves secondary city distribution and price-tier diversification requirements.
- Direct Sales:Artisan craft demonstrations and customization consultations preserve margin capture in Moroccan and Tunisian production centers facing generational skill transfer gaps.
Established infrastructure sits with Retail Stores. Channel investment flows concentrate in Online as e-commerce infrastructure maturity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE and Saudi Arabia concentrate luxury leather goods demand through hospitality procurement and retail corridor expansion. South Africa anchors industrial leather consumption via automotive programs. East African manufacturing clusters attract investment through trade access advantages.
United Arab Emirates
Dubai Mall and Yas Mall retail corridors drive handbag and accessory demand through duty-free and luxury boutique channels. Emirates Authority for Standardization and Metrology governs chemical content limits and product labeling for imported articles. Dubai's free zone infrastructure hosts finishing operations serving Gulf distribution networks.
Saudi Arabia
Riyadh and Jeddah metropolitan corridors experience smartphone purchasing dominance among under-twenty-five demographics. Social commerce penetration fragments traditional mall channel dominance for initial brand discovery. Saudi Leather Industries Company maintains integrated tanning and finishing capacity in Riyadh serving domestic footwear production.
South Africa
Automotive Production and Development Programme local content requirements redirect leather component procurement toward domestic tanneries. Department of Trade, Industry and Competition enforcement shapes sourcing decisions for vehicle interior programs. KwaZulu-Natal and Eastern Cape industrial zones concentrate certified upholstery manufacturing for premium vehicle specifications.
Ethiopia
Industrial park infrastructure and duty-free export access to US and EU markets attract cut-make-trim investment for volume production. Livestock disease cycles in surrounding East African regions create raw material input instability requiring buffer inventory strategies. Addis Ababa and Hawassa industrial corridors host export-oriented leather goods assembly for international brands.
Morocco
Artisan craft traditions in leatherworking face generational transfer gaps despite continued demand for hand-finished luxury goods. European proximity and trade agreement access sustain export-oriented production for continental markets. Casablanca and Marrakech production centers balance mechanized cutting with specialized hand-stitching for premium positioning.
Middle East and Africa Leather Goods Market Competitive Landscape
Gulf-based retail networks anchor one tier; European luxury houses and regional industrial producers hold complementary positions. Market structure reflects concentration among integrated retail distributors and specialized manufacturers with long-term tannery relationships. Three archetypes dominate: hospitality procurement specialists, vertically integrated regional producers, and global luxury brands with localized craftsmanship training. Competitive moves center on controlled boutique expansion and strategic offtake agreements with regional tanneries.
Within the integrated regional producer tier, Saudi Leather Industries Company exemplifies captive supply chain architecture spanning tanning through finished goods. Among Gulf retail specialists, Chalhoub Group occupies a position bridging duty-free distribution and mall-based luxury access. LVMH Moët Hennessy Louis Vuitton SE represents the global luxury house archetype with localized training investments in UAE craftsmanship programs.
| Leading Market Players |
|---|
| Nike Inc. |
| Chalhoub Group |
| LVMH Moët Hennessy Louis Vuitton SE |
| Saudi Leather Industries Company |
| Azadea Group |
| Kering SA |
| Puma SE |
| Alina Leather |
| Hermès International S.A. |
| Others |
Supply & Pricing Matrix
Chromium-based mineral tanning adoption across Ethiopian and Kenyan tannery clusters is compressing per-unit finishing costs while simultaneously concentrating buyer power among Dubai and Riyadh hospitality procurement programs. This production-method transition enables long-term offtake agreements that displace spot-market flexibility and restructure how regional producers secure hide inputs and price finished goods.
Pricing Analysis
Volume scaling concentrates in top-grade automotive upholstery for South African vehicle programs while margin capture concentrates in full-grain handbags for UAE luxury retail corridors. Price differentiation separates unaltered fiber structure with natural patina development from sanded and finished surfaces suited to mass-market accessory lines. Pricing pressure stems from polyurethane and plant-based synthetic alternatives capturing substitution demand in price-sensitive footwear segments. Corporate gifting programs exhibit highest price sensitivity due to bulk procurement standardization, while individual luxury consumers in Dubai Mall and Yas Mall channels demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Emirates Authority for Standardization and Metrology-aligned retailers now mandate batch-level transparency that forces multi-supplier qualification across Ethiopian, Kenyan, and South African tannery clusters. Raw material flows draw from East African livestock herds, chromium chemical inputs, and hardware components for buckle and fastener integration. Single-source vulnerability sits with hide supply instability from regional disease cycles. Distribution runs through Chalhoub Group duty-free networks and direct-to-consumer online channels as Gulf digital payment rails mature.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
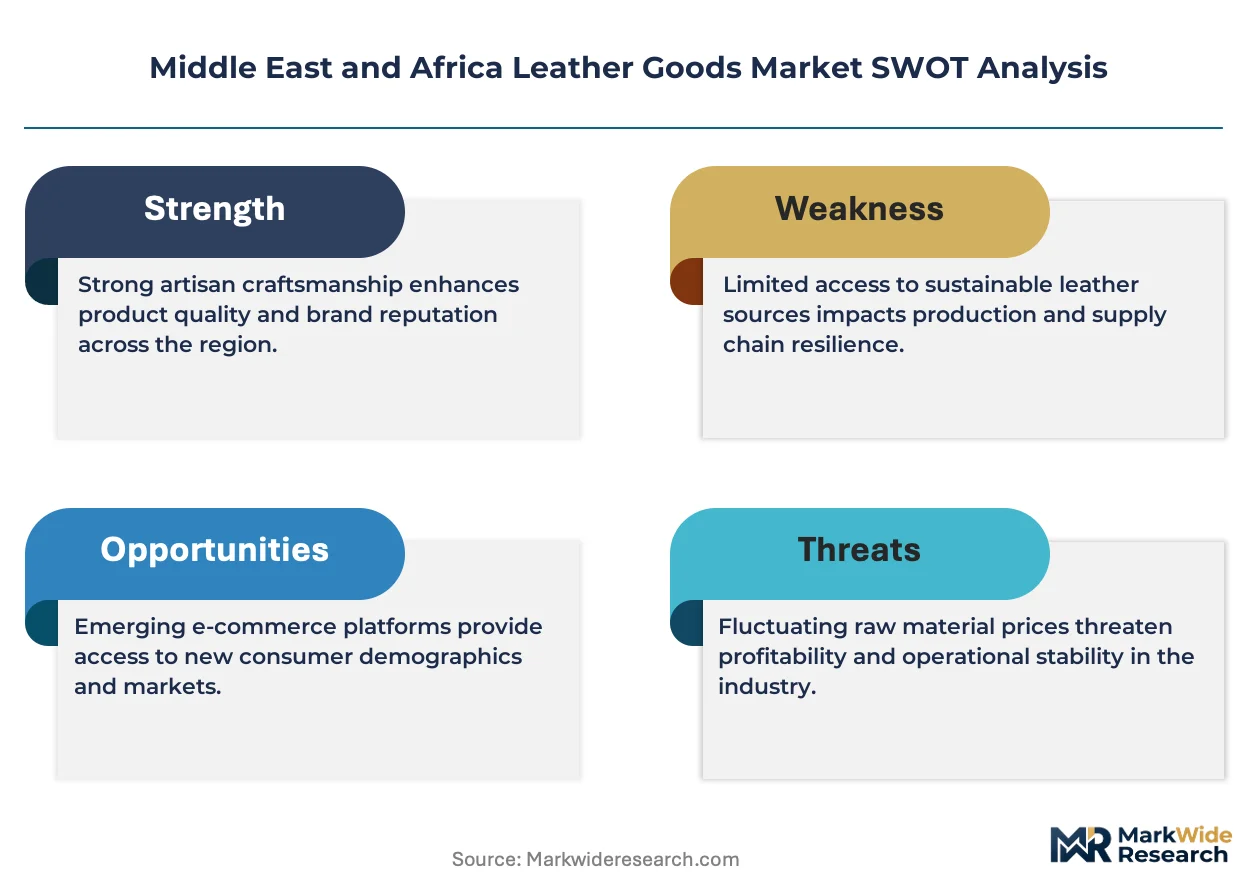
This market functions as a vertical-integration race where captive control over tanning operations determines margin defense against synthetic substitution and regulatory compliance cost escalation.
For Market Incumbents: Cement long-term offtake agreements with Ethiopian and Kenyan tannery clusters before REACH-equivalent Gulf Cooperation Council frameworks formalize. Secure artisan craftsmanship training pipelines in Moroccan and Tunisian production centers to counter generational skill transfer gaps. Backward integration into hide sourcing buffers against East African livestock disease volatility.
For New Entrants and Emerging Players: Enter via social commerce penetration among under-twenty-five demographics in Riyadh and Jeddah metropolitan corridors where smartphone purchasing exceeds desktop transactions. Target cut-make-trim assembly in Hawassa industrial parks leveraging duty-free export access to US and EU markets. Deploy influencer-led discovery campaigns on Instagram and TikTok shopping integrations for initial brand contact.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated regional producers with captive tanning-through-finishing operations and established Emirates Authority for Standardization and Metrology compliance infrastructure. Acquisition targets should demonstrate certified upholstery supply relationships with South African automotive programs. The signal to watch is resolution of Gulf Cooperation Council chemical content harmonization talks determining European tannery market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Tannery Offtake Agreement | Dubai hospitality procurement programs secure full-grain supply chains against spot-market volatility. |
| Social Commerce Platform Integration | Saudi under-twenty-five demographics shift discovery-to-purchase journeys away from mall foot traffic. |
| Artisan Craftsmanship Training Pipeline | Moroccan production centers address generational hand-stitching skill transfer gaps. |
| Automotive Upholstery Certification | South African DTIC local content mandates redirect leather component procurement toward domestic tanneries. |
| Blockchain Hide-to-Handbag Traceability | Emirates Authority for Standardization and Metrology-aligned retailers demand batch-level transparency verification. |
Research Methodology
Multi-period observation of tannery capacity utilization, hide input pricing, and hospitality procurement contract structures anchored the trend analysis, supplemented by interviews with regional distribution network heads, automotive component procurement managers, luxury retail category buyers, and Emirates Authority for Standardization and Metrology compliance officers. Secondary validation drew from customs and trade data, industrial park development records, Gulf Cooperation Council regulatory harmonization documentation, and automotive production program disclosures. Bottom-up assembly of facility-level production capacity and top-down demand estimation from retail corridor foot traffic and e-commerce transaction data were triangulated for cross-verification.
Input-output matrices mapped chromium tanning chemical flows, hide supply from East African livestock clusters, and finished goods distribution through duty-free and direct-to-consumer channels across the analysis window. Segmentation dimensions modeled included product type construction complexity, material grade tier, gender-based purchasing patterns, and distribution channel customer acquisition cost structures. CAGRs were derived from slope analysis of period-to-period value progression adjusted for inflation and currency effects. Industry-specific forecast inputs incorporated REACH-equivalent framework adoption timelines and social commerce penetration rates among Gulf demographics.
Revisions become necessary when Gulf Cooperation Council chemical content harmonization talks resolve with stricter-than-anticipated compliance obligations, when East African livestock disease cycles disrupt hide supply beyond buffer inventory capacities, or when synthetic leather material science advances accelerate substitution in mass-market footwear segments. Deviation in regulatory adoption timelines or raw material input stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Decorative Accessories Market