
 Cufflink Market | 2026-2036
Cufflink Market Size, Share, and Industry Trends Forecast 2026-2036
Cufflink Market Analysis
Titanium and surgical-grade stainless steel are displacing traditional brass and nickel alloys in mid-tier collections, which is realigning cost structures and supplier relationships across the value chain. Cartier sustains its position through vertically integrated ateliers in Switzerland. Tiffany & Co. leverages its heritage silverwork expertise to command premium positioning in North American channels. Montblanc anchors its cufflink portfolio within broader men's accessory ecosystems, reducing customer acquisition costs.
A cufflink is a decorative fastener comprising two linked discs or ornamental heads joined by a short post or chain mechanism, typically manufactured through lost-wax casting, CNC milling, or hand-finishing techniques, and designed to secure shirt cuffs while serving as a visible status signal in formal and business attire. Metal segments dominate unit economics due to perennial demand for precious and semi-precious alloys in gifting occasions. Novelty and themed design types attract younger demographics through limited-edition collaborations and pop-culture licensing, though these SKUs carry higher inventory risk and shorter lifecycle curves.
REACH nickel-release thresholds and EU Green Deal traceability requirements constrain alloy sourcing and mandate expanded supplier documentation across European distribution networks. The US Consumer Product Safety Commission monitors lead content in costume jewelry imports, shaping compliance costs for plastic and coated-metal entry-level lines. Stakeholders must monitor evolving material disclosure mandates and assess whether recycled-content claims will become a qualifying criterion for department store placement.
Market Dynamics
REACH nickel-release thresholds and EU Green Deal traceability mandates are forcing wholesale reformulation of base metal alloys across European supply chains, compressing margins for brass-dependent manufacturers while rewarding early adopters of surgical-grade stainless and titanium alternatives.
Growth Catalysts
- Post-pandemic formal dress normalization:Milan, London, and New York menswear retailers are expanding accessory assortments as office attendance rebounds and wedding calendars refill.
- China's gift-giving culture:Domestic luxury consumption sustains premium accessory purchases during Lunar New Year and corporate gifting seasons.
- REACH compliance as competitive moat:Early certification against nickel-release standards locks out smaller competitors from EU department store placement.
Market Restraints
- Raw material cost volatility:Rhodium and palladium plating costs fluctuate with automotive catalyst demand, squeezing margin on precious-metal finishes.
- Supplier concentration in Pforzheim:German jewelry component clusters control 60% of European finding and mechanism supply, creating single-point vulnerability.
- Substitution by magnetic clasps:Convenience-driven younger professionals in tech and creative sectors increasingly skip cufflinks for button-down or band-collar shirts.
Strategic Opportunities
- Underpenetrated Indian formalwear:Rising white-collar employment in Mumbai and Bangalore creates first-time buyer pools for entry-luxe steel and titanium lines.
- EU Green Deal recycled-content mandates:Early positioning with verified recycled silver and reclaimed ocean plastics secures preferential retail placement by 2027.
- Direct-to-consumer personalization:3D configurators and laser engraving at point of order bypass wholesale margin stacking and capture full retail value.
Industry Challenges
- Lost-wax casting skill scarcity:Master craftsmen retirement in Birmingham's Jewellery Quarter outpaces apprenticeship pipeline, constraining hand-finished capacity.
- Dual certification timelines:Simultaneous REACH, US Consumer Product Safety Commission lead testing, and China's GB standards create 14-18 month product launch cycles.
- Inventory risk on licensed collaborations:Pop-culture and sports partnership SKUs face compressed sell-through windows and markdown exposure if cultural moments pass.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cufflink Market |
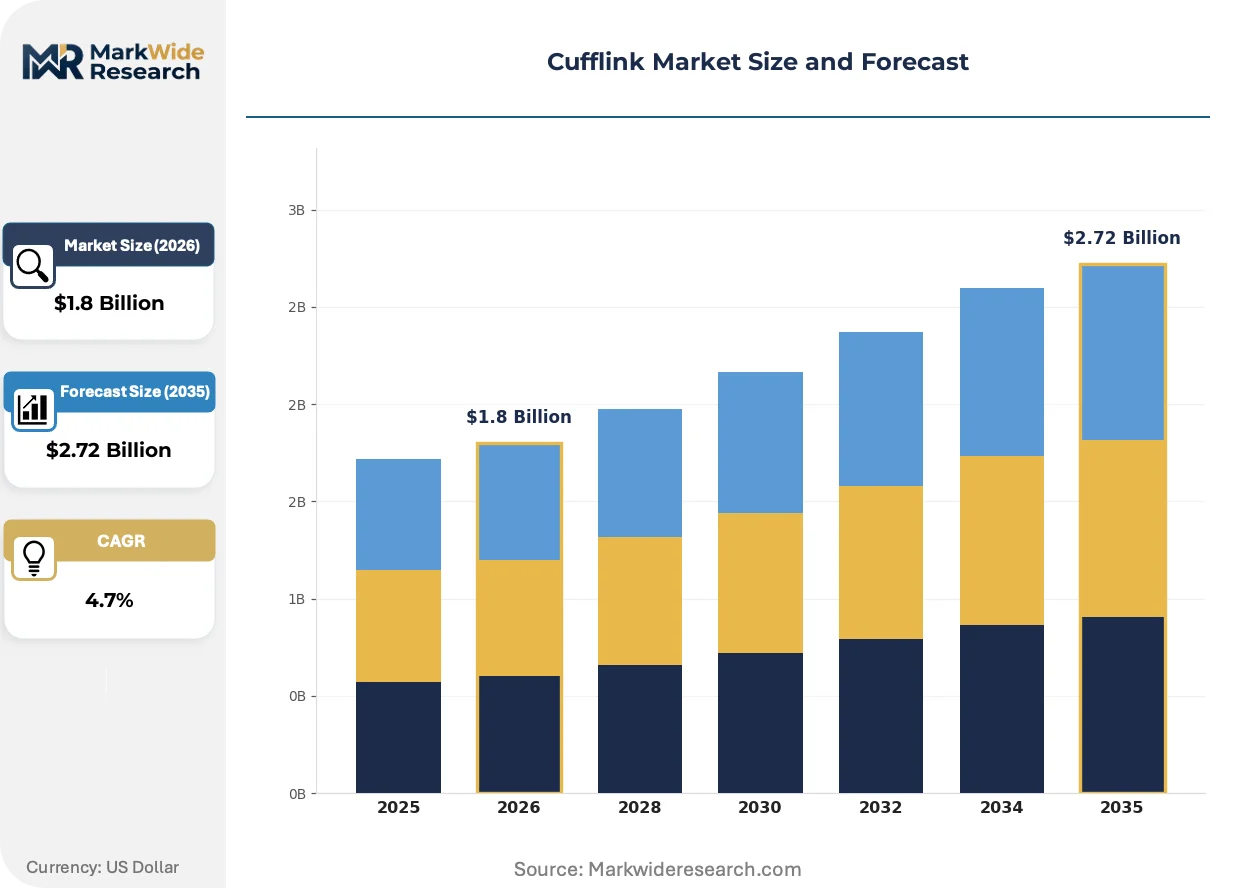
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Metal, Plastic, Fabric, Wood Style: Classic, Modern, Novelty, Vintage Design Type: Engraved, Patterned, Bejeweled, Themed End User: Men, Women, Children, Collectors |
| Companies Covered | Bulgari, Paul Smith, Cartier, Gucci, Dunhill, Tiffany & Co., Hugo Boss, David Yurman, Montblanc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cufflink Market Emerging Trajectories
Digital manufacturing and material science are compressing development cycles while regulatory disclosure requirements deepen supply chain transparency. Three forces are restructuring how value is created and captured.
Titanium and surgical-grade stainless steel is rewriting alloy economics in mid-tier collections. Young professionals entering formalwear markets prioritize hypoallergenic properties and durability over traditional precious-metal signaling. This shift collapses the historical premium attached to nickel-brass constructions and forces heritage manufacturers to retool plating lines.
EU Green Deal traceability requirements and ECHA extended supplier documentation mandates now cover cufflink findings and packaging materials. Manufacturers must map sub-tier alloy provenance back to smelter level, adding administrative overhead that favors larger houses with dedicated compliance functions. Italian and French luxury groups are responding by verticalizing component supply through captive Swiss ateliers.
Corporate procurement departments are consolidating gift purchases through centralized platforms, displacing the traditional boutique relationship model. Volume buyers now demand SKU rationalization, standardized packaging, and consolidated invoicing previously handled by individual store accounts. This concentration is most visible in London's financial services sector and Frankfurt's professional services clusters.
Cufflink Market Segmentation
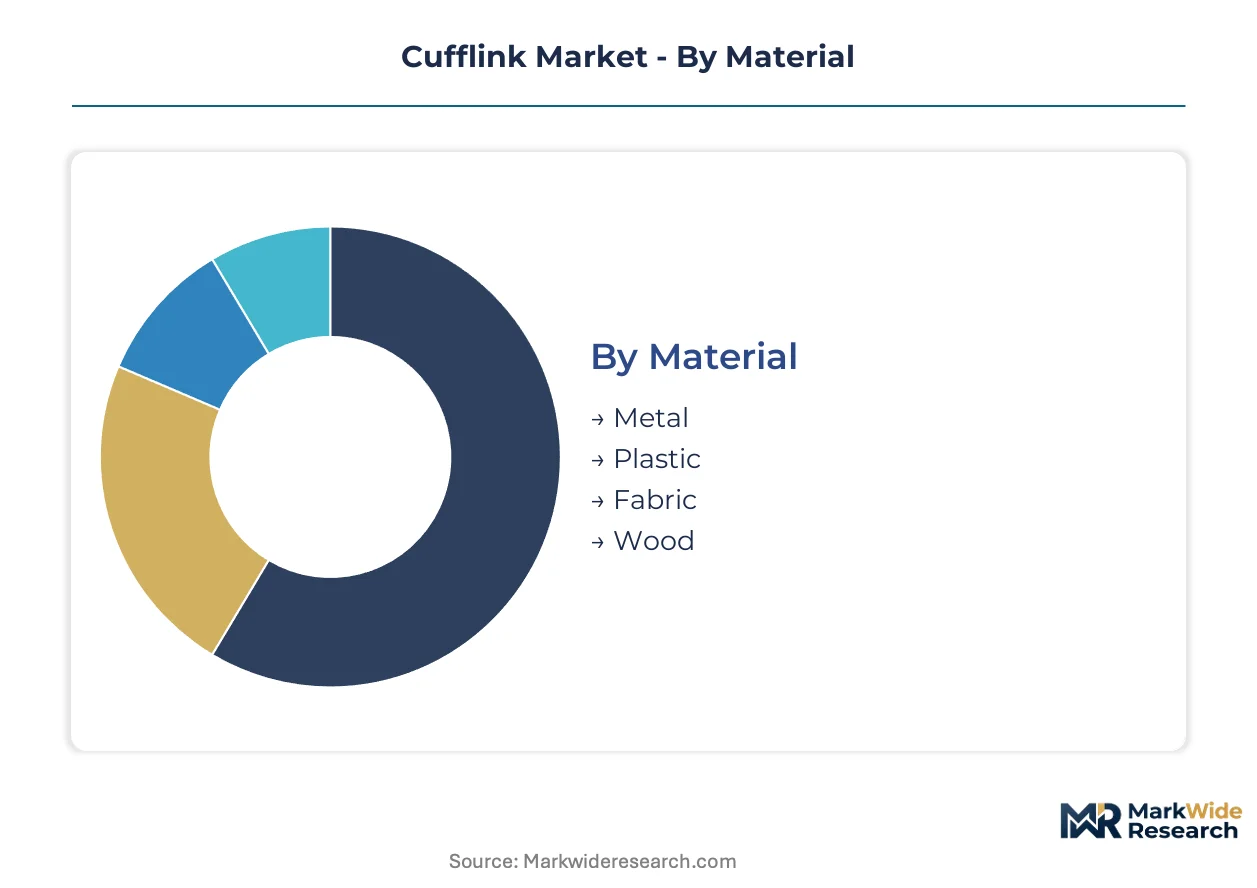
Cufflink manufacturers navigate divergent compliance burdens across material grades and design categories. Segmentation strategy determines which SKUs qualify for EU department store placement versus entry-level online channels.
Material:
REACH nickel-release certification applies differentially across material classes, with precious alloys requiring full ECHA documentation while synthetic alternatives face lighter disclosure thresholds.
- Metal:Surgical-grade stainless steel and titanium alloys dominate mid-tier collections as hypoallergenic alternatives displace nickel-brass constructions. Milan and London menswear retailers concentrate orders here for post-pandemic formalwear restocking. REACH compliance timelines favor established houses with dedicated regulatory functions.
- Plastic:Acetate and resin compounds serve novelty and costume segments with lower unit costs but compressed margin profiles. US Consumer Product Safety Commission lead-content monitoring shapes import documentation for Asian-manufactured lines.
- Fabric:Silk-covered and embroidered variants target summer formalwear and wedding-party coordination sets. Seasonal demand concentration in China's Q1 gifting calendar drives production scheduling.
- Wood:Exotic hardwood and sustainable bamboo constructions appeal to eco-positioned direct-to-consumer brands. EU Green Deal recycled-content verification remains underdeveloped for this substrate.
Metal sits at the top of the volume ranking, with titanium climbing the fastest among alloy subtypes.
Style:
Style segmentation maps directly to customer lifetime value curves, with classic designs sustaining multi-decade purchase cycles while trend-driven categories demand continuous design reinvestment.
- Classic:Round, square, and oval silhouettes in precious metals anchor heritage house portfolios. Swiss ateliers concentrate hand-finishing capacity here for Cartier and Tiffany tier positioning.
- Modern:Minimalist geometries and matte finishes attract younger professionals in Frankfurt and London financial services. Magnetic mechanism innovations compete for convenience-oriented buyers.
- Novelty:Pop-culture licensing and limited-edition collaborations generate media amplification but carry 14-18 month clearance risk if cultural moments pass.
- Vintage:Estate and reproduction Art Deco designs serve collector channels with irregular demand patterns and authentication overhead.
Classic commands the revenue base, with modern styling expanding most quickly among first-time luxury buyers.
Design Type:
Design complexity determines manufacturing process selection—lost-wax casting for dimensional pieces versus CNC milling for precision geometries—and corresponding skill requirements.
- Engraved:Monogram and crest personalization commands premium pricing in corporate gifting channels. Birmingham's Jewellery Quarter master craftsmen retirement constrains hand-engraved capacity expansion.
- Patterned:Guilloche and engine-turned surfaces differentiate mid-luxury collections without gemstone cost burden. Pforzheim component clusters supply specialized finding mechanisms.
- Bejeweled:Precious and semi-precious stone settings require dual certification under REACH and China's GB standards, extending launch timelines.
- Themed:Sports, hobby, and profession-specific motifs serve gift markets with concentrated seasonal demand and higher inventory markdown exposure.
Engraved leads volume contribution, with patterned designs gaining share fastest through mechanized production scaling.
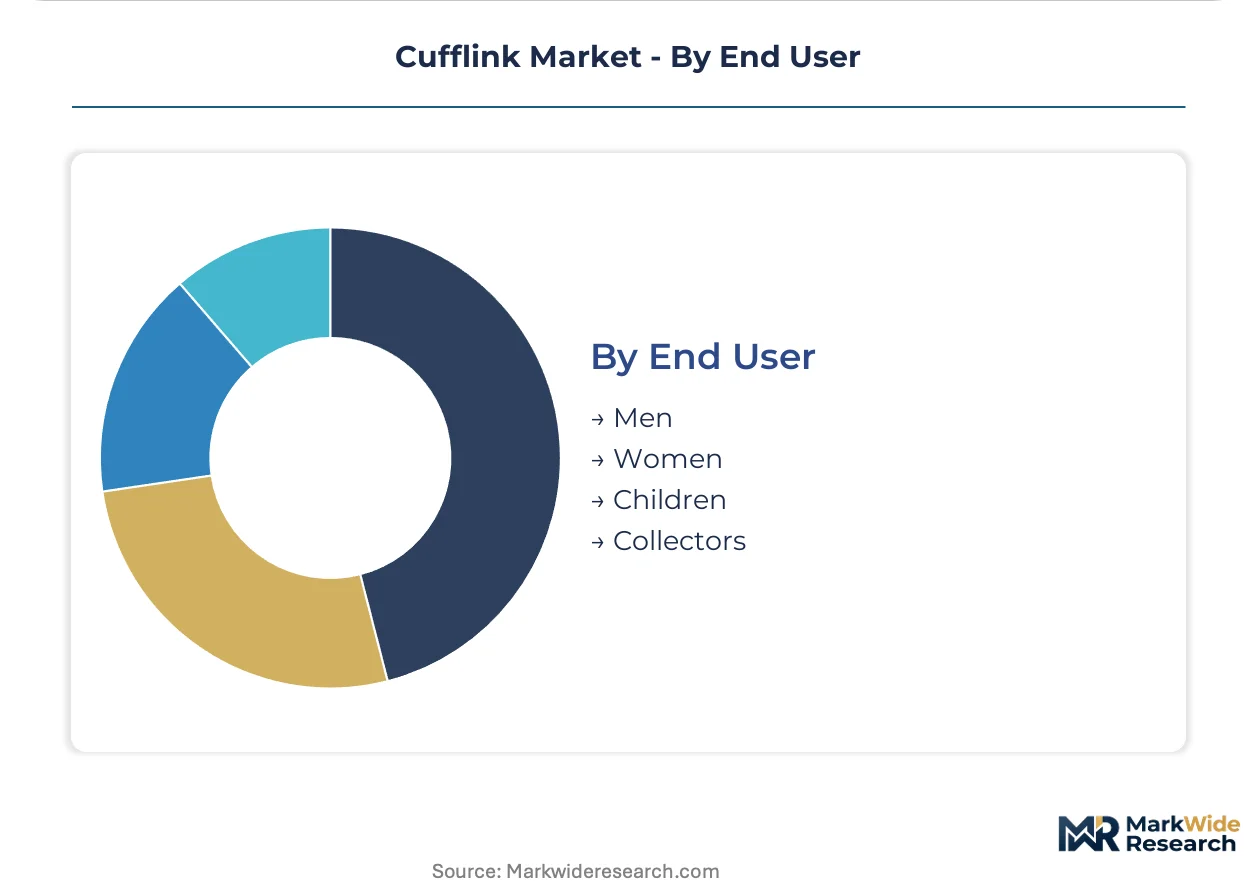
End User:
End-user segmentation reveals divergent channel strategies—men's formalwear through menswear retailers, collector markets through auction houses and specialized dealers.
- Men:Corporate and wedding occasion purchasing sustains core demand with established replenishment cycles. White-collar employment growth in Mumbai and Bangalore creates first-time buyer expansion.
- Women:Oversized and convertible designs for blouses and dresses represent an underdeveloped extension category with fit-standardization challenges.
- Children:Pageant and ceremonial occasions drive minimal volume with high safety-testing requirements for small-component regulations.
- Collectors:Limited editions and precious-metal commemorative pieces trade through specialized channels with authentication and provenance documentation requirements.
Men's segment holds the volume dominance, with collector category showing steepest expansion trajectory among high-net-worth demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pforzheim's jewelry component cluster anchors European supply for precision findings and mechanism assembly, while Milan and London menswear retailers drive demand concentration through formal accessory expansion.
United States
Tiffany & Co. and David Yurman anchor premium positioning through heritage silverwork and Fifth Avenue flagship presence. The US Consumer Product Safety Commission monitors lead content in costume jewelry imports, elevating compliance costs for entry-level coated-metal lines. New York's menswear corridor concentrates boutique distribution, with corporate gifting platforms displacing traditional store accounts.
Germany
Frankfurt's financial services sector consolidates gift procurement through centralized platforms, demanding SKU rationalization and standardized packaging. ECHA nickel-release thresholds under REACH constrain brass-dependent manufacturers, compressing margins while rewarding surgical-grade stainless adopters. Pforzheim's component clusters control sixty percent of European finding supply, creating single-point vulnerability for mechanism sourcing.
United Kingdom
London's menswear retailers expand formal accessory assortments as office attendance rebounds and wedding calendars refill. Birmingham's Jewellery Quarter faces master craftsman retirement outpacing apprenticeship pipelines, constraining hand-finished capacity for engraved and lost-wax casting lines. The British Hallmarking Council maintains precious metal authentication standards for export-bound collections.
China
Domestic luxury consumption and Lunar New Year gift-giving sustain premium accessory purchases across tier-one cities. GB standards for jewelry safety create dual certification timelines alongside REACH and US CPSC requirements, extending product launch cycles. Shanghai and Beijing concentrate white-collar employment growth, generating first-time buyer pools for entry-luxe titanium and steel collections.
Italy
Milan's menswear houses drive formal accessory restocking as post-pandemic dress codes normalize. EU Green Deal traceability mandates force mapping of sub-tier alloy provenance to smelter level, favoring larger houses with dedicated compliance functions. Swiss ateliers in Ticino and Geneva supply vertically integrated finishing capacity for heritage luxury positioning.
Cufflink Market Vendor Landscape
Global majors compete with regional champions across distribution architecture and compliance capability, producing a tiered structure where heritage houses with captive ateliers coexist with design-led independents and private-label aggregators. Consolidation concentrates around three strategic archetypes: vertically integrated Swiss-French luxury groups, British-Italian menswear-aligned accessory houses, and direct-to-consumer personalization specialists. Dominant competitive moves include backward integration into component manufacturing and geographic expansion through airport retail and Asian duty-free channels.
Within the heritage luxury tier, Cartier and Bulgari exemplify vertically integrated positioning through Swiss atelier control, while Tiffany & Co. anchors North American silverwork heritage. Montblanc occupies a distinctive position integrating cufflinks within broader men's accessory ecosystems, reducing customer acquisition costs through cross-category attachment.
| Leading Market Players |
|---|
| Bulgari |
| Paul Smith |
| Cartier |
| Gucci |
| Dunhill |
| Tiffany & Co. |
| Hugo Boss |
| David Yurman |
| Montblanc |
| Others |
Supply Flow & Price Mechanics
Master craftsman concentration in Birmingham's Jewellery Quarter compresses hand-finished capacity and widens labor-cost spreads between artisanal and mechanized production tiers. REACH nickel-release certification in the European Union and ECHA documentation mandates add compliance overhead that stratifies pricing across certified and non-certified supply bases.
Pricing Analysis
Input-cost pass-through from rhodium and palladium plating volatility squeezes margin on precious-metal finishes, forcing tiered pricing stratification across premium heritage positioning, mid-luxe titanium alternatives, and entry-level coated-steel economy lines. Price differentiation hinges on certification grade against REACH thresholds and brand heritage premium. Pricing pressure stems from raw material cost volatility in automotive-catalyst-linked metals. Corporate gifting platforms exhibit lowest price sensitivity; entry-level online channels face highest compression.
Supply Chain Analysis
Freight cost escalation on Asian-manufactured costume jewelry reshapes landed-cost economics for US Consumer Product Safety Commission-monitored imports. Component sourcing concentrates in Germany's Pforzheim cluster, China's Pearl River Delta, and Italy's Valenza Po district. Raw material dependencies include surgical-grade stainless feedstock, rhodium plating solutions, and reclaimed silver alloys. Single-source vulnerability in Pforzheim's 60% European finding supply creates structural risk. Distribution runs through menswear retailer networks, airport duty-free channels, and direct-to-consumer personalization platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal traceability costs in Europe and unregulated alloy sourcing in South Asian manufacturing hubs.
For Market Incumbents: Anticipate magnetic clasp substitution in tech-sector formalwear by locking in titanium alloy supply contracts and accelerating REACH certification lockout of smaller competitors. Prioritize backward integration into Swiss atelier capacity to secure hand-finishing throughput against Birmingham craftsman retirement. For New Entrants and Emerging Players: EU Green Deal recycled-content mandates in Europe open a window for verified reclaimed-ocean-plastic positioning and preferential department store placement. Target underpenetrated Indian formalwear in Mumbai and Bangalore with entry-luxe steel lines. Deploy 3D configurators and laser engraving for direct-to-consumer personalization bypass. For Investors and Strategic Acquirers: Heritage luxury groups with captive Swiss ateliers are the most active acquirer in this space, consolidating vertically integrated finishing capacity. Long-term viability rests on compliance infrastructure depth rather than design differentiation alone. Watch for dual-certification timeline compression as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | Early ECHA compliance locks out smaller competitors from EU department store placement. |
| Swiss Atelier Acquisition | Captive hand-finishing capacity secures heritage positioning against Birmingham craftsman scarcity. |
| Recycled-Content Verification | EU Green Deal positioning secures preferential retail placement ahead of 2027 mandates. |
| Direct-to-Consumer Platform Launch | 3D configurators bypass wholesale margin stacking and capture full retail value. |
| Indian Distribution Partnership | Mumbai and Bangalore white-collar expansion creates first-time buyer pools for entry-luxe lines. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with menswear retailer buyers, jewelry component procurement leads, regulatory compliance officers, and direct-to-consumer brand operators. Secondary validation draws from ECHA substance databases, US Consumer Product Safety Commission import monitoring records, customs trade documentation, and British Hallmarking Council standards. Bottom-up SKU-level modeling triangulates against top-down market sizing across material, style, and end-user segments.
Granularity extends to alloy-grade certification tiers, mechanism types, and regional regulatory clusters. Value projections incorporate price elasticity differentials across corporate gifting, wedding occasion, and collector channels. CAGR derivation reflects segment-level volume trajectories and pricing power dynamics across the analysis window. Industry-specific inputs include lost-wax casting capacity utilization rates and REACH compliance timeline distributions.
Revisions become necessary when regulatory threshold adjustments, raw material cost shocks, or substitution technology adoption rates diverge from modeled assumptions. Forecasts reflect documented assumptions about post-pandemic formal dress normalization velocity and China domestic luxury consumption resilience. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Personal Accessories Market