
 Communication Software Market | 2026-2036
Communication Software Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Software Market Analysis
Platform licensing revenue is rewriting profit dynamics across the communication software value chain. Microsoft Teams leverages its Office 365 integration to anchor enterprise workflows. Zoom Workplace competes through specialized video infrastructure optimized for hybrid work. RingCentral MVP extends its position via channel control over carrier-grade voice services.
Communication software comprises applications enabling real-time voice, video, and data exchange across IP networks using protocols including WebRTC, SIP, and proprietary codecs with latency targets below 150 milliseconds for synchronous sessions. Its primary purpose centers on replacing legacy PBX hardware with software-defined collaboration stacks that reduce capital expenditure while enabling geographic flexibility. Cloud-based deployment leads in new bookings as enterprises abandon on-premise maintenance burdens. AI-driven solutions represent the fastest-expanding technology segment, embedding transcription, sentiment analysis, and automated routing into core platforms. Small enterprises show concentrated demand for bundled SaaS offerings that consolidate messaging, voice, and video under single contracts.
The FCC shapes US market access through net neutrality rulings and E-Rate subsidies for educational connectivity. GDPR and the EU AI Act compel vendors to architect regional data residency and algorithmic transparency into European deployments. HIPAA compliance requirements constrain how communication platforms handle protected health information in US healthcare settings. Stakeholders must monitor how sovereign cloud mandates proliferate across jurisdictions and decide whether to build localized infrastructure or cede those markets to regional specialists.
Market Dynamics
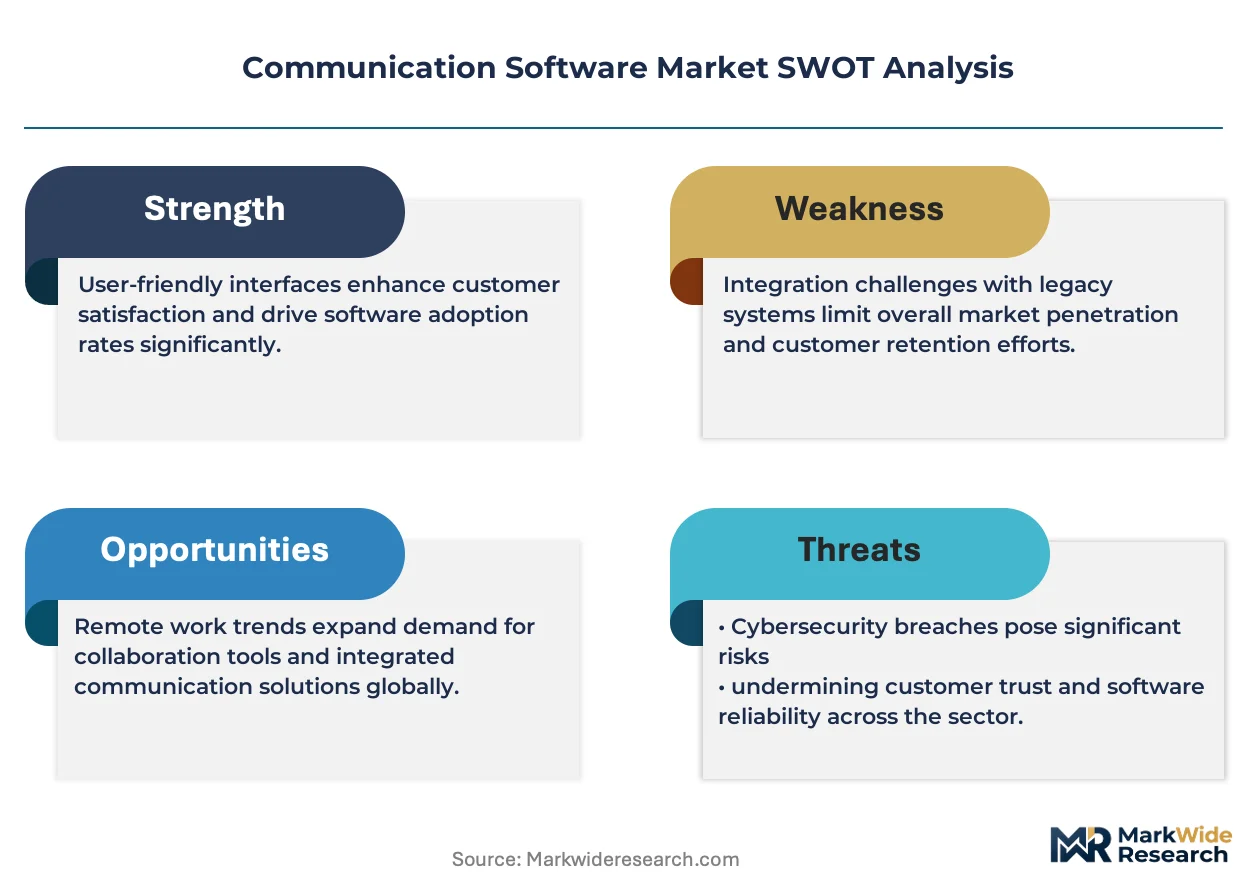
The migration from on-premise PBX hardware to cloud-native collaboration stacks is compressing deployment timelines and redistributing value capture toward platform vendors with integrated AI layers.
Growth Catalysts
- GDPR and EU AI Act:These frameworks mandate algorithmic transparency and data residency, compelling enterprises to upgrade to compliant communication platforms with sovereign cloud features.
- Healthcare telemedicine workflows:HIPAA requirements for protected health information are driving hospital systems toward certified cloud-based platforms that embed end-to-end encryption and audit trails.
- FCC E-Rate subsidies:Educational connectivity funding is accelerating K-12 district adoption of unified communications-as-a-service, replacing legacy copper infrastructure.
Market Restraints
- Specialized engineering talent scarcity:Shortages of WebRTC and SIP protocol engineers in North America and Western Europe are inflating implementation costs and extending project timelines.
- Bandwidth cost volatility:Enterprises in emerging markets face unpredictable last-mile connectivity expenses that erode the total-cost-of-ownership advantage of cloud migration.
- Interoperability limitations:Proprietary codecs from dominant platform vendors create vendor lock-in that fragments enterprise communication environments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentives for domestic data center and device production are creating openings for communication software vendors to localize hosting infrastructure.
- Convergence of WebRTC and edge AI:Real-time transcription and sentiment analysis deployed at the network edge opens new use cases in financial services trading floors and emergency response.
- Japan's METI digital transformation mandates:SMB modernization requirements are creating channel opportunities for bundled SaaS offerings that consolidate messaging, voice, and video.
Industry Challenges
- Multi-cloud certification complexity:Achieving FedRAMP, ISO 27001, and SOC 2 Type II compliance simultaneously requires 18-24 month timelines that delay market entry.
- Legacy PBX integration friction:Hybrid deployments demand specialized professional services to bridge TDM-to-IP gateways, constraining margin expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Software Market |
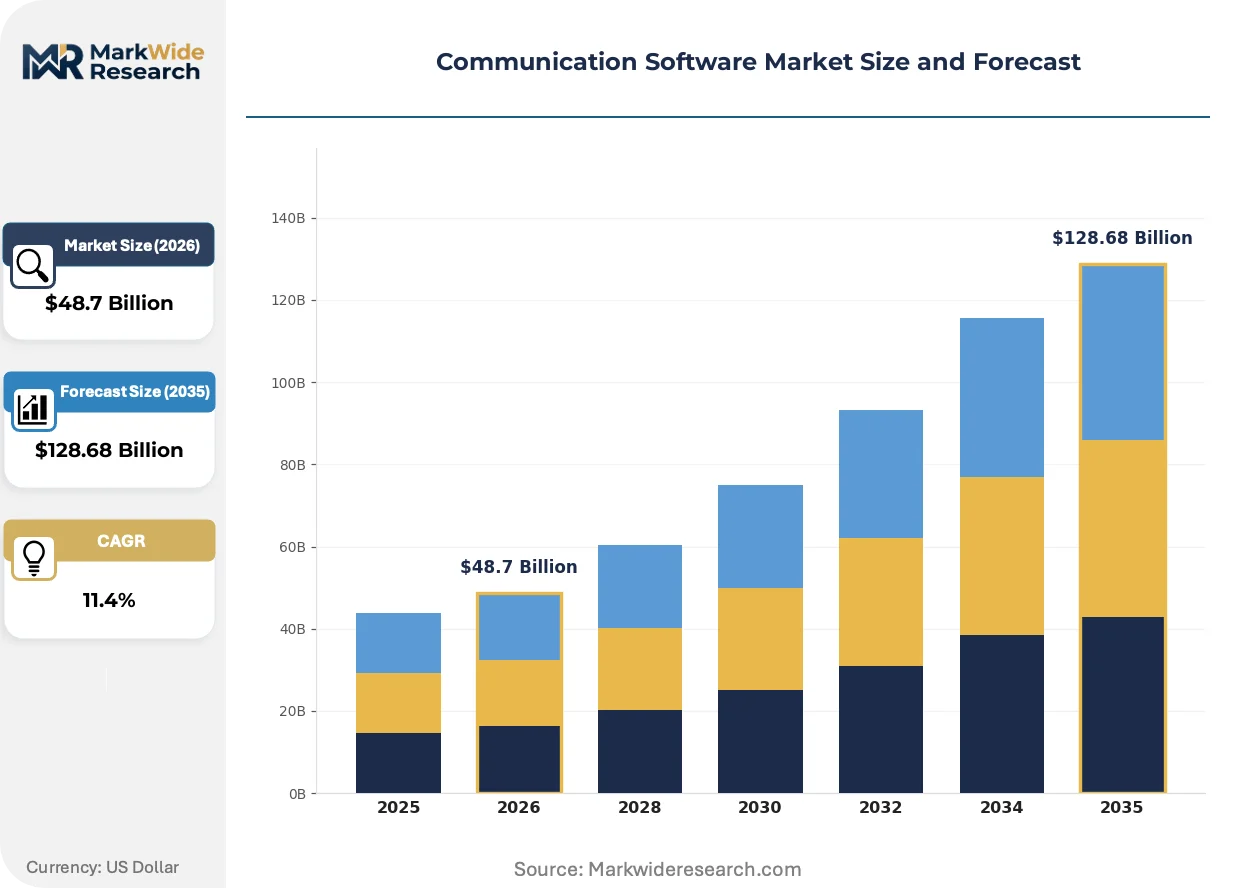
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing, Instant Messaging, Voice Calling, Collaboration Tools Deployment: On-Premise, Cloud-Based, Hybrid, Dedicated Server End User: Small Enterprises, Large Corporations, Educational Institutions, Government Agencies Technology: SaaS, PaaS, WebRTC, AI-Driven Solutions |
| Companies Covered | Cisco Webex Suite, GoTo Connect, Microsoft Teams, Five9, Dialpad, Zoom Workplace, Google Workspace, Intermedia Unite, RingCentral MVP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Software Market Emerging Trajectories
Real-time AI inference at the communication layer is transforming synchronous collaboration from passive connectivity into active workflow automation.
WebRTC with embedded large language models is digitizing meeting transcription, action-item extraction, and sentiment analysis directly within browser-based sessions. Financial services firms and healthcare providers are deploying these capabilities at scale, compressing the post-meeting workstream from hours to seconds. The technology is digitizing administrative overhead that previously required dedicated support staff.
The EU AI Act's risk-based classification system is forcing communication platform vendors to document training data provenance and algorithmic decision logic for high-risk deployments. Vendors must now maintain technical documentation and human oversight mechanisms for AI features handling sensitive conversations. European enterprise buyers are prioritizing providers with established conformity assessment procedures, shifting procurement criteria toward compliance depth.
Enterprise buyers are consolidating vendor relationships around platforms that unify messaging, voice, video, and business applications under single contracts. This pattern is displacing point-solution procurement that characterized early cloud adoption, with IT departments reducing approved vendor lists by half. The shift is most pronounced in United States mid-market enterprises seeking to simplify support overhead and security auditing.
Communication Software Market Segmentation
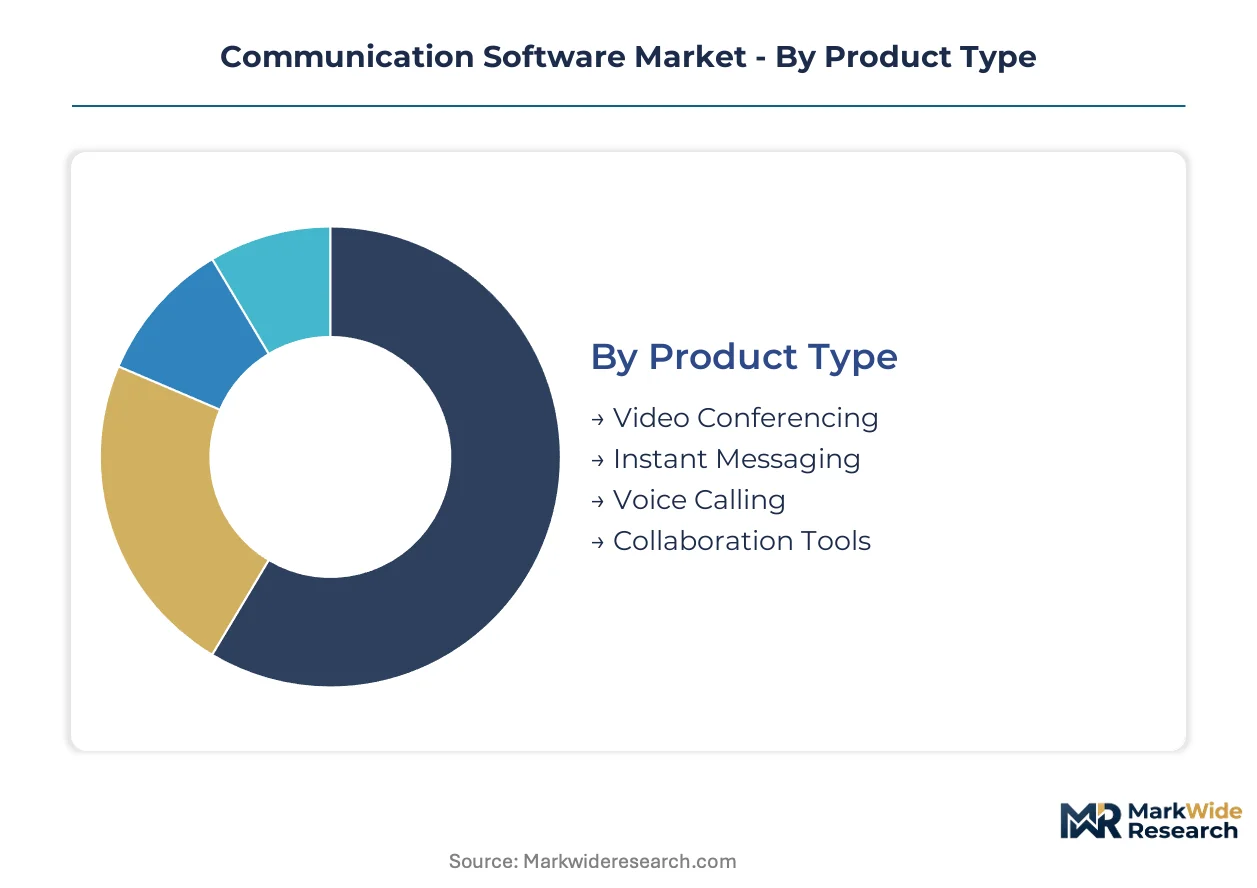
Communication software vendors architect product portfolios around four intersecting dimensions: interaction modality, infrastructure control, buyer scale, and delivery mechanism. Each segmentation axis carries distinct margin profiles, compliance obligations, and competitive dynamics that determine go-to-market economics.
Product Type:
The use-case spectrum spans asynchronous text through synchronous immersive video, with each modality commanding different latency tolerances and integration depth.
- Video Conferencing:Full-duplex audiovisual sessions using H.264/VP9 codecs with sub-150ms latency targets for synchronous collaboration. Demand concentrates in United States financial services trading floors where real-time sentiment analysis and compliance recording drive platform selection.
- Instant Messaging:Persistent chat threads with file sharing, threaded conversations, and searchable history. Healthcare providers in Germany are deploying these tools under GDPR and EU AI Act requirements for encrypted, auditable clinical communication workflows.
- Voice Calling:PSTN-replacement VoIP services with E.164 numbering and emergency calling compliance. Carrier-grade reliability requirements dominate procurement criteria for government agencies.
- Collaboration Tools:Unified workspaces combining document co-editing, task management, and calendar integration. Small enterprises favor bundled offerings that consolidate vendor relationships.
Established volume favors Voice Calling; emerging adoption favors Video Conferencing.
Deployment:
Cost tier structures separate capital-intensive ownership from operational expenditure models, with compliance mandates increasingly dictating architecture choices.
- Cloud-Based:Multi-tenant SaaS delivery with automatic updates and elastic capacity scaling. HIPAA-compliant instances for United States healthcare systems are climbing the fastest as hospital systems abandon on-premise maintenance.
- On-Premise:Customer-managed infrastructure with full data sovereignty and custom security hardening. Defense contractors and classified government facilities maintain this model despite higher total cost of ownership.
- Hybrid:Split workloads with sensitive functions on-premise and burst capacity in cloud. European enterprises facing GDPR data residency requirements are expanding hybrid footprints.
- Dedicated Server:Single-tenant cloud instances with isolated compute and storage resources. Financial services firms in Singapore and Switzerland select this tier for regulatory audit separation.
Operational simplicity favors Cloud-Based; regulatory complexity favors Dedicated Server.
End User:
Customer type determines contract value, sales cycle length, and support intensity across the buyer pyramid.
- Large Corporations:Multi-thousand seat deployments with custom integration requirements and dedicated success management. These buyers drive platform roadmap influence and reference value.
- Small Enterprises:Under-500 employee organizations purchasing standardized packages through self-service or channel partners. Japan's METI digital transformation mandates are accelerating SMB modernization here.
- Educational Institutions:K-12 districts and universities with seasonal usage patterns and accessibility compliance requirements. United States FCC E-Rate subsidies fund connectivity infrastructure upgrades.
- Government Agencies:Federal, state, and municipal entities with FedRAMP, FISMA, and country-specific security certifications. Procurement runs through formal RFP processes with 12-18 month cycles.
Contract value concentrates in Large Corporations; volume expansion concentrates in Small Enterprises.
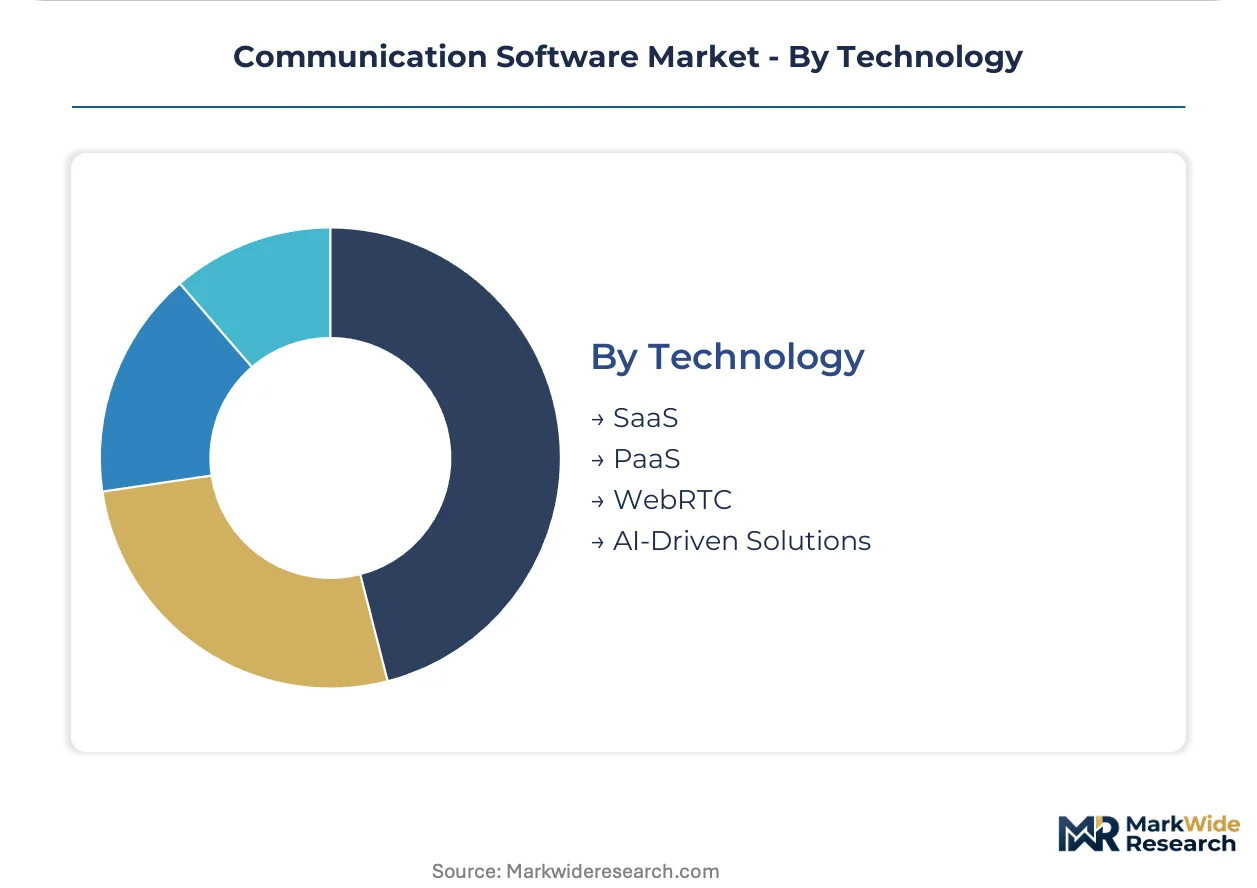
Technology:
Delivery mechanism and protocol stack differentiate vendor capabilities in scalability, customization, and intelligence embedding.
- AI-Driven Solutions:Platforms with native large language models for real-time transcription, translation, and sentiment analysis. Healthcare providers and financial services firms are deploying these capabilities at scale.
- SaaS:Browser and mobile-native applications with zero-install deployment and subscription pricing. This model captures the majority of new enterprise bookings.
- PaaS:Communication APIs and SDKs enabling developers to embed voice, video, and messaging into custom applications. Telemedicine workflow builders and customer service platforms represent primary consumption.
- WebRTC:Open-standard peer-to-peer communication protocols enabling browser-based sessions without plugins. The technology underpins real-time collaboration without proprietary client requirements.
Deployment velocity favors SaaS; capability differentiation favors AI-Driven Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in Germany deploy encrypted clinical messaging under GDPR and EU AI Act mandates, while United States enterprises prioritize FedRAMP-authorized cloud stacks for federal contracting. This divergence creates distinct procurement criteria across Atlantic markets.
United States
Federal modernization mandates and E-Rate subsidies for educational connectivity drive platform adoption. FCC net neutrality rulings shape bandwidth economics for cloud-native deployments. Silicon Valley clusters anchor AI-driven feature development for financial services trading floors.
Germany
Hospital systems demand sovereign data residency for telemedicine workflows under GDPR Article 44 transfer restrictions. BSI IT-Grundschutz certification requirements filter vendor eligibility for public sector procurement. Berlin-Brandenburg hosts specialized engineering talent for WebRTC protocol development.
Japan
METI digital transformation mandates accelerate SMB migration from legacy PBX hardware to bundled SaaS offerings. Personal Information Protection Commission guidelines constrain cross-border data flows for multinational deployments. Osaka-Kansai clusters concentrate channel partner networks for mid-market distribution.
India
PLI scheme incentives for electronics manufacturing attract data center localization investments from communication software vendors. TRAI net neutrality regulations preserve open access for browser-based WebRTC sessions. Bengaluru and Hyderabad anchor developer ecosystems for real-time collaboration API integration.
United Kingdom
Financial services firms in the City of London deploy dedicated server instances for regulatory audit separation under FCA guidelines. NHS digital transformation programs certify cloud platforms for patient communication workflows. Cambridge-Oxford corridor supplies machine learning talent for sentiment analysis feature development.
Communication Software Market Vendor Landscape
Capability concentration sits with specialized video infrastructure vendors; scale advantage sits with platform ecosystems anchored to productivity suites. The vendor base stratifies across three tiers: integrated collaboration stacks, carrier-grade voice specialists, and API-first communication platforms. Dominant competitive moves include portfolio diversification into adjacent workflow automation and strategic partnerships with systems integrators for hybrid deployment support.
Within the integrated collaboration tier, Microsoft Teams and Zoom Workplace exemplify divergent scale strategies—one leveraging existing productivity suite penetration, the other building specialized infrastructure for synchronous video. RingCentral MVP occupies a position bridging carrier-grade voice reliability with cloud-native delivery models. Google Workspace and Cisco Webex Suite represent alternative ecosystem plays, each anchoring different buyer segments through bundled application integration.
| Leading Market Players |
|---|
| Cisco Webex Suite |
| GoTo Connect |
| Microsoft Teams |
| Five9 |
| Dialpad |
| Zoom Workplace |
| Google Workspace |
| Intermedia Unite |
| RingCentral MVP |
| Others |
Supply Flow & Price Mechanics
Overcapacity in cloud data center regions including Northern Virginia and Frankfurt is compressing infrastructure costs for communication software vendors while simultaneously intensifying price competition for enterprise contracts, reshaping how suppliers calibrate margin targets against volume commitments.
Pricing Analysis
Long-term enterprise offtake agreements dominate contract structures for large corporations, with annual or multi-year SaaS subscriptions anchoring vendor revenue predictability. Pricing stratifies across premium, standard, and economy tiers based on AI feature depth and compliance certification grade—FedRAMP-authorized instances command substantial premiums over baseline cloud offerings. Cost compression in the mid-market tier is intensifying because channel partners are consolidating around fewer platforms, squeezing reseller margins. Small enterprises exhibit the highest price sensitivity, while government agencies prioritize certification depth over unit cost.
Supply Chain Analysis
Upstream feedstock for communication software centers on semiconductor fabrication capacity concentrated in Taiwan, South Korea, and the United States, with advanced node production for AI inference chips drawing from TSMC and Samsung foundries. Critical component dependencies include high-bandwidth memory modules, specialized video encoding ASICs, and optical transceivers for data center interconnect. Single-source vulnerability around TSMC's leading-edge nodes represents the dominant structural risk for platform scalability. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and regional systems integrators for hybrid deployment support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Communication software markets are entering a cyclical recovery phase driven by federal modernization mandates and healthcare digitization programs, creating favorable conditions for strategic repositioning across vendor tiers.
For Market Incumbents: Build switching-cost moats through deep integration into electronic health record systems and productivity suite workflows. Defensive consolidation should prioritize acquiring WebRTC engineering teams to address specialized talent scarcity, while expanding FedRAMP authorization scope to capture defense contractor demand. Channel control over carrier-grade voice interconnection agreements remains a critical lever against API-first challengers. For New Entrants and Emerging Players: Mid-market healthcare providers in Germany and Japan represent the most penetrable entry point, as GDPR Article 44 compliance requirements and METI modernization mandates create procurement friction for incumbent platforms. Targeting telemedicine workflow builders with embedded PaaS communication APIs offers lower customer acquisition costs than competing head-on in saturated unified communications segments. A vertical-specific go-to-market angle—certified HIPAA or BSI IT-Grundschutz instances—accelerates trust formation with risk-averse buyers. For Investors and Strategic Acquirers: Capital is best deployed toward AI-native communication platforms with established conformity assessment procedures for EU AI Act compliance, positioning for long-term viability as algorithmic transparency mandates proliferate. Acquisition targets should demonstrate proven edge AI deployment capabilities for real-time transcription and sentiment analysis. The signal to watch is sovereign cloud mandate expansion—jurisdictions requiring data residency will favor vendors with localized infrastructure over global platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Microsoft 365 embedding anchors enterprise workflow stickiness against point-solution competitors. |
| Strategic Partnership | Systems integrator alliances accelerate hybrid deployment support for European GDPR-compliant implementations. |
| Acquisition of Specialist Firm | WebRTC protocol engineering teams address critical talent scarcity constraining implementation timelines. |
| Geographic Expansion | India PLI-scheme data center localization captures sovereign hosting demand from domestic enterprises. |
| Product Launch | Edge AI inference capabilities unlock financial services trading floor and emergency response use cases. |
Methodological Framework
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration for demand assumptions and pricing dynamics. Primary interview findings were cross-validated against secondary sources including SEC filings, hyperscaler capex disclosures, and FCC E-Rate program data. Bottom-up segment sizing and top-down macroeconomic triangulation were applied to ensure internal consistency across the analysis window.
Scenario-bracketing around regulatory implementation timelines and AI adoption curves framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional compliance pattern. CAGRs were derived from fitted growth curves incorporating enterprise cloud migration velocity and sovereign data residency mandate proliferation as industry-specific forecast inputs.
Practitioners should monitor FCC net neutrality rulings, EU AI Act enforcement patterns, and WebRTC engineering wage inflation for early signals requiring forecast revision. Cross-checking against hyperscaler earnings call commentary on enterprise communication attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recipe Apps Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
France HR Payroll Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Aviation Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Runtime Software Market
Software & Services
Global Customer Success Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global Online Expense Management Software Market