
 Advanced Mobile UX Design Services Market | 2026-2036
Advanced Mobile UX Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Mobile UX Design Services Market Outlook
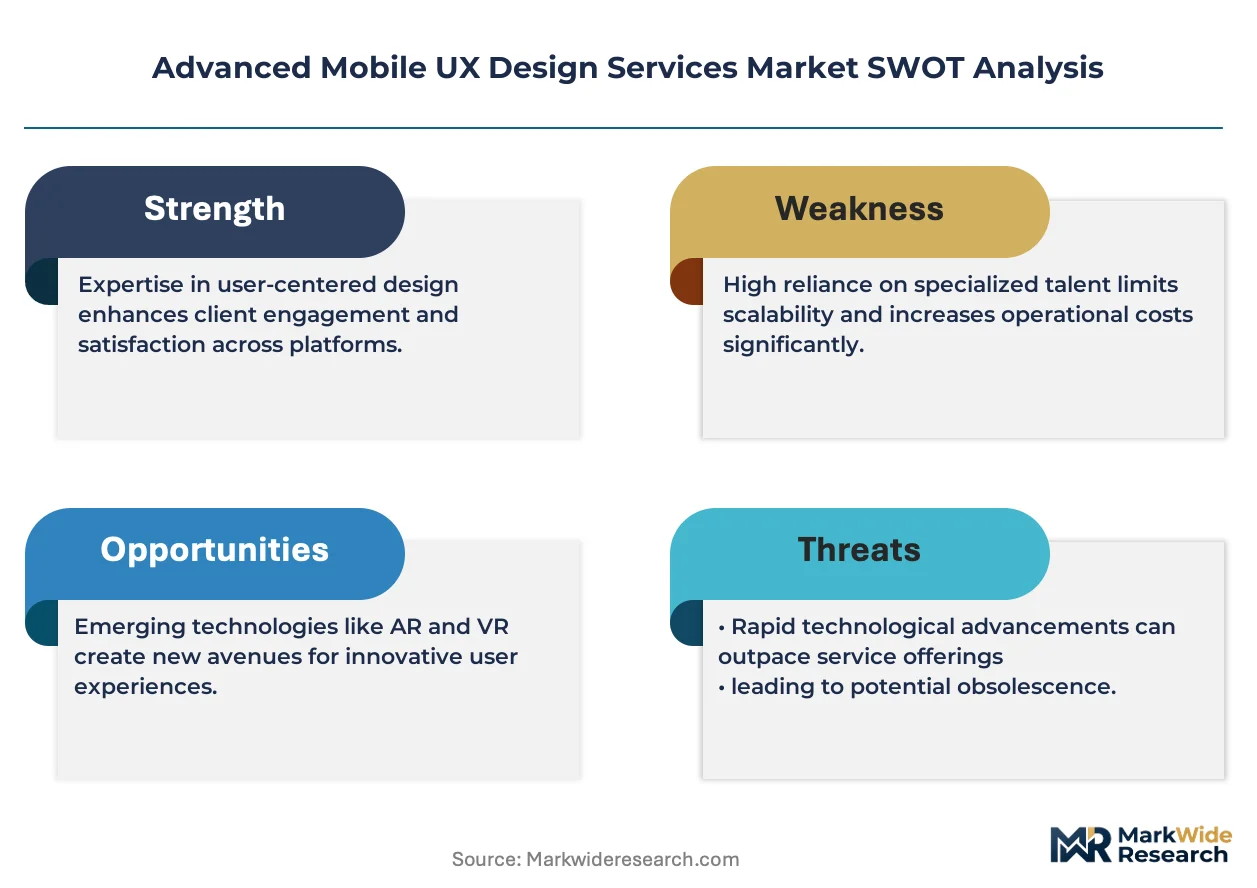
WCAG 2.2 accessibility compliance is unwinding the competitive landscape for mobile UX design services, forcing studios to rebuild certification pipelines around cognitive disability support and motion-sensitivity protocols. IDEO leverages its human-centered design heritage to anchor premium engagements with Fortune 500 clients seeking inclusive interface architectures. Frog Design Inc. competes through deep specialization in hardware-software interaction systems for wearable and IoT-adjacent mobile experiences. Accenture sustains scale advantages by embedding UX teams directly inside enterprise transformation contracts across banking and logistics verticals.
Advanced mobile UX design services encompass the research, architecture, prototyping, and validation workflows that shape how users navigate touchscreen-native software on smartphones and tablets, incorporating technical parameters such as touch-target sizing, haptic feedback latency thresholds, and gesture-recognition accuracy rates to minimize cognitive load and task-completion friction. The primary commercial purpose is to reduce abandonment rates and increase lifetime value in high-frequency consumer applications. Service type segmentation shows user research and usability testing commanding margin premiums as enterprises face post-pandemic pressure to justify every design decision with behavioral evidence. Platform segmentation reveals cross-platform frameworks displacing native iOS and Android builds in mid-market engagements, though Apple and Google design-language fluency still differentiates top-tier studios in regulated industries.
WCAG guidelines from the W3C, Section 508 requirements enforced by federal agencies in the United States, and the European Accessibility Act reshape demand by mandating perceptible, operable, and understandable interfaces for public-facing mobile services. ETSI standards in Europe and FCC guidance on emergency-alert accessibility further constrain design choices for cross-border application deployments. Stakeholders must monitor how generative AI tools for automated interface generation interact with emerging liability frameworks for algorithmic discrimination in digital service delivery.
Market Dynamics
WCAG 2.2 accessibility mandates are compressing design timelines while expanding certification requirements, forcing studios to restructure workflows around cognitive disability protocols and motion-sensitivity testing that previously sat outside standard engagement scopes.
Growth Catalysts
- Biometric authentication flows:Fintech and health-tech verticals are rebuilding consumer-facing applications around fingerprint, facial, and voice recognition interfaces that reduce friction and abandonment rates in high-frequency transactions.
- Section 508 requirements:Federal agencies in the United States mandate perceptible, operable, and understandable interfaces for public-facing mobile services, creating guaranteed demand streams for certified accessibility specialists.
- Predictive interaction models:AI-powered personalization engines anticipate user intent before explicit input, reducing task-completion steps and driving enterprise investment in advanced UX research capabilities.
Market Restraints
- Specialized talent scarcity:Cognitive accessibility expertise and motion-physiology knowledge concentrate in a handful of metropolitan design clusters, inflating labor costs and extending project timelines.
- Cross-platform framework limitations:Mid-market engagements relying on React Native and Flutter face performance ceilings in regulated industries requiring native iOS and Android builds with hardware-optimized haptic feedback.
- European Accessibility Act compliance costs:Cross-border application deployments must satisfy divergent national implementations of perceptibility and operability standards, multiplying validation overhead.
Strategic Opportunities
- Wearable and IoT-adjacent experiences:Hardware-software interaction design for smartwatches, hearables, and ambient computing devices represents an underdeveloped service category with limited specialist competition.
- Generative AI interface generation:Automated prototyping tools converging with human-centered validation workflows could compress research-to-production cycles while maintaining behavioral evidence standards.
- India's digital public infrastructure:The country's stack of identity, payment, and health interfaces creates demand for localization expertise and inclusive design adaptation at scale.
Industry Challenges
- WCAG 2.2 cognitive disability certification:Studios must rebuild training pipelines and testing protocols around support for users with memory, attention, and executive function variations, extending qualification periods.
- Algorithmic discrimination liability:Emerging legal frameworks for AI-driven personalization create exposure when predictive models inadvertently exclude users with atypical interaction patterns or assistive technology dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Mobile UX Design Services Market |
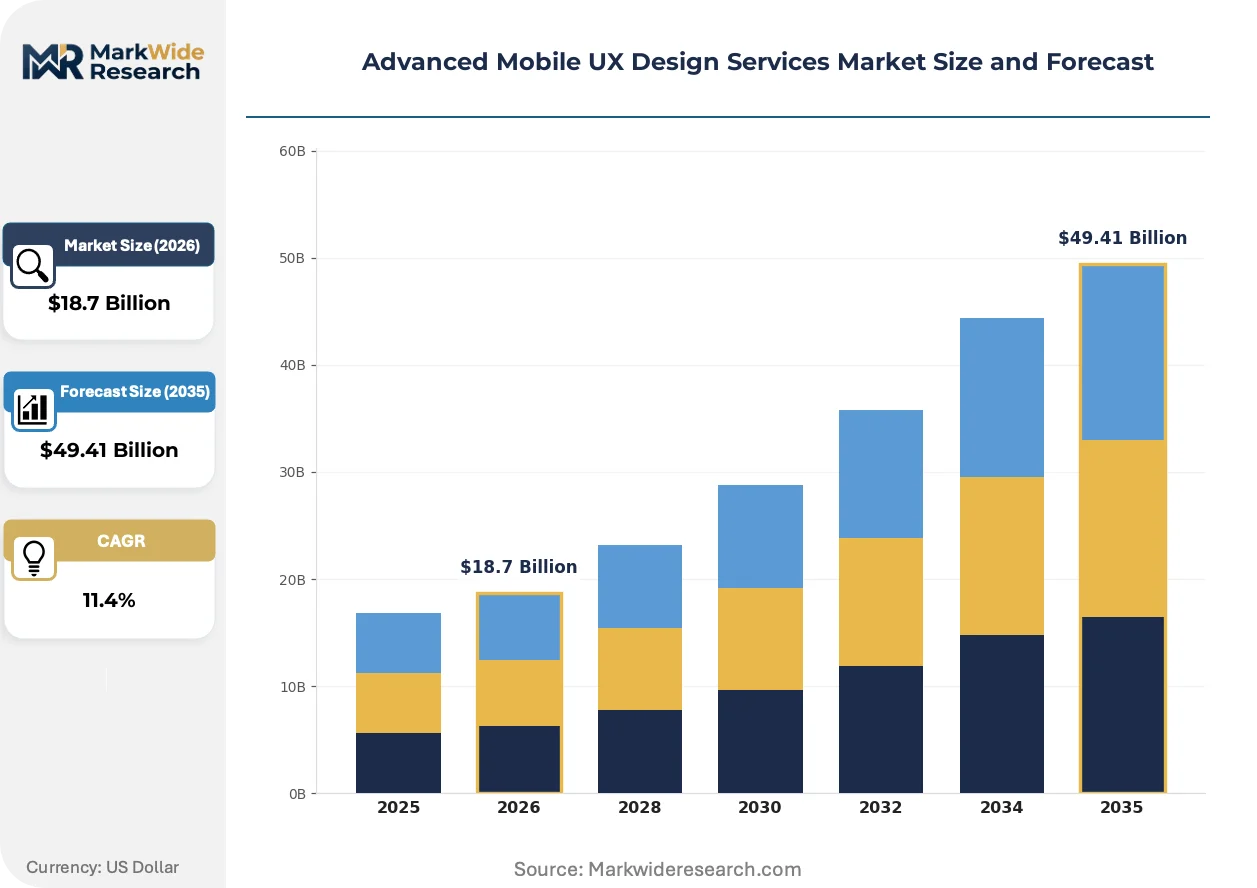
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: UI Design, User Research, Prototyping, Usability Testing End User: Startups, Enterprises, Agencies, Freelancers Design Approach: User-Centric, Agile, Iterative, A/B Testing Platform: iOS, Android, Cross-Platform, Web |
| Companies Covered | IDEO, Mindtree IT Solutions, DXC Technology, Accenture, IBM Corporation, Google LLC, Zensar Technologies, SoftServe Inc., Frog Design Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Mobile UX Design Services Market Strategic Shifts
Touch-native interaction paradigms are fragmenting as input modalities multiply beyond the smartphone screen, forcing design services to expand competency boundaries into spatial computing and ambient intelligence contexts.
Generative AI prototyping tools are decomposing traditional research-to-wireframe workflows by producing interface variations from natural language prompts. Enterprise UX teams at financial institutions and healthcare providers are piloting these systems for rapid concept validation. The technology is compressing early-stage design cycles while raising new questions about liability for algorithmically generated accessibility failures.
The European Accessibility Act is mandating perceptible, operable, and understandable interfaces across member states by mid-decade. Mobile application publishers serving public sector or essential service contracts must demonstrate conformance through third-party audit trails. Banking and transportation verticals in Germany, France, and the Netherlands are accelerating procurement of certified accessibility expertise to preempt enforcement actions.
Outcome-based service contracts are displacing time-and-materials billing in enterprise engagements. Procurement functions at Fortune 500 technology and retail buyers now tie vendor compensation to measured improvements in task-completion rates and accessibility audit scores. This shift is most visible in United States federal contractor supply chains and European multinational banking procurement frameworks.
Advanced Mobile UX Design Services Market Segmentation
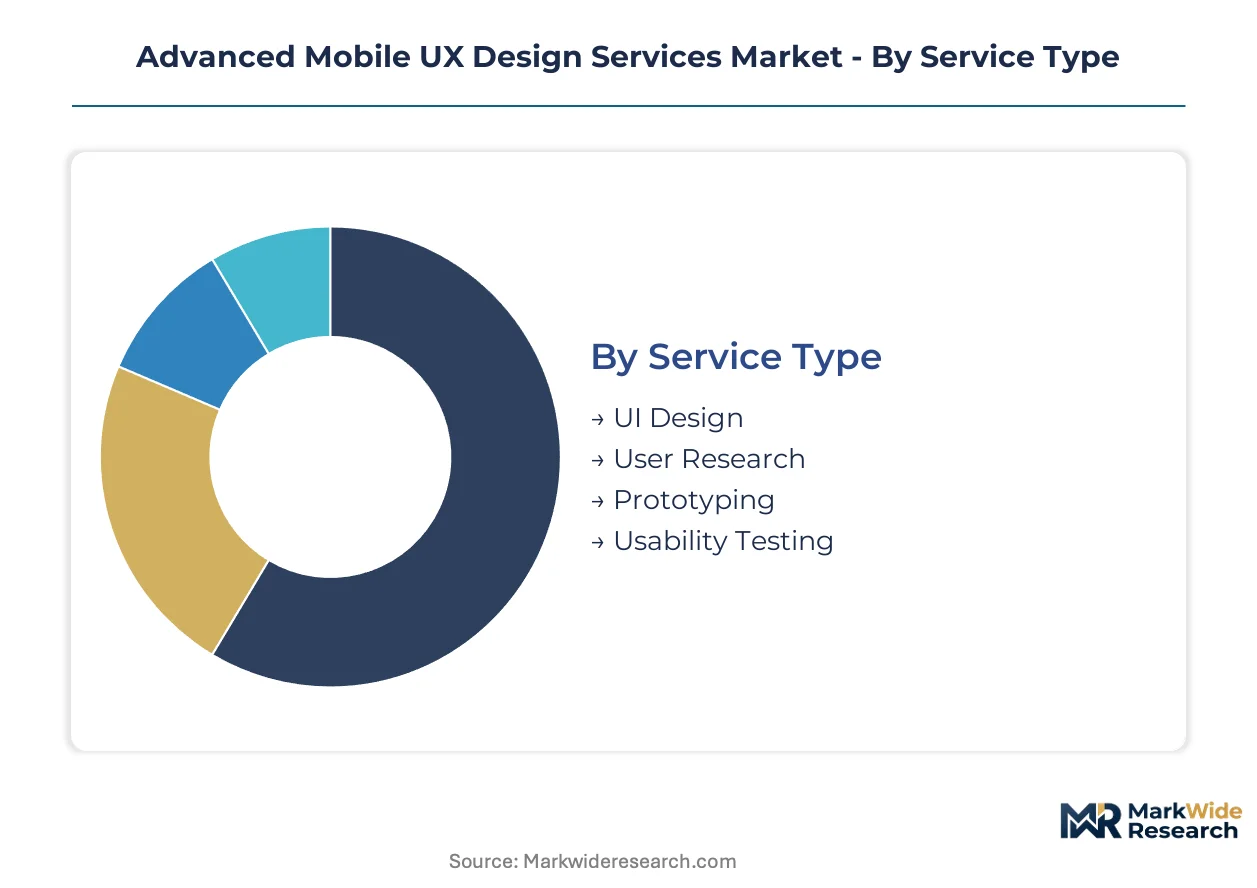
Service providers structure engagements around distinct capability bundles and client maturity levels, with margin concentration shifting toward research-intensive phases as enterprises demand behavioral evidence for design decisions. Platform specialization and regulatory compliance requirements further fragment competitive positioning across the value chain.
Service Type:
Margin pools concentrate in upstream research and validation phases where specialized expertise creates pricing power against commoditized production work.
- User Research:Ethnographic studies, diary studies, and behavioral analytics that establish foundational user mental models before interface construction begins. Fintech and health-tech verticals in the United States are expanding procurement of cognitive walkthroughs and biometric stress-testing to support WCAG 2.2 certification requirements.
- Usability Testing:Moderated and unmoderated evaluation protocols measuring task-completion rates, error recovery paths, and accessibility conformance against motion-sensitivity thresholds. Federal contractor supply chains mandate third-party audit trails, creating guaranteed demand streams for certified specialists.
- UI Design:Visual system architecture encompassing typography, color, and component libraries for touchscreen-native interfaces.
- Prototyping:Interactive simulation workflows spanning low-fidelity wireframes through high-fidelity motion studies.
The dominant share belongs to UI Design, while User Research is closing the gap fastest.
End User:
Client sophistication determines engagement scope, with procurement patterns diverging between compliance-driven enterprise contracts and velocity-focused startup engagements.
- Enterprises:Multi-phase transformation programs embedding UX teams inside banking, logistics, and healthcare modernization initiatives. United States federal agencies and European multinational banks are accelerating outcome-based contracts tied to accessibility audit scores and task-completion metrics.
- Startups:Compressed sprint cycles prioritizing rapid concept validation and investor-ready prototypes over exhaustive research protocols.
- Agencies:White-label service provision to brands lacking in-house design capabilities, common in mid-market retail and hospitality verticals.
- Freelancers:Individual practitioners serving local small-business clients with limited procurement sophistication.
Enterprises command the largest contract values, though Startups are expanding their aggregate spend most steeply.
Design Approach:
Methodology selection reflects organizational culture and regulatory pressure, with iterative frameworks displacing waterfall planning in regulated industries.
- User-Centric:Human-centered design frameworks emphasizing deep empathy research and inclusive co-creation with disability communities. Studios rebuilding certification pipelines around WCAG 2.2 cognitive disability protocols anchor premium positioning through this approach.
- Agile:Sprint-based delivery integrating design, development, and stakeholder feedback in two-week cycles.
- Iterative:Continuous refinement driven by behavioral analytics and longitudinal usability monitoring.
- A/B Testing:Controlled experimentation validating design hypotheses against conversion and engagement metrics.
User-Centric approaches capture the highest hourly rates, while Iterative methodologies are gaining adoption fastest among regulated verticals.
Platform:
Technical architecture choices determine specialist staffing requirements and compliance validation scope across deployment targets.
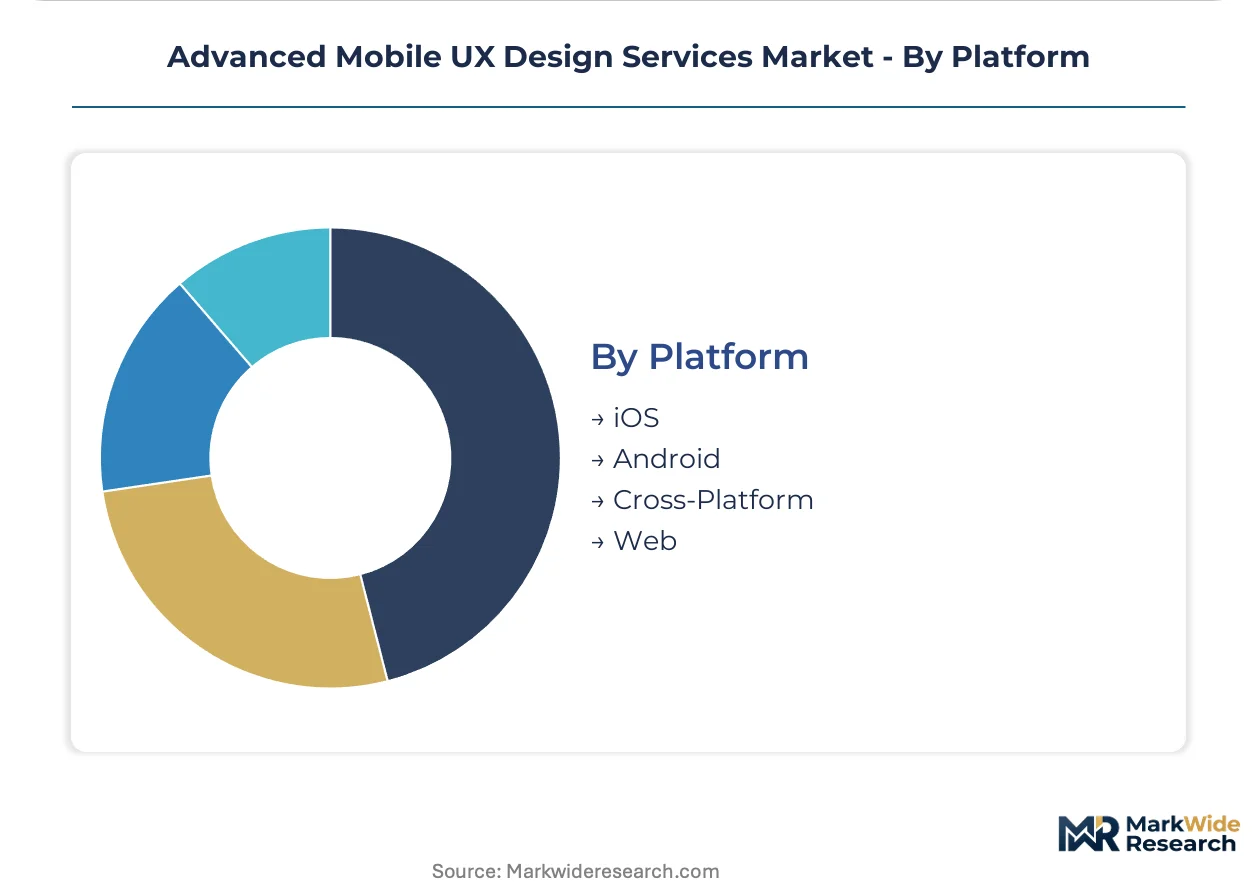
- Cross-Platform:React Native and Flutter frameworks enabling single-codebase deployment across iOS and Android ecosystems. Mid-market engagements favor this approach for cost efficiency, though performance limitations in haptic feedback latency constrain adoption in regulated industries requiring hardware optimization.
- iOS:Native builds leveraging Apple Human Interface Guidelines and proprietary gesture-recognition frameworks.
- Android:Native development following Material Design specifications and Google accessibility tooling.
- Web:Progressive web applications and responsive mobile web experiences bridging native and browser-based interaction paradigms.
Cross-Platform development holds the largest volume share, while iOS specialization commands the steepest rate premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal accessibility mandates and digital infrastructure investments are redrawing procurement patterns across major economies. National regulators now enforce perceptibility standards that determine vendor eligibility for public contracts.
United States
Fintech and health-tech verticals drive enterprise demand for biometric authentication flows and predictive interaction models. Section 508 requirements enforced by federal agencies mandate third-party accessibility audit trails for public-facing mobile services. Design talent clusters concentrate in San Francisco and New York, where studios rebuild certification pipelines around WCAG 2.2 cognitive disability protocols.
Germany
Banking and transportation verticals accelerate procurement of certified accessibility expertise to preempt European Accessibility Act enforcement actions. The country's national digital regulator enforces conformance through third-party validation frameworks. Frankfurt and Berlin host specialist studios serving multinational procurement frameworks with outcome-based contracts.
United Kingdom
Financial institutions pilot generative AI prototyping tools for rapid concept validation while maintaining behavioral evidence standards. The Information Commissioner's Office intersects with accessibility mandates through algorithmic discrimination liability frameworks. London anchors premium engagements with Fortune 500 clients seeking inclusive interface architectures.
India
The country's digital public infrastructure stack of identity, payment, and health interfaces creates demand for localization expertise and inclusive design adaptation at scale. The central bank's payment system regulations shape authentication flow requirements. Bangalore and Hyderabad concentrate cross-platform development specialists serving mid-market engagements.
Japan
Hardware-software interaction design for wearable and ambient computing devices represents an underdeveloped service category with limited specialist competition. METI standards govern haptic feedback latency thresholds in consumer electronics integration. Tokyo and Osaka studios specialize in native iOS builds with hardware-optimized gesture-recognition frameworks.
Advanced Mobile UX Design Services Market Competitive Environment
Listed leaders compete with private specialists across certification depth and platform specialization. The vendor base stratifies into three tiers: global consultancies embedding UX teams inside enterprise transformation contracts, boutique studios commanding premium rates through human-centered design heritage, and mid-market shops leveraging cross-platform frameworks for cost efficiency. Strategic archetypes include accessibility certification specialists, hardware-software interaction designers, and AI-powered personalization engine integrators. Dominant competitive moves involve outcome-based contract structuring and geographic expansion into India's digital public infrastructure market.
Within the human-centered design tier, IDEO and Frog Design Inc. exemplify studios anchoring premium positioning through inclusive co-creation methodologies. Accenture occupies the scale-driven archetype, embedding UX capabilities directly inside banking and logistics modernization programs. These three entities represent distinct competitive vectors: heritage-led certification depth, hardware-software integration specialization, and enterprise transformation contract scale.
| Leading Market Players |
|---|
| IDEO |
| Mindtree IT Solutions |
| DXC Technology |
| Accenture |
| IBM Corporation |
| Google LLC |
| Zensar Technologies |
| SoftServe Inc. |
| Frog Design Inc. |
| Others |
Value Chain & Pricing Dynamics
Scale economies in cognitive accessibility certification pipelines anchor price floors for boutique studios in San Francisco and New York, while Accenture's embedded UX teams inside enterprise banking contracts leverage volume throughput to compress unit economics. WCAG 2.2 compliance mandates widen the spread between certified specialists and commodity cross-platform developers, concentrating margin pools in research-intensive validation phases.
Pricing Analysis
Certification level creates the primary spread between premium human-centered design studios and mid-market cross-platform shops. Three-tier pricing structure across premium, standard, and economy levels reflects WCAG 2.2 cognitive disability protocol depth, native iOS/Android hardware optimization, and outcome-based contract performance guarantees. Cost compression in mid-market React Native engagements intensifies as Indian development centers expand cross-platform capacity. Federal contractors and European multinational banks exhibit lowest price sensitivity, while retail and hospitality agencies face acute procurement pressure.
Supply Chain Analysis
Talent pipeline chokepoints in cognitive accessibility expertise and motion-physiology knowledge concentrate qualified labor in the United States, Germany, and India. Service delivery draws from ethnographic research specialists, biometric testing hardware vendors, and third-party audit certification bodies. Single-source vulnerability runs through WCAG 2.2 accreditation bodies, where limited certifiers create bottleneck risk for studio qualification timelines. Distribution runs through direct enterprise sales teams, design system platform partnerships, and federal contractor procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of practitioners certified in WCAG 2.2 cognitive disability protocols concentrates pricing power among a handful of heritage studios, forcing buyers into extended qualification queues or compromised compliance postures.
For Market Incumbents: Shield certification depth as a moat by accelerating in-house training pipeline investment before regulatory enforcement widens the talent gap. Accenture's embedded model demonstrates how vertical integration into enterprise transformation contracts locks out boutique competitors from banking and logistics verticals. Counter the threat of generative AI prototyping tools by anchoring premium positioning in behavioral evidence standards that automated systems cannot replicate. For New Entrants and Emerging Players: Wearable and IoT-adjacent hardware-software interaction design represents an underdeveloped service layer where incumbents under-serve. Japan's METI-governed haptic feedback requirements and ambient computing device proliferation create a penetrable niche with limited specialist competition. Target outcome-based contracts with mid-market health-tech startups seeking native iOS builds, leveraging India's digital public infrastructure scale for cost-efficient delivery. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among studios with embedded enterprise transformation contracts and federal contractor supply chain accreditation. Long-term viability hinges on certification pipeline depth rather than generative AI tooling adoption. Monitor European Accessibility Act enforcement actions as the inflection signal for accessibility specialist valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| WCAG 2.2 Certification Pipeline Investment | Regulatory enforcement by the European Accessibility Act and Section 508 mandates creates guaranteed demand capture. |
| Embedded Enterprise Transformation Contract | Accenture's banking and logistics vertical integration locks out boutique competitors from multi-year engagements. |
| Wearable Hardware-Software Interaction Specialization | Japan's METI standards and limited specialist competition open margin-rich service categories. |
| Outcome-Based Contract Structuring | Federal contractors and European banks now tie vendor compensation to task-completion metrics and audit scores. |
| Generative AI Prototyping Integration | Financial institutions pilot automated interface generation while maintaining human-centered validation workflows. |
Study Parameters
Desk research of regulatory filings, design system documentation, and federal procurement databases preceded structured interviews with UX research directors, accessibility certification auditors, enterprise IT procurement officers, and fintech product leads. Primary fieldwork across San Francisco, New York, London, Frankfurt, and Bangalore validated service pricing benchmarks and talent pipeline constraints. Secondary sources included WCAG 2.2 technical specifications, Section 508 compliance reports, European Accessibility Act implementation guidance, and SEC disclosures from listed design consultancies. Bottom-up project pipeline analysis triangulated against top-down enterprise IT spending estimates.
Variance decomposition across service type, platform specialization, and end-user maturity segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed user research intensity, native versus cross-platform technical architecture, and regulatory compliance tier. CAGRs derived from longitudinal contract value analysis and staffing cost inflation trajectories. Forecast inputs incorporated biometric authentication flow proliferation rates and generative AI tooling adoption curves in financial services.
Forecasts assume regulatory continuity in United States Section 508 enforcement and European Accessibility Act implementation timelines; material policy shifts in cognitive disability protocol stringency would require re-modeling. Scenario boundaries exclude black-swan disruptions in AI liability frameworks or hardware-software integration standards. Practitioners should keep alternative scenarios live as algorithmic discrimination litigation precedents and WCAG 3.0 draft specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Project Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Identity Resolution Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Self-Service BI Market
Software & Services
North America Automotive Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Global Campaign Management Software Market
Software & Services
Live Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Global Address Verification Software Market
Software & Services
Global ITSM Software Market