
 Aluminium-Free Deodorants Market | 2026-2036
Aluminium-Free Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium-Free Deodorants Market Outlook
Asset-light contract manufacturing and private-label financing is narrowing the capital barrier for challenger brands entering the aluminium-free deodorants space. Unilever PLC leverages its global supply chain infrastructure to sustain volume leadership across multiple distribution formats. Beiersdorf AG anchors its position through specialized R&D in skin-compatible formulations. Native differentiates via direct-to-consumer channel control and subscription-based revenue models.
Aluminium-free deodorants are personal care formulations that omit aluminium salts as active antiperspirant agents, relying instead on botanical extracts, mineral compounds, or enzymatic mechanisms to manage odor. These products typically incorporate baking soda, arrowroot powder, or zinc ricinoleate as functional alternatives, serving consumers seeking reduced chemical exposure or addressing skin sensitivity concerns. The stick format dominates shelf presence in mass retail due to convenience and portability, while the natural formulation segment captures premium margin pools as consumers prioritize ingredient transparency. Online distribution channels represent the fastest-growing access point, though health stores retain concentrated loyalty among ingredient-conscious buyers.
The US FDA regulates cosmetic labeling claims and safety substantiation for deodorant products, while the EU REACH framework restricts specific aluminium compound classifications and mandates ingredient disclosure protocols. Germany's BfR provides additional safety assessments that influence formulation standards across European markets. Stakeholders must monitor evolving state-level ingredient disclosure laws in the US and potential expansion of EU microplastic restrictions that could affect synthetic fragrance carriers.
Market Dynamics
Reformulation mandates under EU REACH are forcing manufacturers to replace aluminium salts with botanical and mineral alternatives, compressing R&D timelines while elevating ingredient transparency requirements across supply chains.
Growth Catalysts
- REACH Restriction Protocols:The EU's classification of certain aluminium compounds as substances of very high concern is compelling incumbent brands to accelerate aluminium-free line extensions.
- Arrowroot Powder Adoption:This starch-based moisture absorber is displacing synthetic alternatives in natural formulations due to superior skin compatibility and clean-label positioning.
- Millennial Purchasing Concentration:Urban consumer clusters in Germany, the United Kingdom, and the United States are driving repeat purchase rates through subscription commerce platforms.
Market Restraints
- Shea Butter Price Volatility:West African supply disruptions are creating input cost instability for emollient-heavy natural deodorant formulations.
- Antiperspirant Efficacy Gap:Aluminium-free alternatives cannot legally claim sweat reduction, limiting clinical positioning against conventional antiperspirants regulated by the US FDA.
- Certification Timeline Friction:COSMOS and NATRUE organic certification processes extend product launch cycles by 8-14 months for challenger brands.
Strategic Opportunities
- Men's Grooming Penetration:Underdeveloped aluminium-free adoption among male consumers in France and Spain offers whitespace for gender-specific formulation marketing.
- Enzymatic Biotechnology Convergence:Combining lactobacillus ferment filtrates with prebiotic skin microbiome support is opening clinical-grade positioning channels.
- Pharmacy Retail Expansion:Boots and dm-drogerie markt are expanding dedicated natural personal care shelf space, creating new premium access points.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Cosmetic chemists with dual competency in natural ingredient stability and microbiome science command premium compensation, constraining talent acquisition.
- Preservative System Validation:Replacing parabens with alternative preservation in water-based sticks requires extended challenge testing protocols that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium-Free Deodorants Market |
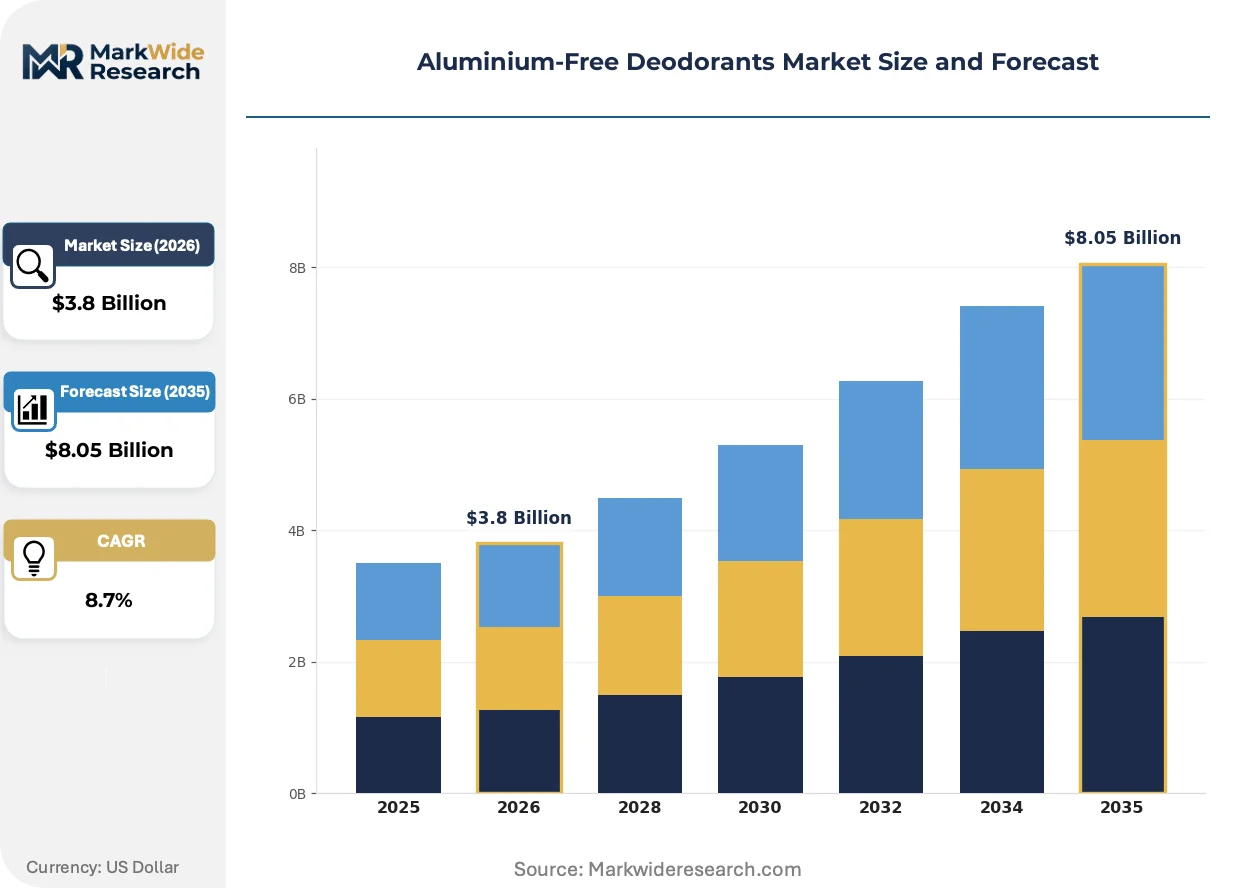
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On, Stick, Spray, Cream Formulation: Natural, Organic, Synthetic, Herbal Distribution Channel: Online, Supermarkets, Health Stores, Specialty Retail Customer Type: Men, Women, Unisex, Teens |
| Companies Covered | Unilever PLC, Procter and Gamble Co., Colgate-Palmolive Co., L'Oreal SA, Beiersdorf AG, Native, Schmidt's, Weleda, Lume, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium-Free Deodorants Market Strategic Shifts
Ingredient biotechnology and microbiome science are converging to redefine efficacy claims, while regulatory disclosure mandates and direct-to-consumer channel maturation are compressing traditional brand-building timelines.
Zinc ricinoleate derived from castor oil is hybridizing with prebiotic inulin in next-generation odor-neutralization systems. Premium skincare enthusiasts in Scandinavian markets are adopting these hybrid formats at accelerated trial rates. The convergence is compressing differentiation cycles between masstige and clinical-positioned entrants.
REACH Article 33 disclosure obligations are mandating supply chain transparency down to 0.1% weight-by-weight concentration thresholds for substances of very high concern. German manufacturers are restructuring supplier qualification protocols to maintain BfR compliance documentation. Smaller contract manufacturers without dedicated regulatory affairs functions are exiting the private-label supply base.
Ingredient-conscious buyers are unbundling deodorant from bundled personal care routines, creating standalone premium purchase occasions. Health food retailers in the Netherlands and Austria are capturing this fragmentation through curated clean-beauty assortments. The shift is most pronounced among consumers with diagnosed skin sensitivity conditions seeking dermatologist-aligned alternatives.
Aluminium-Free Deodorants Market Segmentation
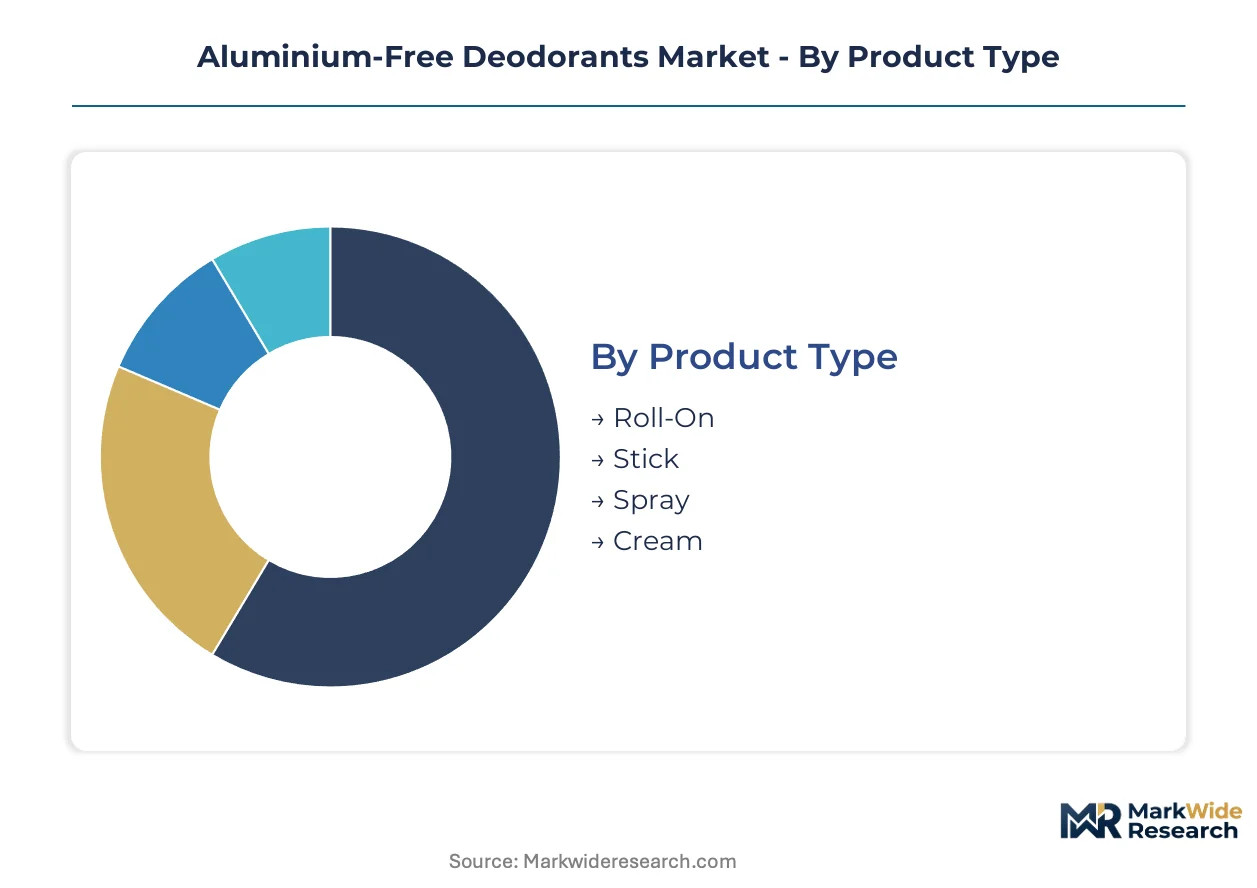
Segmentation in the aluminium-free deodorants market reveals distinct performance profiles across format preferences and ingredient philosophies. Manufacturers must align R&D investment and channel strategy with the specific technical requirements and margin structures of each segment cluster.
Product Type:
Mature formats coexist with emerging alternatives as consumer portability needs evolve against sustainability pressures.
- Roll-On:Liquid-based formulations with ball applicator mechanisms deliver precise dosage control and quick-dry characteristics. Demand concentrates in Germany and the United Kingdom among consumers transitioning from conventional antiperspirants, driven by familiarity with liquid formats and pharmacy retail availability.
- Stick:Solid wax-based compositions using candelilla or carnauba wax as structural agents dominate mass retail shelf presence. The format retains volume leadership across US and German supermarkets due to travel convenience and extended product lifespan, though packaging waste concerns are accelerating biodegradable tube adoption.
- Spray:Aerosol and pump-dispensed dry formulations utilize compressed air or hydrocarbon propellants for even application coverage. Compressed air systems are gaining traction in Scandinavian markets where volatile organic compound restrictions are tightening.
- Cream:Jar-packaged emollient-rich formulations requiring finger application serve intensive moisturization needs. The segment attracts consumers with eczema or dermatitis diagnoses seeking barrier repair alongside odor management.
Stick retains volume leadership; spray holds the steepest expansion curve.
Formulation:
Cost tier stratification separates premium-positioned ingredient stories from mass-market functional equivalents.
- Natural:Formulations incorporating baking soda, arrowroot powder, or mineral salts without synthetic fragrance carriers. Arrowroot powder adoption is displacing cornstarch in German and Dutch formulations due to superior moisture absorption and non-GMO positioning.
- Organic:COSMOS or NATRUE-certified compositions mandating minimum organic content thresholds and restricted synthetic preservative use. Certification timelines extend launch cycles, constraining challenger brand velocity in premium channels.
- Synthetic:Conventional chemical architectures omitting aluminium salts while retaining synthetic fragrance compounds and preservative systems. Price positioning undercuts natural alternatives by 30-40% in mass retail, capturing cost-conscious switchers.
- Herbal:Botanical extract-focused formulations emphasizing traditional medicine lineages such as Ayurvedic or Traditional Chinese Medicine ingredient sourcing. Ayurvedic-positioned products are expanding fastest in UK specialty retail among South Asian diaspora consumers.
Natural formulations command the widest distribution footprint; organic is climbing the fastest.
Distribution Channel:
Customer type fragmentation is reshaping where purchase decisions occur and how loyalty is constructed.
- Online:Direct-to-consumer platforms and marketplace listings enabling subscription commerce and ingredient transparency tools. Subscription models in the United States are driving repeat purchase rates above 60% for established challenger brands.
- Supermarkets:Mass retail placement requiring slotting fee investments and standardized packaging formats for shelf efficiency. German dm-drogerie markt and Rewe are expanding dedicated natural personal care sections, creating new premium access points.
- Health Stores:Curated assortments in Holland & Barrett, Whole Foods, and independent organic retailers serving ingredient-conscious buyers. Staff consultation availability drives trial conversion for microbiome-positioned entrants.
- Specialty Retail:Department store beauty halls and perfumery chains emphasizing experiential sampling and gift-oriented packaging. The channel captures highest per-unit margins but requires substantial marketing co-investment.
Supermarkets retain volume leadership; online holds the steepest expansion curve.
Customer Type:
Application context varies sharply across demographic segments with divergent efficacy expectations and price sensitivity profiles.
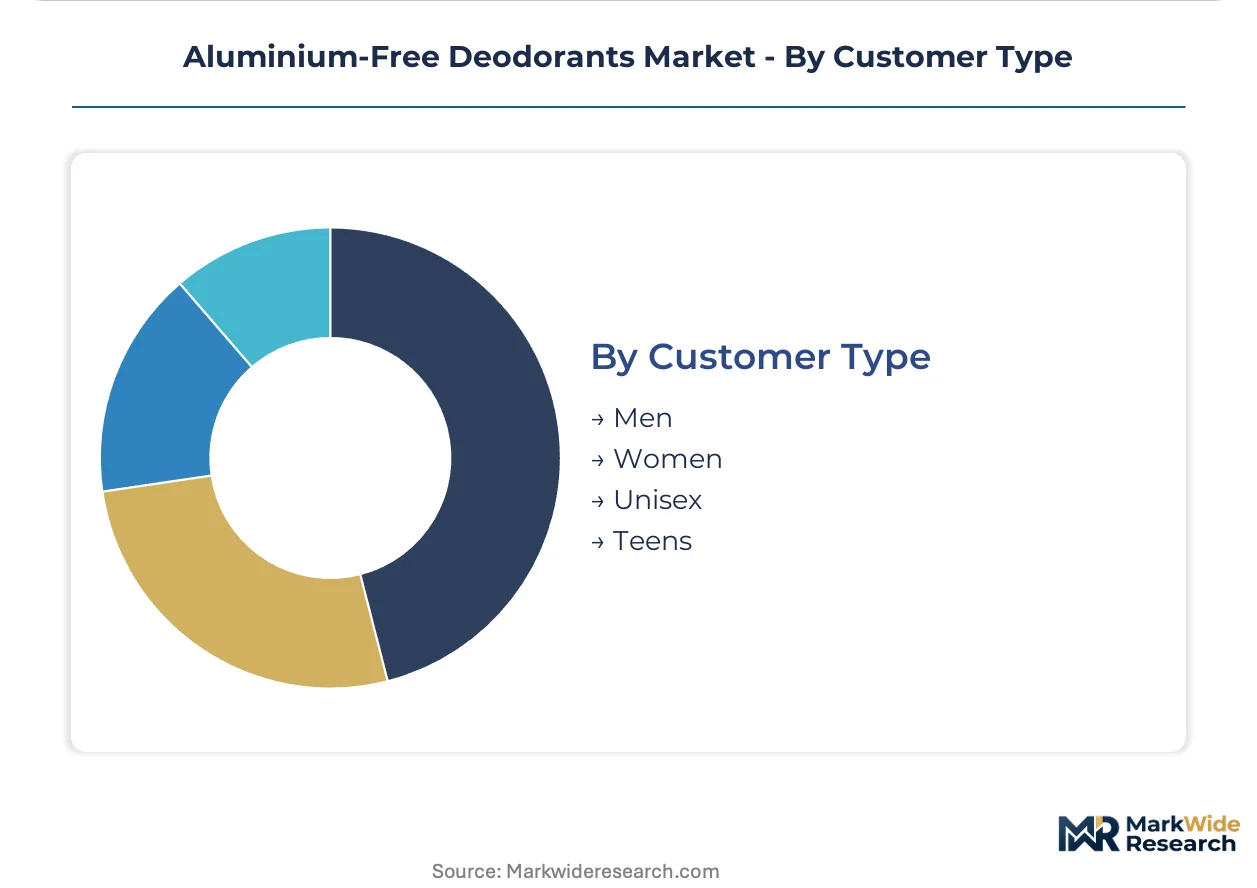
- Men:Formulations addressing higher apocrine gland density and grooming routine integration, often with subdued fragrance profiles. Underdeveloped adoption in France and Spain offers whitespace for gender-specific marketing.
- Women:The largest historical segment with broadest format acceptance and highest willingness to pay for skin-compatible ingredients. Dermatologist endorsement carries disproportionate influence in purchase decisions.
- Unisex:Neutral fragrance positioning and minimalist packaging designed for household sharing and reduced SKU complexity. The segment is expanding fastest among cohabiting urban millennials seeking routine simplification.
- Teens:Entry-level price points and educational messaging around puberty-related body odor management. Parental purchase influence dominates, with clean-label claims serving as proxy for safety reassurance.
Women retain volume leadership; unisex is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Article 33 disclosure obligations are restructuring supplier qualification protocols across European manufacturing bases. German and Dutch formulators are accelerating organic certification timelines to maintain BfR compliance documentation. United States direct-to-consumer platforms are capturing subscription-driven repeat purchase rates above sixty percent.
United States
Urban millennial clusters in New York and Los Angeles are driving clean-label personal care penetration through subscription commerce platforms. FDA cosmetic labeling claims enforcement requires safety substantiation for all aluminum-free efficacy positioning. Native and other challenger brands headquartered in San Francisco anchor direct-to-consumer channel control with recurring revenue models.
Germany
Arrowroot powder adoption is displacing cornstarch in natural formulations due to superior moisture absorption and non-GMO clean-label positioning. BfR safety assessments influence formulation standards across neighboring European markets. Berlin and Hamburg manufacturing clusters are restructuring supplier protocols to maintain REACH compliance documentation at 0.1% weight-by-weight thresholds.
United Kingdom
Holland & Barrett health store networks are capturing ingredient-conscious buyer fragmentation through curated clean-beauty assortments. The UK's post-EU regulatory alignment maintains REACH-equivalent substance restrictions for aluminum compound classifications. London specialty retail and pharmacy chains are expanding dedicated natural personal care shelf space for microbiome-positioned entrants.
France
Underdeveloped aluminum-free adoption among male consumers creates whitespace for gender-specific formulation marketing. ANSM cosmetic safety monitoring reinforces EU-wide disclosure mandates for substances of very high concern. Paris beauty halls and perfumery chains emphasize experiential sampling for premium skincare enthusiasts seeking clinical-grade positioning.
Netherlands
Health food retailers in Amsterdam and Rotterdam are unbundling deodorant from bundled personal care routines through standalone premium purchase occasions. Dutch formulators lead arrowroot powder integration due to superior skin compatibility in humid climate conditions. Eindhoven contract manufacturing clusters are narrowing capital barriers for challenger brands through asset-light private-label financing.
Aluminium-Free Deodorants Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Incumbent multinationals leverage global supply chain infrastructure to sustain volume leadership across supermarkets and pharmacy retail. Direct-to-consumer specialists and natural-formulation challengers occupy distinct archetypes based on subscription revenue models and ingredient transparency positioning. Competitive moves concentrate on portfolio diversification into men's grooming segments and enzymatic biotechnology convergence for clinical-grade efficacy claims.
Within the incumbent multinational tier, Unilever PLC and Beiersdorf AG exemplify scale-driven supply chain leverage across European and North American mass retail. Among direct-to-consumer specialists, Native occupies a position anchored in subscription-based revenue models and channel control. Procter and Gamble Co. and L'Oreal SA represent portfolio diversification strategies extending aluminum-free lines from established personal care franchises.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter and Gamble Co. |
| Colgate-Palmolive Co. |
| L'Oreal SA |
| Beiersdorf AG |
| Native |
| Schmidt's |
| Weleda |
| Lume |
| Others |
Value Chain & Pricing Dynamics
Arrowroot powder price volatility from West African supply disruptions determines both the premium spread for organic-certified formulations and the geographic restructuring of raw material sourcing networks across European manufacturing bases.
Pricing Analysis
Certification level creates the primary spread between mass-market and premium tiers, with COSMOS and NATRUE organic credentials commanding 40-60% markups over conventional natural alternatives. Three-tier pricing structure separates dermatologist-endorsed clinical positioning from standard clean-label offerings from economy synthetic alternatives. Cost compression in the synthetic tier is intensifying because cornstarch substitution programs are narrowing input cost differentials. Subscription-commerce buyers in the United States exhibit lowest price sensitivity, while supermarket switchers from conventional antiperspirants drive volume at entry price points.
Supply Chain Analysis
Single-source dependency on shea butter cooperatives in Ghana and Burkina Faso dominates supply chain risk profiles for emollient-heavy natural formulations. Manufacturing concentration centers on Germany, the Netherlands, and the United States, with Eindhoven and Berlin clusters anchoring European contract production. Zinc ricinoleate from castor oil cultivation in India, arrowroot starch from West Africa, and candelilla wax from northern Mexico constitute critical input dependencies. Distribution runs through pharmacy retail chains in Germany and direct-to-consumer platforms in the United States, with health food retailers capturing premium access in the Netherlands and Austria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ingredient-conscious buyer fragmentation is creating distinct niche opportunities across microbiome-positioned, gender-specific, and dermatologist-aligned product archetypes that reward targeted positioning over mass-market coverage.
For Market Incumbents: Insulate premium positioning through captive supply agreements with arrowroot powder cooperatives and accelerated BfR-compliant formulation pipelines that preempt REACH restriction expansions. Deepen backward integration into enzymatic biotechnology capabilities to defend against clinical-grade challenger entrants. Prioritize men's grooming line extensions in France and Spain before specialist brands establish gender-specific credibility. For New Entrants and Emerging Players: Underpenetration in male aluminium-free adoption across Southern Europe offers immediate whitespace for apocrine-gland-specific formulations with subdued fragrance profiles. Pharmacy retail expansion at dm-drogerie markt and Boots creates shelf access without mass retail slotting fee burdens. Target enzymatic biotechnology convergence with lactobacillus ferment positioning to differentiate from commodity baking soda alternatives. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors direct-to-consumer specialists with subscription infrastructure and clean-label supply chain documentation. Long-term viability hinges on microbiome science differentiation rather than ingredient-avoidance positioning. Watch for EU microplastic restriction expansion affecting synthetic fragrance carriers as the inflection signal for reformulation-heavy investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Commerce Infrastructure | Native's recurring revenue model demonstrates 60%+ repeat purchase retention in US urban clusters. |
| Enzymatic Biotechnology Convergence | Lactobacillus ferment filtrates with prebiotic support open clinical-grade positioning channels in Scandinavia. |
| Men's Grooming Line Extension | France and Spain present underdeveloped adoption whitespace for gender-specific apocrine formulations. |
| Pharmacy Retail Shelf Expansion | dm-drogerie markt and Boots dedicated natural sections create premium access without mass retail fees. |
| Organic Certification Acceleration | COSMOS and NATRUE credentials compress challenger brand velocity but defend margin in health stores. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA cosmetic labeling filings, EU REACH substance restriction databases, and Nielsen retail audit data covering German and US mass retail channels. Interviews with cosmetic formulation chemists, pharmacy retail category buyers, contract manufacturing procurement leads, and dermatology clinic retail coordinators informed supply chain and efficacy positioning assessments. Bottom-up volume modeling from ingredient input demand and top-down triangulation against personal care category expenditure trends validated market size estimates.
Forecast inputs span product format adoption curves, organic certification penetration rates, and subscription commerce growth patterns across the analysis window. Segmentation dimensions include formulation philosophy, distribution channel, customer type, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical clean-label personal care category performance and projected REACH restriction enforcement timelines. Arrowroot powder substitution rates and enzymatic biotechnology adoption velocity constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer microbiome specialists or accelerated EU microplastic restrictions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Colombia Cosmetics Products Market