
 Europe Professional Beauty Services Market | 2026-2036
Europe Professional Beauty Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Professional Beauty Services Market Insights
Market Context
Premium service tiers is rotating toward certified organic and clean-beauty protocols across European salons. L'Oréal Professionnel leverages its Paris-based R&D hub to develop professional-grade formulations that meet stringent EU standards. TONI&GUY Hairdressing anchors its competitive position through specialized editorial and fashion-sector styling services. Sally Beauty Holdings Inc extends its wholesale distribution network to supply independent salons across Southern and Eastern Europe.
Technical Definition and Segments
Europe Professional Beauty Services encompasses licensed, facility-based aesthetic treatments including chemical hair processing, dermal resurfacing, and semi-permanent nail augmentation performed with professional-grade compounds and calibrated equipment. These services require practitioner certification, controlled environments, and products with higher active-ingredient concentrations than retail equivalents. Hair Care services dominate revenue within the Service Type dimension due to repeat-visit frequency and upsell potential for color and treatment add-ons. The Equipment category under Product Type commands elevated margins as salons invest in laser, LED, and microcurrent technologies. Mobile Services within the End User dimension represents the fastest-expanding channel as digitized booking platforms reduce customer acquisition costs for independent practitioners.
Regulatory Environment
REACH and the EU Green Deal constrain ingredient palettes for professional formulations, while ECHA classification rules govern salon chemical handling and ventilation standards. France's ANSM and Germany's BfArM enforce divergent notification requirements for novel cosmetic active ingredients, fragmenting product registration timelines across the region. Stakeholders must monitor pending CSRD sustainability disclosure rules that will mandate supply-chain transparency for salon-group procurement decisions.
Market Dynamics
REACH compliance costs and CSRD disclosure mandates are compressing margins for independent salons while accelerating consolidation among multi-location chains that can amortize regulatory overhead across larger revenue bases.
Growth Catalysts
- Clean-beauty certification mandates:France's ANSM and Germany's BfArM are tightening notification requirements for novel cosmetic actives, pushing salons toward pre-certified professional-grade formulations that reduce liability exposure.
- Urban cluster densification:Milan, Paris, and London generate disproportionate service demand due to concentrated high-net-worth populations and fashion-industry adjacency.
- LED and microcurrent device proliferation:Non-invasive skin treatment technologies expand addressable client bases beyond traditional chemical-peel candidates.
Market Restraints
- Professional-grade ingredient cost volatility:Botanical extracts and peptide complexes face agricultural supply fluctuations that compress salon service margins.
- Equipment supplier concentration:Laser and microcurrent device manufacturing clusters in Northern Italy and Southern Germany create geographic supply risk.
- REACH registration timelines:ECHA's extended safety-data requirements delay new active ingredient commercialization by 18-24 months.
Strategic Opportunities
- Eastern European penetration gaps:Poland and Romania exhibit salon density ratios below Western European benchmarks with rising disposable income trajectories.
- Mobile service platform expansion:Digitized booking infrastructure reduces customer acquisition costs for independent practitioners operating outside fixed-location overhead.
- CSRD-aligned procurement transparency:Salon groups can differentiate through supply-chain disclosure that meets emerging corporate client sustainability mandates.
Industry Challenges
- Certified practitioner scarcity:Advanced chemical hair processing and laser operation require specialized training pipelines that lag demand growth in Southern Europe.
- Legacy booking system integration:Independent salons face friction migrating from paper-based appointment management to platform-connected infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Professional Beauty Services Market |
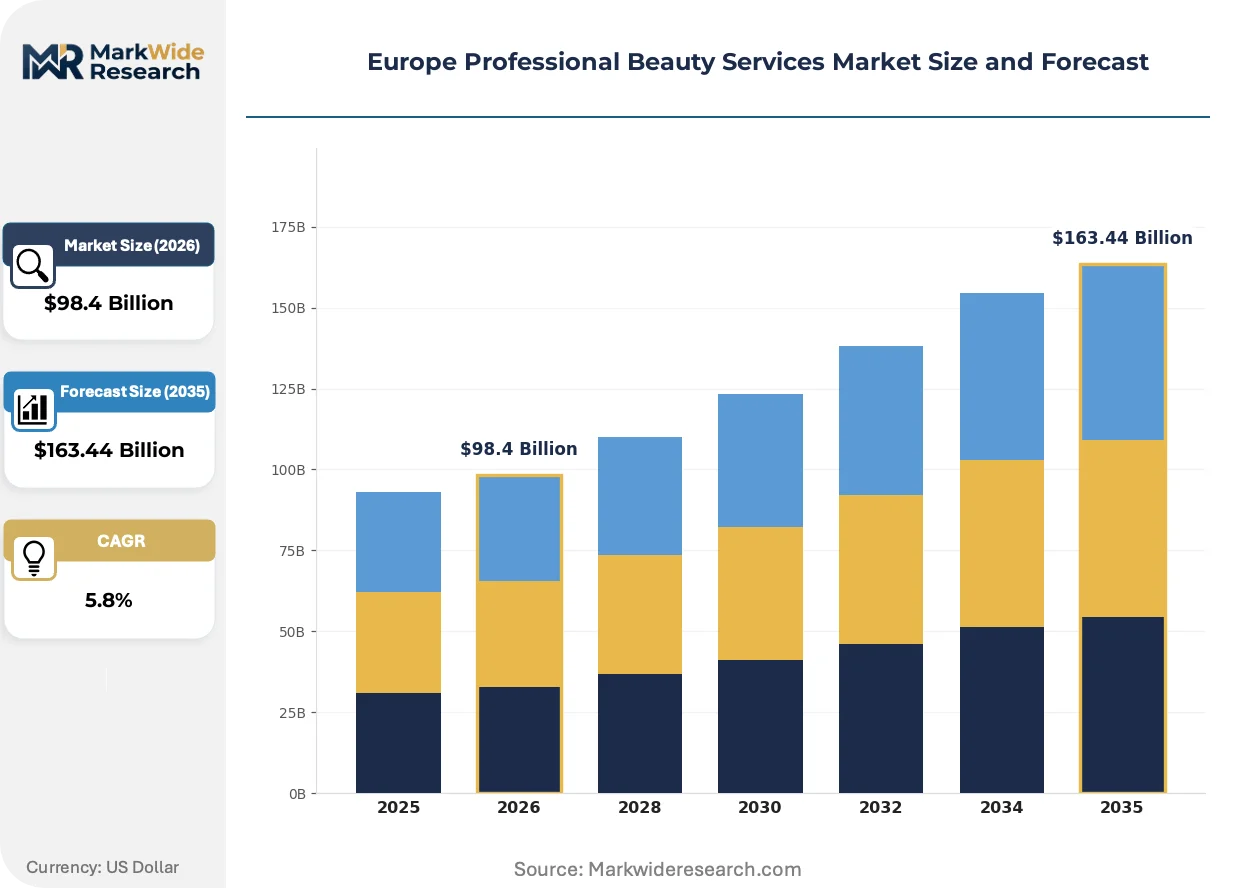
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $163.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hair Care, Skin Care, Nail Care, Makeup Services End User: Salons, Spas, Mobile Services, Educational Institutions Product Type: Cosmetics, Skincare Products, Haircare Products, Equipment Client Type: Individuals, Professionals, Corporates, Affluent Customers |
| Companies Covered | L'Oréal Professionnel, Ulta Beauty Inc, Regis Corp, Great Clips Inc, Fantastic Sams Franchise, TONI&GUY Hairdressing, Sally Beauty Holdings Inc, Coty Inc, Franck Provost, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Professional Beauty Services Market Trends and Innovations
Professional beauty services across Europe are pivoting toward technology-augmented personalization and regulatory-preemptive formulation strategies that redefine competitive differentiation.
AI-powered skin diagnostic imaging is displacing manual consultation protocols in premium-tier salons. Paris and London flagship locations deploy facial-scanning hardware that generates treatment recommendations within 90 seconds. This compression of assessment time is displacing traditional aesthetician-led consultation revenue models toward device-dependent service architectures.
CSRD sustainability disclosure rules are mandating supply-chain transparency for salon-group procurement decisions. The framework requires documented ingredient provenance and carbon footprint attribution across professional product lines. German salon chains are responding fastest, integrating blockchain-tracked certification into supplier qualification criteria.
Subscription-based maintenance programs are replacing transactional appointment booking in urban UK markets. Clients pre-commit to quarterly color-refresh and treatment cycles through platform-locked pricing. This behavioral shift concentrates most visibly in London's Zone 1-2 postcodes where time-scarcity premiums exceed price sensitivity thresholds.
Europe Professional Beauty Services Market Segmentation
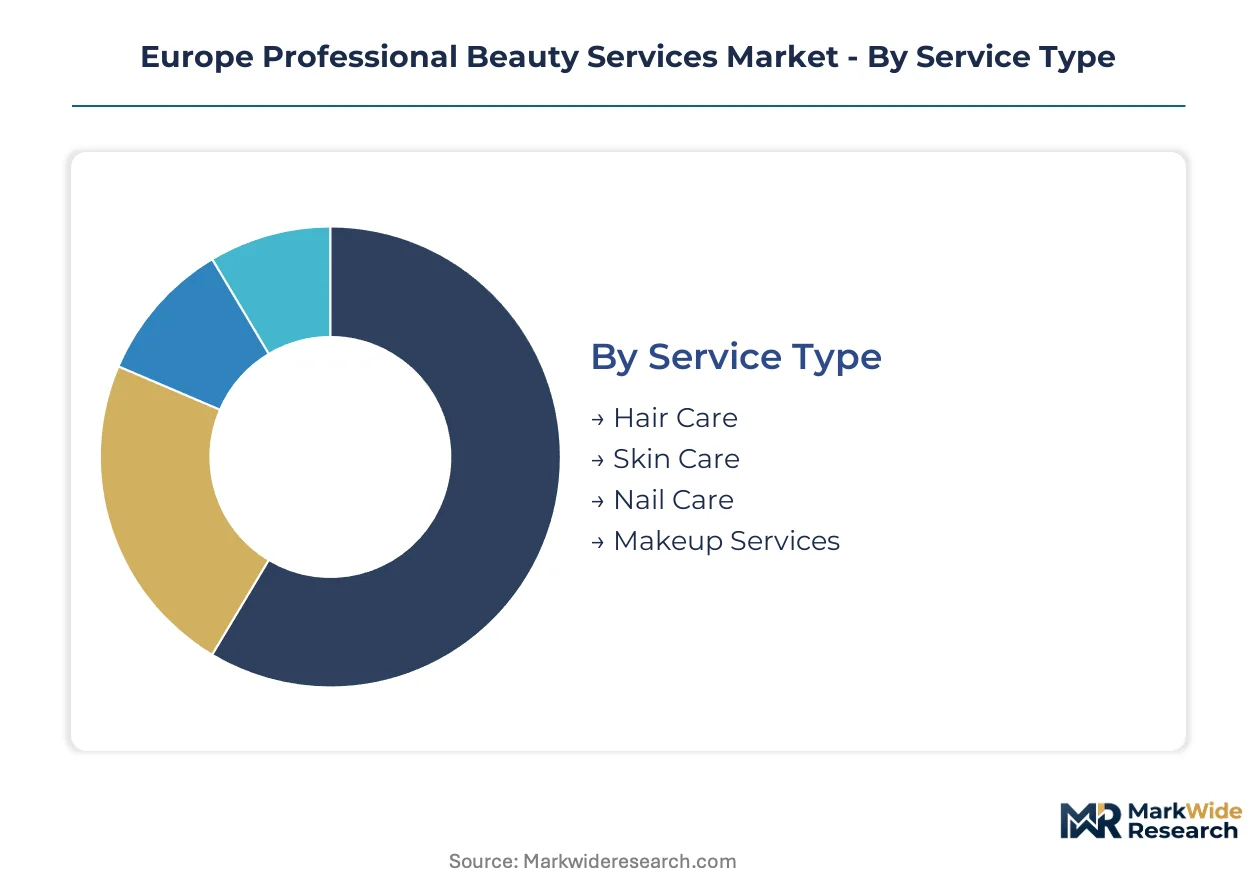
Professional beauty services across Europe fragment across four distinct dimensions that determine regulatory exposure, margin architecture, and customer acquisition economics. Each segmentation layer carries divergent compliance burdens under REACH, CSRD, and national health authority frameworks.
Service Type:
REACH and national health authority classifications differentiate service tiers by chemical risk exposure and practitioner certification requirements.
- Hair Care:Chemical processing services including coloration, perming, and keratin treatments use professional-grade formulations with elevated active concentrations. Demand concentrates in Paris, London, and Milan salon clusters where repeat-visit frequency drives recurring revenue. Regulatory complexity from ECHA ventilation and handling mandates elevates operational overhead.
- Skin Care:Dermal resurfacing, LED therapy, and microcurrent treatments require controlled environments and device calibration protocols. French and German urban centers exhibit strongest uptake as affluent clientele prioritize non-invasive aesthetic protocols. ANSM and BfArM notification requirements for novel actives extend product development timelines.
- Nail Care:Gel augmentation and acrylic sculpting services use methacrylate-based compounds subject to occupational exposure limits.
- Makeup Services:Editorial, bridal, and permanent makeup applications serve fashion-industry adjacencies and event-driven demand.
Hair Care handles the majority of throughput; Skin Care is the fastest mover on share.
End User:
Facility-based versus distributed service models create divergent capital intensity profiles and customer acquisition cost structures.
- Salons:Fixed-location operations with calibrated equipment suites and controlled ventilation systems anchor professional service delivery. UK and German multi-location chains amortize regulatory compliance costs across larger revenue bases. CSRD disclosure mandates favor consolidated procurement and supply-chain transparency.
- Spas:Wellness-integrated facilities combine aesthetic treatments with hospitality service tiers. Italian thermal spa traditions and Nordic wellness culture drive geographic concentration. Premium positioning supports elevated pricing for certified organic protocols.
- Mobile Services:Digitized booking platforms reduce customer acquisition costs for independent practitioners operating outside fixed-location overhead. Fastest-expanding channel as platform infrastructure matures across urban UK and French markets.
- Educational Institutions:Training facilities and certification programs supply licensed practitioners to commercial operators.
Salons command the dominant revenue position; Mobile Services exhibit the steepest expansion trajectory.
Product Type:
Margin concentration varies sharply between consumable formulations and durable equipment categories.
- Equipment:Laser, LED, and microcurrent devices command elevated margins as salons invest in technology-augmented service differentiation. Manufacturing clusters in Northern Italy and Southern Germany create geographic supply concentration. CE marking and MDR compliance extend procurement qualification timelines.
- Cosmetics:Professional-grade color cosmetics and treatment formulations with higher active concentrations than retail equivalents. REACH registration requirements constrain ingredient palette innovation. German salon chains lead blockchain-tracked supply-chain certification adoption.
- Skincare Products:Peptide complexes and botanical extracts face agricultural supply fluctuations that compress service margins.
- Haircare Products:Professional coloration and treatment lines anchor recurring procurement relationships with salon operators.
Equipment delivers the highest margin contribution; Cosmetics represents the largest procurement volume category.
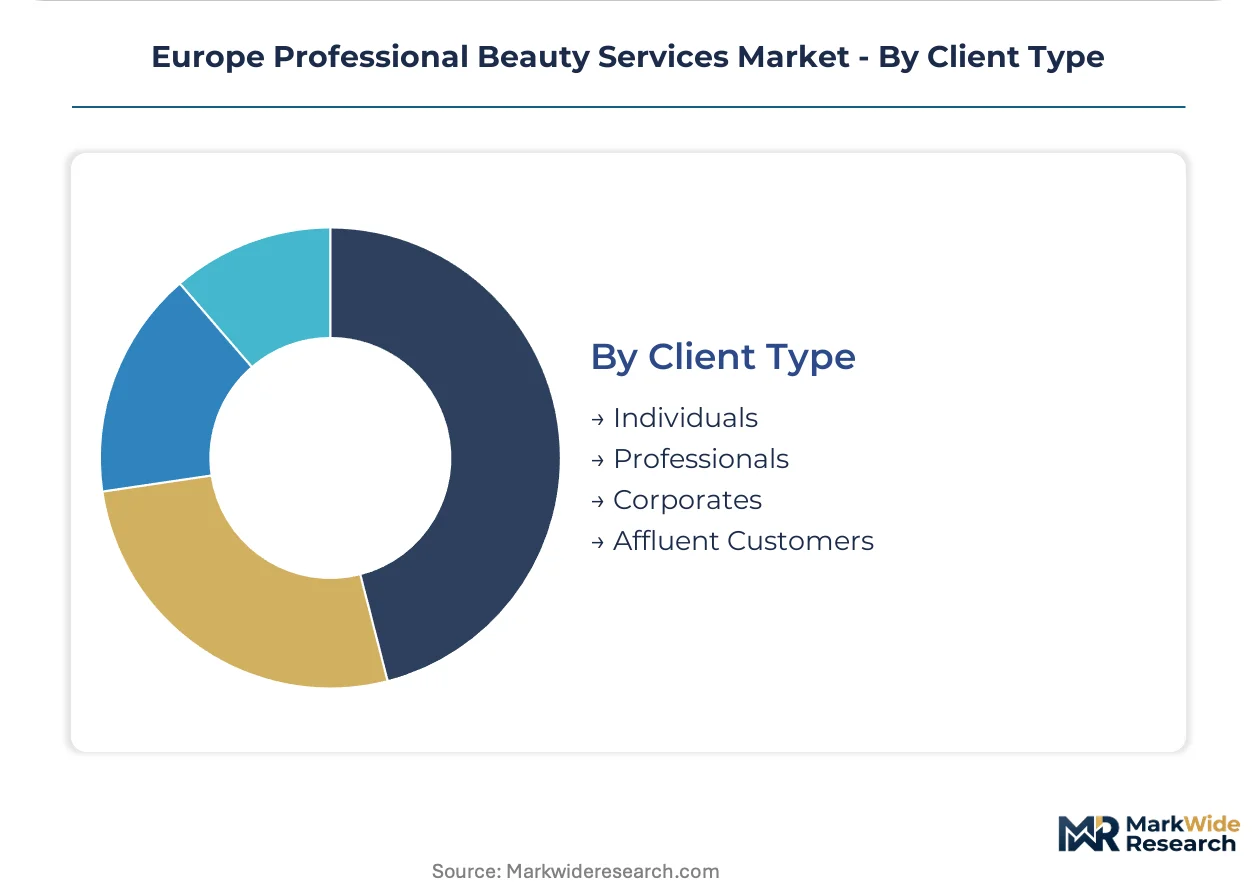
Client Type:
Customer segmentation determines pricing architecture and service protocol customization depth.
- Affluent Customers:High-net-worth individuals in London Zone 1-2, Paris arrondissements, and Milan centro storico drive premium-tier demand. Time-scarcity premiums exceed price sensitivity, supporting subscription-based maintenance program adoption.
- Individuals:Transactional appointment booking for occasion-driven services across price-accessible salon tiers.
- Professionals:Fashion, editorial, and entertainment sector clients requiring specialized styling and makeup services.
- Corporates:Wellness program procurement and executive grooming services for financial and professional services firms.
Affluent Customers generate disproportionate revenue per visit; Corporates represent the fastest-expanding contract-based segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional-grade formulation manufacturing clusters in Northern Italy and Southern Germany anchor supply-side capacity for salon equipment and chemical compounds across the continent. REACH registration requirements and CSRD disclosure mandates create divergent compliance burdens that favor consolidated multi-location chains over independent operators. Urban demand concentrates in fashion-industry adjacent metropolitan zones where affluent clientele drive premium service adoption.
Germany
BfArM notification requirements for novel cosmetic actives extend product development timelines for professional formulations. The EU Green Deal's chemical hazard classification rules elevate operational overhead for Berlin and Munich salon clusters. Bavaria's precision manufacturing base supplies calibrated laser and microcurrent devices to premium-tier operators across Central Europe.
France
ANSM tightening of clean-beauty certification standards pushes Parisian salons toward pre-certified organic protocols. Subscription-based maintenance programs displace transactional booking in Zone 1-2 postcodes where time-scarcity premiums dominate. L'Oréal Professionnel's Paris R&D hub develops REACH-compliant professional-grade coloration systems for export markets.
United Kingdom
London's editorial and fashion-sector styling services anchor TONI&GUY Hairdressing's competitive positioning through specialized practitioner training. Digitized booking platforms reduce customer acquisition costs for mobile service practitioners operating across Greater London and Manchester. Post-Brexit regulatory divergence from REACH creates fragmented product registration requirements for cross-border salon chains.
Italy
Milan's centro storico salon density supports the highest per-capita professional service spending in Southern Europe. Italian thermal spa traditions drive wellness-integrated aesthetic treatment demand in Lombardy and Veneto. Northern Italy's manufacturing clusters produce CE-marked LED therapy devices subject to MDR compliance timelines.
Poland
Rising disposable income trajectories in Warsaw and Kraków create penetration gaps below Western European salon density benchmarks. Independent practitioners leverage mobile service platforms to bypass fixed-location overhead in secondary urban markets. Polish operators face delayed access to novel active ingredients due to ECHA extended safety-data review periods.
Europe Professional Beauty Services Market Competitive Landscape
Concentration sits with multi-location salon chains and integrated beauty conglomerates that amortize regulatory compliance costs across larger revenue bases. The vendor base spans three strategic archetypes: Paris-based formulation developers, UK-headquartered editorial styling specialists, and US-origin wholesale distributors. Competitive moves center on M&A consolidation of independent salon networks and backward integration into professional-grade product manufacturing.
Within the integrated conglomerate tier, L'Oréal Professionnel and Coty Inc exemplify formulation-to-service vertical control. TONI&GUY Hairdressing occupies a position among editorial-specialist operators with fashion-sector adjacency. Sally Beauty Holdings Inc represents wholesale distribution archetypes supplying independent salons across Southern and Eastern Europe. These anchors illustrate divergent scale economies: R&D-amortized product development, practitioner certification premiums, and procurement-volume leverage respectively.
| Leading Market Players |
|---|
| L'Oréal Professionnel |
| Ulta Beauty Inc |
| Regis Corp |
| Great Clips Inc |
| Fantastic Sams Franchise |
| TONI&GUY Hairdressing |
| Sally Beauty Holdings Inc |
| Coty Inc |
| Franck Provost |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Northern Italian and Southern German manufacturing clusters shapes both supply concentration and price floors for professional-grade salon equipment. REACH registration cost amortization across larger production volumes elevates minimum efficient scale thresholds, compressing margins for smaller formulation suppliers while entrenching pricing power among consolidated equipment makers.
Pricing Analysis
REACH compliance costs dictate the pricing tier structure across European professional beauty services. Three-tier pricing structure across premium, standard, and economy levels separates certified organic protocols from conventional formulations and unbranded alternatives. Price differentiation rests on certification grade and brand premium, with German salon chains commanding loyalty-based volume discounts. Cost compression in the independent salon tier is intensifying because ECHA extended safety-data review periods delay cost-recovery timelines. Corporate wellness procurement exhibits lowest price sensitivity; mobile service practitioners in secondary Polish and Romanian markets face highest price elasticity.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for botanical extract shipments from Asia Minor underwrites supply security planning for peptide-dependent skincare formulations. Manufacturing gravity centers on Northern Italy for CE-marked LED therapy devices, Southern Germany for precision microcurrent hardware, and France for professional coloration chemistry. Raw material dependencies include methacrylate compounds for nail augmentation, agricultural-derived botanical extracts, and rare-earth elements for laser cavity components. Single-source vulnerability concentrates in Northern Italian device manufacturing clusters where MDR compliance timelines extend supplier qualification periods. Distribution runs through wholesale distributors supplying independent salons across Southern and Eastern Europe, anchored by consolidated procurement networks serving multi-location chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional beauty services across Europe are entering a cyclical recovery phase as post-pandemic service frequency normalization and urban cluster densification restore utilization rates at fixed-location facilities.
For Market Incumbents: Fortify market position through backward integration into professional-grade formulation manufacturing and captive supply of certified organic product lines. Consolidate independent salon networks in Warsaw and Kraków before mobile service platforms achieve critical mass. Channel control through digitized booking infrastructure investments will defend against platform-mediated customer acquisition cost compression threatening independent operator economics. For New Entrants and Emerging Players: Anchor in Eastern European penetration gaps where salon density ratios trail Western European benchmarks and rising disposable income trajectories support greenfield expansion. Poland's secondary urban markets exhibit the most penetrable whitespace for mobile service platform deployment. A direct-to-professional distribution model bypassing wholesale markups offers viable go-to-market positioning against established supply relationships. For Investors and Strategic Acquirers: Multi-location salon chains with integrated training academies and blockchain-tracked supply-chain certification represent the highest-conviction acquisition archetype for medium-term value creation. Long-term viability across the analysis window depends on CSRD-aligned procurement transparency capabilities that unlock corporate wellness contract segments. Monitor ECHA regulatory timeline compression as the inflection signal indicating accelerated consolidation velocity among formulation-dependent service operators.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Aligned Supply-Chain Certification | Blockchain-tracked ingredient provenance unlocks corporate wellness procurement contracts requiring sustainability disclosure. |
| Mobile Service Platform Expansion | Digitized booking infrastructure reduces customer acquisition costs for independent practitioners beyond fixed-location overhead. |
| Backward Integration into Formulation Manufacturing | In-house production of REACH-compliant professional-grade coloration systems captures margin from third-party suppliers. |
| Eastern European Salon Network Consolidation | Acquisition of independent operators in Warsaw and Kraków builds density before mobile platforms achieve scale. |
| AI-Powered Diagnostic Device Deployment | Facial-scanning hardware integration at Paris and London flagship locations compresses consultation-to-treatment conversion timelines. |
Research Methodology
Initial hypotheses were tested against primary input from salon chain procurement directors, independent practitioner network coordinators, professional product formulation R&D leads, and regulatory affairs specialists at national health authorities, then refined through secondary validation. Bottom-up and top-down triangulation combined trade flow analysis from Eurostat customs data, ECHA registration database extracts, ANSM and BfArM notification filings, and SEC disclosures from listed beauty conglomerates with structured interviews across 12 European metropolitan salon clusters.
Variance decomposition across service type, end-user channel, product category, and client archetype dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value build-ups calibrated to regulatory timeline assumptions and urban demand density coefficients. Industry-specific forecast inputs included ECHA safety-data review period distributions and mobile service platform penetration curves across UK and French urban markets.
Material uncertainties — REACH registration timeline extensions, CSRD disclosure mandate implementation sequencing, and agricultural supply fluctuations affecting botanical extract costs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and practitioner certification pipeline throughput that could shift with policy acceleration or training capacity constraints. Practitioners should keep alternative scenarios live as EU Green Deal chemical hazard reclassification proceedings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Waterless Cosmetics Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Germany Lip Care Products Market