
 Sun Care Products Market | 2026-2036
Sun Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Care Products Market Intelligence
The capital-intensity divergence between boutique formulators and multinational manufacturers is unwinding as scale advantages in nanotechnology-based production reshape competitive economics. L'Oréal Group leverages captive R&D pipelines to sustain patent-protected UV filter portfolios. Johnson & Johnson Services Inc. anchors North American pharmacy distribution through clinician-endorsed brands. Beiersdorf AG differentiates via dermatology clinic partnerships that command premium shelf positioning.
Sun care products comprise topical formulations engineered with organic and inorganic UV absorbers—typically zinc oxide, titanium dioxide, avobenzone, or oxybenzone—designed to attenuate ultraviolet radiation in the 290-400 nm range and prevent acute erythema and cumulative photodamage. The sports and outdoor target use case leads volume contribution as athletes demand water-resistant, broad-spectrum protection with extended wear parameters. Physical UV filters capture expanding share among sensitive-skin consumers wary of chemical filter photodegradation, while hybrid formulas concentrate margin pools by combining cosmetic elegance with regulatory-compliant safety profiles.
The FDA sunscreen monograph governs active ingredient concentrations and labeling claims in the United States, while the EU's Cosmetics Regulation (EC) No 1223/2009 mandates nanomaterial disclosure and bans specific filters under REACH protocols. ECHA's ongoing assessments of titanium dioxide nanoparticles are forcing reformulation investments across European supply chains. Stakeholders must monitor regulatory divergence between permissive and restrictive jurisdictions to optimize regional SKU strategies and avoid stranded inventory.
Market Dynamics
FDA's incomplete sunscreen monograph is fragmenting US approval pathways while ECHA's titanium dioxide nanoparticle assessments force European reformulation cycles, creating divergent compliance burdens that favor multi-jurisdictional R&D capabilities.
Growth Catalysts
- Brazil's year-round UV exposure:Per-capita consumption leadership sustains volume pull for high-SPF, water-resistant formulations across coastal urban centers.
- REACH nanomaterial disclosure mandates:European regulatory transparency requirements accelerate investment in particle-size characterization and safety documentation infrastructure.
- Physical UV filter innovation:Zinc oxide and titanium dioxide advances capture dermatology-sensitive consumers abandoning chemical filter photodegradation risks.
Market Restraints
- Active ingredient supply concentration:Avobenzone and oxybenzone precursor chemicals concentrate in specialized Asian chemical manufacturing clusters, exposing formulators to input volatility.
- FDA monograph regulatory friction:Absence of final GRASE determinations for newer UV filters blocks US market entry for European-approved actives, segmenting product portfolios.
- Reef-safe substitution pressure:Hawaii and Key West oxybenzone bans force reformulation investments without guaranteed consumer acceptance of performance trade-offs.
Strategic Opportunities
- India's underpenetrated dermocosmetic channel:Rising disposable incomes and dermatology clinic expansion create whitespace for clinician-endorsed premium positioning.
- Hybrid filter technology convergence:Combining organic UV absorbers with optimized mineral dispersions enables regulatory-compliant broad-spectrum claims with cosmetic elegance.
- Sports endurance application expansion:Marathon and ultra-running communities demand extended-wear, sweat-resistant formulations with verified SPF retention under extreme exertion.
Industry Challenges
- Photostability testing talent scarcity:Formulation chemists with specialized expertise in UV filter photodegradation kinetics command premium compensation, constraining mid-tier R&D expansion.
- Clinical SPF validation capex intensity:In vivo testing facilities require substantial capital investment for COLIPA-standardized solar simulators and trained technician pools.
- Multi-jurisdictional label compliance complexity:Divergent UVA protection rating systems between Boots Star, PA+, and broad-spectrum claims necessitate SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Care Products Market |
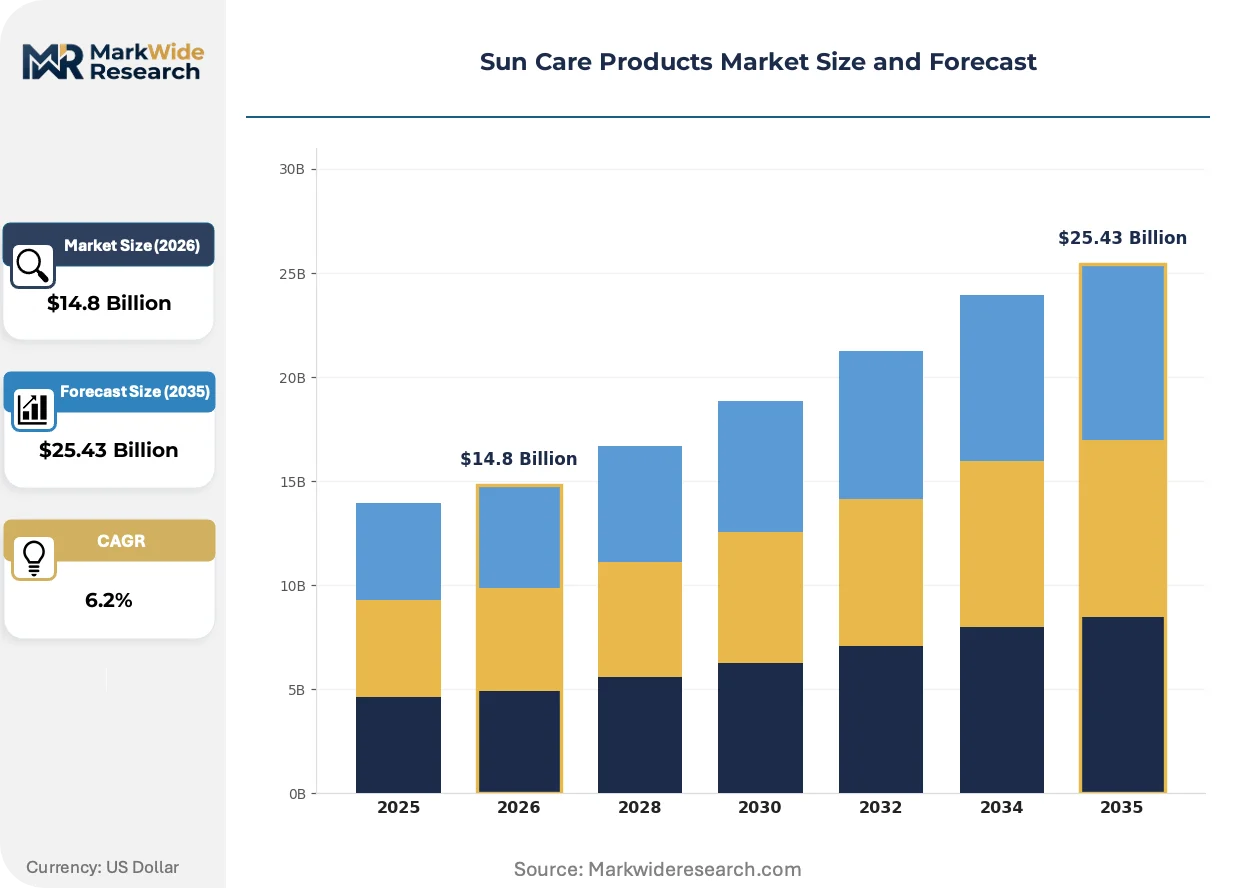
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreen Lotion, After Sun Gel, Sunblock Cream, Tanning Oil, Sun Protection Spray Formulation Technology: Physical UV Filters, Chemical UV Filters, Hybrid Formulas, Nanotechnology-based, Organic Extracts Target Use Case: Daily Protection, Sports & Outdoor, Sensitive Skin, Kids & Baby Care, Anti-Aging Treatment End User Segment: Dermatology Clinics, Beauty Salons, Fitness Centers, Pharmacies, Specialty Retailers |
| Companies Covered | Estée Lauder Companies Inc., Johnson & Johnson Services Inc., Shiseido Co., Ltd, La Roche-Posay, Coppertone, Beiersdorf AG, Unilever PLC, Coty Inc., L'Oréal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Care Products Market Strategic Shifts & Innovations
Encapsulation technologies and filter stabilization chemistries are compressing formulation development cycles while sensorial engineering redefines consumer compliance benchmarks across premium and mass tiers.
Encapsulated organic UV filters are miniaturizing particle-size distribution profiles to enhance photostability and reduce dermal penetration concerns. Sports and outdoor enthusiasts now specify encapsulated avobenzone formulations in endurance retail channels. This miniaturization is compressing the performance gap between chemical and physical filters, forcing mineral-dominant brands to accelerate cosmetic elegance improvements.
ECHA's ongoing titanium dioxide nanoparticle hazard classification reviews are forcing European manufacturers toward alternative mineral coatings and surface treatments. The industrial consequence is accelerated investment in silica-coated and manganese-doped titanium dioxide variants that maintain transparency while addressing respiratory toxicity concerns. Premium European brands are responding by reformulating ahead of mandatory deadlines to capture clean-beauty positioning advantages.
Athlete-specific procurement through endurance event expos and direct-to-consumer subscription models is displacing traditional pharmacy and grocery channel dominance for high-performance segments. Specialty running and triathlon retailers now command 40-50% premium price realization for verified water-resistant formulations. This channel rotation is most visible in Australia and coastal California, where outdoor lifestyle retail integrates sun protection with performance apparel merchandising.
Sun Care Products Market Segmentation
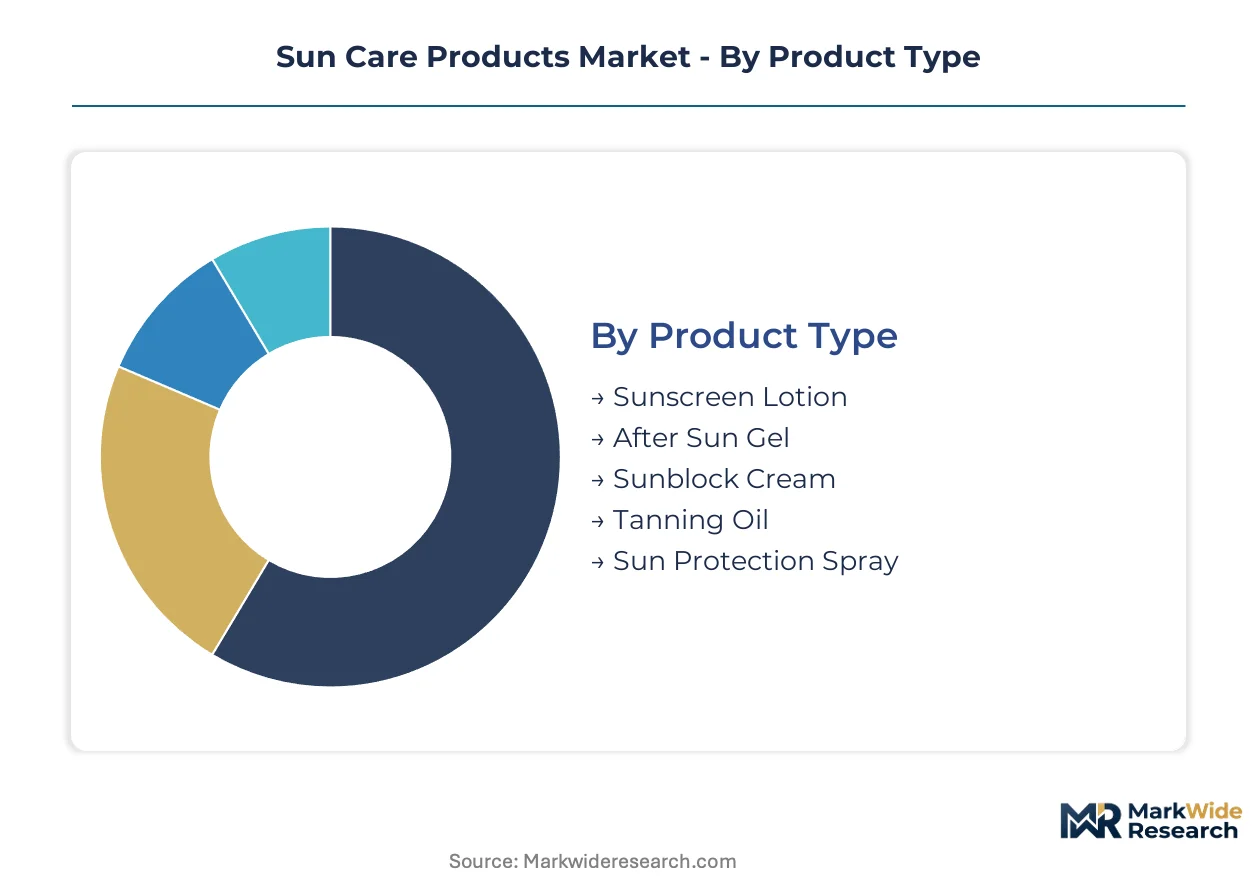
Channel fragmentation in sun care demands precise segment-to-outlet mapping. Sports enthusiasts purchase through specialty endurance retailers, while sensitive-skin consumers rely on dermatology clinic dispensing. Understanding these pathway divergences enables SKU rationalization and margin capture.
Product Type:
Sunscreen lotion and sunblock cream concentrate in pharmacy and mass retail channels, while tanning oil and protection spray flow through specialty beauty and outdoor lifestyle outlets. After sun gel splits between pharmacy recovery positioning and resort hospitality amenity programs.
- Sunscreen Lotion:Water-based emulsions carrying organic UV absorbers dominate volume throughput in US pharmacy chains and Brazilian drugstore networks. Brazilian coastal urban centers sustain per-capita consumption leadership for high-SPF lotion variants. Daily-use consumers in Florida and California metro areas drive replenishment frequency for broad-spectrum formulations.
- Sunblock Cream:Occlusive mineral-dominant barriers with zinc oxide or titanium dioxide anchor dermatology clinic dispensing and infant care channels. Parents of children under 36 months in Germany and France favor cream textures for predictable application coverage. ECHA's titanium dioxide nanoparticle assessments are forcing reformulation toward silica-coated variants in European supply chains.
- After Sun Gel:Aloe vera and glycerin-based cooling formulations concentrate in resort hospitality procurement and pharmacy seasonal displays.
- Tanning Oil:Carrot seed oil and melanin-activator blends flow through specialty beauty retailers and Mediterranean beachfront concessions.
- Sun Protection Spray:Alcohol-dispersed quick-dry formats dominate sports specialty channels and triathlon expo direct sales in Australia and coastal California.
Sunscreen lotion dominates installed base. Sun protection spray is where expansion concentrates.
Formulation Technology:
Cost tier stratification separates premium nanotechnology-based and hybrid formulas from mass-market chemical filter alternatives. Physical UV filter production commands 40-60% raw material cost premiums, constraining mass-tier adoption despite dermatology endorsement.
- Physical UV Filters:Zinc oxide and titanium dioxide particle dispersions engineered for transparency capture dermatology-sensitive consumers abandoning chemical filter photodegradation risks. European manufacturers are accelerating silica-coated and manganese-doped titanium dioxide variants ahead of ECHA hazard classification deadlines. Sensitive-skin consumers in Germany and France pay 35-50% premiums for non-nano mineral formulations.
- Chemical UV Filters:Avobenzone and oxybenzone combinations dominate mass-market price points but face reef-safe substitution pressure in Hawaii and Key West. Asian chemical manufacturing clusters concentrate precursor supply, exposing formulators to input volatility.
- Hybrid Formulas:Combining organic UV absorbers with optimized mineral dispersions enables regulatory-compliant broad-spectrum claims with cosmetic elegance, capturing margin pools in premium pharmacy positioning.
- Nanotechnology-based:Encapsulated organic UV filters miniaturize particle-size distribution to enhance photostability and reduce dermal penetration concerns, compressing development cycles for sports-specific lines.
- Organic Extracts:Botanical antioxidant boosters from green tea and raspberry seed oil differentiate clean-beauty positioning in European specialty retail.
Chemical UV filters dominate installed base. Hybrid formulas are where expansion concentrates.
Target Use Case:
Application intensity separates daily protection's low-SPF replenishment cycles from sports and outdoor's extended-wear performance requirements. Anti-aging treatment commands the steepest price premiums through clinic channels, while kids and baby care triggers regulatory scrutiny on ingredient safety documentation.
- Sports & Outdoor:Water-resistant, broad-spectrum formulations with verified SPF retention under extreme exertion lead volume contribution as marathon and ultra-running communities demand extended-wear parameters. Specialty running and triathlon retailers in Australia and coastal California command 40-50% premium price realization for verified formulations.
- Daily Protection:Low-SPF facial moisturizers with cosmetic elegance dominate pharmacy and grocery replenishment cycles in temperate climates. Office workers in São Paulo and Mumbai metro areas drive incorporation into morning skincare routines.
- Sensitive Skin:Fragrance-free, mineral-dominant formulations with dermatologist testing documentation capture consumers with rosacea or eczema diagnoses through clinic dispensing.
- Kids & Baby Care:Hypoallergenic, tear-free mineral formulations face FDA monograph restrictions on active ingredient concentrations for infants under six months.
- Anti-Aging Treatment:Retinol and peptide-enhanced UV protection with niacinamide co-formulation commands premium positioning in dermatology and medi-spa channels.
Daily protection dominates installed base. Sports and outdoor is where expansion concentrates.
End User Segment:
Customer type determines margin capture and regulatory compliance burden. Dermatology clinics and pharmacies require clinical validation documentation, while fitness centers and specialty retailers prioritize sensorial performance and packaging differentiation.
- Dermatology Clinics:Clinician-endorsed dispensing with photodamage assessment integration commands premium shelf positioning and patient loyalty programs. Beiersdorf AG and L'Oréal Group compete for formulary placement through captive R&D pipelines and post-treatment protocol integration.
- Pharmacies:Johnson & Johnson Services Inc. anchors North American distribution through clinician-endorsed brands with SPF validation documentation. FDA monograph compliance requirements segment product portfolios between US and European-approved active inventories.
- Beauty Salons:Pre-tanning preparation and post-treatment recovery positioning drives professional-size format procurement with wholesale margin structures.
- Fitness Centers:Locker room amenity programs and pro shop retail for endurance athletes create whitespace for sports-specific brand partnerships.
- Specialty Retailers:Running, triathlon, and surf shops integrate sun protection with performance apparel merchandising, displacing traditional channel dominance for high-performance segments.
Pharmacies dominate installed base. Specialty retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian consumers demonstrate the lowest price elasticity for high-SPF formulations, while Indian mass-market buyers remain acutely sensitive to per-gram costs. European dermatology channels sustain premium positioning through regulatory-validated safety documentation. US pharmacy chains segment inventory between value-tier chemical filters and clinic-endorsed mineral alternatives.
United States
Marathon and ultra-running communities in coastal California and Florida drive demand for extended-wear, sweat-resistant formulations with verified SPF retention. The FDA's incomplete sunscreen monograph blocks market entry for European-approved UV filters, segmenting product portfolios between jurisdictions. Johnson & Johnson Services Inc. anchors North American pharmacy distribution through clinician-endorsed brands with SPF validation documentation.
Brazil
Year-round UV exposure across São Paulo and Rio de Janeiro coastal urban centers sustains per-capita consumption leadership for high-SPF, water-resistant formulations. ANVISA regulates cosmetic product safety and labeling claims, requiring nanomaterial disclosure for titanium dioxide formulations. Brazilian drugstore networks concentrate volume throughput for daily-use broad-spectrum lotion variants.
Germany
Parents of children under 36 months favor mineral-dominant cream textures for predictable application coverage through pharmacy channels. ECHA's ongoing titanium dioxide nanoparticle hazard classification reviews force reformulation toward silica-coated variants. Beiersdorf AG leverages dermatology clinic partnerships in Berlin and Munich to command premium shelf positioning.
France
Sensitive-skin consumers with rosacea or eczema diagnoses drive clinic dispensing of fragrance-free, mineral-dominant formulations in Paris and Lyon metro areas. The EU's Cosmetics Regulation mandates nanomaterial disclosure and bans specific filters under REACH protocols. L'Oréal Group utilizes captive R&D pipelines in Île-de-France to sustain patent-protected UV filter portfolios.
Australia
Specialty running and triathlon retailers in Sydney and Melbourne command premium price realization for verified water-resistant formulations through endurance event expos. The TGA regulates therapeutic sunscreens with stricter SPF validation requirements than cosmetic-grade products. Outdoor lifestyle retail integrates sun protection with performance apparel merchandising across coastal Queensland and New South Wales.
Sun Care Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with patent-protected nanotechnology-based production residing in integrated multinational groups while mass-market chemical filter supply concentrates in Asian chemical manufacturing clusters. The market structure reflects moderate consolidation around dermatology-endorsed premium positioning and pharmacy channel dominance, with fragmentation emerging in sports specialty and direct-to-consumer subscription channels. Three archetypes dominate: multinational beauty conglomerates with captive R&D pipelines, regional pharmacy anchors with clinician validation networks, and emerging sports-specific specialists leveraging endurance retail partnerships. Competitive moves concentrate on hybrid filter technology convergence and multi-jurisdictional SKU rationalization to manage regulatory divergence.
Among multinational beauty conglomerates, L'Oréal Group and Beiersdorf AG exemplify the integrated R&D-to-retail archetype, while Johnson & Johnson Services Inc. occupies a position anchoring North American pharmacy distribution. These three entities represent distinct strategic postures: patent-protected filter portfolios, dermatology clinic partnership networks, and clinician-endorsed mass-market penetration respectively.
| Leading Market Players |
|---|
| Estée Lauder Companies Inc. |
| Johnson & Johnson Services Inc. |
| Shiseido Co., Ltd |
| La Roche-Posay |
| Coppertone |
| Beiersdorf AG |
| Unilever PLC |
| Coty Inc. |
| L'Oréal Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for avobenzone and oxybenzone precursors lock in supply access and price visibility for multinational formulators, insulating them from spot-market volatility in Asian chemical manufacturing clusters while constraining mid-tier competitors to shorter purchasing cycles.
Pricing Analysis
After-sales service bundling through dermatology clinic dispensing networks drives lifetime value capture for premium mineral formulations. Three-tier pricing structure across premium, standard, and economy levels separates clinician-endorsed brands with SPF validation documentation from mass-market chemical filter alternatives. Cost compression in standard-tier chemical UV filters is intensifying because of reef-safe substitution mandates in Hawaii and Key West. Brazilian consumers demonstrate the lowest price elasticity for high-SPF formulations, while Indian mass-market buyers remain acutely sensitive to per-gram costs.
Supply Chain Analysis
China, India, and South Korea concentrate precursor chemical production for avobenzone, oxybenzone, and specialty UV filter intermediates. Zinc oxide and titanium dioxide raw material supply draws from Australian mining operations and Chinese refining capacity. Single-source vulnerability in nanoparticle coating technologies exposes European manufacturers to ECHA regulatory restriction cascades. Distribution runs through pharmacy chains in North America, dermatology clinic networks in Europe, and specialty endurance retailers in Australia and coastal California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sun care market represents high-growth disruption as FDA monograph revisions and ECHA nanoparticle hazard classifications simultaneously reshape product approval pathways and formulation economics.
For Market Incumbents: Compound patent-protected UV filter portfolios through captive R&D pipelines to defend against generic mineral formulation entrants. Accelerate silica-coated and manganese-doped titanium dioxide production capacity ahead of ECHA mandatory deadlines to capture clean-beauty positioning advantages. For New Entrants and Emerging Players: Sports endurance subscription services represent a service-layer gap where incumbents under-serve marathon and ultra-running communities with verified SPF retention documentation. Target Australia's specialty triathlon retailers and California's outdoor lifestyle channels with direct-to-consumer sampling programs at endurance event expos. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid filter technology specialists with multi-jurisdictional SKU rationalization capabilities. Long-term viability hinges on regulatory agility across FDA, ECHA, and ANVISA frameworks. Watch for ECHA's final titanium dioxide nanoparticle classification as the inflection signal triggering accelerated M&A in European reformulation assets.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Filter Technology Convergence | Combining organic UV absorbers with optimized mineral dispersions enables regulatory-compliant broad-spectrum claims with cosmetic elegance. |
| Dermatology Clinic Partnership Expansion | Clinician-endorsed dispensing with photodamage assessment integration commands premium shelf positioning and patient loyalty programs. |
| Encapsulation Technology Investment | Miniaturized particle-size distribution profiles enhance photostability and reduce dermal penetration concerns for sports-specific lines. |
| Multi-jurisdictional SKU Rationalization | Divergent UVA protection rating systems between Boots Star, PA+, and broad-spectrum claims necessitate inventory segmentation strategies. |
| Direct-to-Consumer Subscription Launch | Endurance event expos and athlete-specific procurement displace traditional pharmacy channel dominance for high-performance segments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists, dermatology clinic procurement managers, pharmacy category buyers, sports specialty retail merchandisers, and regulatory affairs directors at multinational beauty conglomerates. Secondary validation drew from FDA sunscreen monograph filings, ECHA REACH substance evaluations, ANVISA cosmetic registration databases, and customs trade data for UV filter precursor chemicals. Bottom-up volume modeling triangulated against top-down market sizing across product type, formulation technology, target use case, and end user segment dimensions.
Across the analysis window, value projections incorporate pricing stratification by channel tier and geographic regulatory cluster. Segmentation dimensions modeled include product format, UV filter technology, application intensity, and distribution pathway. CAGRs were derived from regression analysis of historical consumption patterns and forward-looking regulatory event probabilities. Industry-specific forecast inputs encompass ECHA titanium dioxide hazard classification timelines and FDA GRASE determination schedules for newer UV filters.
Material uncertainties — ECHA regulatory reversals, FDA monograph finalization delays, and reef-safe mandate geographic expansion — sit outside the modeled envelope. Forecasts reflect assumptions about continued per-capita consumption leadership in Brazil and sports segment premium price realization in Australia. Recalibration cycles align with material shifts in nanomaterial safety documentation and multi-jurisdictional label compliance complexity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Liquid Makeup Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Loose Setting Powder Market