
 Hair Styling Equipment Market | 2026-2036
Hair Styling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Styling Equipment Market Outlook
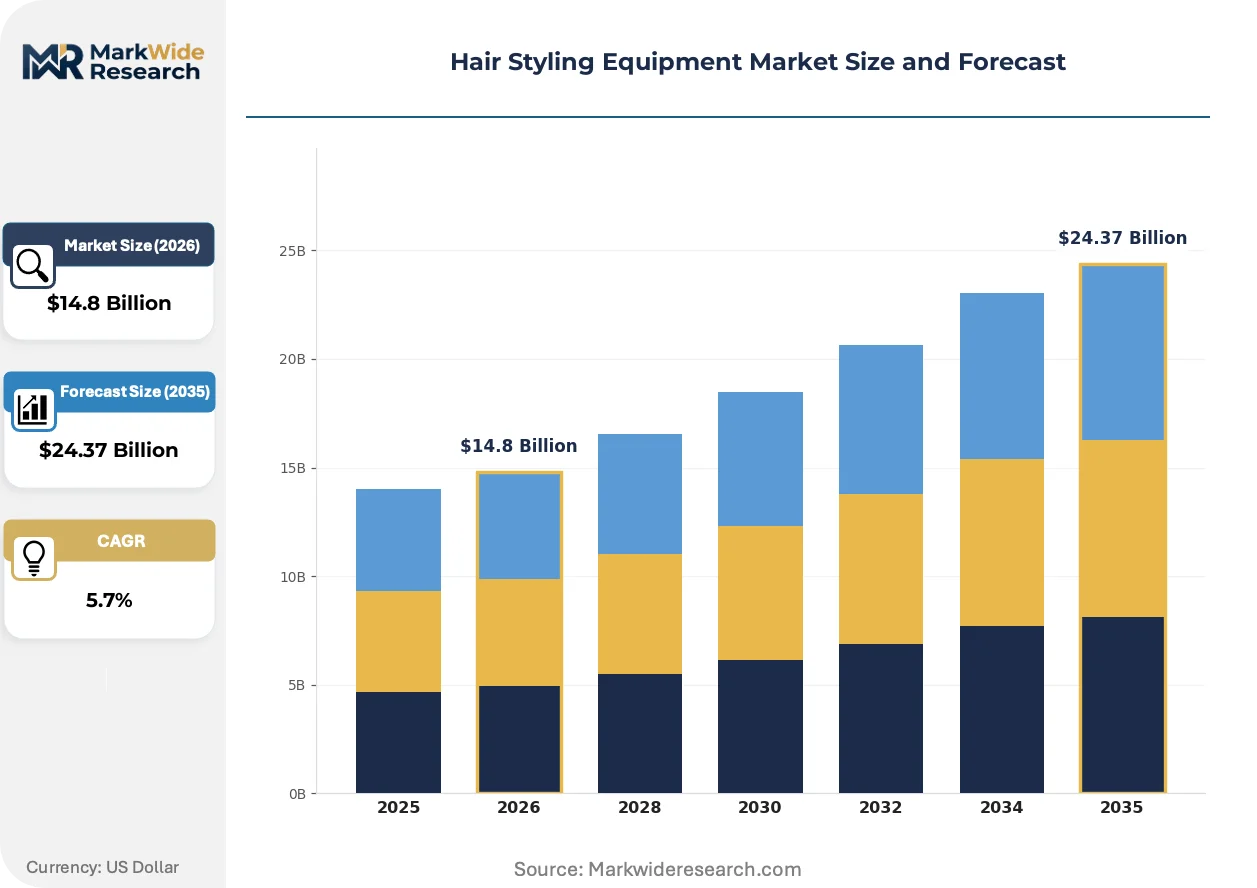
REACH chemical compliance is realigning the cost-of-entry calculus for hair styling equipment manufacturers targeting European distribution. Conair Corporation leverages its North American manufacturing scale to absorb certification costs while sustaining multi-channel dominance. Dyson Ltd anchors its positioning through proprietary motor technology and direct-to-consumer channel control.
Hair styling equipment encompasses electrically powered thermal devices engineered to modify hair texture and shape through controlled heat application, typically operating between 180°C and 230°C with ceramic, tourmaline, or infrared heating elements. These tools serve commercial salon operations and household consumers seeking professional-grade styling outcomes. Hair dryers occupy the largest revenue pool within product type segmentation, while ion technology commands premium positioning across professional channels. Straighteners compete most intensely in the mid-range price tier where brand differentiation weakens and private-label pressure intensifies.
The EU F-Gas Regulation constrains refrigerant-dependent manufacturing processes, while CE marking mandates govern electrical safety standards for devices sold across European member states. The US FDA maintains oversight of claims related to hair treatment efficacy, and the EPA tracks volatile organic compound emissions from coating processes in manufacturing facilities. Stakeholders must monitor evolving chemical disclosure requirements and heating efficiency standards as regulatory fragmentation between jurisdictions deepens compliance complexity.
Market Dynamics
Professional salon chains are consolidating procurement power while demanding connected, sensor-enabled tools that log usage data and enable predictive maintenance contracts, compressing margins for mid-tier manufacturers dependent on undifferentiated ceramic heating platforms.
Growth Catalysts
- Ionic and infrared heating technologies:Tourmaline-coated plates and ceramic infrared elements reduce thermal damage while cutting styling time, driving replacement cycles in premium consumer segments and professional channels.
- REACH chemical compliance:ECHA-mandated substance restrictions are accelerating R&D investment in lead-free solder and halogen-free plastics, creating competitive moats for early-compliant manufacturers accessing European distribution.
- China:Tier-one cities including Shanghai and Shenzhen exhibit deepening penetration of professional-grade tools among affluent households, with salon density per capita approaching German levels in core districts.
Market Restraints
- Copper and rare earth magnet costs:High-performance motor assemblies depend on neodymium and copper windings subject to export restriction volatility and mining concentration in Inner Mongolia.
- Taiwan semiconductor foundry concentration:MCU and power management IC supply for smart styling tools routes through TSMC and UMC, creating single-source vulnerability for temperature control firmware.
- EU F-Gas Regulation:Refrigerant-dependent manufacturing processes for certain coating applications face phase-down schedules constraining production flexibility.
Strategic Opportunities
- India:BIS certification requirements are formalizing quality tiers, creating first-mover advantage for manufacturers establishing local testing partnerships and Hindi-language technical support infrastructure.
- Subscription-based tool access:Professional salons in London and New York are piloting hardware-as-a-service models bundling equipment, maintenance, and stylist training under monthly contracts.
- Dual carbon goals (China):NEEA energy efficiency labeling mandates are accelerating demand for inverter-controlled heating elements that reduce standby power consumption.
Industry Challenges
- Embedded systems engineering talent:Bluetooth connectivity and app ecosystem development require firmware capabilities scarce among traditional appliance engineering teams.
- CE-MDR convergence timelines:Electrical safety and medical device adjacent claims create overlapping certification paths with conflicting documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Styling Equipment Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Curling Irons, Straighteners, Hair Styling Tools End User: Salons, Household Consumers, Professional Stylists, Barbershops Technology: Ion Technology, Ceramic Heating, Infrared Technology, Tourmaline Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Conair Corporation, Dyson Ltd, Koninklijke Philips N.V., Panasonic Corporation, Spectrum Brands Holdings, Helen of Troy Limited, The Procter & Gamble Company, GHD, Revlon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Styling Equipment Market Strategic Shifts
Temperature telemetry and motor control algorithms are converging to enable real-time heat mapping and personalized styling protocols, shifting competitive advantage from hardware specifications to data-enabled service layers.
AI-driven thermal modulation is automating heat distribution across hair strand density variations detected through integrated infrared sensors. Premium salon chains in Seoul and Milan are deploying these systems to standardize outcomes across stylist skill levels. The technology is automating quality consistency that previously required years of manual training, compressing the value of individual stylist expertise.
REACH SVHC disclosure requirements are forcing reformulation of polymer housings and coating chemistries throughout European supply chains. Manufacturers must now maintain substance-level traceability from raw material to finished good. Professional tool lines bearing full material transparency certification command shelf space preference in German and French retail channels.
Direct-to-consumer channel expansion is displacing traditional salon-exclusive distribution for premium heat tool brands. Social commerce platforms and influencer-curated storefronts in Los Angeles and São Paulo now capture significant share of high-ASP purchases. This shift concentrates customer data ownership with manufacturers while fragmenting retail margin pools previously captured by professional supply distributors.
Hair Styling Equipment Market Segmentation
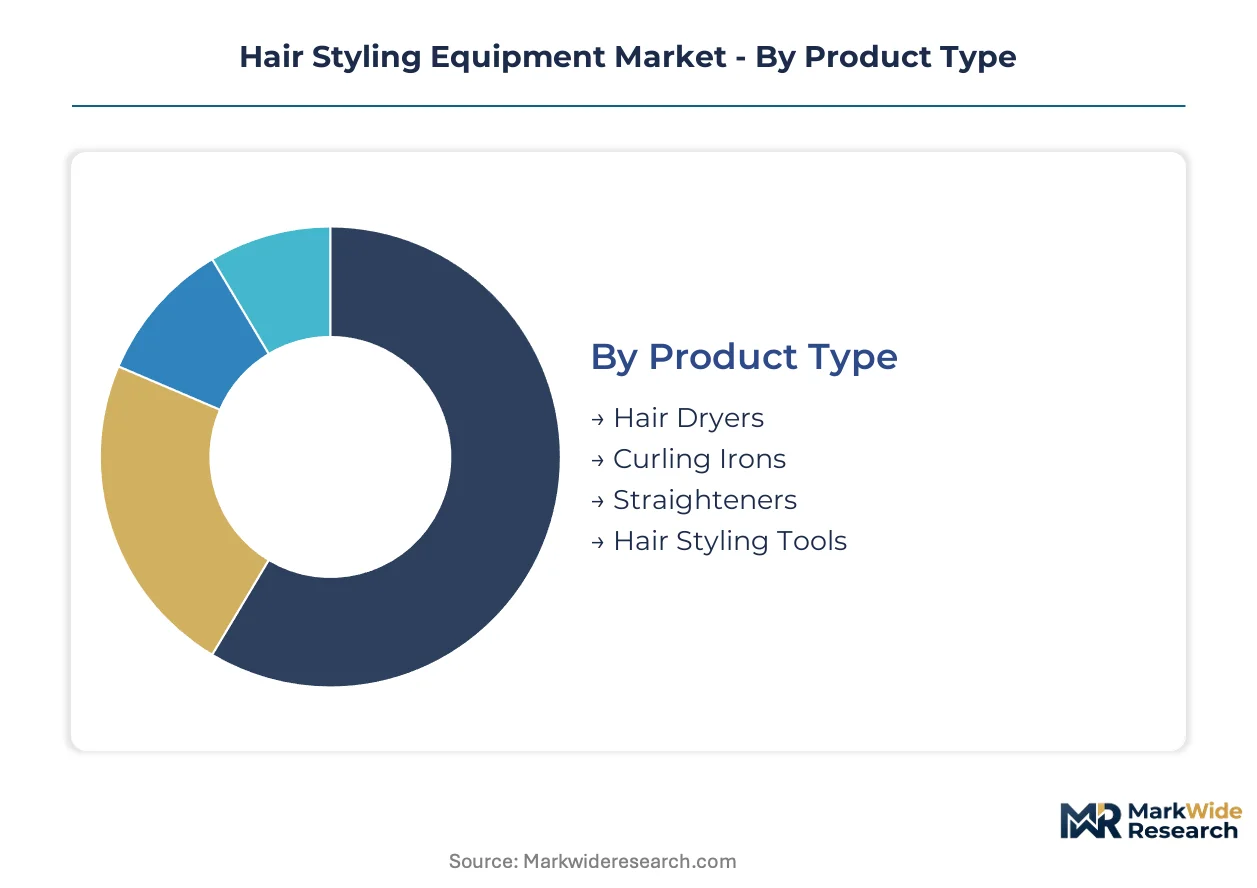
Hair styling equipment segmentation reveals divergent margin structures across thermal technologies and distribution channels. Product type and technology choices determine certification burden, while end-user concentration shapes service attach rates and replacement cycle timing.
Product Type:
Buyers prioritize heat distribution uniformity and motor durability when selecting equipment categories for commercial deployment.
- Hair Dryers:These devices dominate procurement volumes across salon chains and hotel amenity programs. AC motor configurations with ceramic heating elements command preference in German and US professional channels where ECHA-compliant polymer housings are now mandatory.
- Straighteners:Floating plate designs with variable temperature control (120°C–230°C) address diverse hair textures. Demand clusters in China's tier-one cities among affluent households seeking salon-equivalent results, though REACH SVHC disclosure requirements are elevating material costs for European-bound shipments.
- Curling Irons:Barrel diameter selection (19mm–38mm) determines curl formation versatility.
- Hair Styling Tools:Multi-function devices combining drying and styling capabilities.
Volume sits with hair dryers; growth tilts toward straighteners.
End User:
Procurement scale and technical support requirements separate commercial buyers from household purchasers.
- Salons:High-throughput operations demand connected tools with usage logging and predictive maintenance contracts. Sensor-enabled temperature telemetry is gaining traction in Seoul and Milan chains seeking outcome standardization across stylist skill levels.
- Professional Stylists:Independent operators prioritize portability and rapid heat-up times for mobile service delivery.
- Household Consumers:Replacement cycles accelerate where ion technology and ceramic coatings reduce thermal damage perception.
- Barbershops:Beard-specific attachments and precision temperature control address male grooming specialization.
Salons generate the highest per-unit revenue; household consumers expand most quickly.
Technology:
Heating element composition determines energy efficiency ratings and regulatory compliance pathways.
- Ion Technology:Negative ion generators reduce static and cut drying time by breaking water molecule surface tension. Premium positioning in Japanese and South Korean retail channels reflects consumer willingness to pay for frizz reduction claims.
- Ceramic Heating:Aluminum oxide-coated plates distribute heat evenly across hair strands. REACH-mandated lead-free solder requirements are forcing reformulation of heating element assemblies for European market access.
- Infrared Technology:Penetrates hair cuticles with longer wavelength radiation.
- Tourmaline:Crushed mineral coating amplifies ion generation when heated.
Ceramic heating commands current volume leadership; ion technology shows the steepest expansion trajectory.
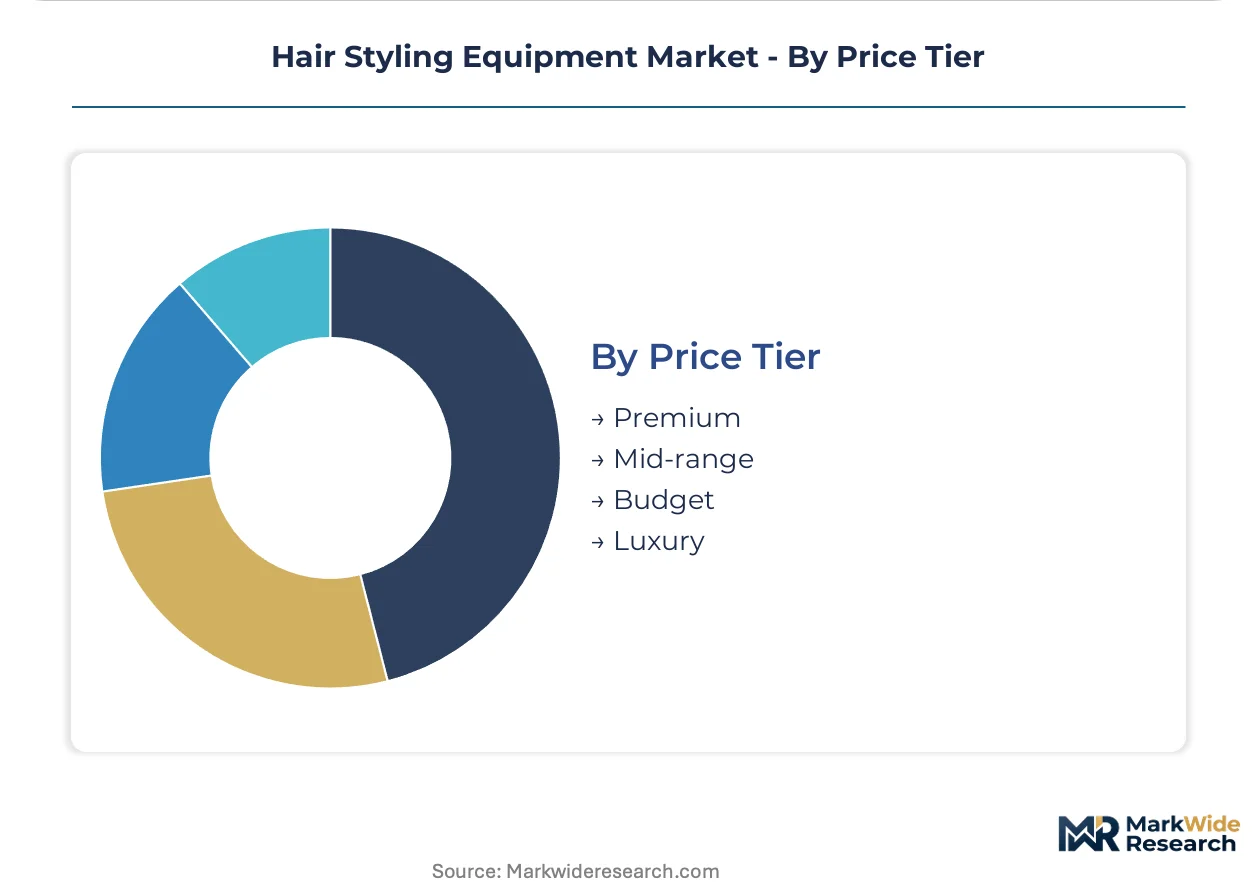
Price Tier:
Distribution channel control and brand equity separate pricing strata more than manufacturing cost differentials.
- Premium:Direct-to-consumer brands with proprietary motor technology and app ecosystem integration. Social commerce platforms in Los Angeles and São Paulo capture significant share of this tier through influencer-curated storefronts.
- Luxury:Limited-edition finishes and concierge service packaging target gift market occasions.
- Mid-range:Private-label pressure intensifies where brand differentiation weakens and ceramic heating platforms commoditize.
- Budget:Basic thermal functionality without advanced coating technologies or connected features.
Premium tier captures margin concentration; mid-range faces the sharpest price compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate contract manufacturing capacity for ceramic heating elements and motor assemblies serving global brands.
United States
Salon chain consolidation in Los Angeles and New York drives procurement of connected tools with predictive maintenance contracts. FDA oversight of hair treatment efficacy claims shapes product labeling requirements. Social commerce platforms in Los Angeles capture significant share of premium heat tool purchases through influencer-curated storefronts.
China
Affluent households in Shanghai and Shenzhen deepen penetration of professional-grade tools as salon density per capita approaches German levels in core districts. NEEA energy efficiency labeling mandates accelerate demand for inverter-controlled heating elements. The Yangtze River Delta manufacturing corridor supplies ceramic heating platforms and motor assemblies for export markets.
Germany
Professional salon chains in Berlin and Munich demand REACH-compliant polymer housings and full material transparency certification. ECHA-mandated substance restrictions elevate R&D investment in lead-free solder and halogen-free plastics. The Rhine-Ruhr industrial region hosts precision tooling suppliers serving premium equipment manufacturers.
India
BIS certification requirements formalize quality tiers as urban households in Mumbai and Delhi upgrade from basic to ionic and ceramic tools. The country's national standards body mandates testing protocols for electrical safety. Manufacturing clusters in Maharashtra and Gujarat establish local testing partnerships and Hindi-language technical support infrastructure.
South Korea
Premium retail channels in Seoul exhibit strong consumer willingness to pay for frizz reduction claims associated with ion technology. The country's national technology regulator oversees electromagnetic compatibility standards for connected devices. AI-driven thermal modulation systems deploy across Seoul salon chains to standardize outcomes across stylist skill levels.
Hair Styling Equipment Market Competitive Environment
United States producers anchor one tier; Asian specialists hold manufacturing scale advantages. The vendor base spans consolidated multi-brand conglomerates and focused single-category innovators. Three archetypes dominate: diversified consumer appliance conglomerates with salon distribution networks, direct-to-consumer challengers with proprietary motor technology, and contract manufacturers supplying private-label programs. M&A activity concentrates brand portfolios under fewer holding companies while strategic partnerships between semiconductor suppliers and tool makers accelerate smart feature integration.
Among diversified appliance conglomerates, Koninklijke Philips N.V. and Panasonic Corporation exemplify scale-driven positioning through broad personal care portfolios and established retail channel access. Dyson Ltd occupies a premium-tier position characterized by proprietary motor technology and direct-to-consumer channel control. These three entities represent distinct competitive vectors: Philips anchors professional salon distribution, Panasonic leverages manufacturing scale across consumer electronics adjacencies, and Dyson exemplifies technology-led premium positioning with vertical integration into motor design.
| Leading Market Players |
|---|
| Conair Corporation |
| Dyson Ltd |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Spectrum Brands Holdings |
| Helen of Troy Limited |
| The Procter & Gamble Company |
| GHD |
| Revlon |
| Others |
Value Chain & Pricing Dynamics
Captive motor manufacturing in Shenzhen and Dongguan anchors both component supply security and premium pricing power for brands controlling proprietary heating element designs. REACH compliance costs in Europe and NEEA labeling mandates in China are forcing tiered cost absorption strategies that separate integrated manufacturers from assembly-dependent competitors.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to professional salon chains in Los Angeles and New York requiring immediate replacement of sensor-enabled tools under predictive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels separates Dyson-grade direct-to-consumer brands from mid-range ceramic platforms and budget thermal devices without connectivity. Cost compression in the mid-range tier is intensifying because private-label programs at Conair and Spectrum Brands are capturing shelf space with undifferentiated heating specifications. Household consumers in China's tier-one cities show least price sensitivity for ion technology claims, while budget-tier buyers in India remain highly elastic to BIS certification cost pass-through.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Shenzhen are elevating automation investment for ceramic heating element assembly lines serving export markets. Manufacturing gravity centers on China for ceramic substrates and motor windings, Taiwan for MCU and power management ICs through TSMC and UMC, and Germany for precision tooling in the Rhine-Ruhr region. Rare earth magnet supply rests on Inner Mongolia mining concentration, copper winding costs, and neodymium export quota volatility. Single-source vulnerability in Taiwan semiconductor foundries threatens temperature control firmware availability for smart styling tools. Distribution runs through professional supply distributors in Berlin and Munich, direct-to-consumer platforms in Los Angeles, and social commerce storefronts in São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH SVHC disclosure requirements and connected-tool R&D investment thresholds is forcing mid-tier ceramic specialists toward exit or acquisition. Margin compression at undifferentiated heating platform manufacturers will accelerate through the projection horizon.
For Market Incumbents: Deepen backward integration into ceramic heating element manufacturing to capture margin otherwise lost to Dongguan contract assemblers. Acquire firmware engineering teams in Seoul or Taipei to close capability gaps in Bluetooth connectivity and app ecosystem development. Defend against direct-to-consumer challengers by locking exclusive salon chain distribution in Berlin and New York through predictive maintenance contract bundling.
For New Entrants and Emerging Players: Begin with BIS certification partnerships in Maharashtra and Gujarat to establish quality-tier credibility before multinational incumbents formalize local testing infrastructure. Target India's tier-two cities where ion technology penetration remains under fifteen percent and Hindi-language technical support creates switching costs. Launch through influencer-curated social commerce storefronts rather than traditional retail to avoid margin capture by professional supply distributors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified personal care conglomerates seeking salon distribution network density. Five-to-ten year viability favors manufacturers with captive motor technology and REACH-compliant material traceability systems already operational. Watch for TSMC capacity allocation announcements affecting MCU availability as the inflection signal for smart tool production bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Traceability | ECHA-mandated SVHC disclosure creates competitive moat for early-compliant manufacturers accessing German retail channels. |
| Predictive Maintenance Contract Bundling | Salon chains in Seoul and Milan standardize outcomes across stylist skill levels through sensor-enabled telemetry integration. |
| Direct-to-Consumer Channel Expansion | Social commerce platforms in Los Angeles and São Paulo fragment retail margin pools previously captured by professional distributors. |
| Firmware Engineering Team Acquisition | Bluetooth connectivity and app ecosystem development require capabilities scarce among traditional appliance engineering teams. |
| NEEA Energy Efficiency Certification | Inverter-controlled heating elements reduce standby power consumption for Shanghai and Shenzhen affluent households. |
Study Parameters
Document review covered SEC filings from Conair Corporation and Helen of Troy Limited, ECHA substance restriction databases, and NEEA energy efficiency labeling records, complemented by interviews with procurement directors at Los Angeles salon chains, Dongguan contract manufacturing executives, and ceramic heating element R&D leads in Shenzhen. Primary fieldwork included discussions with BIS certification specialists in Mumbai, REACH compliance consultants in Berlin, and professional supply distributors in Munich. Secondary validation drew from customs trade data for hair styling equipment imports, FDA hair treatment efficacy claim filings, and EPA volatile organic compound emission tracking for coating processes. Bottom-up product type segmentation triangulated against top-down regional demand aggregation.
Historical shipment data cross-referenced against panel input from salon chain procurement officers and direct-to-consumer brand executives informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, heating technology composition, end-user concentration, and price tier positioning. CAGRs derived from curve-fitting approaches applied to professional salon equipment replacement cycles and household consumer upgrade patterns. Forecast inputs incorporated REACH compliance cost pass-through assumptions and Taiwan semiconductor foundry capacity allocation trends affecting smart tool availability.
Underlying measurement precision varies by segment; professional salon procurement data carries tighter precision than household consumer channel estimates. Forecasts reflect documented assumptions regarding ceramic heating element cost trajectories and ion technology adoption curves. Material deviation in TSMC capacity constraints, Inner Mongolia rare earth export quotas, or ECHA substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Argentina Beauty and Personal Care Products Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
Hair Salon Equipment Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Nail Strengtheners Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Kids Shampoo Market