
 Plant-Based Skincare Products Market | 2026-2036
Plant-Based Skincare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Skincare Products Market Analytics
Clean beauty certification is bifurcating the competitive landscape into premium validated tiers and mass-market claims. True Botanicals leverages third-party clinical testing to sustain its premium positioning. Dr. Hauschka anchors European heritage formulations, while Herbivore Botanicals differentiates through minimalist ingredient transparency.
Plant-based skincare products comprise topical formulations where active and base ingredients derive from botanical sources such as cold-pressed oils, fermented extracts, or bioactive peptides, excluding synthetic petrochemicals and animal-derived components. These formulations serve therapeutic, protective, and aesthetic functions for skin barrier maintenance and cellular regeneration. Moisturizers and serums capture the deepest margin pools due to higher per-unit pricing and repeat purchase frequency. Botanical extracts lead ingredient sourcing as brands emphasize traceable supply chains, while recyclable containers dominate packaging innovation as retailers impose sustainability gatekeeping.
EMA cosmetic ingredient guidelines, EPA chemical disclosure rules, and FDA MoCRA modernization collectively tighten compliance thresholds for cross-border sellers. These frameworks elevate testing costs but simultaneously filter out unsubstantiated natural claims, rewarding brands with verified supply chain documentation. Stakeholders must monitor evolving state-level bans on specific botanical allergens and packaging mandates that could reshape formulation priorities faster than federal harmonization allows.
Market Dynamics
Clean beauty certification requirements are fragmenting competitive tiers, forcing brands to choose between costly third-party validation and unsubstantiated marketing claims. This structural pressure concentrates margin capture among vertically integrated formulators with documented supply chain control.
Growth Catalysts
- Millennial and Gen Z salon channel penetration:Professional spa and aesthetic clinic adoption accelerates trial rates and premium price acceptance for botanical formulations.
- EU REACH ingredient disclosure mandates:Transparency requirements reward brands with pre-existing supply chain documentation, filtering out unsubstantiated natural competitors.
- Fermented bioactive peptide technology:Cold-pressed oil extraction paired with enzymatic processing enhances active compound bioavailability in topical applications.
Market Restraints
- Botanical raw material price volatility:Climate-sensitive crop yields for shea, marula, and bakuchiol create margin compression for non-integrated formulators.
- Single-origin supply concentration:Madagascar vanilla and Moroccan argan dependencies expose brands to geopolitical and weather-related disruption.
- Photostability limitations:Unencapsulated plant-derived retinol alternatives degrade faster than synthetic counterparts, requiring complex stabilization chemistry.
Strategic Opportunities
- South Korean regulatory fast-track:MFDS streamlined cosmetic approval pathways for documented clean formulations reduce time-to-market for validated entrants.
- Waterless solid format expansion:Concentrated balm and bar formats eliminate preservative requirements and align with zero-waste retail mandates.
- Biotechnology-synthetic biology convergence:Lab-cultured botanical actives from Ginkgo Bioworks-style platforms decouple supply from agricultural constraints.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient instability and performance benchmarks commands premium compensation.
- Multi-certification compliance timelines:Simultaneous pursuit of COSMOS, Leaping Bunny, and B Corp standards extends product development cycles.
- Legacy ERP integration friction:Batch-level ingredient traceability requirements strain existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Skincare Products Market |
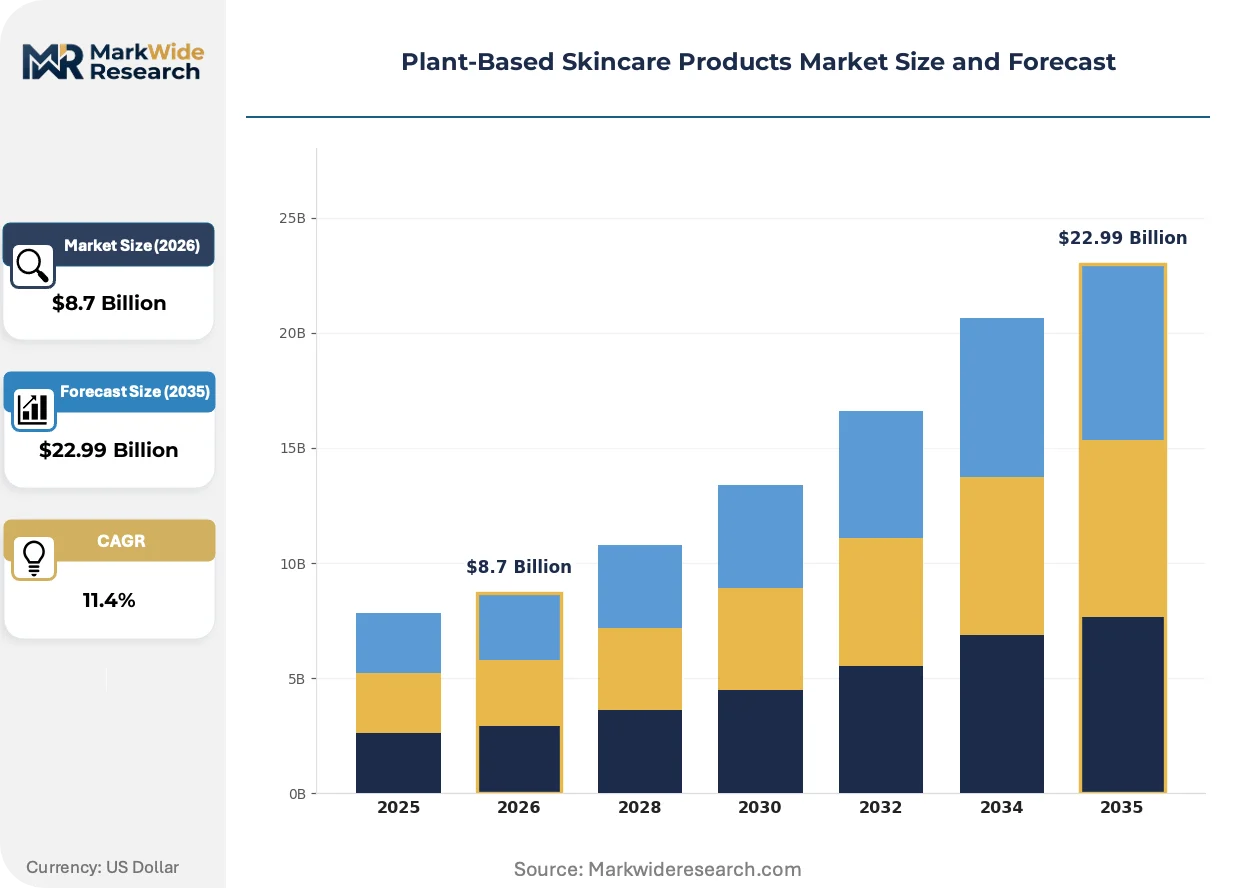
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Serums, Masks Ingredient Source: Botanical Extracts, Oils, Peptides, Clay Target Consumer: Vegans, Eco-Conscious Buyers, Health Enthusiasts, Sensitive Skin Users Packaging Type: Recyclable Containers, Biodegradable Tubes, Glass Bottles, Eco-Friendly Jars |
| Companies Covered | True Botanicals, Dr. Hauschka, Herbivore Botanicals, Annmarie Skin Care, Melvita, OSEA Malibu, Pai Skincare, Mukti Organics, Weleda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Skincare Products Market Evolving Landscape
Biotechnology is collapsing the cost-performance tradeoff that historically separated synthetic and plant-derived actives. Formulators now access clinically equivalent botanical alternatives through precision fermentation and cellular agriculture platforms.
Encapsulation technology is miniaturizing lipid nanoparticle delivery systems for unstable polyphenols and carotenoids. Prestige dermatology clinics in Seoul and New York are adopting these formats for in-office protocols. The compression of efficacy gaps between natural and synthetic retinoids is forcing incumbent brands to reformulate or lose clinical credibility.
MoCRA modernization in the United States now mandates facility registration and adverse event reporting for all cosmetic manufacturers. The FDA's expanded inspection authority elevates compliance costs for cross-border sellers. Small-batch indie brands without quality management systems face exit pressure, consolidating shelf space for documented operators.
Subscription-based replenishment models are displacing traditional retail discovery for core skincare routines. Direct-to-consumer channels in France and California capture recurring revenue through personalized botanical regimen algorithms. Professional spa accounts increasingly demand white-label manufacturing partnerships rather than branded resale arrangements.
Plant-Based Skincare Products Market Segmentation
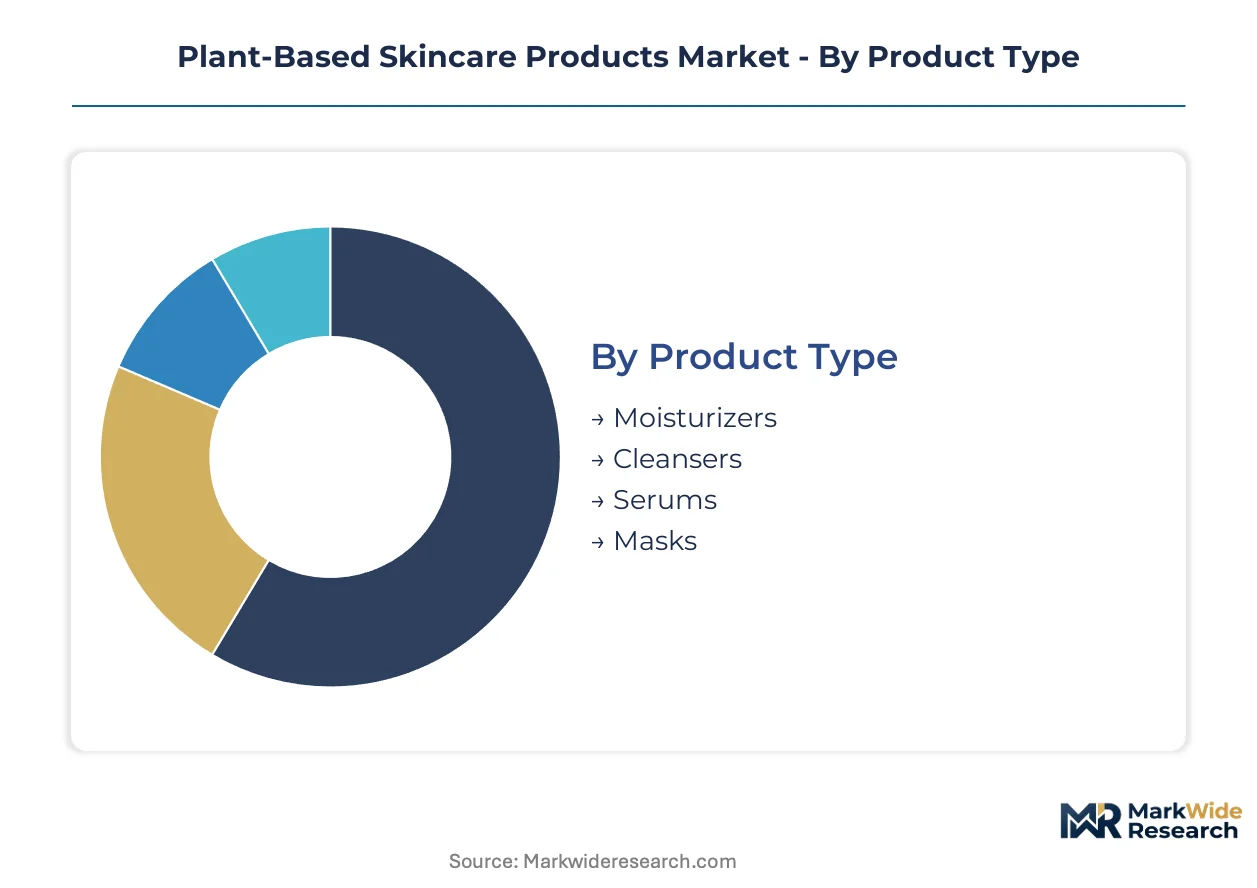
Plant-based skincare segmentation reveals distinct supply chain configurations and margin structures across product formats and consumer cohorts. Understanding these divides enables targeted positioning for professional salon channels versus mass retail penetration.
Product Type:
Domestic production dominates moisturizers and cleansers for local market speed, while serums and masks flow through export-led supply chains serving premium spa networks in France and South Korea.
- Moisturizers:Emulsion-based formulations combining cold-pressed oils with humectant botanicals deliver barrier repair functions. Demand concentrates in professional aesthetic clinics across California and New York where repeat purchase cycles sustain subscription revenue models. EU REACH documentation requirements favor established formulators with verified supply chains.
- Serums:High-concentration aqueous solutions featuring fermented bioactive peptides target cellular regeneration protocols. South Korean MFDS fast-track approvals accelerate time-to-market for documented clean formulations entering Seoul dermatology clinics. Waterless concentrated formats reduce preservative loads and align with zero-waste mandates.
- Cleansers:Surfactant-free oil and balm formats dissolve impurities without stripping lipid barriers.
- Masks:Sheet and clay formats deliver intensive treatment protocols through occlusive delivery mechanisms.
Moisturizers hold the largest share; momentum sits with serums.
Ingredient Source:
Cost tier stratification separates commodity botanicals from precision-fermented actives commanding formulation premiums in clinical-grade products.
- Botanical Extracts:Cold-pressed and solvent-extracted compounds from shea, marula, and bakuchiol provide antioxidant and anti-inflammatory properties. Single-origin dependencies in Madagascar and Morocco expose supply chains to climate and geopolitical disruption, compressing margins for non-integrated brands.
- Oils:Carrier and essential oil fractions deliver emollient and aromatic functions through lipophilic delivery systems.
- Peptides:Enzymatically processed protein fragments signal collagen synthesis pathways in topical applications.
- Clay:Mineral-rich sedimentary deposits provide adsorptive cleansing and sebum regulation in mask formulations.
Botanical extracts anchor volume; peptides are climbing the fastest on biotechnology cost curves.
Target Consumer:
Application intensity varies by consumer archetype, with health enthusiasts driving daily regimen adherence while sensitive skin users restrict usage to hypoallergenic certified lines.
- Vegans:Formulations excluding all animal-derived inputs including honey, beeswax, and lanolin analogs. Demand clusters in urban coastal markets across France and California where ethical consumption correlates with premium price acceptance.
- Eco-Conscious Buyers:Consumers prioritizing carbon footprint reduction and packaging circularity over ingredient provenance alone.
- Health Enthusiasts:Wellness-integrated buyers seeking functional skin health outcomes through microbiome-supporting formulations.
- Sensitive Skin Users:Reactive skin cohorts requiring fragrance-free, minimal-ingredient protocols with documented allergen screening.
Eco-conscious buyers hold the largest share; vegans are gaining share fastest on certification differentiation.
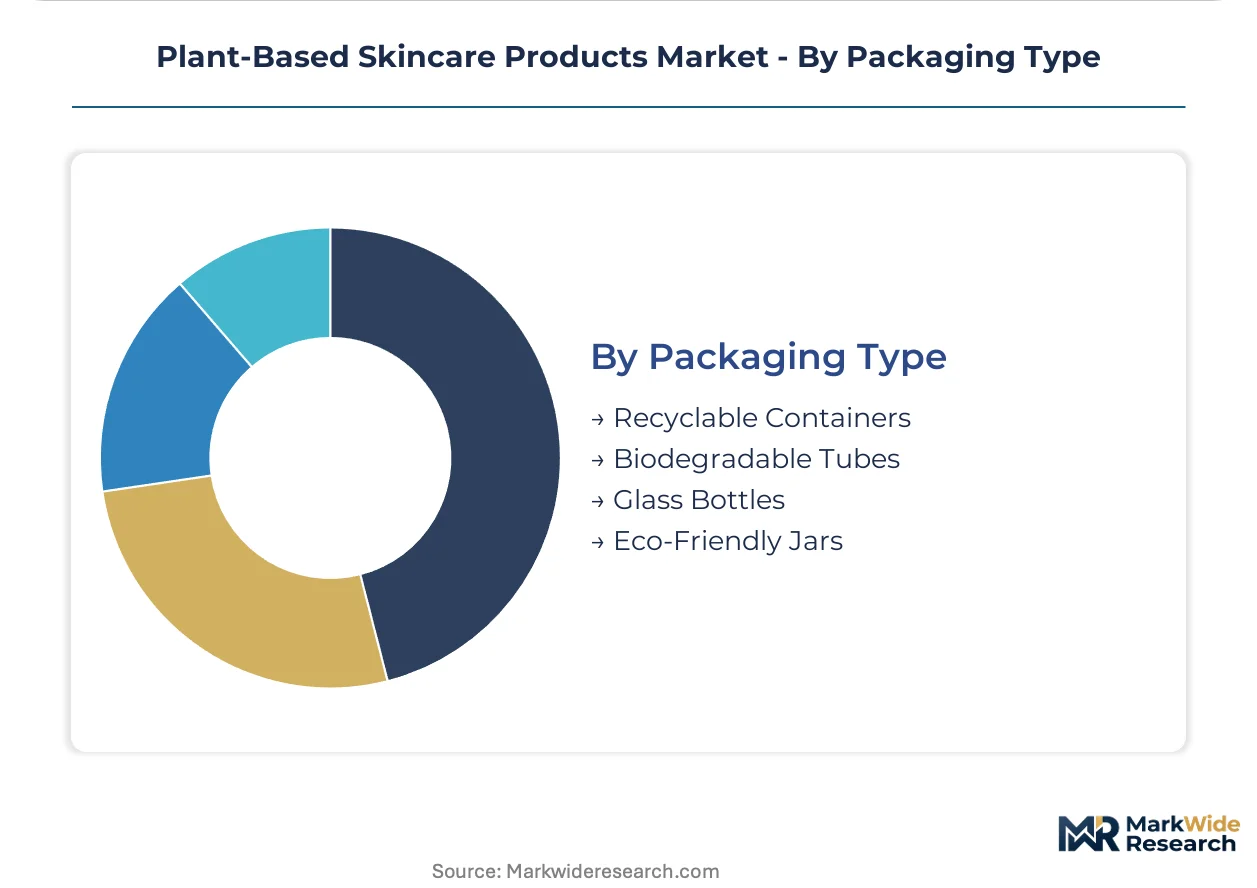
Packaging Type:
Customer type separation distinguishes refill-focused subscription users from single-purchase retail buyers prioritizing shelf aesthetics.
- Recyclable Containers:Post-consumer recycled plastic and aluminum formats meeting retailer sustainability gatekeeping requirements. French and German retailers now mandate minimum recycled content thresholds, filtering out virgin packaging suppliers.
- Biodegradable Tubes:Polylactic acid and cellulose-based flexible packaging engineered for industrial composting streams.
- Glass Bottles:Inert borosilicate and amber glass providing photostability for oxidation-sensitive actives.
- Eco-Friendly Jars:Reusable and refillable rigid containers supporting closed-loop retail partnerships.
Recyclable containers hold the largest share; glass bottles show steepest expansion trajectory on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation expertise and clean beauty certification infrastructure concentrate supply-side capabilities in France, South Korea, and the United States. These three markets anchor distinct competitive advantages spanning heritage botanical science, biotechnology-enabled fermentation, and direct-to-consumer subscription scale.
France
Paris and Provence-Alps-Côte d'Azur host legacy botanical formulators serving EU REACH-compliant professional spa channels. ANSM cosmetic safety guidelines enforce stringent allergen screening for sensitive skin lines. L'Occitane-en-Provence and Grasse perfume clusters supply cold-pressed oil extraction infrastructure to premium domestic brands.
South Korea
Seoul Capital Area dermatology clinics drive fermented bioactive peptide adoption through MFDS fast-track approval pathways. K-beauty export licensing rewards documented clean formulation supply chains. Busan-Ulsan biotechnology corridors cultivate precision fermentation platforms for lab-cultured botanical actives.
United States
California and New York metro areas concentrate Millennial and Gen Z subscription revenue for moisturizers and serums. FDA MoCRA modernization mandates facility registration and adverse event reporting. Los Angeles-based formulators integrate white-label manufacturing partnerships with professional spa accounts.
Germany
Bavaria and Baden-Württemberg anchor European heritage formulation science through NATRUE and COSMOS certification bodies. ECHA REACH enforcement filters unsubstantiated natural claims from cross-border sellers. Frankfurt-Rhine-Main logistics hubs enable batch-level ingredient traceability for recyclable packaging mandates.
Australia
Sydney and Melbourne coastal markets correlate vegan certification with premium price acceptance among ethical consumption cohorts. TGA cosmetic ingredient guidelines align with ISO 16128 natural origin standards. Byron Bay and Noosa clusters specialize in waterless solid format balms for zero-waste retail partnerships.
Plant-Based Skincare Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the plant-based skincare landscape. Premium validated tiers concentrate among vertically integrated formulators with documented supply chain control, while mass-market claimants struggle under multi-certification compliance timelines. Three archetypes dominate: heritage European houses with cold-pressed oil extraction infrastructure, biotechnology-enabled fermentation specialists, and direct-to-consumer subscription operators with personalized regimen algorithms. Competitive intensity manifests through strategic partnerships with professional spa networks and portfolio diversification into waterless solid formats.
Within the heritage formulation tier, Dr. Hauschka and Weleda exemplify European botanical science anchoring, while True Botanicals occupies a position representing third-party clinical testing validation for premium positioning. Herbivore Botanicals sits within the minimalist ingredient transparency archetype, demonstrating how supply chain documentation serves as competitive moat under tightening EPA and FDA disclosure frameworks. These three players collectively illustrate how certification differentiation separates margin-capturing tiers from unsubstantiated claimants.
| Leading Market Players |
|---|
| True Botanicals |
| Dr. Hauschka |
| Herbivore Botanicals |
| Annmarie Skin Care |
| Melvita |
| OSEA Malibu |
| Pai Skincare |
| Mukti Organics |
| Weleda |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Moroccan argan cooperatives and Madagascar vanilla estates lock in multi-year price visibility for premium tier formulators while insulating them from spot market volatility that compresses mass-market margins. These contractual structures simultaneously guarantee supply access for EU REACH-compliant documentation and anchor cost predictability for subscription-based replenishment models in California and New York.
Pricing Analysis
EU REACH and FDA MoCRA dictate the pricing tier structure by elevating compliance costs that filter out unsubstantiated natural claimants. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated botanicals with third-party testing from mass-market alternatives. Price differentiation hinges on certification grade and supply chain documentation depth. Cost compression in the standard tier is intensifying because climate-sensitive crop yields for shea and bakuchiol squeeze non-integrated formulators. Eco-conscious buyers in professional spa channels show least price sensitivity, while mass retail consumers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Inventory buffers for cold-pressed oils and fermented extracts extend lead times to 16-24 weeks, forcing working capital intensity that favors scaled operators. Geographic concentration centers on Morocco for argan, Madagascar for vanilla, and South Korea for bioactive peptide fermentation infrastructure. Raw material dependencies rest on shea butter from West Africa, marula oil from Southern Africa, and lab-cultured actives from Busan-Ulsan biotechnology corridors. Single-origin supply concentration creates vulnerability to geopolitical disruption and weather-related crop failure. Distribution runs through professional spa networks in France and Seoul, direct-to-consumer subscription platforms in California, and white-label manufacturing partnerships with aesthetic clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based skincare functions as a service-attach business where personalized regimen algorithms and subscription replenishment layers expand faster than individual product sales. Recurring revenue from algorithm-driven botanical protocols captures lifetime value beyond transactional retail margins.
For Market Incumbents: Secure backward integration into cold-pressed oil extraction infrastructure in Provence-Alps-Côte d'Azur and Grasse clusters to defend against biotechnology-enabled fermentation specialists eroding heritage positioning. Lock in COSMOS and B Corp certification moats before multi-compliance timelines extend product development cycles for challengers. Control professional spa channel relationships through white-label manufacturing partnerships rather than branded resale arrangements. For New Entrants and Emerging Players: Differentiate on waterless solid format innovation targeting zero-waste retail mandates in German and French markets where virgin packaging suppliers face exclusion. Target the sensitive skin user segment with fragrance-free, minimal-ingredient protocols where documented allergen screening commands premium pricing and incumbent reformulation lags. Pursue South Korean MFDS fast-track pathways for fermented bioactive peptide formulations entering Seoul dermatology clinics. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated formulators with documented supply chain control and existing clean beauty certifications that filter out unsubstantiated competitors. Long-term viability across the projection horizon favors biotechnology-enabled fermentation specialists decoupling from agricultural constraints through lab-cultured actives. Watch for inflection when encapsulated lipid nanoparticle delivery systems achieve cost parity with synthetic stabilization chemistry in prestige dermatology protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Beauty Certification Investment | COSMOS and B Corp validation filters unsubstantiated competitors from EU and US retail shelf space. |
| Biotechnology Platform Partnership | Precision fermentation agreements with Busan-Ulsan corridors decouple supply from Madagascar and Moroccan crop volatility. |
| Professional Spa Channel Integration | White-label manufacturing partnerships with Seoul and New York aesthetic clinics displace traditional branded resale. |
| Waterless Format Expansion | Concentrated balm and bar formats eliminate preservative requirements and satisfy German retailer sustainability gatekeeping. |
| Subscription Algorithm Development | Personalized botanical regimen platforms in California and France capture recurring revenue beyond transactional discovery. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulators, professional spa procurement directors, regulatory affairs specialists at clean beauty certifiers, and biotechnology platform engineers, then refined through secondary validation. Primary interviews captured supply chain documentation practices, certification compliance timelines, and encapsulation technology adoption curves. Secondary sources included EU REACH registration databases, FDA MoCRA facility registration filings, MFDS cosmetic approval records, and ANSM allergen screening guidelines. Bottom-up volume builds triangulated against top-down spending estimates from professional aesthetic clinic networks and direct-to-consumer subscription platforms.
Variance decomposition across the modeling period isolates drivers by product format, ingredient source technology tier, target consumer archetype, and packaging sustainability grade. Segmentation dimensions span moisturizers versus serums versus waterless formats, cold-pressed extracts versus precision-fermented actives, vegan versus eco-conscious versus sensitive skin positioning, and recyclable versus biodegradable versus glass packaging. CAGRs were derived from growth rate reconciliation between historical trajectory analysis and forward-looking adoption curve modeling. Industry-specific inputs include professional spa channel penetration rates and biotechnology cost curve trajectories for lab-cultured botanicals.
Material uncertainties — regulatory harmonization delays, state-level botanical allergen bans, and climate-induced crop yield disruption — sit outside the modeled envelope. Forecasts reflect assumptions about certification adoption timelines and subscription platform scaling efficiency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Hand Soap in Retail Market