
 Spray Tanning Market | 2026-2036
Spray Tanning Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Tanning Market Analysis
EU REACH restrictions on synthetic UV filters is shifting formulation strategies across the spray tanning supply chain. St. Tropez leverages its prestige brand architecture to command premium shelf placement in professional channels. Bondi Sands competes through aggressive digital-native marketing and beach-lifestyle positioning. Norvell Sunless anchors its business model on equipment-plus-solution bundling for salon operators.
Spray tanning applies dihydroxyacetone (DHA) in mist or aerosol form to temporarily darken epidermal keratinocytes without melanin production or UV exposure. The process typically employs 3-12% DHA concentration with erythrulose added to extend color longevity and reduce orange undertones. Self-tan mousse dominates retail velocity due to predictable application and lower mess profile, while spray solution commands the professional margin pool through recurring salon purchases. Mobile services represent the fastest-expanding application channel as post-pandemic consumers prioritize convenience and privacy.
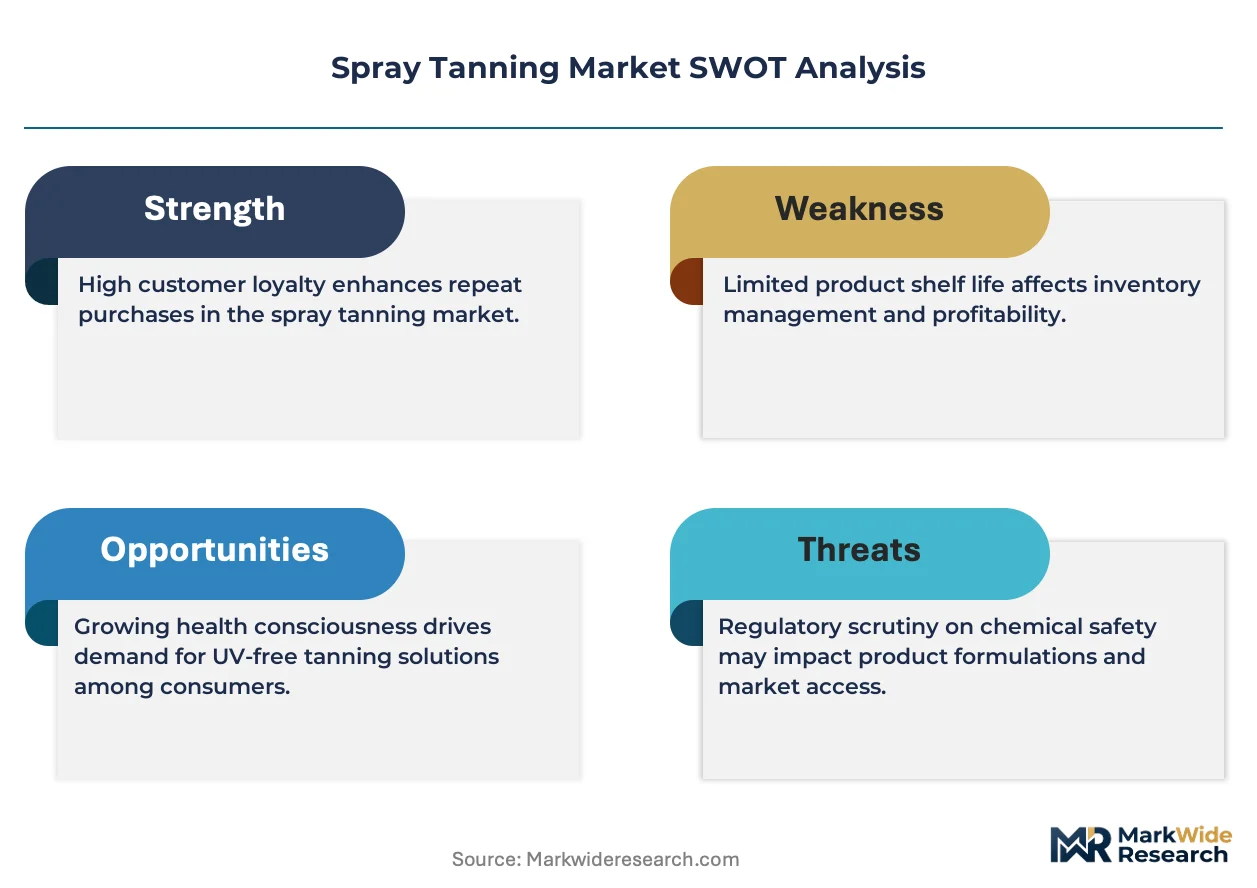
FDA oversight of DHA concentration limits and inhalation exposure warnings shapes product labeling and booth ventilation requirements in the United States. The EU Cosmetics Regulation and ECHA substance evaluations impose additional formulation disclosure and nanomaterial restrictions for aerosol variants. Australia's TGA and state-level cosmetic safety offices enforce parallel standards that affect import eligibility. Stakeholders must monitor evolving inhalation toxicity studies and potential reclassification of DHA as a respiratory sensitizer across multiple jurisdictions.
Market Dynamics
EU REACH restrictions on synthetic UV filters are forcing wholesale reformulation across the spray tanning supply chain, redirecting R&D investment toward dihydroxyacetone-based alternatives and compressing margins for legacy aerosol manufacturers.
Growth Catalysts
- REACH compliance migration:EU restrictions on oxybenzone and octinoxate are accelerating DHA adoption as the sole approved tanning active, creating formulation standardization across export markets.
- Mobile service infrastructure:Post-pandemic privacy preferences are driving capital deployment into van-based and at-home service models, bypassing fixed-location overhead.
- Brazilian aesthetic culture:Year-round beach exposure norms in Rio de Janeiro and São Paulo sustain baseline demand for cosmetic bronzing regardless of seasonal variation.
Market Restraints
- DHA supply concentration:Three specialty chemical manufacturers control pharmaceutical-grade dihydroxyacetone production, creating input vulnerability for mid-tier formulators.
- FDA inhalation exposure thresholds:Ventilation and labeling requirements for booth-based application impose fixed compliance costs that disadvantage smaller salon operators.
- Natural sun exposure substitution:Warm-climate retirement migration to Florida, Arizona, and coastal Spain reduces addressable demand among affluent demographic cohorts.
Strategic Opportunities
- Men's grooming penetration:Under-15% male usage rates in the United States, Australia, and United Kingdom represent expansion headroom through fitness and wellness channel positioning.
- Erythrulose-DHA hybrid development:Converging sugar-derived actives with amino acid stabilizers enables 7-10 day color persistence, commanding premium pricing in professional channels.
- Med-spa integration:Dermatology and cosmetic surgery practices in Beverly Hills, Miami, and London are bundling spray tanning with laser and injectable services.
Industry Challenges
- Certified technician scarcity:State-level cosmetology licensing in California, New York, and Texas requires 300-600 training hours, constraining mobile service scaling.
- Booth capex depreciation cycles:HVLP turbine and extraction system replacement every 4-5 years pressures independent salon cash flows.
- Inhalation toxicity study monitoring:Pending ECHA respiratory sensitizer reclassification of DHA creates regulatory overhang for aerosol product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Tanning Market |
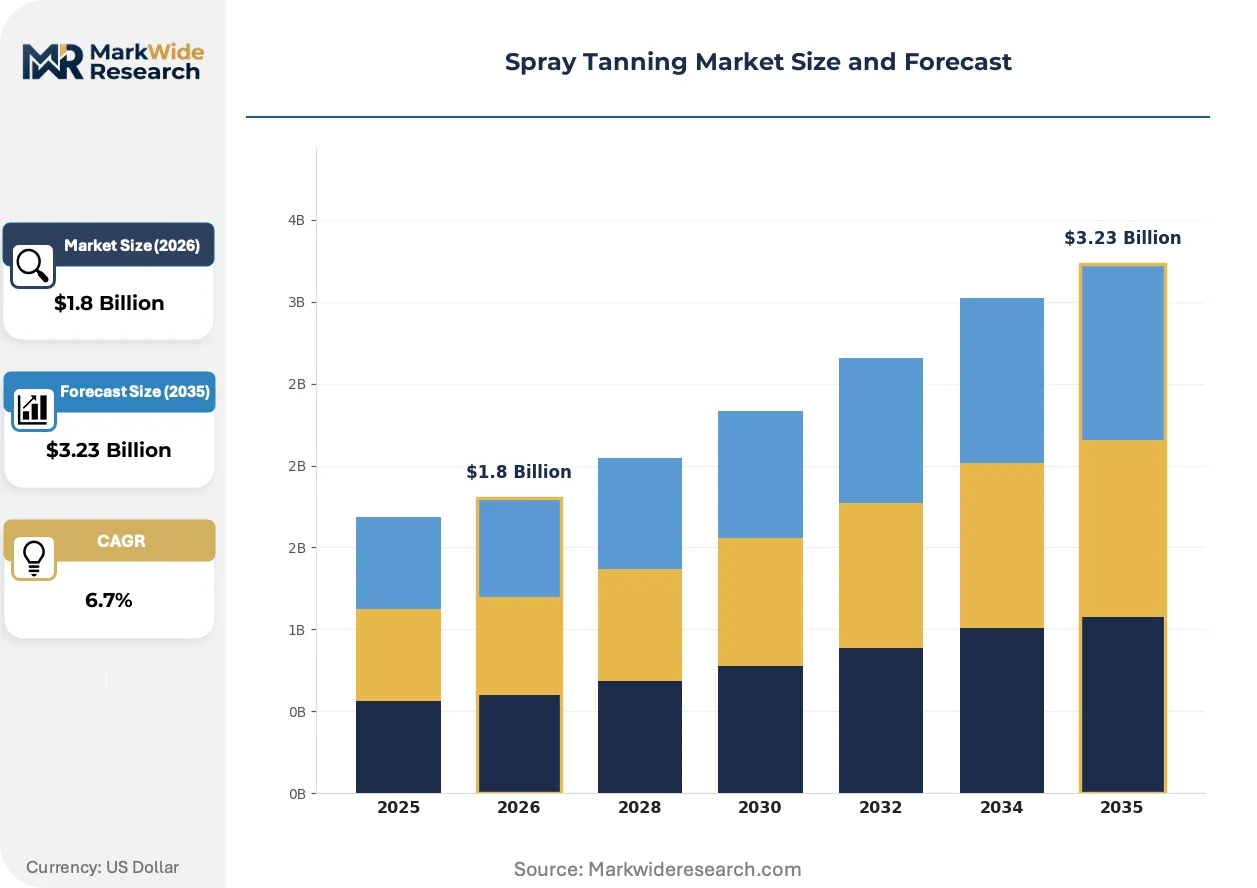
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tanner, Instant Tanner, Self-Tan Mousse, Spray Solution Application: Salons, At-Home Use, Mobile Services, Spas Formulation: Aerosol, Lotion, Gel, Cream Consumer Segment: Women, Men, Teens, Professionals |
| Companies Covered | Sunless Inc, Million Dollar Tan, St. Tropez, Norvell Sunless, GloBody, Bondi Sands, Aviva Labs, Sjolie Inc, Fake Bake, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Tanning Market Emerging Trajectories
Formulation chemistry, service delivery architecture, and regulatory disclosure requirements are simultaneously evolving, compressing product development cycles and rewarding agile supply chain configuration.
Micro-mist application technology is converging with precision dosing systems to reduce overspray waste and improve transfer efficiency in professional settings. High-volume salon operators in Melbourne and Los Angeles are retrofitting legacy turbines with ceramic atomization nozzles. This convergence is compressing per-service product cost and enabling subscription-based solution procurement models.
ECHA substance evaluation protocols are mandating expanded safety data sheet disclosure for aerosolized DHA formulations above 10% concentration. Manufacturers serving EU professional channels must now submit chronic inhalation studies and nanomaterial characterization. Booth operators in Germany and France are responding by migrating toward lotion-based hand-application services to sidestep aerosol classification thresholds.
Subscription pre-booking platforms are displacing walk-in appointment economics across premium salon segments. Urban consumers in Sydney, Chicago, and São Paulo now expect same-day mobile dispatch through app-based scheduling. This behavioral shift is most visible among millennial and Gen-Z demographics, where package commitment rates exceed 60% versus 25% for unplanned salon visits.
Spray Tanning Market Segmentation
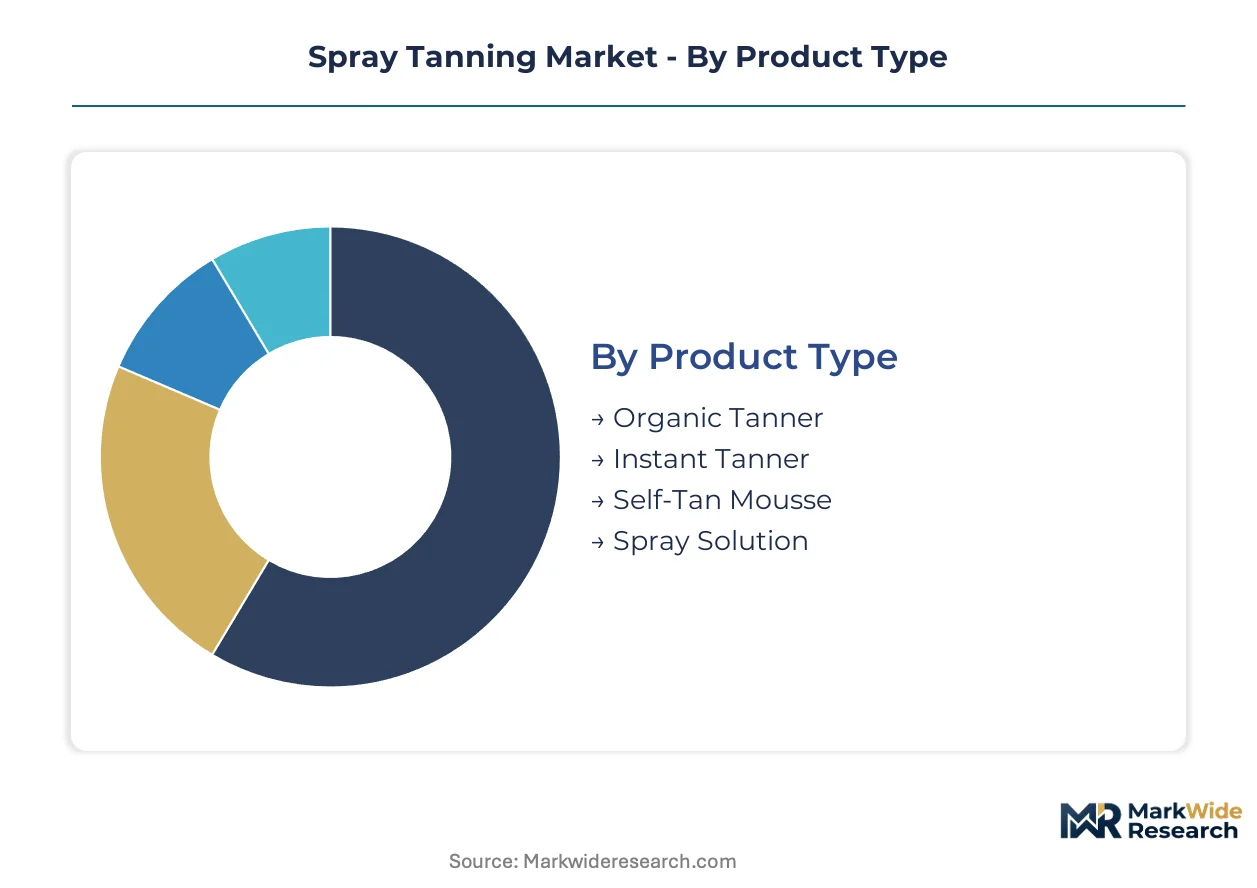
Segmentation in spray tanning reveals divergent margin structures across product formats and service delivery modes. DHA concentration, application setting, and consumer willingness to pay for convenience determine profitability tiers.
Product Type:
Volume concentrates in mass-market formulations while premium pricing attaches to certified organic positioning and professional-grade solutions.
- Spray Solution:Professional-grade DHA formulations at 8-12% concentration dominate recurring revenue pools in salon channels. Brazilian and Australian operators favor bulk concentrate procurement to reduce per-service cost.
- Self-Tan Mousse:Predictable application and controlled dosing drive retail velocity through e-commerce and pharmacy chains. UK and US consumers favor this format for at-home convenience without equipment investment.
- Organic Tanner:Plant-derived DHA sources and certified clean-label positioning command shelf space in premium beauty retail.
- Instant Tanner:Wash-off cosmetic bronzers serve event-driven demand with zero DHA commitment.
Mature deployment sits with Spray Solution. Newer deployment is concentrated in Organic Tanner.
Application:
Fixed-location overhead versus variable-cost mobility defines competitive economics across service delivery architectures.
- Mobile Services:Van-based operations eliminate lease burden while capturing privacy-premium pricing in affluent suburbs. Post-pandemic booking platforms in Sydney and Los Angeles enable same-day dispatch economics.
- Salons:Booth-based HVLP turbine systems generate recurring solution purchases and membership lock-in. California and Texas licensing requirements constrain technician supply.
- Spas:Bundled wellness positioning attaches spray tanning to massage and facial services in resort and urban luxury segments.
- At-Home Use:Direct-to-consumer retail bypasses service labor entirely, capturing cost-sensitive demand through pharmacy and mass-market channels.
Volume leadership resides with Salons. Steepest expansion trajectory belongs to Mobile Services.
Formulation:
Regulatory classification of aerosol exposure thresholds is redirecting R&D investment toward non-atomized delivery systems.
- Aerosol:Pressurized DHA mist enables rapid full-body coverage in commercial booth settings. ECHA inhalation toxicity evaluations in Germany and France are triggering migration toward alternative formats.
- Lotion:Hand-application services sidestep aerosol classification while extending color longevity through slower DHA absorption kinetics.
- Gel:Clear-drying formulations reduce transfer staining on clothing and bedding in overnight development protocols.
- Cream:Rich emollient bases target dry-skin demographics with added moisturizing actives.
Established share clusters in Aerosol. Emerging preference concentrates in Lotion.
Consumer Segment:
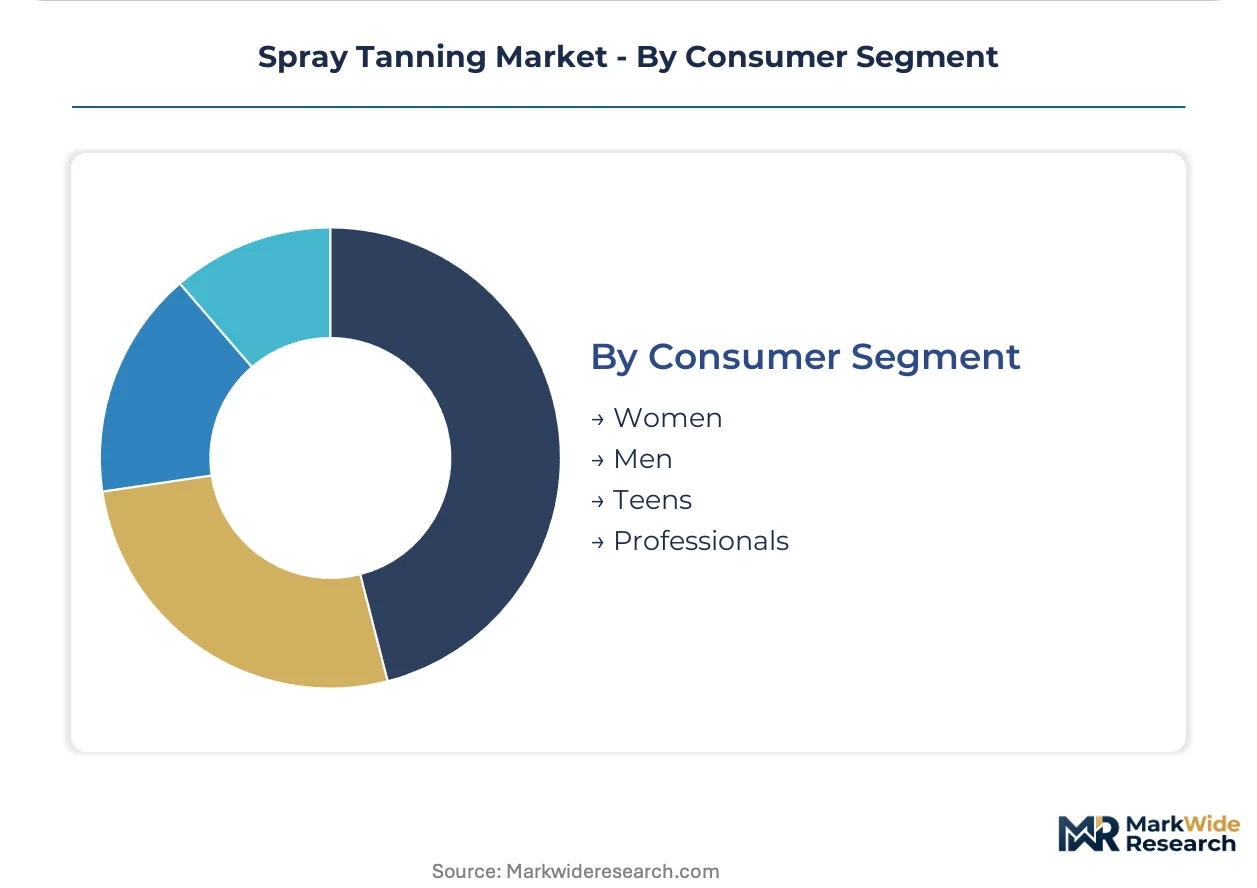
Gender-based usage gaps and life-stage occasionality create divergent targeting strategies for acquisition spend.
- Women:Core demographic sustaining baseline demand across all product and service formats. Brazilian beach culture and Australian outdoor lifestyle normalize year-round maintenance behavior.
- Men:Under-15% penetration in US, UK, and Australian markets represents expansion headroom through fitness and grooming channel positioning.
- Teens:Prom and event-driven occasionality concentrates demand in seasonal peaks with parental purchasing involvement.
- Professionals:On-camera and client-facing occupations sustain premium service subscriptions in urban centers.
Revenue concentration rests with Women. Fastest share gains are emerging in Men.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the professional spray tanning infrastructure through its dense concentration of celebrity-facing salons and equipment manufacturers. The metropolitan corridor generates disproportionate influence on formulation trends and service standards that propagate to secondary markets.
United States
FDA ventilation requirements and DHA concentration labeling rules shape booth-based operations in California, Texas, and Florida. State-level cosmetology licensing mandates 300-600 training hours, constraining technician supply in New York and Texas. Miami and Beverly Hills med-spa clusters bundle spray tanning with cosmetic dermatology services.
Brazil
Year-round beach culture in Rio de Janeiro and São Paulo sustains baseline demand regardless of seasonal variation. ANVISA cosmetic safety standards govern DHA formulation imports and professional service protocols. São Paulo's upscale salon districts drive premium solution procurement from international suppliers.
Australia
TGA oversight parallels FDA standards with additional state-level cosmetic safety enforcement in New South Wales and Victoria. Sydney and Melbourne mobile service platforms capture privacy-premium pricing through same-day dispatch apps. Queensland's coastal retirement corridors sustain maintenance-oriented subscription behavior.
Germany
ECHA substance evaluations and REACH compliance protocols mandate expanded safety data sheet disclosure for aerosolized DHA above 10% concentration. Berlin and Munich salon operators migrate toward lotion-based hand-application to sidestep aerosol classification thresholds. The country's pharmaceutical-grade chemical manufacturing base supplies DHA inputs to European formulators.
United Kingdom
MHRA and Trading Standards enforcement aligns with EU Cosmetics Regulation post-Brexit transition periods. London's premium beauty retail channels command shelf space for certified organic positioning variants. Self-tan mousse dominates at-home consumption through pharmacy and e-commerce velocity.
Spray Tanning Market Vendor Landscape
Premium-margin players sit above commodity-margin players across brand architecture and distribution channel depth. The vendor base clusters into three tiers: prestige lifestyle brands, equipment-plus-solution bundlers, and private-label commodity suppliers. Strategic archetypes include digital-native beach-lifestyle marketers, professional-channel equipment anchors, and clean-label organic specialists. Dominant competitive moves encompass subscription-based solution procurement models and med-spa service bundling partnerships.
Within the prestige tier, St. Tropez and Bondi Sands exemplify divergent path-to-market strategies. St. Tropez occupies a position anchored on professional salon placement and celebrity endorsement architecture. Bondi Sands represents the digital-native archetype through beach-lifestyle positioning and aggressive social-native customer acquisition. Norvell Sunless anchors the equipment-plus-solution bundling model for salon operator lock-in.
| Leading Market Players |
|---|
| Sunless Inc |
| Million Dollar Tan |
| St. Tropez |
| Norvell Sunless |
| GloBody |
| Bondi Sands |
| Aviva Labs |
| Sjolie Inc |
| Fake Bake |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade dihydroxyacetone feedstock costs cascade through formulation tiers, with Brazilian and Australian bulk concentrate buyers capturing margin advantage over US salon operators locked into branded solution subscriptions.
Pricing Analysis
Outcome-based pricing anchored to color longevity and streak-free finish commands premium positioning in professional channels. Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations from private-label salon concentrates and mass-market self-tan mousses. Price differentiation hinges on DHA concentration grade and technician certification level. Pricing pressure stems from ECHA disclosure mandates compressing aerosol margins, while mobile service subscribers demonstrate lowest price sensitivity versus at-home retail buyers.
Supply Chain Analysis
Certified technician scarcity in California, Texas, and New York constrains service capacity expansion despite equipment availability. DHA production concentrates in Germany, China, and India, with pharmaceutical-grade output controlled by three specialty chemical manufacturers. Formulation houses draw from sugar-derived feedstocks and amino acid stabilizers, facing single-source vulnerability in erythrulose supply. Distribution runs through equipment-plus-solution bundlers to salon operators, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance costs erect a barrier-to-entry moat that rewards incumbent formulators with pre-certified DHA supply relationships and penalizes late entrants facing retrospective safety data obligations.
For Market Incumbents: Lock in technician certification pipelines through cosmetology school partnerships in California and Texas, insulating against labor scarcity. Secure backward integration into pharmaceutical-grade DHA sourcing to hedge supply concentration risk among the three dominant specialty chemical manufacturers. For New Entrants and Emerging Players: Capture white-space in men's grooming channels through fitness studio partnerships, where under-15% penetration rates in the United States and Australia offer expansion headroom. Target mobile service platforms in Sydney and Los Angeles with app-based dispatch infrastructure, bypassing fixed-location overhead entirely. For Investors and Strategic Acquirers: ECHA's respiratory sensitizer reclassification of DHA is the leading indicator that aerosol-exposed equipment manufacturers face asset stranding risk. Favor acquisition targets with lotion-based service capabilities and med-spa bundling relationships in Beverly Hills and Miami. Long-term viability hinges on formulation agility across non-atomized delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Formulation Development | Clean-label positioning captures shelf space in premium UK and US beauty retail channels. |
| Mobile Service Platform Integration | Same-day dispatch apps in Sydney and São Paulo displace walk-in salon economics. |
| Med-Spa Service Bundling | Dermatology partnerships in Beverly Hills and Miami attach spray tanning to injectable services. |
| Erythrulose-DHA Hybrid R&D | Extended color persistence commands subscription pricing in professional channels. |
| Technician Certification Pipeline Investment | Cosmetology school partnerships in California and Texas alleviate licensed labor scarcity. |
Methodological Framework
Multi-period observation of DHA supply contracts, salon equipment procurement cycles, and mobile service booking platform growth anchored the trend analysis, supplemented by interviews with formulation chemists, salon franchise operators, equipment manufacturers, and state cosmetology board officials. Secondary validation drew from FDA 510(k) filings, ECHA substance evaluation protocols, ANVISA cosmetic safety registrations, TGA product listings, and customs trade data for DHA concentrate imports. Bottom-up service revenue estimates triangulated against top-down formulation volume projections.
Segment-weighting across product type, application channel, formulation chemistry, and consumer demographic dimensions structured the analytical framework. CAGRs were derived from fitted growth curves applied to professional solution procurement, retail self-tan velocity, and mobile service expansion trajectories over the projection horizon. Industry-specific inputs incorporated technician licensing hour requirements, booth equipment depreciation schedules, and subscription platform commitment rate differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA respiratory sensitizer reclassification timing and DHA supply contract renewals among the three dominant pharmaceutical-grade manufacturers. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
Asia-Pacific Hair Removal Wax Market