
 Bath and Body Products Market | 2026-2036
Bath and Body Products Market Size, Share, and Industry Trends Forecast 2026-2036
Bath and Body Products Market Analysis
Buyer concentration across mass retailers and specialty beauty chains is restructuring procurement leverage for bath and body suppliers. L'Oreal SA leverages its dermatological science heritage to command shelf space in pharmacy channels. Unilever PLC sustains volume leadership through economies of scale in body wash manufacturing. Bath & Body Works Inc anchors North American mall-based distribution with seasonal scent rotation strategies.
Bath and body products encompass surfactant-based cleansers, emollient-rich moisturizers, and exfoliant formulations designed for epidermal hygiene and skin barrier maintenance, typically incorporating pH-balanced systems between 4.5 and 6.5 to preserve acid mantle integrity. Their primary commercial purpose centers on daily personal care rituals across consumer demographics, with therapeutic positioning expanding into stress relief and sleep enhancement claims. Body washes dominate volume throughput in developed markets where showering habits prevail over bathing, while lotions capture disproportionate margin pools due to higher per-unit pricing and repeat purchase frequency. The naturals and organic ingredient segment is attracting reformulation investment as clean label expectations migrate from food into topical products.
The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EPA regulates antimicrobial claims in soap formulations that cross into drug territory; in Europe, REACH compliance and the EU Green Deal chemicals strategy are accelerating substitution of synthetic preservatives and microplastic-containing exfoliants. These regulatory pressures are elevating formulation costs and favoring manufacturers with dedicated regulatory affairs capabilities and established supplier audit programs. Stakeholders must monitor evolving state-level ingredient bans and certification standards to anticipate reformulation timelines and inventory transitions.
Market Dynamics
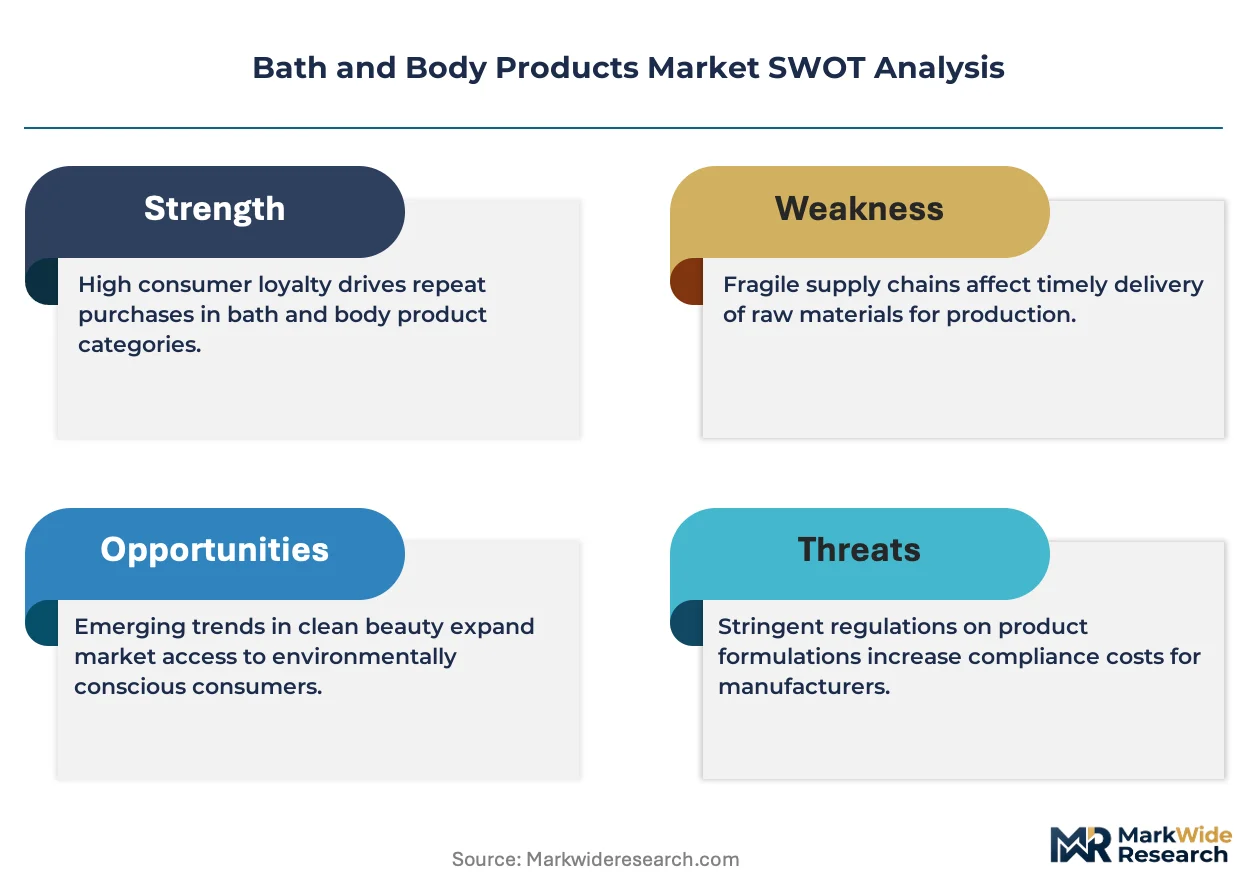
The bath and body sector faces structural pressure from the EU's REACH chemicals framework and proliferating state-level clean beauty legislation, which together mandate ingredient disclosure and accelerate substitution timelines for synthetic preservatives and microplastic-containing exfoliants.
Growth Catalysts
- Clean Label Migration:Consumer expectations for ingredient transparency, honed in food markets, now drive reformulation investment in surfactant-based cleansers and emollient-rich moisturizers.
- Urban India Demand Concentration:Organized retail and e-commerce platforms in Mumbai, Delhi, and Bangalore accelerate category penetration among millennial and Gen Z consumers.
- REACH Compliance Deadlines:The EU Green Deal chemicals strategy forces inventory transitions that favor manufacturers with dedicated regulatory affairs capabilities and established supplier audit programs.
Market Restraints
- Palm Oil Derivative Volatility:Lauryl sulfate and glycerin feedstock costs fluctuate with Malaysian and Indonesian export policies, compressing margin pools for mid-tier body wash manufacturers.
- Preservative Substitution Technical Limits:Natural alternatives to parabens and formaldehyde-releasing compounds exhibit shorter shelf stability, constraining distribution reach for clean-positioned brands.
- Specialty Retailer Consolidation:Buyer concentration across mass retailers and pharmacy chains restructures procurement leverage, squeezing smaller suppliers on payment terms and slotting fees.
Strategic Opportunities
- Therapeutic Positioning White Space:Stress relief and sleep enhancement claims in bath soaks and shower steamer formats attract premium pricing from wellness-oriented demographics in Germany and South Korea.
- Refill Infrastructure Investment:Concentrate and bulk dispensing systems in UK supermarkets and French pharmacy channels reduce per-unit packaging costs while locking in repeat purchase frequency.
- Biotechnology-Enabled Fermentation:Precision fermentation of squalane and ceramides converges with synthetic biology to decouple high-performance emollients from agricultural commodity cycles.
Industry Challenges
- Reformulation Talent Scarcity:Cosmetic chemists with dual competency in natural ingredient stability and regulatory submission timelines command premium compensation, constraining mid-cap R&D expansion.
- Multi-Jurisdiction Certification Complexity:Simultaneous pursuit of COSMOS, NaTrue, and EWG Verified labels extends product development cycles and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath and Body Products Market |
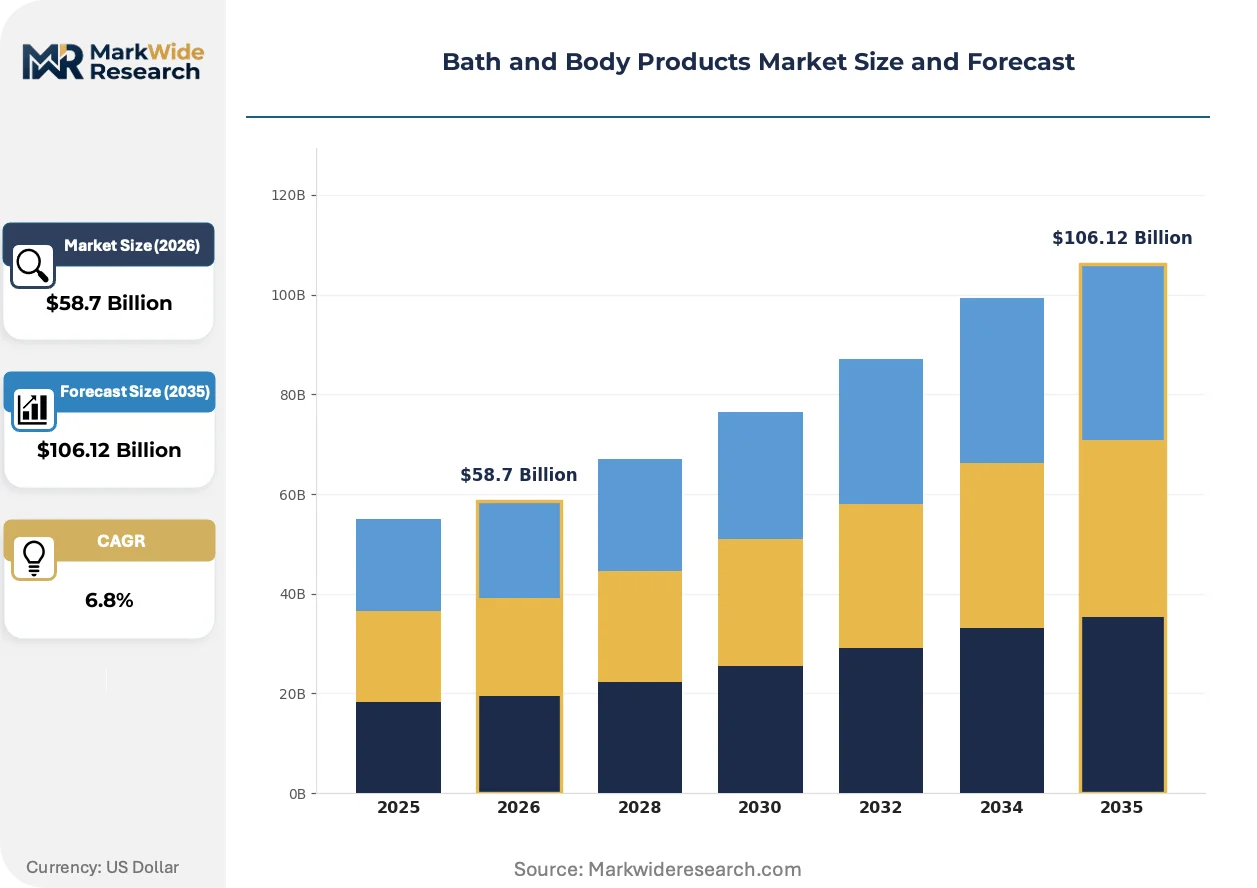
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Scrubs, Soaps, Body Washes Ingredient Type: Naturals, Organic, Synthetic, Herbal User Type: Men, Women, Children, Unisex Packaging Type: Bottles, Tubes, Jars, Pouches |
| Companies Covered | Beiersdorf AG, Kao Corporation, L'Oreal SA, Bath & Body Works Inc, Coty Inc, Unilever PLC, The Estee Lauder Companies Inc, L'Occitane International SA, The Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath and Body Products Market Emerging Trajectories
Waterless and solid format innovation is compressing logistics costs and packaging waste footprints while forcing reformulation of traditional emulsion chemistry around anhydrous delivery systems.
Biotechnology-derived surfactants is modularizing supply chain architecture for cleansing products. Rhamnolipid and sophorolipid biosurfactants, produced via microbial fermentation, replace petroleum-derived sodium lauryl sulfate in premium body washes. Specialty beauty brands in France and Japan are accelerating adoption to meet biodegradability mandates. This modularizing of ingredient sourcing is enabling smaller brands to bypass traditional chemical distributor networks and contract directly with fermentation facilities.
REACH microplastic restrictions are restructuring exfoliant formulation. The 2023 EU prohibition on synthetic polymer microparticles in rinse-off cosmetics forces substitution toward cellulose, silica, or enzymatic alternatives. Manufacturers serving European pharmacy channels face compressed inventory transition timelines. Body scrub and polish segments in Germany, the Netherlands, and Belgium are responding with accelerated certification of natural-origin alternatives.
Subscription-based replenishment models are displacing conventional retail purchase cycles for lotion and body wash categories. Direct-to-consumer platforms in the United States and United Kingdom bundle seasonal scent rotations with auto-ship logistics, capturing higher lifetime value from repeat buyers. This behavior shift concentrates demand data with platform operators, weakening traditional retailer's category management influence in North American and British urban markets.
Bath and Body Products Market Segmentation
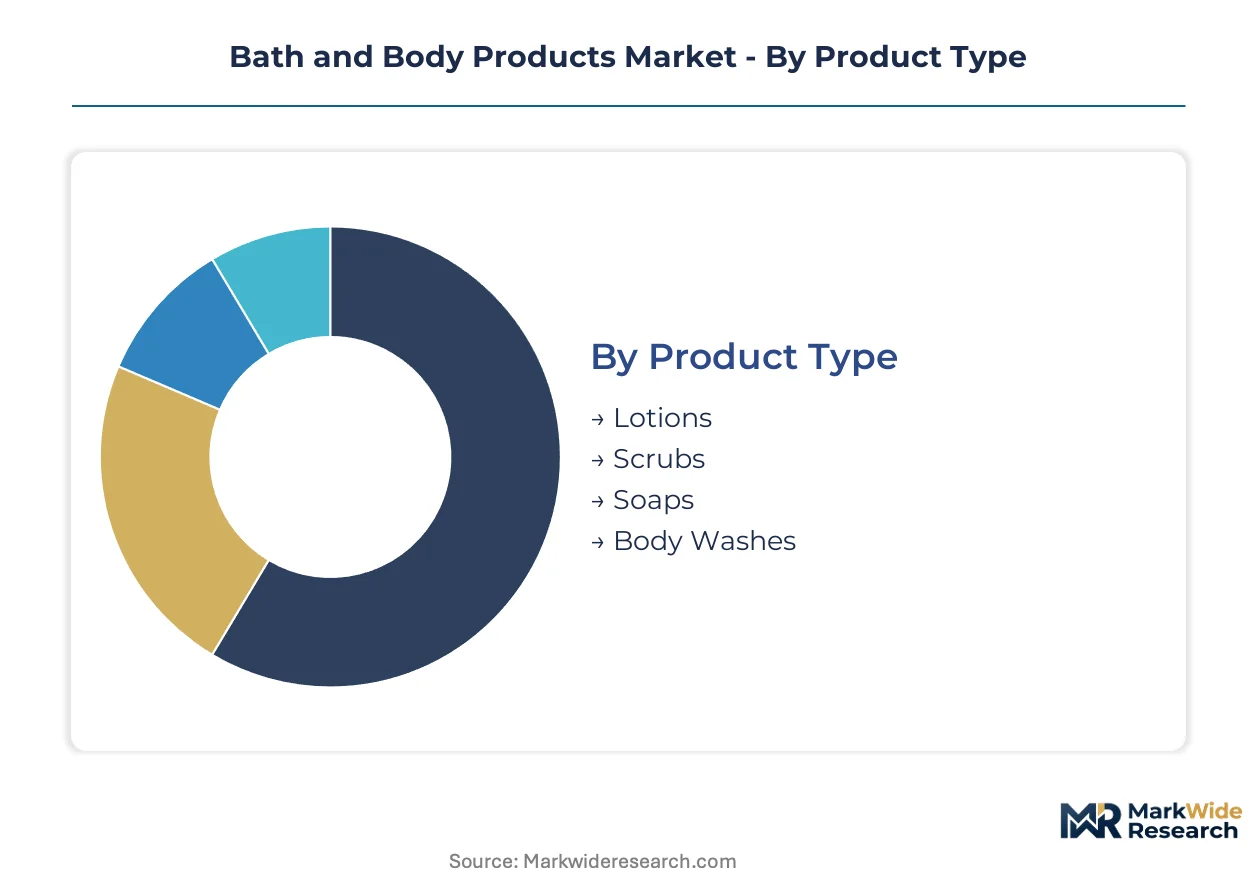
Segmentation in bath and body products determines manufacturing asset allocation, formulation R&D priorities, and channel-specific marketing spend. Distinct product formats, ingredient positioning, and user demographics each command separate supply chain configurations and margin structures.
Product Type:
Supply concentration in body washes and lotions dominates volume throughput, while scrubs and soaps occupy specialized manufacturing niches with distinct equipment requirements.
- Body Washes:Surfactant-based formulations in pH-balanced systems between 4.5 and 6.5 preserve acid mantle integrity during daily cleansing rituals. Demand concentrates in Germany, the United Kingdom, and urban India where showering habits prevail over bathing; REACH compliance deadlines accelerate substitution of synthetic polymer thickeners toward biosurfactant alternatives.
- Lotions:Emollient-rich moisturizers incorporating ceramides, squalane, or shea butter derivatives deliver skin barrier maintenance for post-cleansing application. North American pharmacy channels and French dermocosmetic retailers capture disproportionate margin pools through higher per-unit pricing and subscription-based replenishment models.
- Scrubs:Exfoliant formulations face compressed inventory transitions following EU microplastic restrictions, forcing rapid certification of cellulose, silica, or enzymatic alternatives in rinse-off applications.
- Soaps:Traditional bar formats experience resurgence in waterless and solid format innovation, compressing logistics costs while requiring reformulation around anhydrous delivery systems.
Today's leader: Body Washes. Tomorrow's challenger: Lotions.
Ingredient Type:
Cost tier stratification separates premium-positioned naturals and organic segments from commodity synthetic formulations, with herbal extracts occupying a mid-tier functional positioning.
- Naturals:Plant-derived surfactants, emollients, and preservatives command reformulation investment as clean label expectations migrate from food into topical products. Urban Indian millennials and Gen Z consumers in Mumbai and Bangalore drive fastest adoption through organized retail and e-commerce platforms.
- Organic:COSMOS and NaTrue certified ingredients require established supplier audit programs and dedicated regulatory affairs capabilities, elevating formulation costs while locking in premium shelf space in UK supermarkets and French pharmacy channels.
- Synthetic:Petroleum-derived sodium lauryl sulfate and paraben preservatives face substitution pressure from biotechnology-enabled fermentation alternatives.
- Herbal:Ayurvedic and traditional medicine-inspired botanical extracts attract wellness-oriented positioning in stress relief and sleep enhancement claims.
Organic commands premium pricing. Naturals gain share fastest.
User Type:
Application-specific formulation requirements drive distinct scent profiles, packaging aesthetics, and therapeutic positioning across demographic segments.
- Women:Seasonal scent rotation strategies and therapeutic bath soaks capture repeat purchase frequency through direct-to-consumer auto-ship logistics in the United States and United Kingdom.
- Men:Grooming-integrated body care with simplified multi-functional formats concentrates demand in mass retail and specialty beauty chains restructuring procurement leverage.
- Children:Hypoallergenic and tear-free formulations face stringent safety labeling oversight from FDA cosmetic regulations and heightened parental scrutiny of ingredient disclosure.
- Unisex:Neutral scent profiles and minimalist packaging aesthetics expand addressable market while reducing SKU complexity for mid-tier manufacturers.
Women's segment anchors current revenue. Unisex offers expansion pathway.
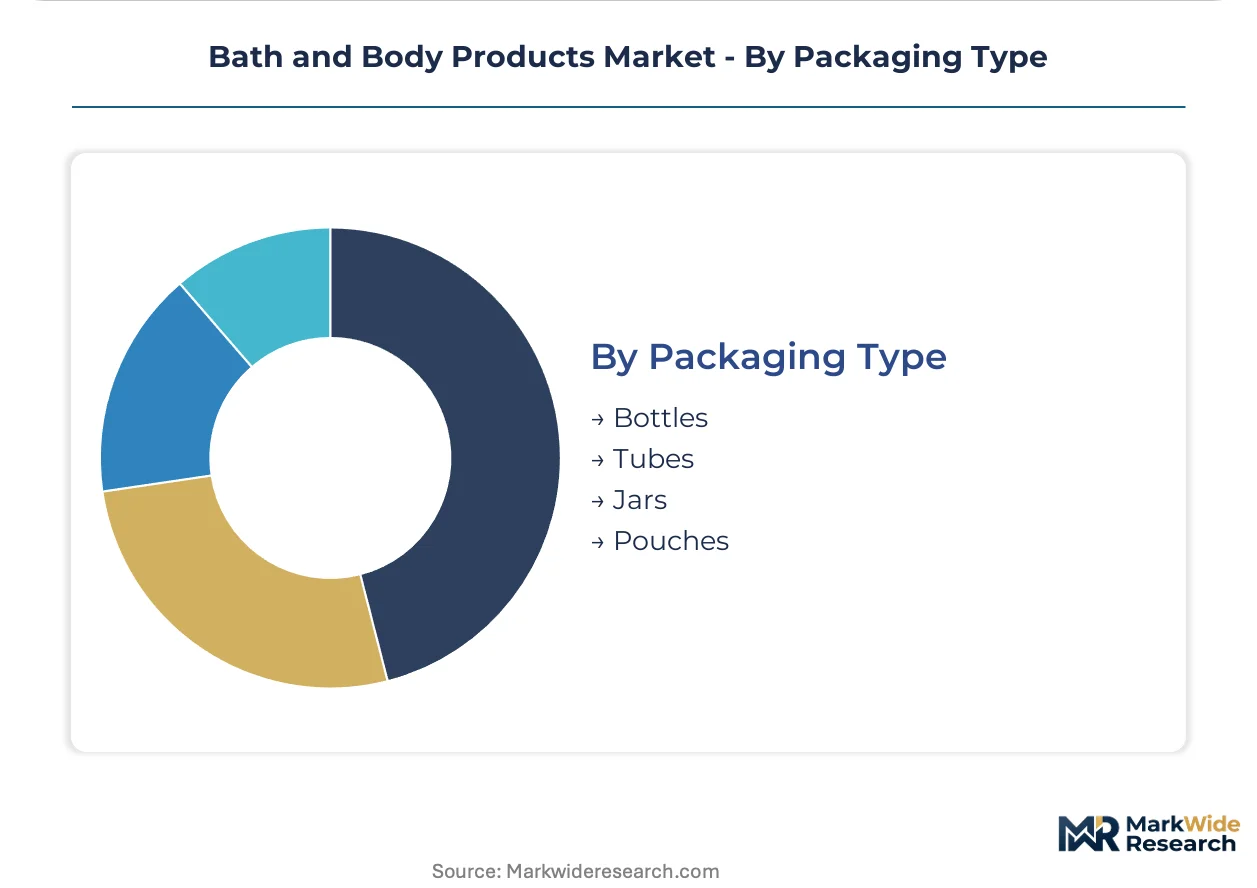
Packaging Type:
Volume and margin characteristics vary sharply by format, with refill infrastructure investment reshaping competitive economics in concentrate and bulk dispensing systems.
- Bottles:Standard pump and flip-cap containers dominate body wash and lotion categories, though per-unit packaging costs face pressure from concentrate dilution-at-home alternatives in UK and French retail.
- Tubes:Squeeze formats suit travel-size and on-the-go applications, with aluminum laminate barriers extending shelf stability for natural preservative systems.
- Jars:Wide-mouth containers accommodate thick cream and scrub textures while enabling consumer access to last-product recovery; glass and post-consumer recycled plastic variants attract clean beauty positioning.
- Pouches:Flexible refill formats reduce per-unit packaging costs and enable bulk dispensing systems in supermarket and pharmacy channels, locking in repeat purchase frequency through lower price points.
Bottles hold installed base. Pouches show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists with dual competency in natural ingredient stability and regulatory submission timelines concentrate in Germany, France, and the United States, anchoring formulation innovation clusters that serve multinational brand headquarters.
United States
Millennial and Gen Z consumers in New York and Los Angeles drive wellness-oriented routines through direct-to-consumer auto-ship platforms. The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while California's state-level clean beauty legislation tightens ingredient disclosure requirements. Greater Boston hosts biotechnology fermentation facilities supplying biosurfactant alternatives to premium body wash manufacturers.
Germany
Pharmacy channel concentration in Berlin and Hamburg captures disproportionate margin pools for dermocosmetic body care. The EU's REACH chemicals framework and Green Deal chemicals strategy accelerate substitution of synthetic preservatives and microplastic-containing exfoliants. The Rhine-Ruhr industrial corridor houses precision fermentation facilities producing rhamnolipid biosurfactants for rinse-off cosmetic applications.
France
Seasonal scent rotation strategies and therapeutic bath soaks attract premium pricing from wellness-oriented demographics in Paris and Lyon. ANSM and ECHA jointly enforce REACH microplastic restrictions that force rapid certification of cellulose and silica exfoliant alternatives. The Provence-Alpes-Côte d'Azur region supplies lavender and botanical extract feedstocks to organic-certified formulation houses.
India
Urban millennials in Mumbai, Delhi, and Bangalore accelerate category penetration through organized retail and e-commerce platforms. BIS standards and forthcoming state-level cosmetic safety regulations elevate formulation compliance costs for imported brands. The Maharashtra industrial corridor hosts contract manufacturers serving both domestic mass retailers and export markets.
United Kingdom
Concentrate and bulk dispensing systems in London and Manchester supermarkets reduce per-unit packaging costs while locking in repeat purchase frequency. The Competition and Markets Authority monitors retail buyer concentration across pharmacy chains that restructures procurement leverage for mid-tier suppliers. The Midlands manufacturing belt produces aluminum laminate barrier tubes extending shelf stability for natural preservative systems.
Bath and Body Products Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The sector exhibits moderate consolidation with scale advantages concentrating in mass retail distribution and pharmacy channel access. Three strategic archetypes dominate: multinational CPG conglomerates leveraging dermatological science heritage, specialty beauty retailers anchoring mall-based and direct-to-consumer distribution, and mid-tier contract manufacturers serving private label programs. Competitive moves center on M&A-driven portfolio diversification into therapeutic positioning segments and backward integration into biotechnology-enabled fermentation feedstocks.
Within the multinational conglomerate tier, L'Oreal SA and Unilever PLC exemplify scale-driven archetypes with established regulatory affairs capabilities spanning multiple jurisdictions. L'Occitane International SA occupies a position within the specialty pure-play segment, representing focused geographic and channel strategies. These three entities collectively illustrate the competitive spectrum from mass-market volume leadership to premium-tier botanical positioning.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Kao Corporation |
| L'Oreal SA |
| Bath & Body Works Inc |
| Coty Inc |
| Unilever PLC |
| The Estee Lauder Companies Inc |
| L'Occitane International SA |
| The Procter & Gamble Company |
| Others |
Supply Flow & Price Mechanics
Clean beauty legislation in California and the EU's REACH microplastic restrictions are forcing rapid inventory transitions that compress margin pools for mid-tier manufacturers while rewarding suppliers with established regulatory affairs capabilities and dedicated supplier audit programs.
Pricing Analysis
Capacity additions in Malaysia and Indonesia are reshaping price floors for palm oil-derived surfactants and glycerin feedstocks. Three-tier pricing structure across premium dermocosmetic, standard mass retail, and economy private label levels stratifies the market. Pricing pressure stems from biotechnology-enabled fermentation alternatives displacing petroleum-derived sodium lauryl sulfate in premium tiers. Mass retailers exhibit highest price sensitivity; pharmacy channel buyers absorb premium positioning for clinically validated formulations.
Supply Chain Analysis
Post-consumer recycled plastic collection and aluminum laminate tube recovery flows are emerging as critical reverse logistics capabilities for brands pursuing clean beauty certification. Manufacturing concentrates in Germany, France, and the United States for formulation innovation; India and China anchor contract manufacturing for mass volume production. Feedstock dependencies include Malaysian palm oil derivatives, Provence lavender botanical extracts, and fermentation-derived squalane from biotechnology facilities. Single-source vulnerability in biosurfactant fermentation capacity threatens supply continuity for clean-positioned brands. Distribution runs through mass retail chains, pharmacy channels, and direct-to-consumer auto-ship platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in therapeutic positioning segments and refill infrastructure deployment, where premium pricing power combines with packaging cost reduction to improve unit economics.
For Market Incumbents: Cement pharmacy channel access through dermatological science heritage and regulatory submission capabilities that smaller competitors cannot replicate. Defend against biotechnology-enabled fermentation startups by acquiring precision fermentation facilities in the Rhine-Ruhr corridor or Greater Boston. Prioritize backward integration into squalane and ceramide feedstocks to decouple from agricultural commodity cycles. For New Entrants and Emerging Players: REACH microplastic restrictions in Germany open a window for cellulose and silica exfoliant alternatives in body scrub formulations. Target therapeutic bath soak segments in South Korea and Germany where wellness-oriented demographics pay premium pricing for stress relief claims. Pursue direct-to-consumer auto-ship logistics with seasonal scent rotation strategies to capture lifetime value data. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier contract manufacturers serving private label programs for mass retailers restructuring procurement leverage. Long-term viability hinges on regulatory affairs capabilities spanning FDA cosmetic labeling and EU REACH compliance. Monitor state-level clean beauty legislation adoption rates across the United States as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Infrastructure Investment | Concentrate dispensing systems in UK supermarkets reduce per-unit packaging costs while locking in repeat purchase frequency. |
| Biotechnology Feedstock Integration | Precision fermentation of rhamnolipid biosurfactants decouples premium body wash production from palm oil derivative volatility. |
| Therapeutic Positioning Extension | Sleep enhancement claims in shower steamer formats attract wellness-oriented millennials in Berlin and Seoul pharmacy channels. |
| Regulatory Certification Stacking | Simultaneous COSMOS and EWG Verified labels extend development cycles but secure premium shelf space in French dermocosmetic retail. |
| Direct-to-Consumer Platform Launch | Auto-ship logistics with seasonal scent rotations concentrate demand data and weaken traditional retailer category management influence. |
Methodological Framework
Bottom-up product format modeling reconciled against top-down ingredient supplier tracking forms the analytical core of this study. Primary interviews with cosmetic chemists, regulatory affairs directors at multinational CPG conglomerates, pharmacy chain category buyers, and contract manufacturing procurement leads combined with secondary validation from FDA cosmetic labeling guidance, ECHA REACH substance restrictions, customs trade data for palm oil derivative imports, and Nielsen retail audit data for body wash and lotion categories. Triangulation across these sources ensures coverage of both formulation innovation clusters and mass volume production economics.
Historical trendline analysis of body wash and lotion pricing trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product format, ingredient positioning tier, user demographic, and packaging type, with regional regulatory cluster and channel structure as cross-cutting variables. CAGRs derived from fitted growth curves adjusted for REACH compliance deadline impacts and urban India demand concentration patterns. Industry-specific forecast inputs incorporated biotechnology fermentation capacity buildouts and state-level clean beauty legislation adoption timelines.
Revisions become necessary when EU Green Deal chemicals strategy accelerates beyond current substitution timelines or when Malaysian and Indonesian export policies disrupt palm oil derivative feedstock availability. Practitioners should monitor biosurfactant fermentation facility commissioning announcements and pharmacy chain consolidation activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Nail Strengtheners Market
Beauty & Personal Care
Middle East Herbal Shampoo Market