
 Cheese Cutting Machine Market | 2026-2036
Cheese Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Cutting Machine Market Outlook
Food manufacturers is recalibrating equipment procurement toward high-throughput automated lines that reduce labor dependency and improve portion consistency. GEA Group leverages its dairy processing heritage to dominate industrial-scale cutting system installations across European cheese cooperatives. Tetra Pak sustains technology leadership through integrated packaging-and-cutting line architectures that reduce downstream handling. Marel anchors its position in North American food manufacturing with precision weight-control modules embedded in multi-station cutting platforms.
A cheese cutting machine is an electromechanical or automated device engineered to portion, slice, wedge, or dice cheese blocks and wheels with controlled thickness tolerances, typically operating at blade speeds of 500–2,000 cuts per minute depending on product density and temperature. Industrial cutters lead equipment value capture due to capital intensity and replacement cycles, while ultrasonic cutting technology is displacing conventional blade systems in premium cheese applications where clean edges and reduced product sticking justify higher equipment cost. Food manufacturers represent the deepest demand pool, though supermarket in-house deli automation is expanding the mid-capacity segment faster than historical norms.
The EU Machinery Directive and CE marking framework govern equipment safety and electromagnetic compatibility for machines deployed across European dairy processing plants, while FDA food-contact substance regulations under 21 CFR constrain blade coatings and conveyor materials in US installations. ISO 14159 hygiene design standards increasingly shape supplier R&D priorities as clean-in-place requirements intensify. Stakeholders must monitor how evolving food safety audit protocols and energy efficiency benchmarks reshape total cost of ownership calculations for replacement versus upgrade decisions.
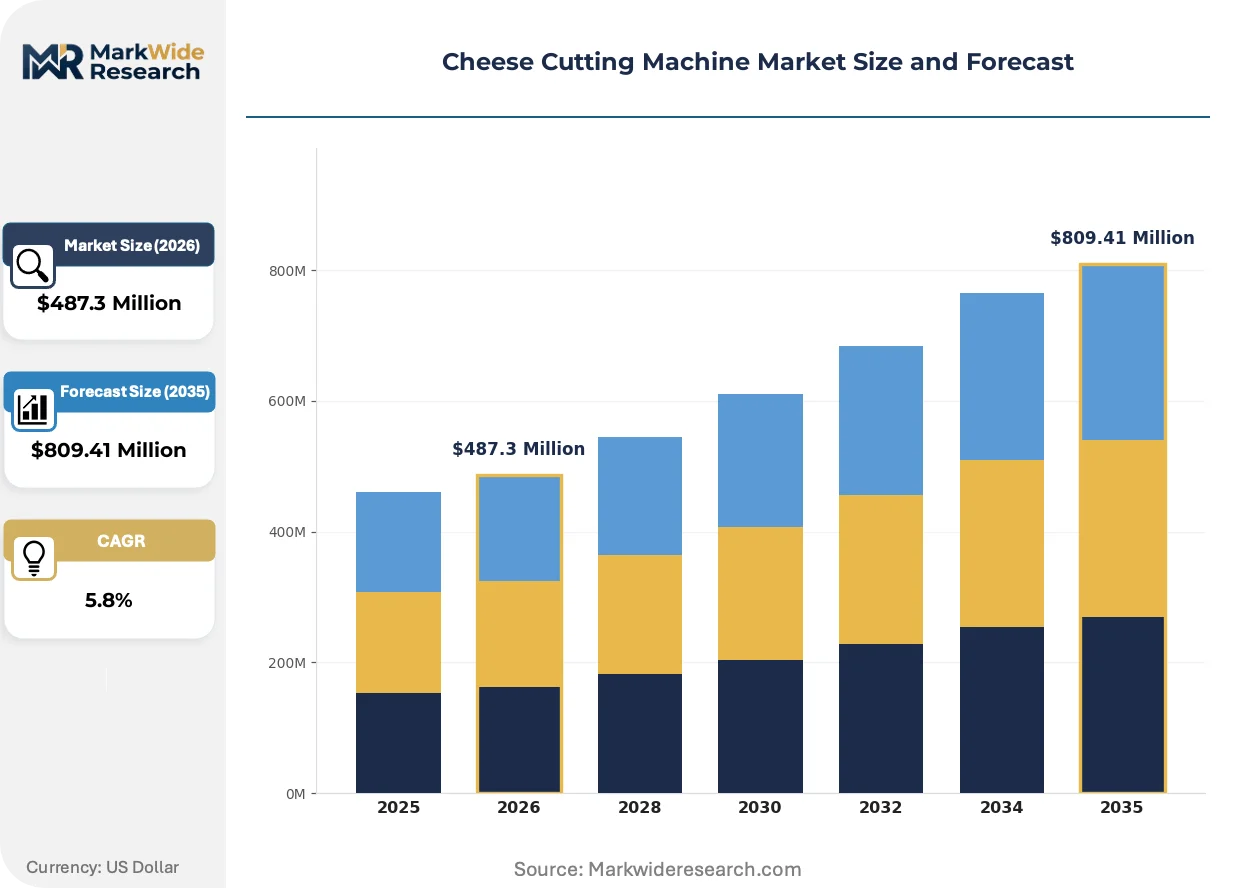
Market Dynamics
Ultrasonic blade technology is compressing replacement cycles for conventional mechanical cutters as food manufacturers prioritize clean-edge portioning and reduced product waste in high-value cheese categories.
Growth Catalysts
- EU Machinery Directive compliance mandates:European dairy cooperatives are accelerating equipment refresh timelines to meet CE marking and electromagnetic compatibility standards ahead of enforcement deadlines.
- Foodservice automation:Deli counter automation in supermarket chains is expanding addressable demand for mid-capacity cutting systems with integrated weighing modules.
- Clean-in-place (CIP) hygiene architecture:ISO 14159 design standards are pulling capital toward stainless-steel conveyor systems and tool-free blade change mechanisms.
Market Restraints
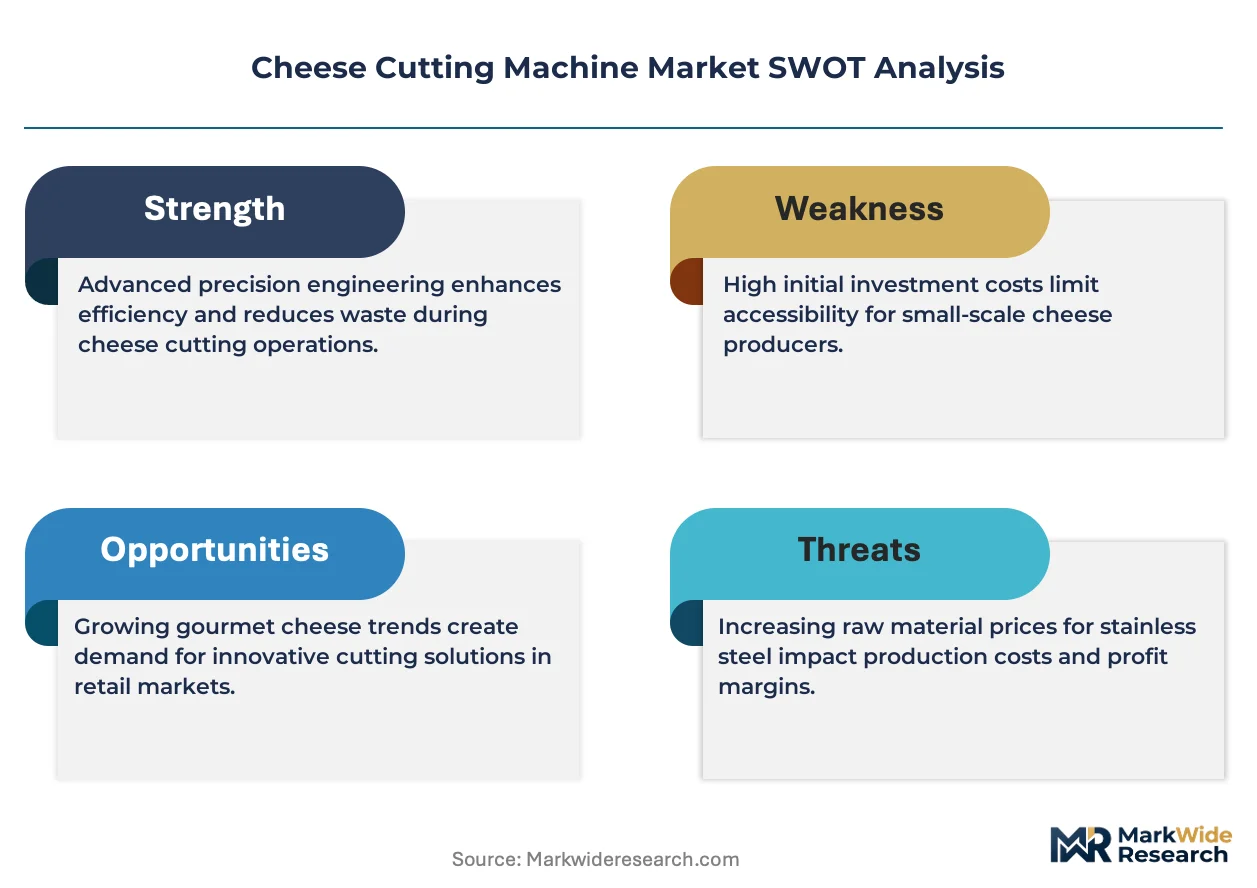
- Stainless steel input volatility:Grade 304 and 316 stainless price swings compress equipment margin buffers for European and North American fabricators.
- Ultrasonic transducer supply concentration:Piezoelectric component sourcing clusters in East Asian manufacturing hubs, creating single-source vulnerability for premium cutting system assemblers.
- FDA 21 CFR food-contact substance timelines:Extended approval cycles for novel blade coatings delay product launches in US dairy processing installations.
Strategic Opportunities
- Plant-based cheese analogs:Alternative dairy processors require modified cutting parameters for temperature-sensitive formulations, opening equipment customization revenue streams.
- EU Green Deal energy efficiency benchmarks:Motor efficiency mandates are creating replacement pull for servo-driven cutting platforms with regenerative braking.
- Direct-to-processor digital distribution:Equipment configurators with virtual commissioning capabilities are compressing sales cycles for regional dairy equipment distributors.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and ultrasonic frequency tuning expertise concentrates in aging workforce cohorts across German and Italian equipment maintenance networks.
- Legacy PLC integration friction:Retrofitting digital cutting controls into 1990s-era dairy lines demands custom I/O mapping that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Cutting Machine Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutters, Electric Cutters, Multi-functional Slicers, Industrial Cutters End User: Restaurants, Cheesemongers, Supermarkets, Food Manufacturers Technology: Laser Cutting, Ultrasonic Cutting, Knife Cutting, Blade Cutting Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | GEA Group, Tetra Pak, Alfa Laval, Mondini S.p.A., Ilapak, JBT Corporation, Marel, Bizerba, Provisur Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Cutting Machine Market Strategic Shifts
Equipment architecture is pivoting from standalone cutting stations toward integrated processing lines where portioning, weighing, and packaging converge under unified control systems.
Ultrasonic cutting technology is electrifying premium cheese applications. High-frequency blade oscillation at 20-40 kHz eliminates mechanical compression and thermal deformation in soft-ripened varieties. Artisanal and specialty cheese producers in France and Switzerland are adopting these systems despite capital premiums. This shift is electrifying equipment upgrade decisions as clean-edge quality becomes a procurement discriminator.
REACH chemical substance restrictions are constraining blade coating formulations across European installations. Perfluorinated compound limitations are forcing suppliers toward ceramic and titanium-nitride alternatives with shorter wear lifespans. German equipment OEMs are responding with modular blade cartridge designs that accelerate replacement without full system downtime.
After-sales service unbundling is fragmenting traditional equipment procurement. Food manufacturers are separating hardware acquisition from maintenance contracts and software subscription tiers. This pattern is most pronounced in North American dairy processing where capital budgeting and operating expenditure lines are managed by distinct procurement functions.
Cheese Cutting Machine Market Segmentation
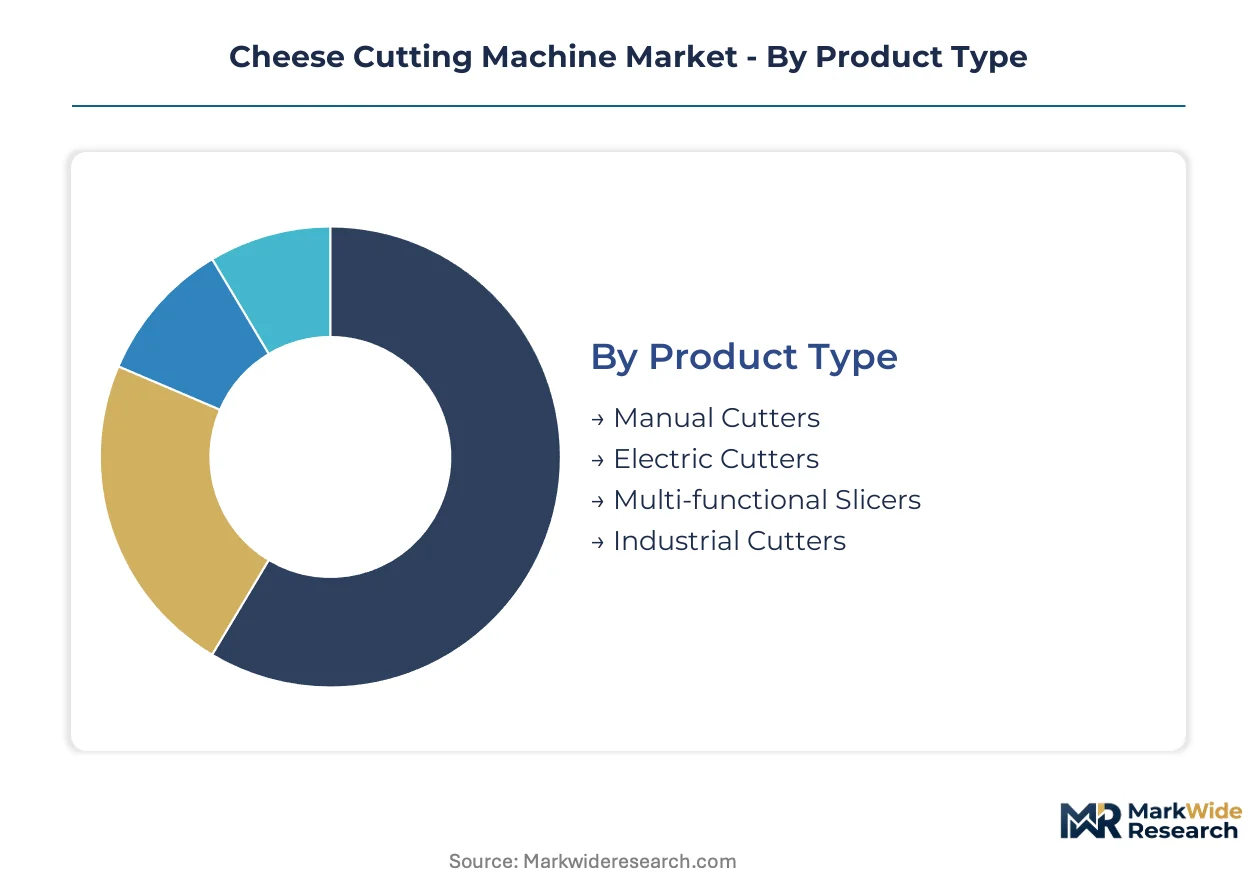
Cheese cutting equipment procurement diverges sharply between standalone deli installations and integrated processing lines. Understanding these deployment patterns clarifies where capital concentrates and which configurations command pricing premiums.
Product Type:
Standalone units serve countertop operations while embedded systems dominate high-volume dairy cooperatives.
- Manual Cutters:Hand-operated wire or blade mechanisms requiring no electrical infrastructure. Artisanal producers in France and Switzerland specify these for soft-ripened varieties where blade pressure damages product integrity.
- Electric Cutters:Motorized blade systems operating at fixed speeds between 200-800 cuts per minute. Demand clusters in independent cheesemongers across Germany where labor costs drive semi-automation.
- Multi-functional Slicers:Modular platforms with interchangeable blade configurations for portioning, wedging, and shredding. Supermarket deli counters in the Netherlands deploy these for SKU flexibility across cheese categories.
- Industrial Cutters:High-throughput systems processing 1,000+ kilograms hourly with servo-controlled precision. Food manufacturers in Wisconsin and Bavaria anchor demand as automated lines replace batch operations.
Volume placements concentrate in Industrial Cutters; the faster expansion belongs to Multi-functional Slicers.
End User:
Capital intensity separates occasional-use operators from continuous-processing facilities.
- Restaurants:Front-of-house portioning equipment emphasizing compact footprints and rapid blade change. Fine-dining establishments in Milan and Lyon specify these for tableside cheese service programs.
- Cheesemongers:Precision cutting tools for irregular wheel shapes and customer-specific thickness requests. Specialty retailers in Copenhagen and Vienna drive demand for adjustable wire tension systems.
- Supermarkets:Mid-capacity automated lines with integrated weighing and labeling modules. German retail chains Edeka and REWE are expanding in-house deli automation faster than historical norms.
- Food Manufacturers:Industrial-scale cutting platforms synchronized with packaging and logistics systems. Dairy cooperatives in Wisconsin and Emmental account for the deepest equipment procurement pools.
Food Manufacturers deploy the largest installed base; Supermarkets are climbing the fastest as deli counter automation accelerates.
Technology:
Cutting mechanism selection hinges on cheese density, temperature sensitivity, and edge-quality requirements.
- Laser Cutting:Focused beam systems achieving sub-millimeter precision without mechanical contact. Experimental deployment in Swiss alpine cheese operations where traditional blade oxidation affects flavor profiles.
- Ultrasonic Cutting:High-frequency blade oscillation at 20-40 kHz eliminating compression and thermal deformation. Premium soft-ripened producers in France adopt these despite capital premiums for clean-edge quality.
- Knife Cutting:Rotating or reciprocating blade systems for standard portioning applications. Baseline technology for entry-level equipment across Eastern European dairy processors.
- Blade Cutting:Fixed-blade configurations with adjustable spacing for uniform slice thickness. Dominant in high-volume cheddar and gouda operations where speed supersedes edge refinement.
Blade Cutting retains the broadest installed footprint; Ultrasonic Cutting is gaining share fastest as premium cheese categories expand.
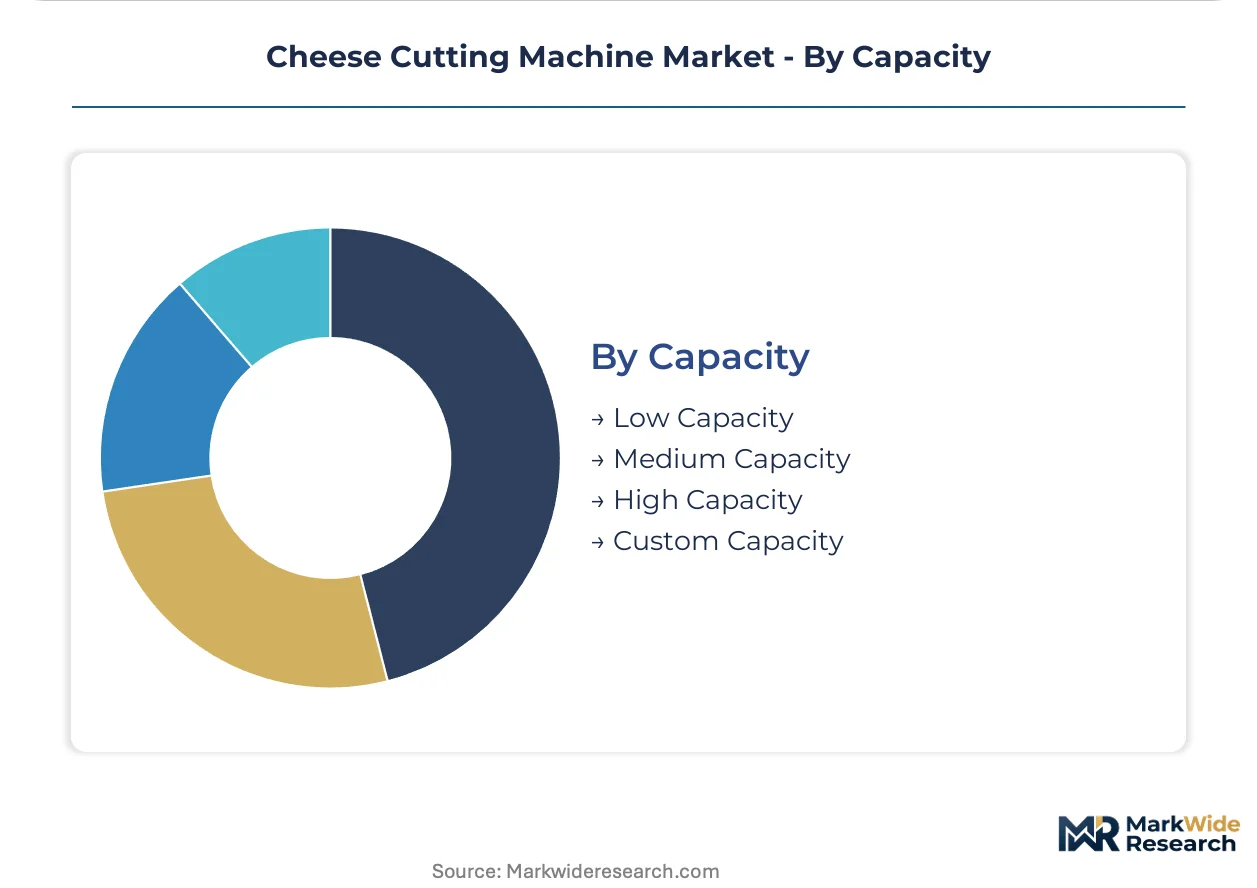
Capacity:
Throughput specifications align with batch frequency and SKU complexity rather than absolute volume alone.
- Low Capacity:Equipment processing under 50 kilograms hourly, typically single-operator stations. Farmstead producers in Vermont and Somerset specify these for seasonal production cycles.
- Medium Capacity:Systems handling 50-300 kilograms hourly with semi-automated feeding mechanisms. Regional dairy processors in Denmark and the Netherlands anchor this segment.
- High Capacity:Continuous-operation lines exceeding 500 kilograms hourly with automated product handling. Major cooperatives in Wisconsin and Lombardy concentrate procurement here.
- Custom Capacity:Bespoke configurations for non-standard wheel dimensions or specialty cheese formats. Artisanal producers in Roquefort and Comté AOP zones require these for protected-origin specifications.
High Capacity systems dominate capital deployment; Custom Capacity shows the steepest expansion trajectory as specialty cheese protection regimes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Wisconsin concentrate dairy equipment manufacturing, with tax incentives pulling capital toward automated processing infrastructure. Investment flows cluster where cooperative dairy networks and stainless-steel fabrication ecosystems overlap.
United States
Dairy cooperatives in Wisconsin and California anchor capital deployment for high-capacity cutting lines. FDA 21 CFR food-contact substance regulations constrain blade coating approvals, extending equipment commissioning timelines. The Upper Midwest dairy corridor from Green Bay to Madison hosts the densest concentration of retrofit installations.
Germany
EU Machinery Directive compliance deadlines accelerate equipment refresh cycles across Bavarian and North Rhine-Westphalian processing plants. CE marking and electromagnetic compatibility certifications dominate supplier qualification protocols. The Munich-Stuttgart industrial belt concentrates servo-driven cutting platform manufacturing.
France
Artisanal cheese protection regimes in Roquefort and Comté AOP zones sustain demand for custom-capacity cutting configurations. REACH chemical restrictions on perfluorinated blade coatings push fabricators toward ceramic alternatives. The Auvergne-Rhône-Alpes region anchors specialty equipment customization revenue.
Switzerland
Swissmedic and federal food safety frameworks govern equipment hygiene standards for alpine cheese operations. Experimental laser cutting deployments in Emmental address flavor preservation concerns from blade oxidation. The Bernese Mittelland hosts precision engineering clusters serving premium cheese producers.
Netherlands
Supermarket chains Edeka and REWE expand deli counter automation faster than historical norms, pulling mid-capacity system demand. ISO 14159 hygiene design standards shape procurement specifications for stainless-steel conveyor architectures. The Randstad logistics corridor enables rapid equipment commissioning for retail installations.
Cheese Cutting Machine Market Competitive Environment
Top-tier vendors anchor integrated processing line architectures, while regional fabricators occupy specialized customization niches. The vendor base stratifies across three tiers: multinational dairy equipment conglomerates with full-line capabilities, mid-scale specialists in ultrasonic or precision cutting, and regional stainless-steel fabricators serving artisanal producers. Strategic moves concentrate on technology licensing partnerships and backward integration into piezoelectric component sourcing.
Among European-based industrial equipment groups, GEA Group, Tetra Pak, and Marel exemplify distinct competitive archetypes. GEA Group represents heritage dairy processing conglomerates leveraging installed base relationships. Tetra Pak occupies the packaging-integration specialist position where cutting and downstream handling converge. Marel anchors the precision-control segment with embedded weight-management architectures. These three entities collectively illustrate how competitive positioning fragments across line-integration versus point-solution specialization.
| Leading Market Players |
|---|
| GEA Group |
| Tetra Pak |
| Alfa Laval |
| Mondini S.p.A. |
| Ilapak |
| JBT Corporation |
| Marel |
| Bizerba |
| Provisur Technologies |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal energy efficiency benchmarks gate qualified supply and premium-tier pricing access, as equipment fabricators in Germany and Italy must certify servo-driven architectures to maintain margin premiums while stainless steel price volatility compresses buffers for non-compliant assemblers.
Pricing Analysis
Short lead-time premiums dominate transactional dynamics, with German dairy cooperatives paying markups for CE-marked equipment available under eight-week delivery windows while spot inventory of conventional blade systems trades at discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by ultrasonic versus mechanical cutting technology and ISO 14159 hygiene certification grade. Cost compression in economy-tier manual cutters is intensifying because of Grade 304 stainless input volatility. Supermarket deli operators show highest price sensitivity; artisanal AOP producers in France demonstrate lowest sensitivity due to protection regime compliance requirements.
Supply Chain Analysis
CE marking and FDA 21 CFR food-contact substance qualifications gate component sourcing, with piezoelectric transducer supply concentrating in East Asian manufacturing hubs and stainless-steel fabrication anchored in Germany, Italy, and Wisconsin. Raw material dependencies draw from nickel-chromium alloy feedstock, servo motor drives, and ceramic blade coatings. Single-source vulnerability in ultrasonic transducer procurement creates structural risk. Distribution runs through regional dairy equipment distributors with direct-to-processor digital channels gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor consolidation is accelerating as REACH chemical restrictions and energy efficiency mandates force smaller fabricators without certification infrastructure toward exit.
For Market Incumbents: Deploy backward integration into piezoelectric component sourcing to neutralize East Asian single-source vulnerability. GEA Group and Tetra Pak should expand captive blade coating capabilities ahead of perfluorinated compound phase-outs, while locking multi-year service contracts with Bavarian dairy cooperatives to defend against ultrasonic specialist encroachment. For New Entrants and Emerging Players: Regional stainless-steel fabricators in France and Switzerland offer partnership pathways into custom-capacity artisanal equipment. Plant-based cheese analog processors present the most penetrable white-space segment, with temperature-sensitive formulation expertise enabling technology licensing plays outside traditional dairy procurement channels. For Investors and Strategic Acquirers: FDA 21 CFR approval timeline acceleration for novel blade coatings is the leading indicator that premium ultrasonic platform valuations will detach from mechanical cutter multiples. Mid-scale specialists with existing CE marking infrastructure and servo calibration technician networks represent priority acquisition archetypes over the coming decade.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Technology Licensing | Enables premium positioning in French soft-ripened cheese AOP zones. |
| Piezoelectric Component Backward Integration | Neutralizes East Asian supply concentration for cutting system assemblers. |
| Servo-Driven Platform Certification | Secures EU Green Deal compliance for Bavarian dairy cooperative contracts. |
| Digital Distribution Configurator Launch | Compresses sales cycles for regional equipment distributors in Netherlands. |
| Plant-Based Analog Customization Partnership | Opens alternative dairy revenue streams beyond traditional cheese processors. |
Study Parameters
Trade association filings, EU Machinery Directive enforcement records, and stainless steel commodity price databases formed the secondary backbone, supplemented by primary interviews with dairy processing plant engineers, OEM procurement teams at GEA Group and Marel, aftermarket service heads, and food manufacturer maintenance directors. Bottom-up and top-down triangulation validated equipment shipment volumes against capital expenditure disclosures from cooperative dairy networks.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks across product type, technology, capacity tier, and end-user segmentation dimensions. CAGRs were derived from installed base replacement cycles and automation penetration curves. Industry-specific inputs included FDA 21 CFR approval pipeline status and EU Green Deal motor efficiency mandate implementation timelines.
Caveats apply where FDA food-contact substance approval delays or REACH chemical restriction expansions could materially shift the outlook. A model refresh is warranted upon material change in ultrasonic transducer supply availability or stainless steel input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Cream Separator Market