
 Commercial Cheese Shredder Market | 2026-2036
Commercial Cheese Shredder Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Cheese Shredder Market Outlook
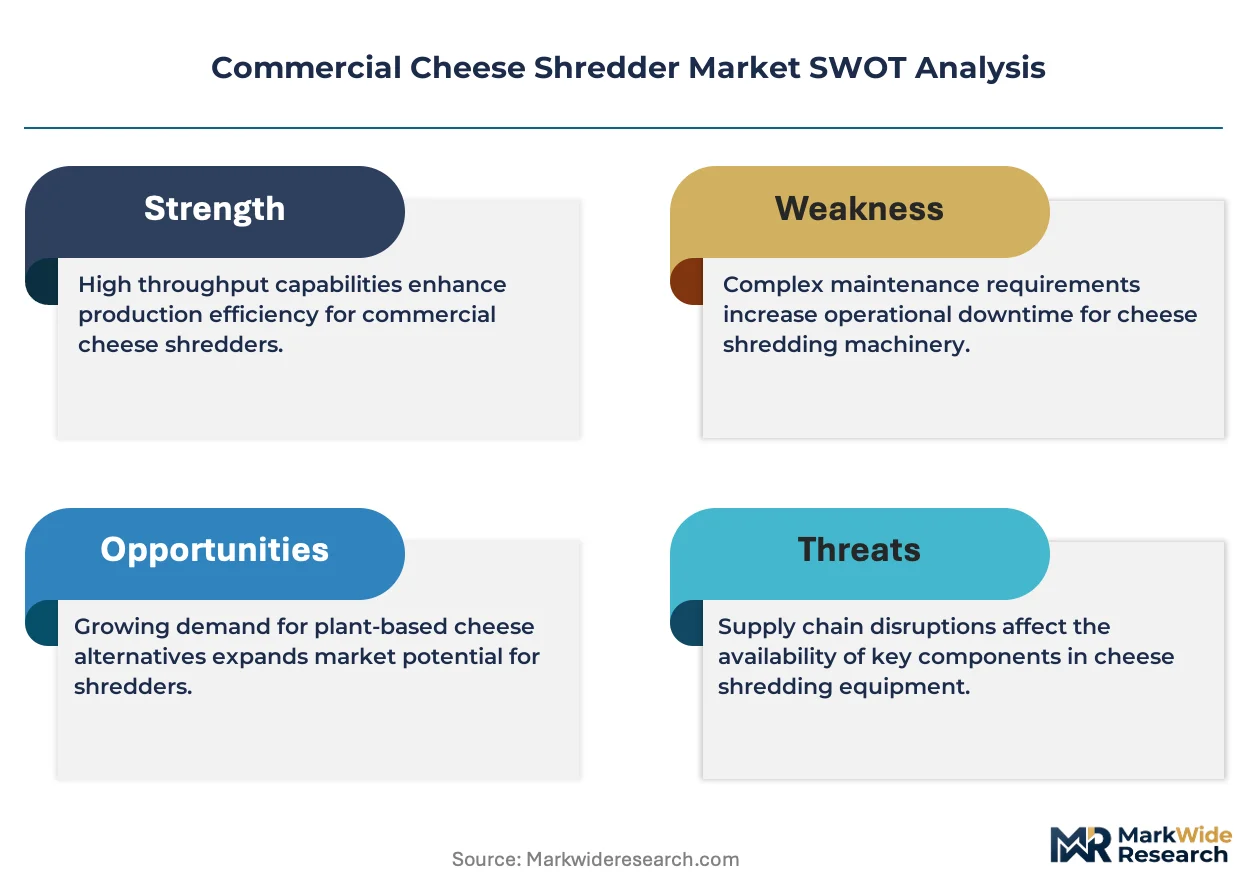
Multi-source procurement among foodservice distributors is shifting toward preferred-vendor agreements with specialized equipment makers. GEA Group AG leverages its integrated dairy processing systems to bundle shredder sales with downstream line equipment. Urschel Laboratories Inc. sustains its position through precision-cutting technology leadership across cheese, vegetable, and protein applications. Weber Maschinenbau GmbH anchors its competitive stance with German-engineered sanitation designs that reduce allergen cross-contamination risks.
A commercial cheese shredder is an electromechanical or manually operated food processing machine designed to reduce cheese blocks into uniform shreds through rotary blades or drum graters, typically constructed from stainless steel with motors rated between 0.5 and 3 horsepower for continuous-duty cycles. Its primary commercial purpose is to standardize portion control and labor efficiency in high-volume food preparation environments where consistency directly impacts product cost and customer experience. Electric units dominate installed capacity across North American and European food manufacturing, while compact manual variants retain margin pools in small-scale catering and specialty retail where capital constraints limit automation investment. Heavy-duty configurations with extra-large capacity ratings represent the fastest-growing product tier as pizza chains and prepared-meal producers scale central commissary operations.
NSF International standards govern food-contact surface requirements and clean-in-place protocols for commercial cheese shredders sold in the United States, while the EU Machinery Directive and CE marking obligations shape safety interlock and noise-emission specifications for European deployments. FDA food code provisions on time-temperature controls indirectly drive demand for shredders with refrigerated feed hoppers that maintain cheese integrity during processing. Stakeholders must monitor evolving state-level organic certification rules and carbon-footprint labeling requirements that could reshape material sourcing for shredder housings and motor assemblies.
Market Dynamics
Automation mandates in dairy processing plants are compressing replacement cycles for legacy shredding equipment, forcing capital redeployment toward continuous-duty electromechanical systems that integrate with downstream packaging lines.
Growth Catalysts
- NSF/ANSI sanitation standards:North American food manufacturing plants face mandatory equipment upgrades to meet clean-in-place protocols, accelerating shredder replacement demand across Wisconsin and California dairy clusters.
- Central commissary scaling:Pizza chains and prepared-meal producers are consolidating production into high-volume facilities that require extra-large capacity shredders with refrigerated feed hoppers.
- EU Machinery Directive compliance:European deployments now require enhanced safety interlocks and noise-emission controls, creating specification premiums for German-engineered sanitation designs.
Market Restraints
- Stainless steel input volatility:Shredder housing and blade material costs fluctuate with nickel and chromium spot markets, compressing margins for equipment assemblers without captive metal supply.
- Specialized motor supplier concentration:Continuous-duty motors rated 0.5–3 horsepower for food-grade applications source predominantly from German and Japanese suppliers, exposing buyers to lead-time risk.
- Manual variant substitution:Compact hand-cranked shredders retain cost advantage in small-scale catering and specialty retail where capital constraints block automation investment.
Strategic Opportunities
- Carbon-footprint labeling mandates:Emerging state-level requirements for equipment environmental disclosure create first-mover advantage for shredder makers with verified low-emission motor assemblies and recyclable housing materials.
- Allergen cross-contamination protocols:Rapid-sanitation designs that reduce changeover time between cheese varieties command premium positioning in multi-product dairy processing facilities.
- Preferred-vendor consolidation:Foodservice distributors are exiting multi-source procurement in favor of bundled equipment agreements with specialized makers who integrate shredders with upstream block-handling systems.
Industry Challenges
- Clean-in-place engineering talent scarcity:Equipment manufacturers struggle to hire fluid dynamics specialists capable of designing sanitation protocols that satisfy both NSF surface requirements and FDA time-temperature controls.
- Legacy system integration friction:New electromechanical shredders must interface with existing dairy processing lines running proprietary control architectures, extending commissioning timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Cheese Shredder Market |
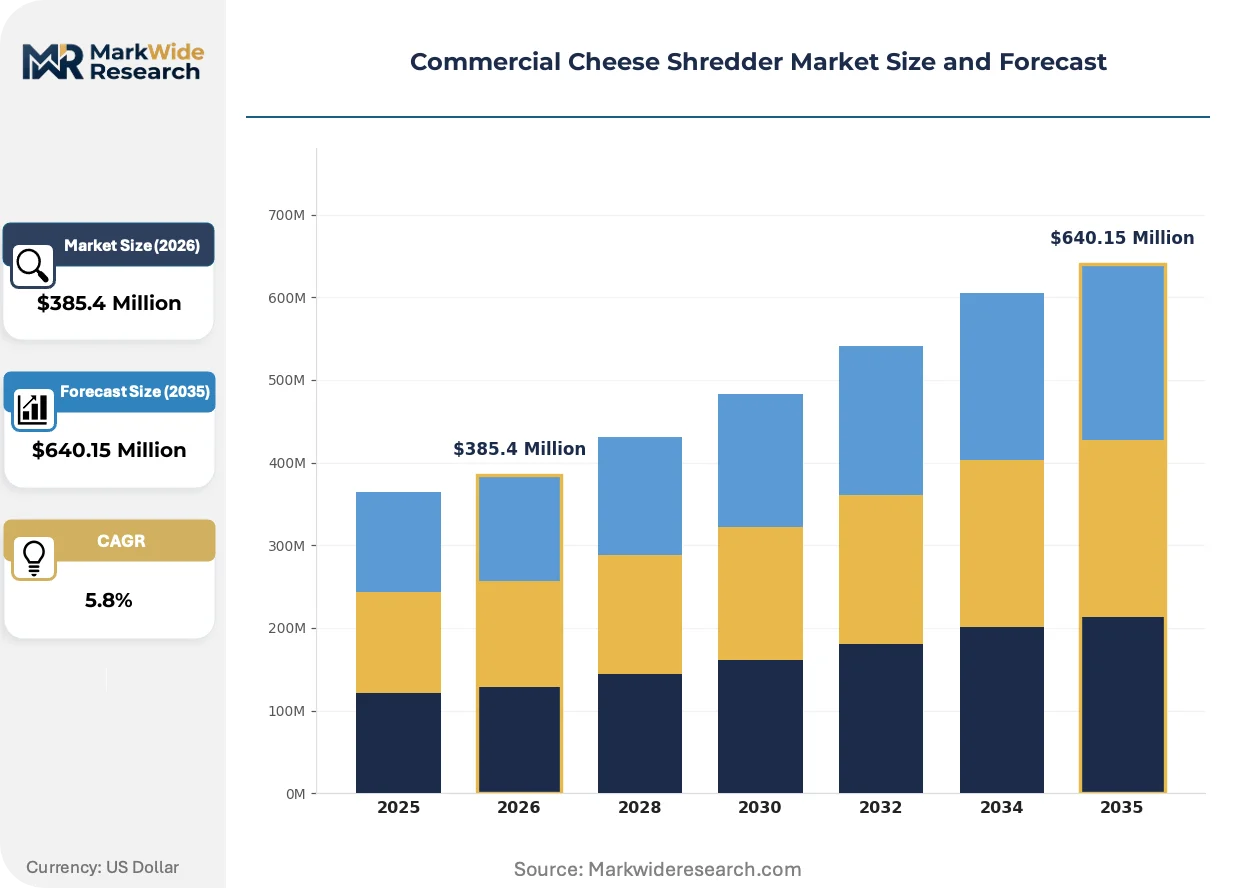
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Heavy-Duty, Compact End User: Restaurants, Supermarkets, Catering Services, Food Manufacturing Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | FAM, Urschel Laboratories Inc., GEA Group AG, MIMASA, Marchant Schmidt Inc., Weber Maschinenbau GmbH, Omcan Inc., Deville Technologies, Palazzolo Cheese Hog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Cheese Shredder Market Strategic Shifts
Rotary blade precision engineering and smart motor controls are converging to reshape equipment performance standards, while regulatory pressure on sanitation and carbon disclosure accelerates specification divergence between premium and economy product tiers.
Precision-cutting drum technology with adjustable grate configurations is expanding into high-volume pizza production facilities. Quick-service restaurant chains operating central commissaries in Texas and Illinois are adopting these systems to standardize shred geometry across multiple cheese varieties. The technology is expanding into territory previously served by fixed-blade equipment, compressing the addressable market for basic rotary designs.
REACH chemical restrictions and evolving EU F-Gas Regulation are reshaping lubricant specifications for food-contact machinery. Equipment makers must now certify bearing greases and motor coolants against substance authorization lists, adding compliance cost but creating specification barriers for non-European competitors. German and Italian dairy equipment exporters are responding fastest, embedding compliant fluid systems into base product configurations.
Outcome-based maintenance contracts are displacing traditional break-fix service arrangements among large-scale food manufacturers. Buyers in California and New York now demand uptime guarantees with penalty clauses, forcing shredder vendors to install predictive vibration sensors and remote diagnostics. This shift concentrates service revenue with equipment makers who control proprietary telemetry platforms, marginalizing third-party maintenance providers.
Commercial Cheese Shredder Market Segmentation
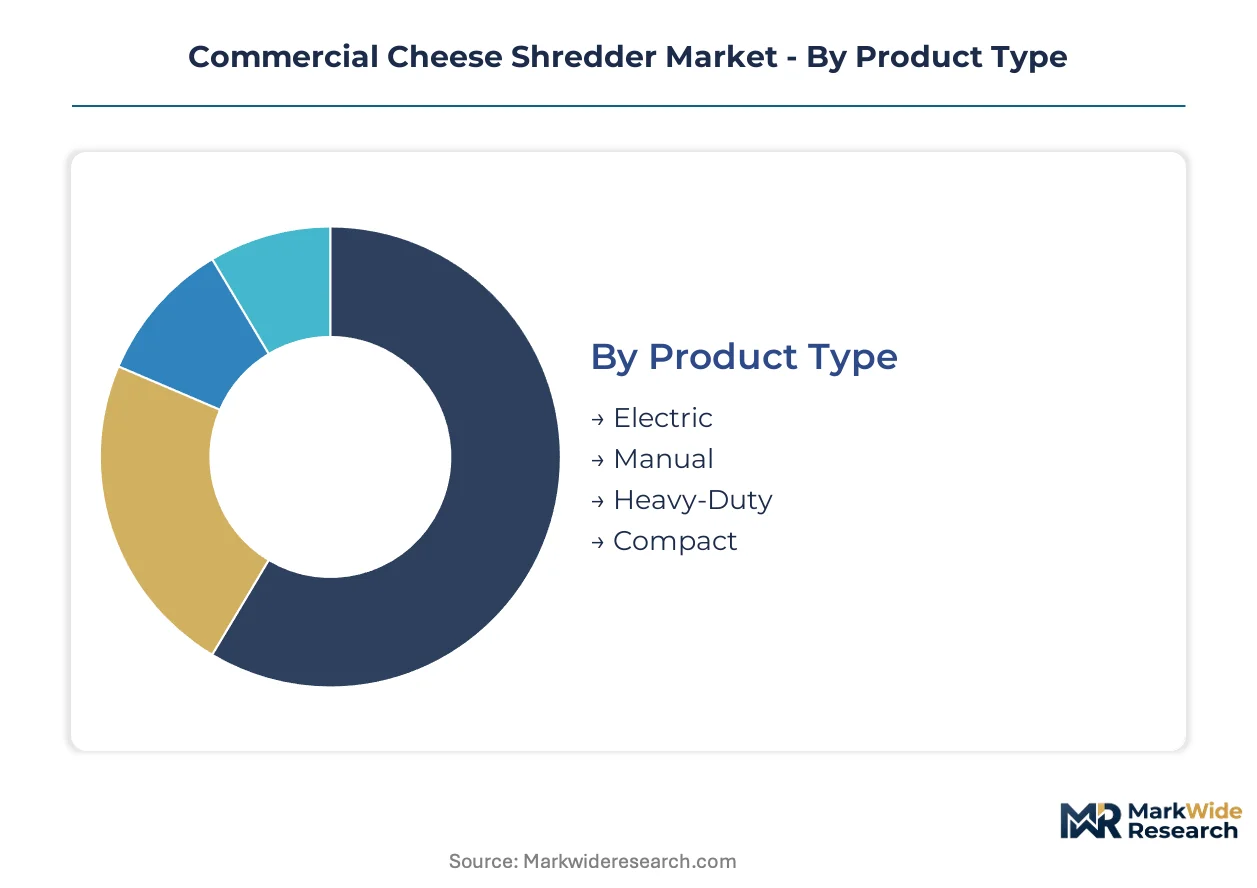
Equipment specification tiers in the commercial cheese shredder market align directly with capital deployment cycles and regulatory compliance burdens. Buyers segment procurement decisions across product type, end-use application, throughput capacity, and channel access, with each dimension carrying distinct margin and replacement-frequency implications for manufacturers.
Product Type:
Replacement cycles accelerate where sanitation mandates force upgrades from legacy manual systems to electromechanical platforms with clean-in-place certification.
- Electric:Continuous-duty motors rated 0.5–3 horsepower dominate food manufacturing installations across Wisconsin and California dairy clusters. NSF/ANSI surface requirements and FDA time-temperature controls drive replacement demand from fixed-blade legacy systems toward smart motor controls with predictive vibration sensors.
- Heavy-Duty:Extra-large capacity configurations integrate with downstream packaging lines in pizza chain central commissaries. Rapid-sanitation designs that reduce allergen changeover time command premium positioning in multi-product dairy processing facilities consolidating production into Texas and Illinois hubs.
- Manual:Hand-cranked compact units retain cost advantage in specialty retail where capital constraints block automation investment.
- Compact:Space-constrained catering operations favor reduced-footprint designs with refrigerated feed hoppers for cheese integrity maintenance.
Electric units sit at the top of the volume ranking, with Heavy-Duty configurations climbing the fastest as commissary scaling accelerates.
End User:
Application-specific throughput requirements and labor cost structures create divergent specification demands across buyer categories.
- Food Manufacturing:Dairy processing plants in Wisconsin and California face compressed replacement cycles as automation mandates eliminate manual shredding lines. Continuous-duty electromechanical systems with CE-marked safety interlocks integrate with proprietary downstream control architectures.
- Restaurants:Quick-service chains operating Texas and Illinois central kitchens standardize shred geometry through precision-cutting drum technology with adjustable grate configurations.
- Catering Services:Event-based volume volatility favors flexible capacity deployment with rapid-sanitation protocols between cheese variety changeovers.
- Supermarkets:In-store prepared-meal counters drive demand for compact refrigerated units maintaining product integrity during intermittent duty cycles.
Food Manufacturing captures the dominant revenue share, though Restaurants gain share fastest through commissary consolidation.
Capacity:
Throughput tier selection correlates with facility scale and product mix complexity in dairy processing operations.
- Extra Large:Central commissary deployments in Texas and Illinois require maximum throughput for pizza chain supply networks. Refrigerated feed hoppers and precision-cutting drum systems address FDA time-temperature controls while standardizing portion geometry.
- Large:Regional dairy processing facilities balance throughput against legacy line integration constraints, requiring electromechanical platforms compatible with proprietary control architectures.
- Medium:Mid-scale catering and prepared-meal producers seek flexible capacity without full commissary capital commitment.
- Small:Specialty retail and boutique foodservice operations prioritize footprint reduction over throughput maximization.
Extra Large capacity leads installed base value, with Large capacity expanding most quickly through regional facility upgrades.
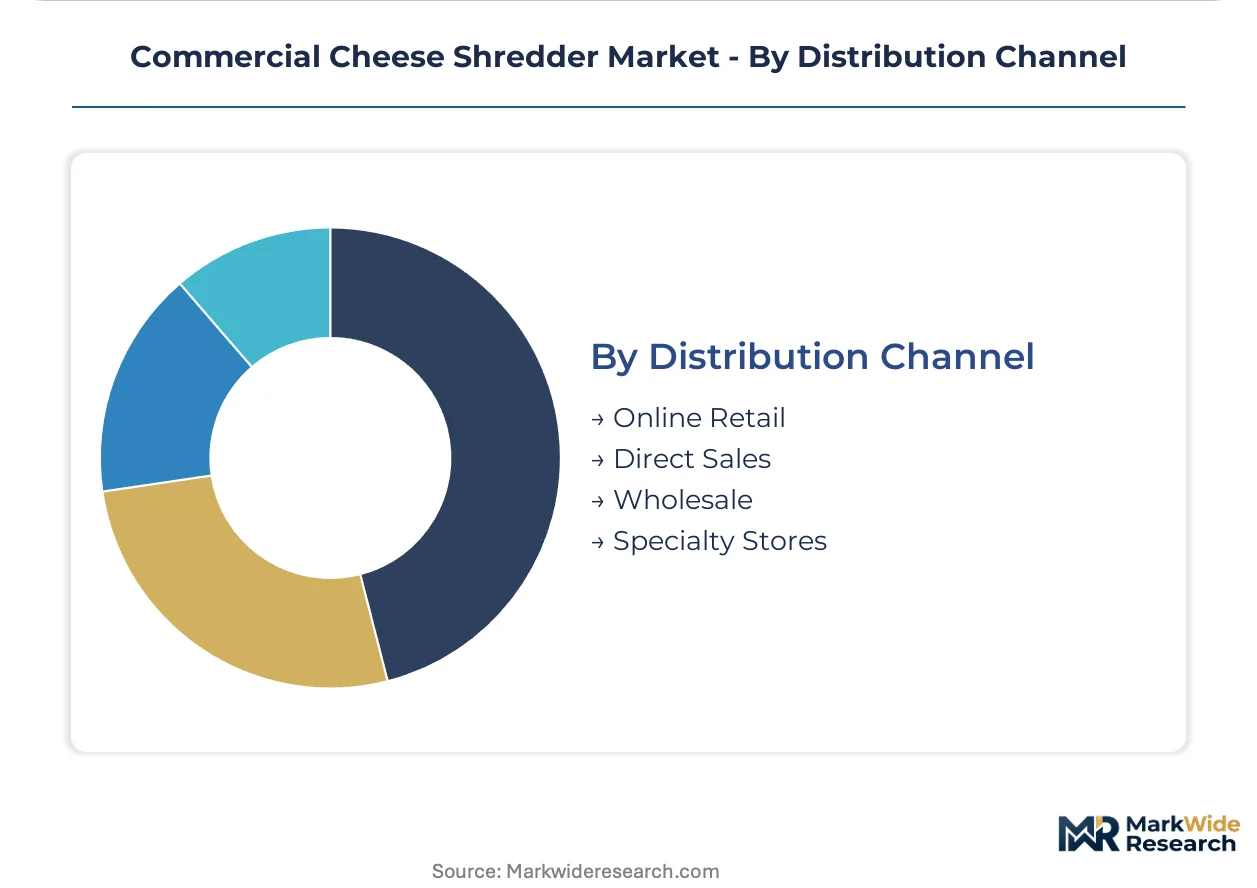
Distribution Channel:
Channel selection reflects buyer sophistication, service requirements, and bundling preferences for integrated dairy processing systems.
- Direct Sales:Large-scale food manufacturers demand bundled equipment agreements with specialized makers integrating shredders with upstream block-handling systems. Outcome-based maintenance contracts with uptime guarantees and penalty clauses concentrate service revenue with OEMs controlling proprietary telemetry platforms.
- Wholesale:Foodservice distributors exit multi-source procurement in favor of preferred-vendor relationships with equipment makers offering downstream line integration.
- Online Retail:Compact manual and electric units for small-scale catering and specialty retail bypass traditional distribution through digital procurement platforms.
- Specialty Stores:Regional dairy equipment dealers provide localized commissioning support for legacy system integration challenges.
Direct Sales dominates transaction value, while Wholesale gains traction fastest through distributor consolidation into preferred-vendor frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin and California dairy processing clusters drive replacement demand for high-capacity electromechanical shredders as automation mandates eliminate manual production lines. Equipment procurement concentrates where FDA food code enforcement intersects with large-scale cheese manufacturing infrastructure.
United States
Central commissaries in Texas and Illinois standardize shred geometry through precision-cutting drum systems for pizza chain networks. NSF/ANSI sanitation standards mandate clean-in-place protocols that accelerate equipment replacement cycles. Wisconsin dairy processors deploy extra-large capacity shredders with refrigerated feed hoppers to maintain cheese integrity during continuous-duty operations.
Germany
German-engineered sanitation designs command specification premiums across European dairy equipment procurement. EU Machinery Directive compliance requirements for enhanced safety interlocks and noise-emission controls reshape product certification obligations. Baden-Württemberg and Bavaria industrial clusters anchor production of continuous-duty motors rated for food-grade applications.
Italy
Emilia-Romagna cheese producers seek rapid-sanitation designs that reduce allergen changeover time between variety runs. REACH chemical restrictions reshape lubricant specifications for food-contact machinery bearing systems. Lombardy dairy processing facilities integrate shredders with proprietary downstream packaging line control architectures.
Canada
Ontario and Quebec food manufacturers adopt outcome-based maintenance contracts with uptime guarantees and penalty clauses. Health Canada food safety provisions drive demand for equipment with verified clean-in-place certification. Regional dairy clusters near Toronto and Montreal prioritize legacy system integration capabilities in new electromechanical procurement.
France
Île-de-France prepared-meal producers consolidate production into high-volume facilities requiring heavy-duty shredder configurations. ECHA substance authorization lists for bearing greases and motor coolants add compliance cost barriers for non-European equipment competitors. Auvergne-Rhône-Alpes cheese processing operations emphasize carbon-footprint labeling readiness in equipment selection criteria.
Commercial Cheese Shredder Market Competitive Environment
Global majors compete with regional champions across integrated dairy processing systems versus standalone equipment specialization. The vendor base stratifies between bundled line integrators, precision-cutting technology specialists, and sanitation-focused engineering houses. Three archetypes dominate: diversified industrial conglomerates with downstream integration capabilities, mid-scale specialists in precision cutting applications, and regional fabricators emphasizing compliant material specifications. Competitive moves concentrate on preferred-vendor consolidation with foodservice distributors and outcome-based service contract structures that capture recurring revenue.
Within the diversified industrial tier, GEA Group AG and Urschel Laboratories Inc. exemplify contrasting strategic positions. GEA Group AG anchors bundled equipment agreements that integrate shredders with upstream block-handling and downstream packaging systems. Urschel Laboratories Inc. occupies a specialist position across precision-cutting applications spanning cheese, vegetable, and protein processing categories. Weber Maschinenbau GmbH represents the engineering-intensive archetype, with German GmbH structure signaling formalized technical standards compliance. These three entities collectively illustrate the competitive spectrum from integrated systems provision through component specialization.
| Leading Market Players |
|---|
| FAM |
| Urschel Laboratories Inc. |
| GEA Group AG |
| MIMASA |
| Marchant Schmidt Inc. |
| Weber Maschinenbau GmbH |
| Omcan Inc. |
| Deville Technologies |
| Palazzolo Cheese Hog |
| Others |
Value Chain & Pricing Dynamics
Backward integration into stainless steel sourcing and continuous-duty motor production anchors competitive positioning for equipment assemblers facing nickel and chromium spot market volatility. German and Japanese motor suppliers command specification premiums that cascade through OEM pricing structures, while captive metal supply insulates vertically integrated manufacturers from margin compression.
Pricing Analysis
Stainless steel input cost pass-through dominates equipment pricing, with nickel and chromium spot market movements compressing assembler margins within quarters. Pricing stratifies across NSF-certified premium tiers, CE-marked European configurations, and uncertified economy units for emerging markets. Cost compression in mid-tier electric shredders is intensifying because food manufacturing buyers consolidate procurement into preferred-vendor agreements. Small-scale catering operators exhibit highest price sensitivity, while dairy processing clusters in Wisconsin and California prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Refurbishment flows for continuous-duty motors and precision-cutting drums create secondary supply channels that extend equipment lifecycle and dampen replacement demand. Manufacturing concentrates in Germany, Italy, and the United States, with Baden-Württemberg and Bavaria clusters anchoring motor production. Supply chains draw from stainless steel mills, specialized bearing manufacturers, and food-grade lubricant formulators facing REACH authorization constraints. Single-source vulnerability in 0.5–3 horsepower motor ratings exposes buyers to lead-time risk. Distribution runs through direct OEM sales for large manufacturers and wholesale foodservice channels for compact units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial cheese shredder market functions as a stable compounder where automation mandates in dairy processing plants generate predictable replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Anchor market position through outcome-based maintenance contracts with uptime guarantees that concentrate service revenue and marginalize third-party providers. Invest in clean-in-place engineering talent to address fluid dynamics specialist scarcity that delays NSF certification timelines. Defend against emerging Asian competitors by embedding REACH-compliant lubricant systems as base configurations rather than optional upgrades.
For New Entrants and Emerging Players: Enter via rapid-sanitation design specialization targeting multi-product dairy facilities in Emilia-Romagna and Lombardy where allergen changeover protocols command premium positioning. Target compact refrigerated units for supermarket prepared-meal counters, a segment where capital constraints block incumbent automation bundling. Pursue digital-first distribution through online retail platforms bypassing consolidated wholesale channels.
For Investors and Strategic Acquirers: Roll-up economics work for precision-cutting technology specialists because fragmented regional fabricators lack R&D scale to match adjustable grate configuration advances. Five-to-ten-year viability hinges on carbon-footprint labeling readiness as state-level mandates emerge. Monitor ECHA substance authorization list expansions for bearing grease restrictions that would force formulation redesigns and consolidation among compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Preferred-Vendor Consolidation | Bundled equipment agreements with foodservice distributors capture recurring service revenue streams. |
| Clean-in-Place Certification Investment | NSF/ANSI compliance opens Wisconsin and California dairy cluster replacement cycles. |
| Predictive Maintenance Platform Deployment | Remote vibration sensors enable outcome-based contracts with penalty-backed uptime guarantees. |
| REACH-Compliant Lubricant Integration | Pre-certified bearing systems create specification barriers for non-European competitors. |
| Carbon-Footprint Labeling Preparation | Verified low-emission motor assemblies secure first-mover advantage under emerging state mandates. |
Study Parameters
Coverage spans North America, Europe, and select Asia-Pacific markets, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with dairy processing plant engineers, foodservice distributor procurement directors, OEM sales executives, and aftermarket service managers. Secondary sources included FDA food code provisions, EU Machinery Directive guidance documents, NSF/ANSI certification databases, and stainless steel trade flow data. Bottom-up equipment unit estimates triangulated against top-down dairy industry capital expenditure benchmarks.
Granularity-level modeling addressed product type, end-use application, throughput capacity tier, and distribution channel across the projection horizon. Segment-specific CAGRs derived from replacement cycle analysis, regulatory compliance deadlines, and automation penetration curves. Forecast inputs incorporated dairy processing employment trends, pizza chain commissary expansion announcements, and evolving state-level organic certification rules.
The model holds under stable stainless steel pricing and consistent regulatory enforcement; deviation in nickel spot volatility or sudden EU F-Gas Regulation amendments would shift equipment procurement timing. Practitioners should monitor ECHA substance authorization list updates and state carbon-labeling rulemakings for early signals of specification disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Milk Pasteurization Machines Market