
 Skating Shoes Market | 2026-2036
Skating Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Skating Shoes Market Outlook
Recreational users is rotating toward premium customizable models as fitness-oriented consumers replace occasional hobbyists as the dominant buyer archetype. Decathlon SA leverages its vertically integrated sporting goods network to control entry-level price points across European retail. Nike Inc. competes through R&D intensity in lightweight composite uppers that reduce fatigue during extended urban skating sessions. K2 Sports Europe GmbH anchors its position in North American inline hockey through specialized boot constructions that emphasize ankle stability and power transfer.
Skating shoes are engineered footwear systems combining rigid polymer or carbon-fiber shells with precision-molded liners and chassis-mounted wheel assemblies, designed to translate human locomotion into controlled rolling motion across hard surfaces. Inline skates dominate commercial volume due to their versatility across fitness, commuter, and aggressive skating disciplines, while speed skates command concentrated margin pools among competitive athletes requiring heat-moldable carbon boots. Composite materials are displacing leather in premium tiers because manufacturers can tune stiffness-to-weight ratios more precisely, though leather sustains heritage positioning in artistic quad skating where flexibility and aesthetic tradition matter.
CE marking governs mechanical safety and chemical compliance for skating shoes sold across European markets, while the EU Green Deal's extended producer responsibility frameworks are reshaping material sourcing decisions. In the United States, the Consumer Product Safety Commission monitors injury reporting thresholds that indirectly influence design standards for ankle support systems. ASTM International publishes voluntary performance specifications that major brands reference for liability insulation. Stakeholders must monitor how regulatory divergence between European sustainability mandates and American liability standards fragments supply chain compliance costs.
Market Dynamics
The EU Green Deal's extended producer responsibility frameworks are forcing manufacturers to reconfigure material sourcing and end-of-life collection systems across European supply chains. This regulatory pressure compounds with recreational buyer demand for customizable, bio-based products to reshape competitive investment priorities.
Growth Catalysts
- Urban Fitness Infrastructure:Municipal skate parks and dedicated lanes in Berlin, Copenhagen, and Amsterdam accelerate replacement cycles among commuter and fitness-oriented users. Cities expand maintenance budgets for polyurethane wheel-friendly surfaces.
- REACH-compliant Bio-synthetics:ECHA-registered thermoplastic elastomers derived from castor oil enable manufacturers to meet chemical traceability mandates while reducing petroleum dependence in boot shells and liners.
- Inline Hockey League Expansion:Organized amateur leagues across Germany, the Czech Republic, and Sweden drive specialized equipment demand with season-bound procurement patterns.
Market Restraints
- Petrochemical Price Volatility:Polyurethane foam and polycarbonate shell materials expose margin structures to naphtha and propylene feedstock fluctuations.
- Carbon-Fiber Supply Concentration:Toray Industries, Mitsubishi Chemical, and SGL Carbon control premium-grade precursor supply, creating bottleneck risk for heat-moldable speed skate manufacturers.
- Quad Skate Substitution:Artistic roller skating's heritage positioning in dance and rink disciplines limits inline conversion in Eastern European and Latin American recreational markets.
Strategic Opportunities
- Modular Upgrade Systems:Frame-swappable chassis designs allow users to convert between fitness, urban, and aggressive wheel configurations without full boot replacement.
- EU Green Deal Material Credits:Bio-based content thresholds unlock preferential procurement status for municipal and institutional buyers under national green public procurement schemes.
- Direct-to-Consumer Heat Molding:At-home liner customization kits bypass specialty retail dependency and capture margin from intermediate recreational users seeking personalized fit.
Industry Challenges
- CE Marking Conformity Assessment:Mechanical safety testing for ankle retention systems and chassis impact resistance creates 8-14 month certification timelines for new product introductions.
- Legacy Inventory Obsolescence:Petroleum-based stockpiles face stranded asset risk as retailers demand bio-based certification documentation under EU Green Deal disclosure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skating Shoes Market |
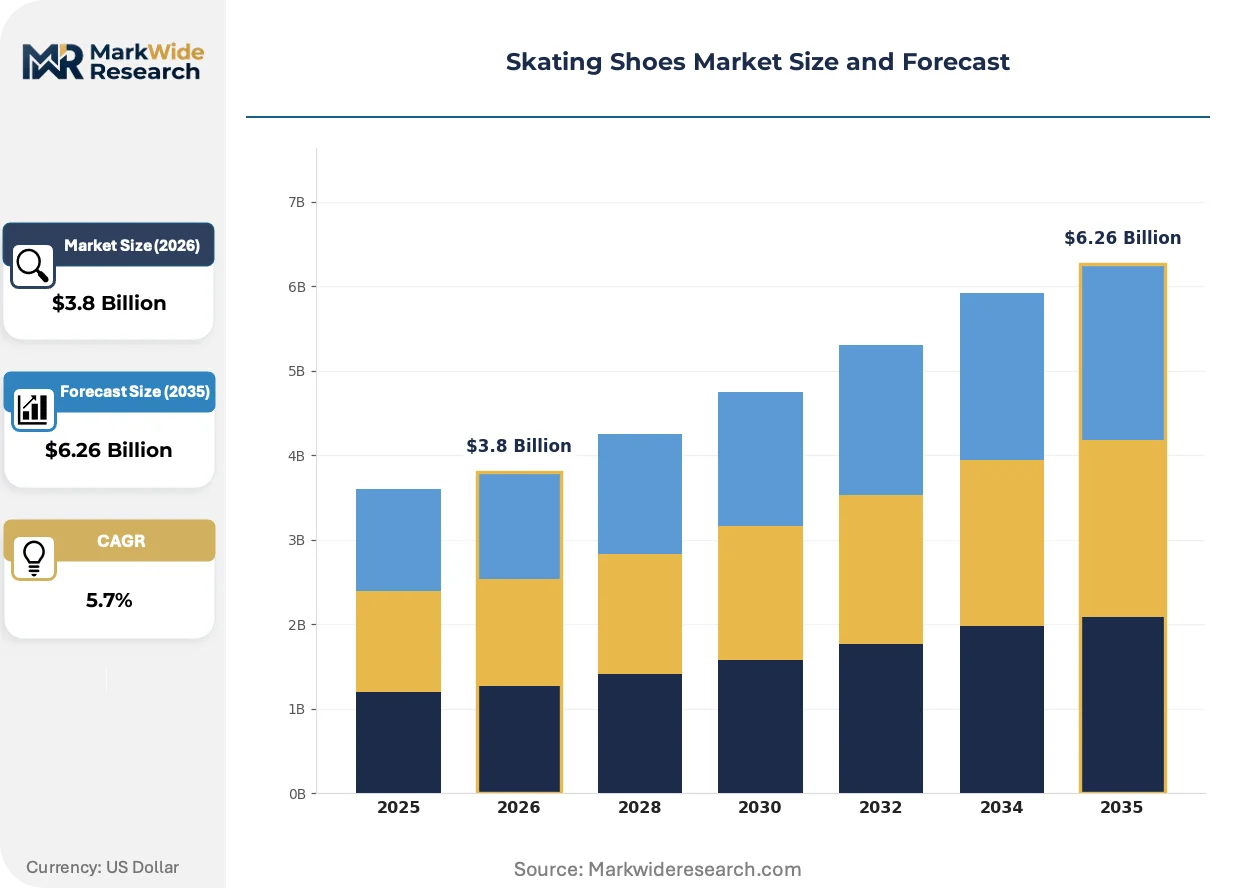
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Skates, Quad Skates, Freestyle Skates, Speed Skates Material: Leather, Synthetic, Composite, Rubber End User: Professionals, Amateurs, Recreational Users, Children Feature: Lightweight, Waterproof, High Ankle Support, Customizable |
| Companies Covered | Decathlon SA, Nike Inc., K2 Sports Europe GmbH, New Balance Athletics Inc., Tecnica Group SpA, Powerslide GmbH, Bont Skates Online Shop, EDEA srl, Riedell Shoes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skating Shoes Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to redefine product architecture and supply chain transparency. Manufacturers face simultaneous pressure to reduce petroleum dependence and maintain performance benchmarks established by carbon-fiber elite tiers.
Thermoplastic polyurethane (TPU) foam liners with programmable density gradients are displacing traditional EVA foam in mid-premium fitness skates. Recreational users seeking extended urban sessions adopt heat-activated customization without specialty retail visits. This material shift compresses distribution margins previously captured by bootfitting services while enabling mass-market personalization.
The EU Green Deal's digital product passport requirements mandate granular material disclosure for skating shoes sold across European markets. Manufacturers must document polymer origins, additive compositions, and recycling pathways through blockchain-verified supply chain records. German and French retailers now require passport completion before shelf placement, accelerating compliance investment among mid-tier suppliers.
Subscription-based wheel replacement programs are emerging as the dominant aftermarket model for high-frequency urban commuters. Users in Copenhagen and Amsterdam pay monthly fees for polyurethane wheel refreshment rather than purchasing full sets. This service unbundling shifts manufacturer revenue toward consumables and captures lifetime value from fitness-oriented buyers who previously exited after initial purchase.
Skating Shoes Market Segmentation
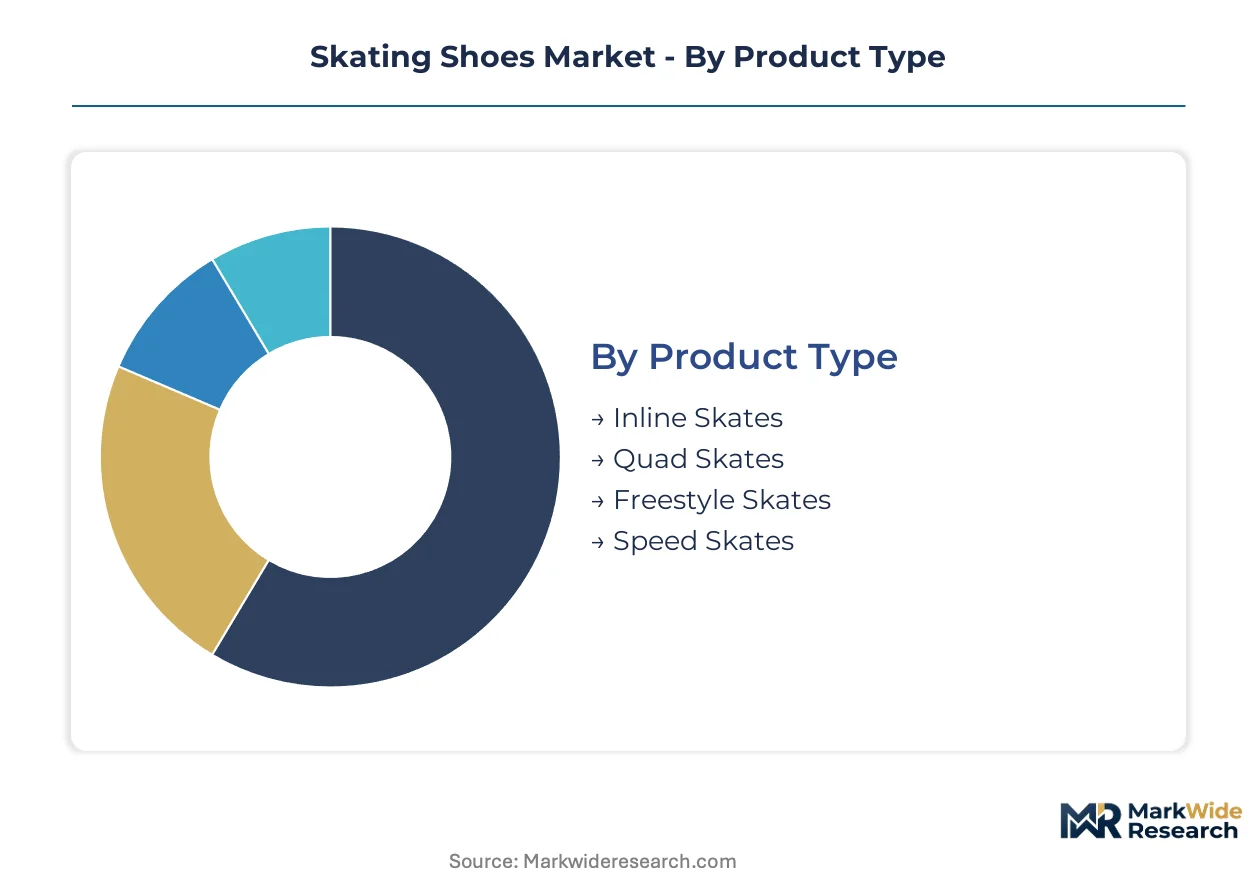
Skating shoes fragment across four distinct category axes that determine manufacturing investment priorities and margin capture potential. Product architecture and material composition drive technical differentiation, while end-user archetypes and feature specifications shape pricing power and channel strategy.
Product Type:
Inline skates face the most intense substitution pressure from quad alternatives in artistic and rink disciplines, while speed skates confront concentrated carbon-fiber supply bottlenecks that constrain volume scaling.
- Inline Skates:Polyurethane wheels mounted on aluminum or composite frames dominate commercial volume across fitness, commuter, and aggressive skating disciplines. Demand concentrates most visibly in Germany, where municipal skate infrastructure in Berlin and dedicated urban lanes in Copenhagen accelerate replacement cycles among fitness-oriented commuters.
- Quad Skates:Four-wheel configurations with rubber or polyurethane tires sustain heritage positioning in artistic roller skating and rink disciplines. Eastern European and Latin American recreational markets resist inline conversion, preserving stable demand for leather-boot quad systems where flexibility and aesthetic tradition matter more than speed efficiency.
- Freestyle Skates:Reinforced boot shells and grind plates engineered for urban trick skating and skate park use. Aggressive skating communities in Amsterdam and Barcelona drive specialized frame and wheel configurations.
- Speed Skates:Heat-moldable carbon-fiber boots with low-cut ankle profiles optimize power transfer for competitive racing. Toray Industries and Mitsubishi Chemical precursor supply concentration creates procurement risk for manufacturers targeting elite athlete segments.
Inline skates retain volume leadership; speed skates hold the steepest expansion curve.
Material:
Cost tier stratification separates petroleum-dependent synthetics from bio-based alternatives that unlock EU Green Deal procurement advantages.
- Synthetic:Thermoplastic polyurethane and polycarbonate shell materials enable precise stiffness-to-weight tuning at mid-market price points. REACH-compliant bio-synthetics derived from castor oil are displacing petroleum-based formulations in European supply chains subject to ECHA traceability mandates.
- Composite:Carbon-fiber and glass-fiber reinforced polymers dominate premium heat-moldable speed skate construction. German and French retailers now require digital product passport documentation before shelf placement, accelerating compliance investment for composite-intensive product lines.
- Leather:Full-grain and synthetic leather uppers sustain artistic quad skate positioning where heritage aesthetics and flexibility specifications prevail. Eastern European rink operators maintain leather procurement for dance discipline equipment.
- Rubber:Natural and synthetic rubber compounds form quad skate wheels and select inline skate tire formulations. Petrochemical price volatility in naphtha feedstocks exposes margin structures to procurement cost swings.
Synthetic materials command the broadest addressable base; composites capture the highest per-unit margins.
End User:
Customer type determines channel strategy, with recreational users displacing occasional hobbyists as the dominant growth vector.
- Recreational Users:Fitness-oriented urban commuters and casual skaters seeking extended session comfort without competitive specifications. Copenhagen and Amsterdam subscription-based wheel replacement programs capture lifetime value from high-frequency users who previously exited after initial purchase.
- Amateurs:Organized league participants in inline hockey and recreational racing with season-bound procurement patterns. German, Czech, and Swedish amateur leagues drive specialized boot constructions emphasizing ankle stability.
- Professionals:Competitive athletes and sponsored skaters requiring heat-moldable customization and elite-tier chassis performance. Carbon-fiber supply concentration limits manufacturer capacity to serve this segment at scale.
- Children:Adjustable-size boot systems with growth accommodation features and protective specifications. Entry-level price point sensitivity concentrates volume in mass retail channels.
Recreational users anchor volume expansion; professionals sustain premium pricing tiers.
Feature:
Application-specific performance requirements segment demand across urban commuting, competitive racing, and all-weather use cases.
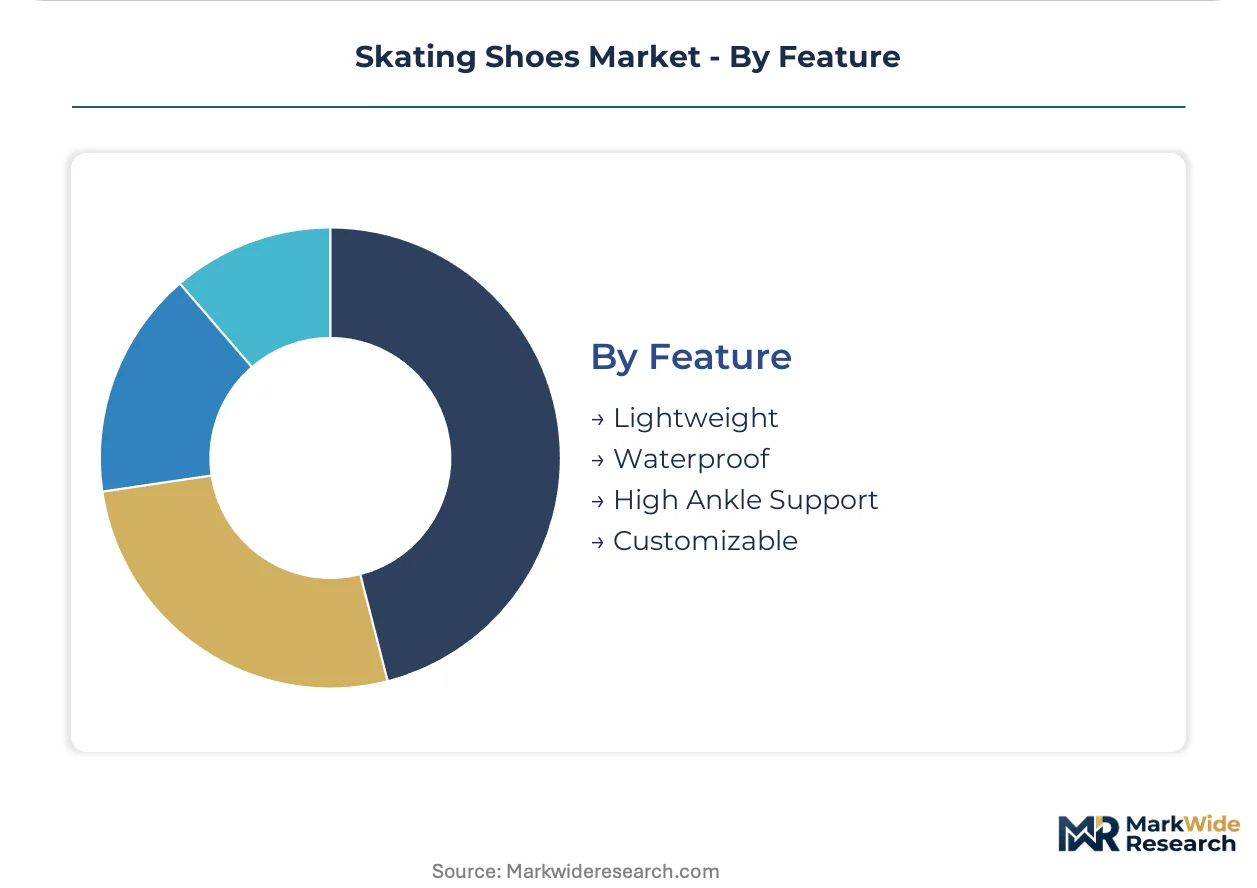
- Lightweight:Composite upper constructions and hollow-frame chassis designs reduce fatigue during extended urban skating sessions. Nike R&D intensity in this specification targets fitness-oriented commuter segments.
- Customizable:Heat-moldable liners and frame-swappable chassis enable personalization without specialty retail dependency. At-home customization kits capture margin from intermediate recreational users.
- High Ankle Support:Reinforced cuff constructions and precision-molded liners stabilize aggressive skating and inline hockey applications. CE marking mechanical safety testing for ankle retention systems creates 8-14 month certification timelines.
- Waterproof:Membrane-lined boot systems and corrosion-resistant hardware for all-weather urban commuting. Northern European climate conditions sustain niche demand despite weight penalties.
Lightweight specifications dominate unit volume; customizable features command the strongest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's dominance in European skating shoe distribution, connecting Bavarian manufacturing clusters to North Sea ports and Danube basin markets.
Germany
Berlin's municipal skate park network and Hamburg's inline hockey league infrastructure drive replacement cycles among fitness commuters and amateur athletes. KBA vehicle safety standards influence chassis impact testing protocols for urban skating equipment. Bavaria's carbon-fiber precursor processing facilities near Munich supply heat-moldable boot manufacturers serving competitive racing segments.
United States
Los Angeles skate park density and New York City's Hudson River Greenway commuter lanes sustain high-frequency urban skating populations. CPSC injury reporting thresholds shape ankle support system design standards for domestic manufacturers. Pacific Northwest composite materials clusters in Oregon supply lightweight shell components to premium fitness skate assemblers.
France
Paris-Île-de-France's RER commuter belt and Lyon-Rhône-Alpes recreational trail networks expand the fitness-oriented user base beyond occasional hobbyists. ANSM chemical safety disclosure requirements accelerate digital product passport adoption for bio-based synthetic materials. The Eindhoven-Strasbourg logistics corridor concentrates distribution warehousing for Western European retail channels.
Netherlands
Amsterdam's dedicated urban skating lanes and Rotterdam's subscription wheel replacement programs capture lifetime value from high-frequency commuters. REACH-compliant castor oil-derived thermoplastic elastomer registration through ECHA enables bio-based boot shell production for EU Green Deal procurement eligibility. Randstad metropolitan logistics hubs coordinate last-mile delivery for direct-to-consumer customization kit distribution.
China
Shenzhen-Pearl River Delta electronics integration capabilities and Yangtze River Delta polymer processing capacity support mid-market synthetic skate assembly. SAMR product quality supervision and GB standards compliance create export certification requirements for European-bound shipments. Zhejiang province's thermoplastic polyurethane foam molding facilities supply programmable density liner components to global brands.
Skating Shoes Market Competitive Environment
Concentration sits with diversified sporting goods conglomerates and specialized European boot fabricators. The vendor base splits between mass-market retailers controlling entry-level price points and premium-tier specialists capturing heat-moldable customization margins. Two strategic archetypes dominate: vertically integrated sporting goods networks leveraging retail footprint, and engineering-focused specialists emphasizing chassis precision and material science. Competitive moves center on bio-based material certification for EU Green Deal compliance and direct-to-consumer fit customization bypassing specialty retail.
Within the diversified sporting goods tier, Decathlon SA and Nike Inc. exemplify scale-driven market presence. Decathlon's vertically integrated retail network spans European mass-market channels, while Nike's composite upper R&D intensity targets extended urban session fatigue reduction. K2 Sports Europe GmbH anchors the specialized fabricator archetype, with its GmbH structure indicating German corporate organization and inline hockey boot construction expertise. These three occupy positions across the pricing spectrum from entry-level adjustable children's systems to elite-tier carbon-fiber racing platforms.
| Leading Market Players |
|---|
| Decathlon SA |
| Nike Inc. |
| K2 Sports Europe GmbH |
| New Balance Athletics Inc. |
| Tecnica Group SpA |
| Powerslide GmbH |
| Bont Skates Online Shop |
| EDEA srl |
| Riedell Shoes Inc. |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber precursor capacity utilization at Toray Industries and Mitsubishi Chemical facilities shapes both supply concentration and price floors for heat-moldable speed skate tiers. Bavarian composite processing clusters leverage scale economies to defend premium positioning against mid-market synthetic alternatives, while REACH-compliant bio-synthetic registration costs erect entry barriers that protect incumbent margin structures.
Pricing Analysis
Volume-discount tiering structures separate elite heat-moldable carbon-fiber platforms from mass-market adjustable children's systems. Three-tier pricing stratification across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from petrochemical feedstock volatility in polyurethane foam and polycarbonate shell materials. Children and entry-level recreational users exhibit highest price sensitivity, while competitive professionals absorb premium tiers for customization performance.
Supply Chain Analysis
Just-in-time inventory strategies dominate synthetic boot assembly in Zhejiang province, while European manufacturers maintain strategic stockpiles of carbon-fiber precursor against Toray supply bottlenecks. Raw material dependencies center on castor oil-derived thermoplastic elastomers, naphtha-based polyurethane formulations, and Japanese carbon-fiber precursor. Single-source vulnerability concentrates in Mitsubishi Chemical and SGL Carbon supply agreements. Distribution runs through Randstad metropolitan logistics hubs and the Eindhoven-Strasbourg corridor for Western European retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. EU Green Deal extended producer responsibility frameworks and CE marking conformity timelines create structural barriers that favor incumbents with compliance infrastructure already deployed.
For Market Incumbents: Secure bio-based synthetic certification pipelines ahead of national green public procurement scheme deadlines. Deepen backward integration into castor oil-derived thermoplastic elastomer supply to deflect petrochemical price volatility. Lock in frame-swappable chassis patent portfolios before modular upgrade systems commoditize across mid-tier competitors.
For New Entrants and Emerging Players: Differentiate on direct-to-consumer heat-molding service models that bypass specialty retail dependency. Target subscription-based wheel replacement programs in Amsterdam and Copenhagen where high-frequency commuters exhibit loyalty stickiness. Pursue white-label partnerships with municipal skate park procurement authorities seeking EU Green Deal material credit compliance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fabricators with heat-moldable customization capabilities over diversified sporting goods conglomerates. Long-term viability hinges on carbon-fiber supply agreement security and digital product passport infrastructure deployment. The signal to watch is ECHA registration velocity for bio-based synthetic alternatives crossing threshold volumes that trigger incumbent price repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Implementation | Blockchain-verified material documentation satisfies ANSM and German retailer shelf-placement requirements. |
| Backward Integration into Bio-Synthetics | Castor oil-derived TPU production secures EU Green Deal procurement eligibility for municipal buyers. |
| Direct-to-Consumer Customization Launch | At-home heat-molding kits capture margin from intermediate recreational users avoiding bootfitting services. |
| Subscription Wheel Replacement Program | Monthly polyurethane refreshment fees shift revenue toward consumables in Copenhagen and Amsterdam commuter segments. |
| Modular Chassis Platform Standardization | Frame-swappable designs extend product lifecycle and reduce full-boot replacement frequency among fitness users. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with bootfitting specialists, municipal skate park procurement officers, composite materials procurement leads, and inline hockey league equipment managers. Secondary validation drew from ECHA registration databases, CE marking conformity assessment records, customs trade data for carbon-fiber precursor shipments, and municipal infrastructure budget disclosures. Bottom-up unit demand estimates and top-down market value reconciliation provided analytical triangulation.
Across the analysis window, forecasts incorporate product type segmentation by inline, quad, freestyle, and speed configurations; material tier stratification across synthetic, composite, leather, and rubber categories; and end-user archetype differentiation between recreational, amateur, professional, and children segments. CAGRs were derived from replacement cycle frequency modeling, urban infrastructure investment pipelines, and league expansion trajectories in Germany, the Czech Republic, and Sweden.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and petrochemical price stability assumptions; material deviation would warrant model refresh. Revision becomes warranted when carbon-fiber precursor supply concentration crosses disruption thresholds or when municipal green procurement scheme adoption accelerates beyond baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tetherball Market
Sports Equipment
Football Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Shuttlecock Market