
 Kick Scooter Tire Market | 2026-2036
Kick Scooter Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Kick Scooter Tire Market Analytics
Asset-light leasing models for fleet operators is rewriting competitive entry barriers in the kick scooter tire aftermarket. Segway-Ninebot leverages its captive OEM supply chain to dominate replacement channels for its own deployed units. Xiaomi competes through aftermarket accessibility, sustaining volume across independent repair networks. Razor USA anchors the consumer segment with established retail distribution in North American sporting goods channels.
Kick scooter tires are ground-contact elastomer components, typically molded from rubber or polyurethane compounds in diameters ranging from 100mm to 125mm, engineered to absorb vibration and maintain traction on urban surfaces. Solid tires currently lead fleet procurement due to puncture immunity and reduced maintenance intervals, while pneumatic variants retain preference in premium consumer models where ride quality commands priority. Polyurethane formulations represent the fastest-expanding material segment as manufacturers seek weight reduction and wear-rate improvements over conventional rubber compounds.
The EU Machinery Directive and CE marking requirements govern mechanical safety standards for tires sold within Europe, while the EPA oversees chemical composition limits for rubber compounds in the United States. China's GB standards and SAMR product quality certifications shape export manufacturing compliance for suppliers serving international markets. Stakeholders must monitor evolving micromobility safety regulations and material sustainability mandates to anticipate compliance-driven specification changes before they disrupt supply relationships.
Market Dynamics
Shared micromobility fleet operators are consolidating procurement power and forcing tire suppliers into long-term service contracts that bundle replacement volume with predictive maintenance software, fundamentally restructuring how aftermarket revenue flows through the value chain.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for mechanical safety are compelling fleet operators to accelerate replacement cycles on older scooter models, generating predictable aftermarket demand spikes across Germany, France, and the Netherlands.
- Polyurethane formulation advances:New elastomer compounds delivering 30-40% weight reduction over rubber are capturing design wins in premium consumer segments where ride efficiency commands price premiums.
- Battery-tire integration standards:Emerging protocols linking tire pressure monitoring with power management systems are creating specification lock-in for suppliers capable of delivering smart-enabled tire assemblies.
Market Restraints
- Natural rubber price volatility:Input cost swings for conventional rubber compounds compress margin predictability for manufacturers without forward commodity hedging capabilities or alternative material portfolios.
- Chinese manufacturing concentration:GB standards-certified production clusters in Zhejiang and Guangdong provinces create geographic supply risk that intensifies during port congestion or energy rationing events.
- Solid tire performance ceiling:Puncture-immune designs sacrifice vibration damping and traction quality, limiting penetration into consumer segments where ride comfort remains non-negotiable.
Strategic Opportunities
- Indian urban micromobility expansion:BIS certification pathways and municipal e-scooter permits in Bangalore, Delhi, and Mumbai are opening fleet procurement channels previously dominated by European and North American operators.
- Circular material mandates:EU Green Deal sustainability requirements and extended producer responsibility frameworks are rewarding suppliers with certified recycled content capabilities and closed-loop collection infrastructure.
- Direct-to-fleet digital platforms:API-integrated ordering systems that synchronize tire replacement with telematics-triggered maintenance alerts are displacing traditional distributor relationships among large-scale sharing operators.
Industry Challenges
- Cross-material certification timelines:Validating polyurethane compounds under multiple national safety regimes simultaneously stretches R&D resources and delays product launches in fast-moving fleet procurement windows.
- Telematics integration complexity:Embedding pressure and temperature sensors into tire assemblies requires firmware coordination with scooter OEMs, creating IP negotiation friction and technical standard misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kick Scooter Tire Market |
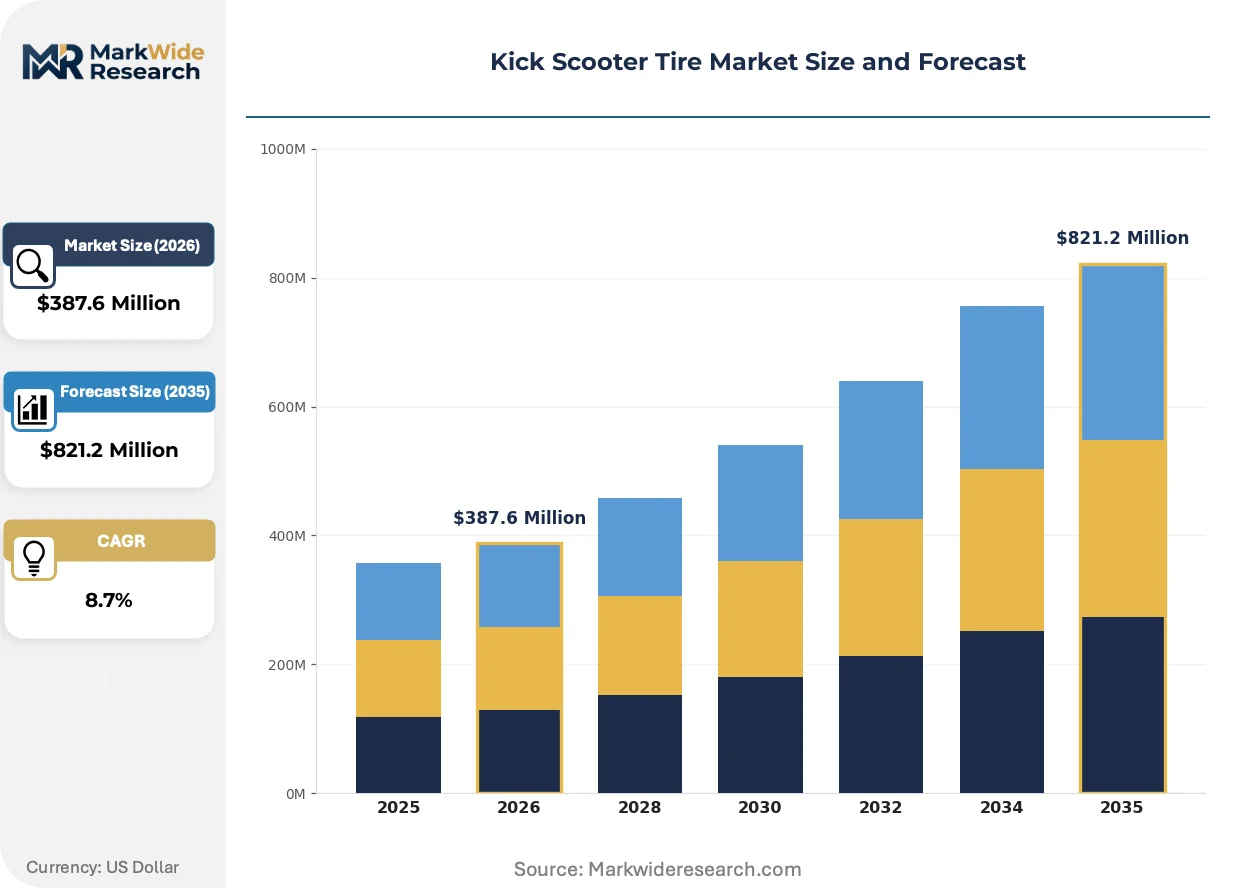
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solid Tires, Pneumatic Tires, Swappable Tires, Custom Tires Size: 100mm, 110mm, 120mm, 125mm Material: Rubber, Polyurethane, Foam, Carbon Fiber Brand: Hurtle, Razor, Swagtron, Yvolve |
| Companies Covered | Segway-Ninebot, Xiaomi, Razor USA, YADEA, NIU Technologies, Okai, Hiboy, Apollo Scooters, Unagi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kick Scooter Tire Market Evolving Landscape
Digital thread technologies are collapsing the distance between tire performance data and procurement decisions, enabling predictive replacement models that treat tires as monitored assets rather than commodity consumables.
Airless cellular structures are virtualizing the trade-off between puncture immunity and ride quality. Michelin and Bridgestone have accelerated development programs targeting 125mm urban scooter formats. Fleet operators in Paris and Berlin are piloting these designs to eliminate roadside maintenance calls. The technology is virtualizing traditional segmentation between solid and pneumatic categories by delivering vibration absorption without inflation infrastructure.
REACH chemical restrictions on polycyclic aromatic hydrocarbons in rubber compounds are forcing reformulation of conventional tire recipes. The European Chemicals Agency enforcement timeline is compressing supplier transition windows. Manufacturers serving EU markets are accelerating bio-based plasticizer adoption to maintain market access.
Leasing-based procurement is displacing spot purchasing among large fleet operators. Operators in Barcelona and Austin now contract tire replacement as a bundled service with per-kilometer pricing. This model concentrates buying power with vertically integrated service providers and marginalizes independent distributors lacking predictive maintenance capabilities.
Kick Scooter Tire Market Segmentation
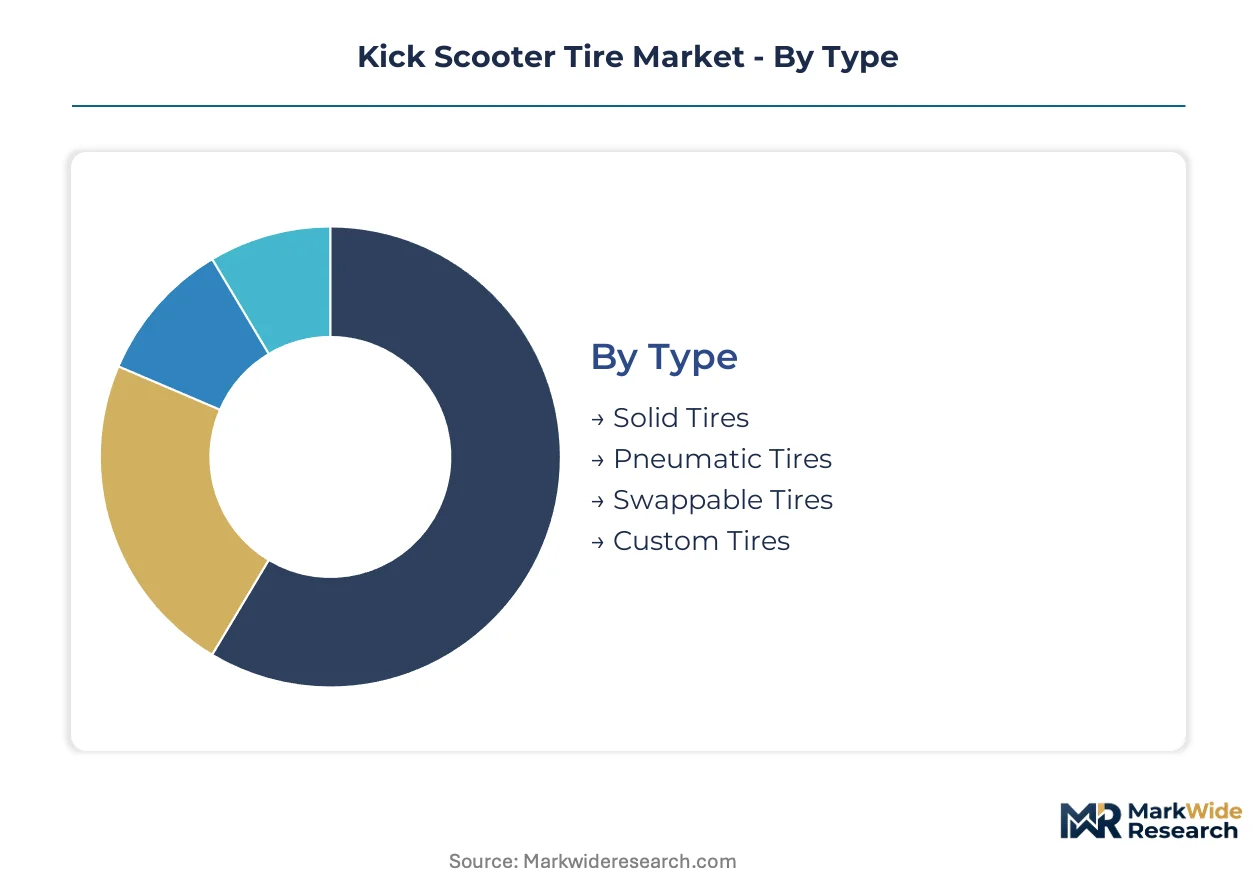
Kick scooter tire procurement patterns diverge sharply across fleet, consumer, and aftermarket channels. Specification requirements from shared micromobility operators differ fundamentally from individual rider preferences, creating distinct demand profiles within each segment category.
Type:
Application context determines tire architecture selection, with fleet operators prioritizing operational uptime against individual riders valuing ride quality.
- Solid Tires:Molded from dense rubber or polyurethane compounds without air chambers, these designs eliminate puncture failures entirely. Shared fleet procurement in Germany, France, and the United States concentrates here, driven by maintenance cost reduction mandates and roadside service elimination targets.
- Pneumatic Tires:Inflated air chambers deliver superior vibration damping and traction on uneven urban surfaces. Premium consumer models in North American sporting goods channels retain preference for this architecture where ride comfort commands specification priority.
- Swappable Tires:Quick-release mounting systems enable field replacement without specialized tools. Aftermarket accessibility drives demand among independent repair networks serving multi-brand scooter populations.
- Custom Tires:Proprietary tread patterns and durometer specifications developed for specific OEM platforms. Captive supply relationships dominate this segment.
Solid configurations command the established base. The steepest expansion runs through swappable designs as fleet maintenance protocols standardize around rapid field service.
Size:
Wheel diameter specifications cluster around urban surface compatibility and deck clearance requirements, with fleet standardization pushing convergence toward mid-range formats.
- 100mm:Compact diameter optimized for lightweight portable scooters and youth models. Entry-level consumer segments in European retail channels maintain residual demand for this legacy specification.
- 110mm:Balanced ground clearance and rotational inertia for general urban commuting. This diameter captures the broadest aftermarket replacement volume across independent service points.
- 120mm:Expanded contact patch and obstacle rollover capability for premium commuter applications. Fleet operators in Paris and Berlin are piloting this format to reduce vibration-related component fatigue.
- 125mm:Maximum diameter for high-performance and heavy-rider capacity models. Emerging airless cellular structures from Michelin and Bridgestone target this specification exclusively.
The 110mm specification anchors current procurement volumes. The steepest expansion trajectory belongs to 125mm formats as next-generation suspension-integrated designs gain fleet validation.
Material:
Compound chemistry determines weight, wear rate, and regulatory compliance, with sustainability mandates accelerating substitution away from conventional petroleum-based formulations.
- Rubber:Natural and synthetic elastomer blends processed through compression or injection molding. REACH polycyclic aromatic hydrocarbon restrictions are compelling reformulation of traditional recipes across EU-serving suppliers.
- Polyurethane:Thermoset polymer systems delivering 30-40% weight reduction against rubber equivalents. This compound is climbing fastest as manufacturers optimize for scooter range efficiency and extended wear performance.
- Foam:Microcellular structures providing pneumatic-like cushioning without inflation infrastructure. Niche applications in rental fleet maintenance reduction programs.
- Carbon Fiber:Reinforced composite casings for ultra-lightweight racing and premium performance segments. Limited volume due to cost structure and impact fragility constraints.
Rubber compounds retain the installed base. Polyurethane formulations are gaining share fastest on weight reduction and sustainability credentialing advantages.
Brand:
Brand affiliation reflects channel access strategies, with OEM-captive positioning competing against aftermarket accessibility approaches.
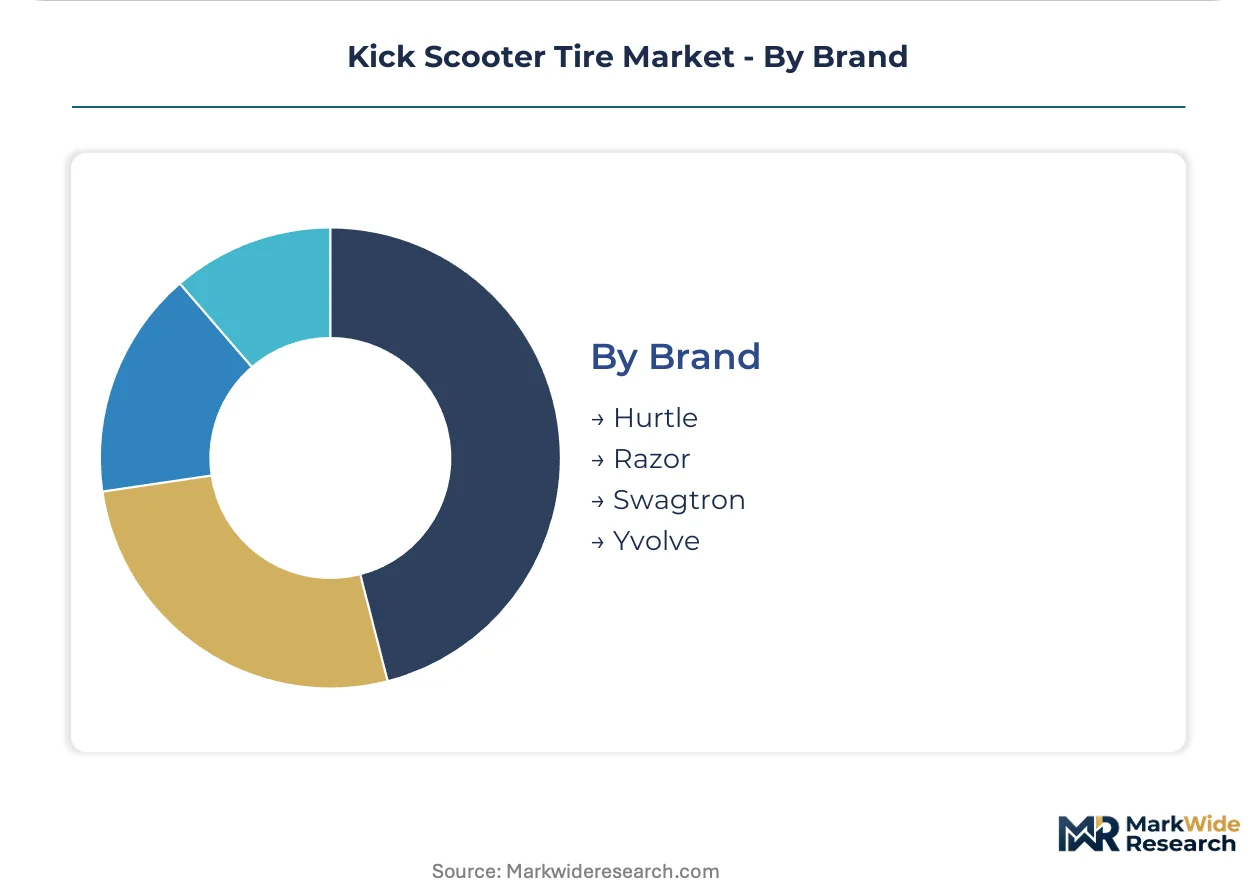
- Hurtle:Budget-focused positioning through mass-market e-commerce platforms and discount retail channels. Price-sensitive consumer segments drive replacement tire demand.
- Razor:Established North American sporting goods distribution with youth and entry-commuter model concentration. Retail presence anchors consumer segment visibility.
- Swagtron:Direct-to-consumer digital sales model with expanded aftermarket parts availability. Independent repair network penetration sustains replacement volume.
- Yvolve:Premium positioning through specialty scooter retailers and performance-oriented product lines. Enthusiast community engagement supports brand loyalty in tire replacement cycles.
Razor's retail infrastructure commands the established consumer base. The steepest expansion runs through Swagtron's digital-direct aftermarket accessibility model.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export manufacturing clusters in Zhejiang and Guangdong provinces supply the majority of global kick scooter tire volume, while import demand concentrates in fleet-dense European and North American cities where replacement cycles drive aftermarket procurement.
Germany
Shared micromobility operators in Berlin and Munich maintain the largest active scooter fleets in Europe, generating predictable replacement tire demand through centralized procurement contracts. KBA vehicle safety standards and EU Machinery Directive CE marking requirements govern tire specifications for commercial deployments. Manufacturing supply relationships cluster around Hamburg port logistics infrastructure serving northern European distribution networks.
France
Paris leads European fleet density with extensive scooter-sharing permits and dedicated urban micromobility infrastructure driving tire consumption rates. ANSM product safety oversight and emerging battery-tire integration protocols are tightening compliance specifications for smart-enabled tire assemblies. Industrial supply channels concentrate through Lyon logistics hubs connecting Zhejiang manufacturing exports to French fleet operators.
United States
Austin and Los Angeles anchor North American shared fleet deployment, with procurement power consolidating among operators pursuing predictive maintenance service contracts. EPA chemical composition limits for rubber compounds regulate domestic import specifications, while NHTSA safety standards influence tire architecture selection. West Coast port infrastructure handles the majority of Chinese tire imports serving domestic aftermarket channels.
China
Zhejiang and Guangdong provinces host GB standards-certified production clusters supplying export volume to international markets. SAMR product quality certifications and MIIT industrial standards shape manufacturing compliance for suppliers serving EU and North American customers. Shenzhen and Hangzhou manufacturing centers are integrating polyurethane formulation capabilities to capture premium segment demand.
India
Bangalore, Delhi, and Mumbai municipal e-scooter permits are opening fleet procurement channels previously dominated by European and North American operators. BIS certification pathways govern tire import specifications and domestic manufacturing quality standards. Tamil Nadu industrial corridors are developing component supply capabilities to serve anticipated fleet expansion in southern Indian urban centers.
Kick Scooter Tire Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated OEMs and specialized aftermarket suppliers competing through channel access differentiation. Three strategic archetypes dominate: captive OEM supply chains controlling replacement channels for proprietary scooter platforms, independent manufacturers serving multi-brand repair networks, and digital-direct specialists bypassing traditional distribution. Competitive moves center on predictive maintenance software bundling and polyurethane material certification to capture fleet procurement contracts.
Within the captive OEM tier, Segway-Ninebot and Xiaomi exemplify contrasting channel strategies—one leveraging proprietary supply chain control while the other sustains aftermarket accessibility across independent repair networks. Razor USA anchors the consumer segment archetype through established North American retail distribution. These three companies represent the primary competitive positioning vectors: OEM-captive integration, aftermarket openness, and retail channel density.
| Leading Market Players |
|---|
| Segway-Ninebot |
| Xiaomi |
| Razor USA |
| YADEA |
| NIU Technologies |
| Okai |
| Hiboy |
| Apollo Scooters |
| Unagi |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Hamburg container freight corridors transmit cost volatility from Zhejiang manufacturing clusters through to European fleet procurement contracts, compressing margin buffers for suppliers lacking forward logistics hedging while enabling price differentiation between rubber-dependent and polyurethane-capable producers serving premium specification tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle tire volume with predictive maintenance software subscriptions. Three-tier pricing structure across premium polyurethane, standard rubber, and economy solid-tire levels reflects certification grade differentiation under EU Machinery Directive CE marking and volume scale commitments from large fleet operators. Pricing pressure stems from natural rubber input cost swings compressing margin predictability for conventional compound manufacturers. Price-sensitive independent repair networks drive spot-market negotiation intensity, while fleet operators with captive service contracts exhibit lowest sensitivity due to operational uptime prioritization.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard procurement practice among European fleet operators, straining working capital for Zhejiang and Guangdong manufacturers without supply-chain finance facilities. Raw material flows rest on Malaysian and Thai natural rubber plantations, Saudi petrochemical feedstocks for polyurethane precursors, and carbon black from Chinese furnace operations. Single-source vulnerability concentrates in GB standards-certified production clusters exposed to energy rationing events. Distribution runs through Hamburg and Rotterdam port logistics hubs serving northern European fleet operators, with West Coast North American volume flowing through Los Angeles-Long Beach infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kick scooter tire market sits in early-cycle expansion as Indian municipal e-scooter permit programs accelerate fleet deployment timelines previously concentrated in European and North American cities.
For Market Incumbents: Pre-empt margin compression from polyurethane formulation commoditization by accelerating backward integration into captive elastomer compounding capabilities in Zhejiang production clusters. Defend against emerging airless cellular structure displacement by securing exclusive pilot validation contracts with Paris and Berlin fleet operators before Michelin and Bridgestone scale manufacturing. For New Entrants and Emerging Players: Establish a beachhead in Bangalore and Delhi aftermarket channels where BIS certification requirements create temporary shelter from established Chinese export manufacturers. Target swappable tire architectures for independent repair networks serving multi-brand scooter populations, leveraging API-integrated ordering platforms that synchronize with telematics-triggered maintenance alerts to bypass traditional distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified rubber component conglomerates with underutilized kick scooter tire divisions lacking fleet service contract capabilities. Long-term viability hinges on positioning for EU Green Deal circular material mandates requiring closed-loop collection infrastructure. Monitor battery-tire integration standard finalization as inflection signal for specification lock-in winners.| Strategic Initiative | Industry Significance |
|---|---|
| Polyurethane Formulation Scale-Up | Captures 30-40% weight reduction advantages for range-optimized fleet specifications. |
| Predictive Maintenance Software Integration | Locks fleet operators into per-kilometer service contracts displacing spot purchasing. |
| Airless Cellular Structure Pilot Validation | Secures design wins with Paris and Berlin operators eliminating roadside maintenance calls. |
| EU Green Deal Certification Investment | Qualifies suppliers for extended producer responsibility framework procurement preferences. |
| Indian BIS Certification Pathway Development | Opens municipal fleet channels in Bangalore, Delhi, and Mumbai before competitor entry. |
Research Methodology
The analysis maps solid, pneumatic, swappable, and custom tire sub-sectors, each validated through fleet procurement managers, aftermarket service technicians, polyurethane R&D directors, and logistics coordinators at Zhejiang export manufacturers. Primary interview insights triangulated against customs trade records, EU Machinery Directive compliance filings, SAMR product quality certification databases, and SEC 10-K disclosures from listed micromobility operators. Bottom-up segment sizing and top-down macro constraint checks ensured methodological consistency.
Assumptions held fixed include EU Machinery Directive enforcement timelines, natural rubber commodity price bands, and fleet operator consolidation trajectories, while variables tested across polyurethane adoption rates, Indian permit issuance velocity, and airless cellular structure manufacturing scale. Segmentation dimensions modeled encompass tire architecture type, diameter specification, compound chemistry, and channel access strategy. CAGRs derived from replacement cycle frequency analysis tied to fleet utilization intensity and consumer ownership duration patterns, with battery-tire integration protocol adoption curves informing smart-enabled assembly demand projections.
Stress conditions across natural rubber price volatility, port congestion recurrence, and REACH chemical restriction enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet operator procurement consolidation and material substitution timelines. Macroeconomic contraction, regulatory acceleration beyond modeled timelines, or breakthrough airless manufacturing cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Ladderball Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Europe Kickboxing Equipment Market