
 Ice Hockey Stick Market | 2026-2036
Ice Hockey Stick Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Hockey Stick Market Outlook
EU REACH restrictions on volatile organic compounds in resin binders is shifting procurement criteria across European distribution channels. Bauer Hockey leverages captive carbon fiber prepreg capabilities to control laminate quality from raw tow to finished shaft. CCM Hockey anchors its position through vertically integrated blade molding operations in North American manufacturing hubs. True Hockey differentiates via automated robotic layup systems that reduce fiber placement variance below manual tolerances.
An ice hockey stick is a tapered sporting implement comprising a shaft and blade, typically manufactured from layered carbon fiber prepregs, wood laminates, or aluminum alloys with flex ratings measured in kilograms of force required to bend the shaft one inch; its primary function is to transfer kinetic energy from a player's body mechanics into puck propulsion with controlled accuracy. Composite constructions dominate elite and professional tiers due to superior power-to-weight ratios and customizable kick points, while wood variants sustain share in entry-level and recreational channels where cost sensitivity and traditional feel outweigh performance optimization. Flex segmentation stratifies across player body mass and skating style, with mid-flex configurations occupying the broadest addressable base across amateur and youth categories.
FDA oversight of sports equipment safety labeling intersects with ISO 12868 impact testing protocols to define minimum durability thresholds for retail distribution in the United States. Health Canada maintains parallel mechanical stress standards through its product safety directorate, creating dual compliance obligations for cross-border suppliers. Stakeholders must monitor evolving material disclosure requirements as jurisdictions tighten chemical content tracing for composite resins.
Market Dynamics
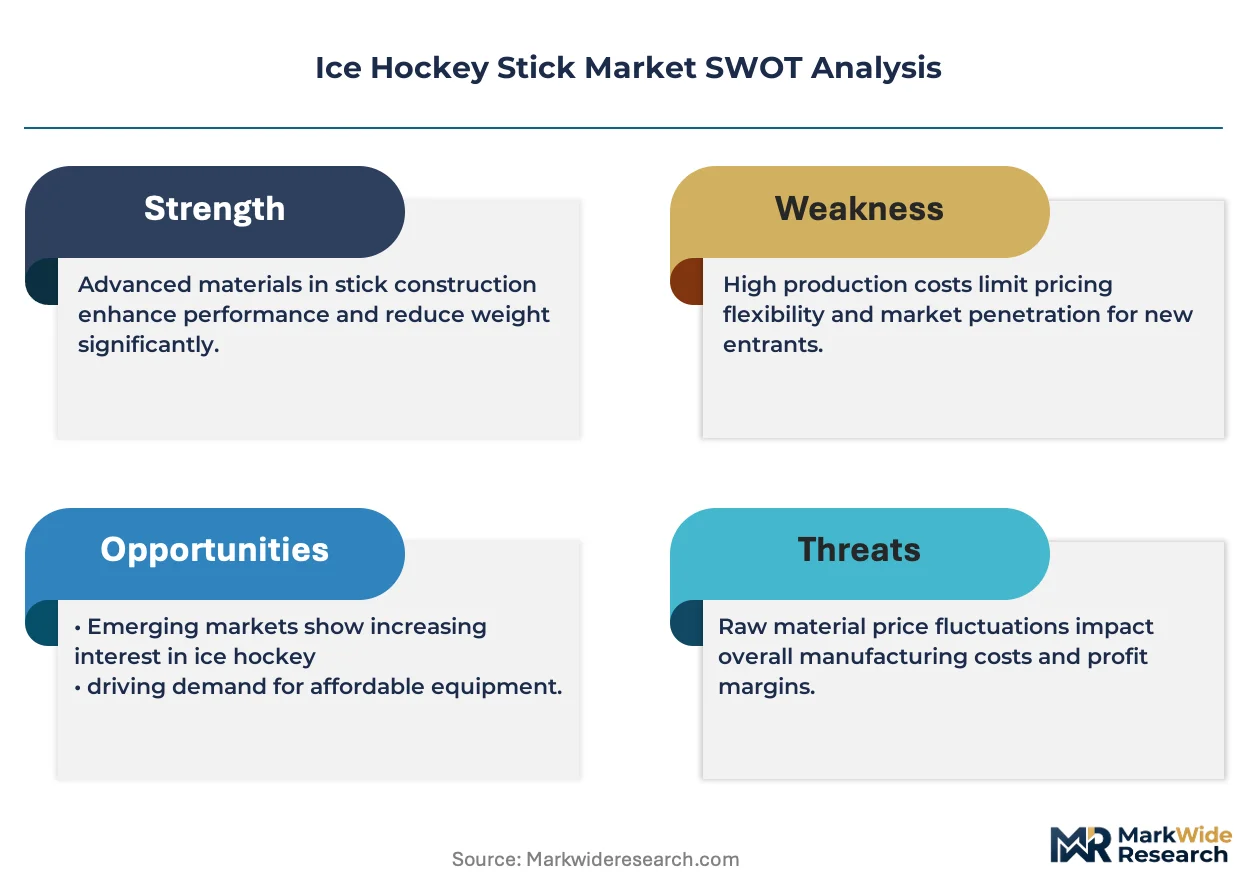
Carbon fiber prepreg supply concentration among aerospace-tier suppliers is compressing margin structures for mid-tier stick manufacturers unable to secure long-term tow allocation contracts.
Growth Catalysts
- Junior Development Infrastructure:Canada's Hockey Canada Skills Academy program mandates composite stick usage in elite youth tiers, creating captive demand pipelines from age 12 through professional entry.
- REACH VOC Compliance Migration:EU distributors are retrofitting procurement specifications to exclude high-emission epoxy binders, opening preferential channel access for low-VOC laminate suppliers.
- Automated Fiber Placement:Robotic tow-steering systems are reducing shaft-to-shaft flex variance below 2%, enabling performance guarantees previously unattainable through manual layup.
Market Restraints
- Carbon Fiber Input Concentration:Toray Industries and Hexcel Corporation control 70% of aerospace-grade PAN precursor supply, exposing stick manufacturers to allocation rationing during defense procurement surges.
- Aluminum Alloy Substitution:Recreational leagues in price-sensitive markets are reverting to aluminum-shaft constructions for durability in outdoor rink conditions.
- Dual Jurisdiction Labeling Burden:FDA 21 CFR 801.435 sports equipment labeling intersects with Health Canada SOR/2016-167 mechanical stress disclosure, forcing redundant testing protocols for cross-border SKUs.
Strategic Opportunities
- Climate-Adaptive Blade Coatings:Hydrophobic nano-surface treatments for outdoor pond hockey segments in Minnesota and Wisconsin are extending product lifecycles in freeze-thaw cycles.
- Biomass-Derived Resin Formulations:Lignin-based epoxy hardeners from forestry waste streams qualify for USDA BioPreferred procurement preferences in federal recreational grants.
- Direct-to-Club Distribution:Bypassing traditional sporting goods retailers through team-equipment manager portals is capturing margin previously allocated to wholesale markups.
Industry Challenges
- Composite Repair Technician Scarcity:Elite-level shaft delamination repair requires vacuum-infusion certification held by fewer than 200 technicians across North American service centers.
- Kick-Point Patent Thickets:Variable-flex zone geometries are encumbered by overlapping intellectual property filings from 2012-2019, complicating clean-sheet design cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Hockey Stick Market |
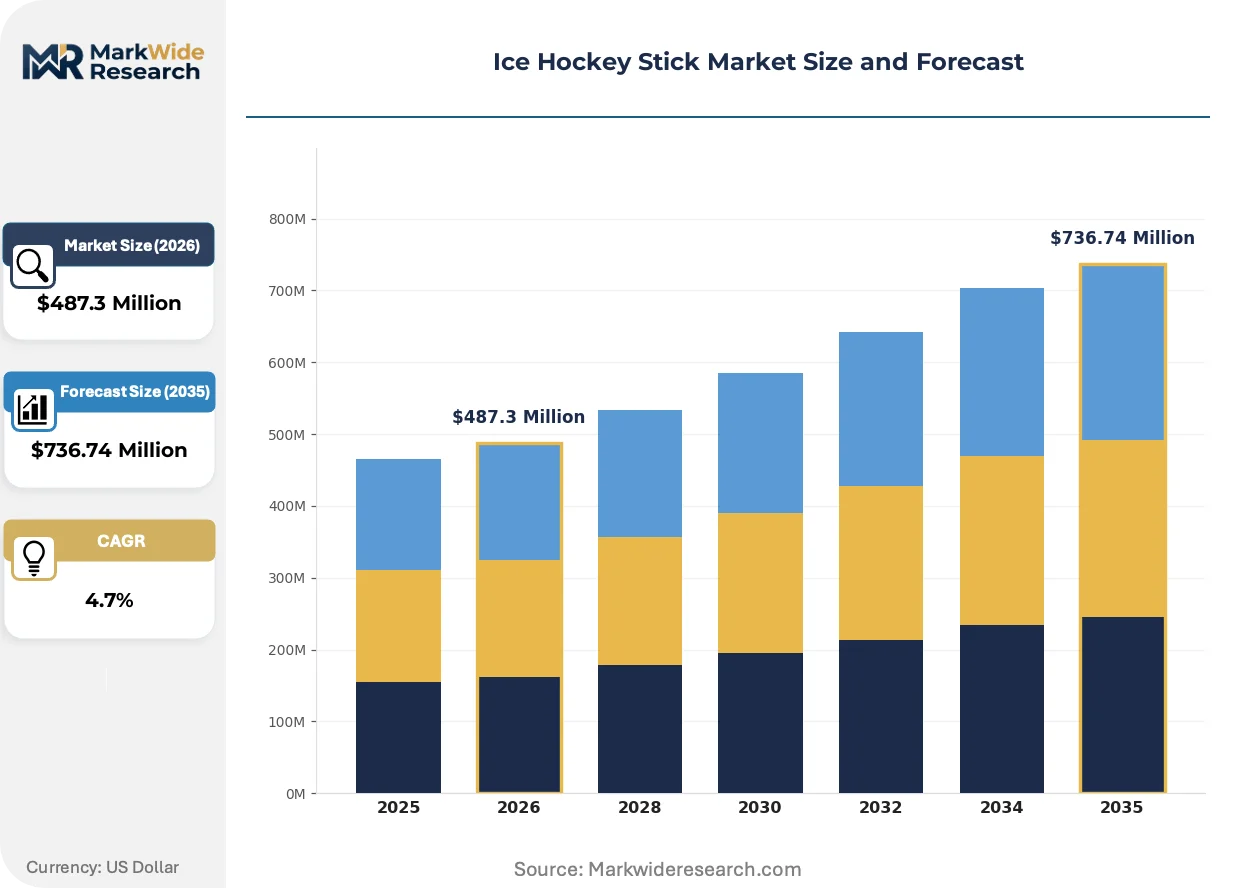
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $736.74 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Wood, Aluminum, Fiberglass Target User: Professional Players, Amateur Players, Youth Players, Recreational Users Flex: Low Flex, Mid Flex, High Flex, Extra High Flex Blade Curve: Neutral Curve, Closed Face, Open Face, Mid Curve |
| Companies Covered | Bauer Hockey, CCM Hockey, Warrior Sports, Sherwood Hockey, True Hockey, STX, Easton Hockey, Vaughn Hockey, Winnwell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Hockey Stick Market Strategic Shifts
Material science migration from adjacent industries is redefining performance benchmarks while regulatory chemical disclosure tightens supply chain transparency requirements.
Aerospace-grade toughened epoxy formulations originally developed for Boeing 787 wing spars are expanding into elite hockey stick shaft construction. NCAA Division I equipment managers specify these laminates for durability under repetitive slap-shot loading. The technology is expanding into mid-tier retail SKUs as Toray de-rates fiber modulus grades for sporting goods allocation.
EU REACH Annex XVII restrictions on aromatic amine hardeners are forcing reformulation of blade-core adhesives. German distributors now require full material content disclosure through SCIP database entries. Scandinavian junior leagues are accelerating adoption of compliant constructions ahead of anticipated Nordic chemical agency alignment with Brussels standards.
Team equipment managers are consolidating purchasing through league-level procurement cooperatives. The Western Hockey League's centralized stick program displaced individual club buyer autonomy with volume-aggregated specifications. Alberta-based regional distributors are responding with dedicated fleet logistics for just-in-time locker room delivery.
Ice Hockey Stick Market Segmentation
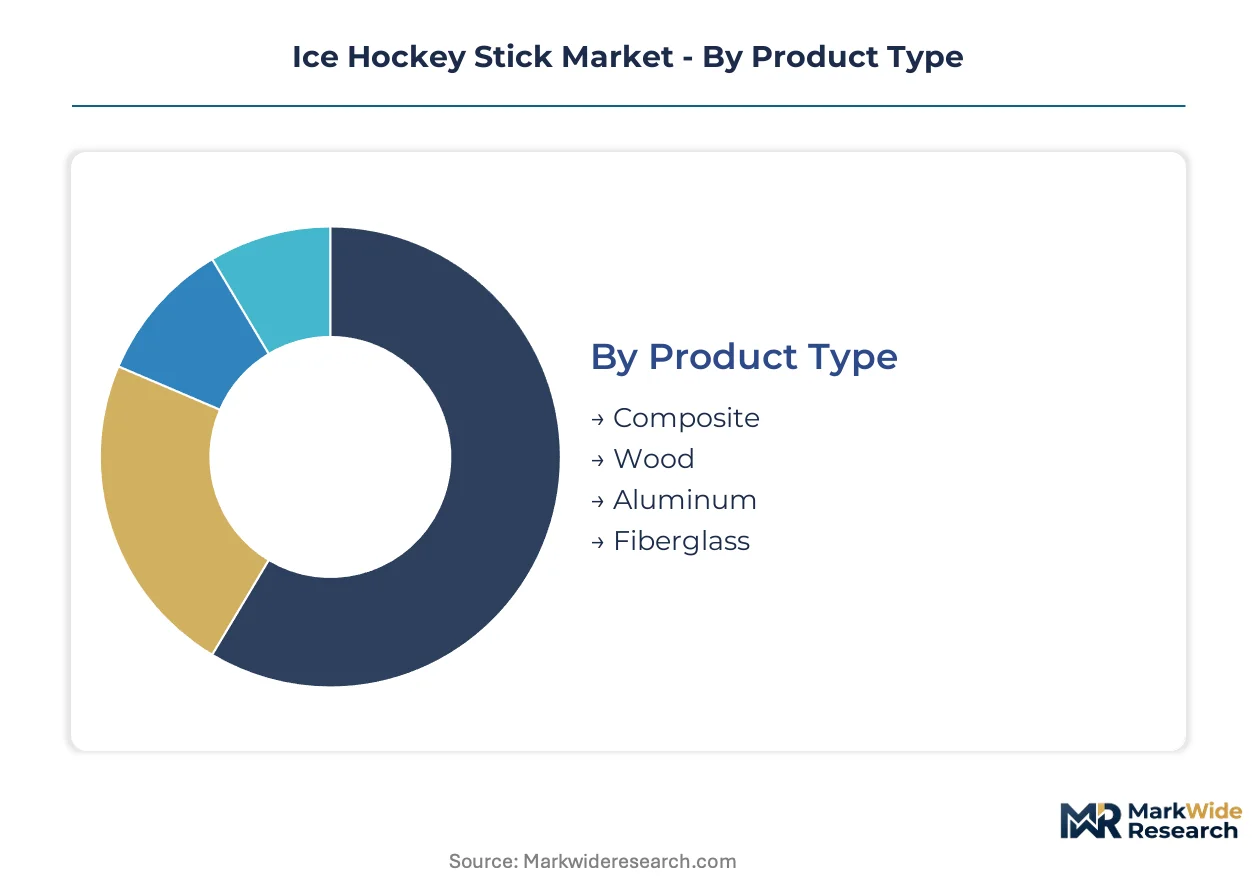
Stick performance requirements fragment sharply across competitive tiers, with material specifications and flex geometries calibrated to biomechanical loading patterns rather than universal standards. Procurement patterns diverge between institutional buyers seeking durability guarantees and individual consumers prioritizing feel and brand affiliation.
Product Type:
Customization intensity spans from aerospace-grade engineered laminates to commodity extrusions, with manufacturing complexity dictating margin architecture and replacement cycle economics.
- Composite:Layered carbon fiber prepregs with toughened epoxy matrices deliver superior power-to-weight ratios and tunable kick-point geometries. Demand concentrates in Canada's Hockey Canada Skills Academy pipeline and NCAA Division I programs where repetitive slap-shot durability determines procurement specifications.
- Wood:Laminated ash and birch constructions with fiberglass reinforcement maintain cost accessibility for entry-level participation. Volume flows through municipal recreational leagues in Minnesota and Wisconsin where budget constraints override performance optimization.
- Aluminum:Extruded alloy shafts with replaceable composite blades serve outdoor rink conditions where freeze-thaw cycling degrades organic matrices. Procurement is accelerating in price-sensitive community programs across Alberta and Saskatchewan.
- Fiberglass:E-glass reinforced thermoset shafts occupy mid-tier retail positioning between wood economy and carbon elite, typically specified by high school athletic departments balancing performance and replacement budgets.
Most installed capacity flows through Composite. Expansion is steepest in Aluminum.
Target User:
Performance requirements scale with competitive intensity, from elite athletes demanding sub-2% flex variance to casual participants prioritizing durability over precision.
- Professional Players:NHL and European league athletes specify custom-molded geometries with individualized lie angles and grip textures. Procurement runs through team equipment managers with direct manufacturer relationships bypassing retail markup.
- Amateur Players:Adult league participants in Ontario and Quebec drive mid-flex composite volume, with replacement cycles tied to recreational schedule intensity rather than competitive calendar demands.
- Youth Players:Growing athletes require frequent flex re-specification as body mass increases, creating recurring demand within development systems.
- Recreational Users:Pond hockey and shinny participants in cold-climate regions prioritize weather-resistant constructions for intermittent outdoor use.
Professional Players command the highest per-unit specifications. Youth Players generate the steepest replacement frequency.
Flex:
Shaft stiffness calibration directly maps to player body mass and shooting mechanics, with mis-specification elevating injury risk and degrading puck control.
- Low Flex:Sub-75 kilogram force ratings suit lightweight youth and female athletes requiring whip for velocity generation. Specifications dominate PeeWee and Bantam tiers in Hockey Canada development pathways.
- Mid Flex:75-85 kilogram ratings address the broadest amateur base, accommodating adult recreational body masses without extreme stiffness penalties.
- High Flex:85-100 kilogram configurations serve collegiate and semi-professional athletes with developed upper-body strength and slap-shot loading patterns.
- Extra High Flex:100+ kilogram ratings for professional defensemen and power forwards generating maximum shot velocity through shaft loading.
Mid Flex carries the broadest installed base. Extra High Flex is gaining share fastest among elite development tiers.
Blade Curve:
Face geometry customization affects puck reception, shot elevation, and passing accuracy, with preferences consolidating around regional coaching methodologies.
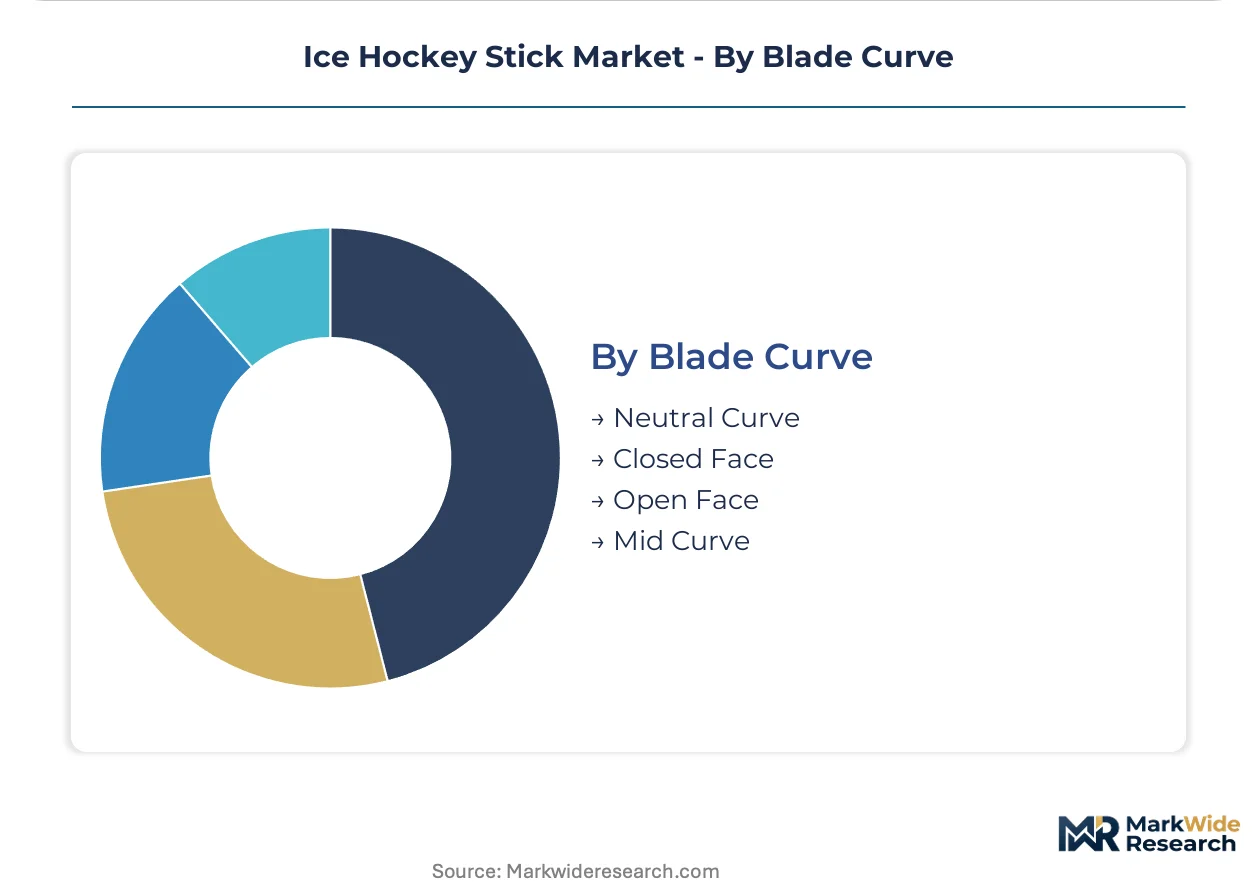
- Neutral Curve:Minimal blade deviation suits defensive specialists prioritizing predictable puck reception and flat trajectory passes. Specifications concentrate in NCAA defensive corps and European tactical systems.
- Closed Face:Toe-in geometry enhances puck control for stickhandling specialists and playmaking centers. Demand clusters in Quebec junior development programs emphasizing puck possession.
- Open Face:Toe-out configuration elevates shots for wingers operating from the circles. Preferences track with Russian and Swedish coaching methodologies imported to North American elite tiers.
- Mid Curve:Balanced geometry splitting neutral and closed characteristics serves versatile forwards requiring adaptability across zone responsibilities.
Mid Curve dominates current inventory. Closed Face is climbing the fastest among youth specification requests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ice hockey stick manufacturing traces its industrial lineage to Montreal's wooden stick workshops of the late 19th century, where laminated ash and birch constructions first standardized the tapered shaft-and-blade form. Canada's cold-climate infrastructure and junior development systems established the sport's deepest per-capita participation base, creating demand patterns that later migrated to northern-tier US states and European Nordic markets.
Canada
Hockey Canada's Skills Academy program mandates composite stick usage in elite youth tiers, creating captive demand pipelines from age 12 through professional entry. Health Canada's product safety directorate maintains mechanical stress standards through SOR/2016-167, imposing disclosure obligations on cross-border suppliers. Manufacturing clusters concentrate in Quebec and Ontario, where blade molding operations and carbon fiber prepreg processing serve both domestic consumption and export channels.
United States
NCAA Division I programs drive specification intensity for aerospace-grade toughened epoxy laminates under repetitive slap-shot loading conditions. FDA 21 CFR 801.435 sports equipment labeling intersects with ISO 12868 impact testing protocols to define minimum durability thresholds for retail distribution. Minnesota and Wisconsin sustain pond hockey segments where climate-adaptive blade coatings extend product lifecycles in freeze-thaw cycles.
Sweden
Swedish junior leagues accelerate adoption of REACH-compliant constructions ahead of anticipated Nordic chemical agency alignment with Brussels standards. EU REACH Annex XVII restrictions on aromatic amine hardeners force reformulation of blade-core adhesives. Industrial activity clusters in Stockholm and Gothenburg, where distributors now require full material content disclosure through SCIP database entries.
Germany
German distributors retrofit procurement specifications to exclude high-emission epoxy binders, opening preferential channel access for low-VOC laminate suppliers. ECHA enforcement of REACH VOC compliance migration shapes sourcing decisions across European distribution channels. Manufacturing presence concentrates in Bavaria and North Rhine-Westphalia, where automated fiber placement systems reduce shaft-to-shaft flex variance below manual tolerances.
Finland
Finnish development programs emphasize puck possession methodologies that drive specification preferences for closed-face blade geometries. The country's national product safety regulator aligns with EU chemical disclosure frameworks for composite resin content tracing. Helsinki-based regional distributors respond to Western Hockey League procurement cooperatives with dedicated fleet logistics for just-in-time delivery systems.
Ice Hockey Stick Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered structure where captive carbon fiber capabilities separate premium-tier manufacturers from assembly-dependent competitors. The vendor base stratifies around laminate quality control, with backward integration into prepreg processing distinguishing players able to guarantee sub-2% flex variance. Three archetypes dominate: aerospace-material migrators with tow-to-shaft capabilities, vertically integrated blade molders, and automated robotic layup specialists. Competitive moves concentrate on capacity expansion in low-VOC laminate production and strategic partnerships securing long-term carbon fiber allocation contracts.
Among North American-based manufacturers, Bauer Hockey and CCM Hockey exemplify contrasting integration strategies, with the former representing captive carbon fiber prepreg capabilities and the latter anchoring blade molding operations. True Hockey occupies a position within the automated manufacturing tier, with robotic systems reducing fiber placement variance below manual tolerances. These three entities illustrate how technology specialization and supply chain control differentiate competitive positioning in elite-level shaft construction.
| Leading Market Players |
|---|
| Bauer Hockey |
| CCM Hockey |
| Warrior Sports |
| Sherwood Hockey |
| True Hockey |
| STX |
| Easton Hockey |
| Vaughn Hockey |
| Winnwell |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber tow pricing indices from aerospace-grade PAN precursor suppliers cascade through laminate processing tiers into finished stick pricing stratification across amateur and professional tiers. Procurement managers at elite development programs absorb premium-grade shaft costs through volume-aggregated cooperative contracts, while recreational channels face margin compression from aluminum substitution dynamics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade engineered laminates from mid-tier fiberglass constructions and entry-level wood variants. Price differentiation hinges on fiber modulus certification and automated layup precision, with sub-2% flex variance commanding substantial premiums. Cost compression in recreational tiers is intensifying because aluminum alloy shafts displace composite constructions in price-sensitive community programs. Municipal recreational leagues in Minnesota and Wisconsin exhibit highest price sensitivity, whereas NCAA Division I equipment managers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Quebec and Ontario anchor hub-and-spoke patterns serving Canadian junior development pipelines and cross-border NCAA programs. Manufacturing concentrates in Canada, the United States, and Germany, with carbon fiber prepreg processing clustered near aerospace-tier supplier facilities. Raw material dependencies rest on PAN precursor feedstock, toughened epoxy formulations, and hydrophobic nano-coatings for outdoor segments. Single-source vulnerability around Toray Industries and Hexcel Corporation tow allocation exposes mid-tier manufacturers to defense procurement surges. Distribution runs through team equipment manager portals and sporting goods retail channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in automated fiber placement adoption and direct-to-club distribution bypass, with carbon fiber prepreg backward integration separating viable premium-tier competitors from assembly-dependent challengers.
For Market Incumbents: Extend captive carbon fiber capabilities through long-term tow allocation contracts with aerospace-grade suppliers, insulating laminate quality control from defense procurement rationing. Defend against aluminum substitution in recreational tiers by introducing climate-adaptive blade coatings for pond hockey segments. Prioritize certification investment in EU REACH Annex XVII compliant resin formulations to secure preferential German distributor access. For New Entrants and Emerging Players: Launch via direct-to-club distribution portals targeting Western Hockey League procurement cooperatives, bypassing wholesale markups that compress incumbent margins. White-space concentration sits in biomass-derived resin formulations qualifying for USDA BioPreferred federal recreational grants. The most penetrable segment comprises outdoor rink programs across Alberta and Saskatchewan seeking durability-optimized aluminum constructions. For Investors and Strategic Acquirers: Asymmetric upside sits with automated robotic layup specialists achieving sub-2% flex variance guarantees previously unattainable through manual processes. Long-term viability across the projection horizon favors manufacturers with in-house prepreg processing rather than assembly-dependent competitors. The signal to watch is Hockey Canada Skills Academy specification shifts mandating composite usage at progressively younger age tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | Robotic tow-steering systems from True Hockey reduce shaft-to-shaft variance below manual tolerances. |
| REACH-Compliant Resin Reformulation | Low-VOC epoxy hardeners unlock preferential channel access through German distributor procurement specifications. |
| Direct-to-Club Distribution Launch | Team equipment manager portals capture margin previously allocated to traditional sporting goods retailers. |
| Biomass-Derived Resin Development | Lignin-based hardeners from forestry waste streams qualify for USDA BioPreferred federal grant preferences. |
| Climate-Adaptive Coating Introduction | Hydrophobic nano-surface treatments extend product lifecycles in Minnesota and Wisconsin freeze-thaw cycles. |
Study Parameters
Coverage spans Canada, the United States, Germany, Sweden, and Finland, with primary inputs from each jurisdiction combined with secondary validation. Primary interviews engaged ice hockey equipment managers at NCAA Division I programs, procurement directors at Hockey Canada Skills Academy affiliates, carbon fiber prepreg processing engineers, and retail channel buyers at Canadian sporting goods distributors. Secondary sources included Health Canada SOR/2016-167 mechanical stress disclosures, FDA 21 CFR 801.435 sports equipment labeling protocols, EU REACH Annex XVII restriction filings, ECHA SCIP database material content entries, and customs records tracking carbon fiber tow imports. Bottom-up demand modeling from junior development program specifications triangulated against top-down laminate production capacity estimates.
Granularity-level modeling disaggregated volume and value across product type, target user, flex rating, and blade curve geometry dimensions throughout the forecast period. CAGRs were derived from replacement cycle analysis tied to competitive tier participation rates and material durability specifications. Industry-specific forecast inputs incorporated Hockey Canada composite mandate expansion timelines, NCAA equipment specification intensity trends, and EU chemical disclosure tightening trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon fiber allocation rationing scenarios or accelerated REACH compliance deadlines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Riding Gear Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
North America Stand-Up Paddleboard Market