
 Textile Floorings Market | 2026-2036
Textile Floorings Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Floorings Market Outlook
The EU Green Deal's building performance standards is rebalancing procurement criteria across commercial fit-out sectors toward low-embodied-carbon textile floorings. Mohawk Industries leverages integrated fiber-to-finish manufacturing to control recycled content ratios across broadloom and modular carpet lines. Shaw Industries Group anchors its position through closed-loop reclamation infrastructure that recaptures nylon face fiber from installed commercial carpets. Tarkett S.A. competes on bio-based polyurethane backing formulations that reduce petroleum-derived content without sacrificing dimensional stability.
Textile floorings encompass woven, tufted, and needle-punched constructions manufactured from natural or synthetic fibers with pile weights typically ranging from 16 to 48 ounces per square yard, designed to provide thermal insulation, acoustic absorption, and slip-resistant walking surfaces in interior environments. The material dimension shows nylon sustaining premium positioning in high-traffic commercial applications due to solution-dyed colorfastness and resilience under rolling loads, while polypropylene occupies value-tier hospitality and residential segments where stain resistance outweighs longevity requirements. Installation method selection varies structurally by building age and substrate condition, with direct glue down dominating new commercial construction and stretch-in retaining share in residential replacement where subfloor irregularities complicate adhesive application.
EPA guidelines on indoor air quality and VOC emissions constrain adhesive and backing chemistries available to US manufacturers, while REACH restrictions in Europe limit certain flame retardant and stain repellent treatments previously standard in contract-grade products. OSHA workplace safety standards influence commercial specification through slip resistance testing protocols that filter out low-pile-density products from institutional bidding pools. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life collection costs from municipalities to original manufacturers.
Market Dynamics
Renovation cycles across commercial real estate are compressing replacement timelines for interior finishes, while embodied carbon thresholds from the EU Green Deal reconfigure specification criteria toward recyclable and bio-based constructions.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy performance upgrades across existing commercial stock are triggering systematic replacement of floor finishes with low-carbon alternatives.
- Hospitality refurbishment waves:Hotel operators in Germany's urban corridors are accelerating 7-10 year renovation cycles to maintain brand positioning against new supply.
- Solution-dyed nylon technology:Colorfastness under UV exposure and resilience under rolling loads sustains premium positioning in high-traffic institutional environments.
Market Restraints
- Petrochemical feedstock volatility:Nylon 6,6 and polypropylene face fiber production remains tethered to propylene and adipic acid price swings that compress margin predictability.
- REACH chemical restrictions:ECHA limitations on PFAS-based stain repellents and halogenated flame retardants force reformulation of contract-grade products without performance degradation.
- Hard surface substitution:Luxury vinyl tile and polished concrete are capturing specification share in commercial segments where moisture resistance and seamless cleaning outweigh acoustic benefits.
Strategic Opportunities
- Extended producer responsibility frameworks:EU member states are shifting end-of-life collection costs to original manufacturers, rewarding those with closed-loop reclamation infrastructure.
- Healthcare facility expansion:Aging demographics in Japan and Western Europe are driving new hospital construction where slip-resistant textile flooring meets OSHA and JIS testing protocols.
- Bio-based polyurethane backings:Castor oil-derived polyols are converging with recycled content face fibers to meet LEED-equivalent certification thresholds without dimensional stability trade-offs.
Industry Challenges
- Installation skill fragmentation:Direct glue-down specification demands substrate preparation expertise that is thinning across aging commercial flooring contractor networks.
- VOC compliance timeline compression:EPA indoor air quality guidelines and state-level adhesive restrictions require simultaneous reformulation of multiple product lines with limited testing window overlap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Floorings Market |
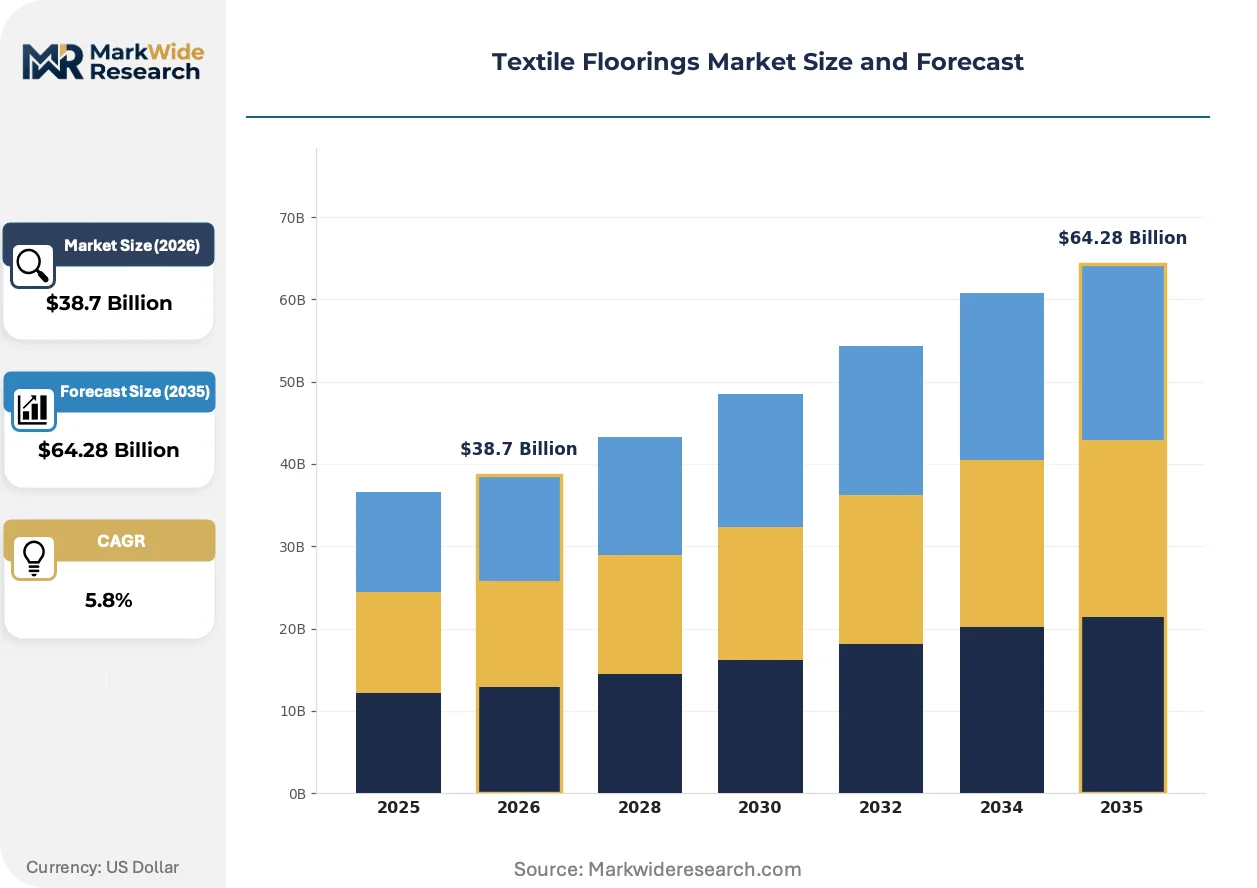
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Carpet, Rugs, Matting, Textiles Material: Wool, Nylon, Polyester, Polypropylene End User: Residential, Commercial, Hospitality, Institutional Installation: Direct Glue Down, Stretch In, Tacks, Loose Lay |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Tarkett S.A., Interface, Inc., Beaulieu International Group, Forbo Holding AG, Mannington Mills, Inc., Balta Group, Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Floorings Market Strategic Shifts
Material science advances are dissolving the boundary between performance and sustainability credentials, while procurement digitization compresses specification-to-installation timelines across commercial fit-out projects.
Recycled nylon face fiber derived from post-consumer fishing nets and industrial scrap is converging with bio-based backing chemistries to create specification-grade products that satisfy both LEED points and performance warranties. Hospitality and corporate office buyers in Northern Europe are adopting these constructions at pace, compressing the historical premium gap between virgin and recycled-content alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are forcing systematic elimination of stain-repellent treatments that had been standard in contract-grade carpet for three decades. ECHA's 2023 restriction proposal is accelerating reformulation investment across broadloom and modular lines. German and French commercial specifiers are now requiring third-party certification of PFAS-free chemistries in public procurement tenders.
Building information modeling integration is enabling real-time visualization of textile flooring specifications within digital twin environments before physical sampling. Commercial architects and facility managers are replacing traditional showroom visits with virtual material libraries that compress decision cycles from weeks to days. This pattern is most visible in US and UK commercial real estate corridors where developer timelines pressure early-stage material lock-in.
Textile Floorings Market Segmentation
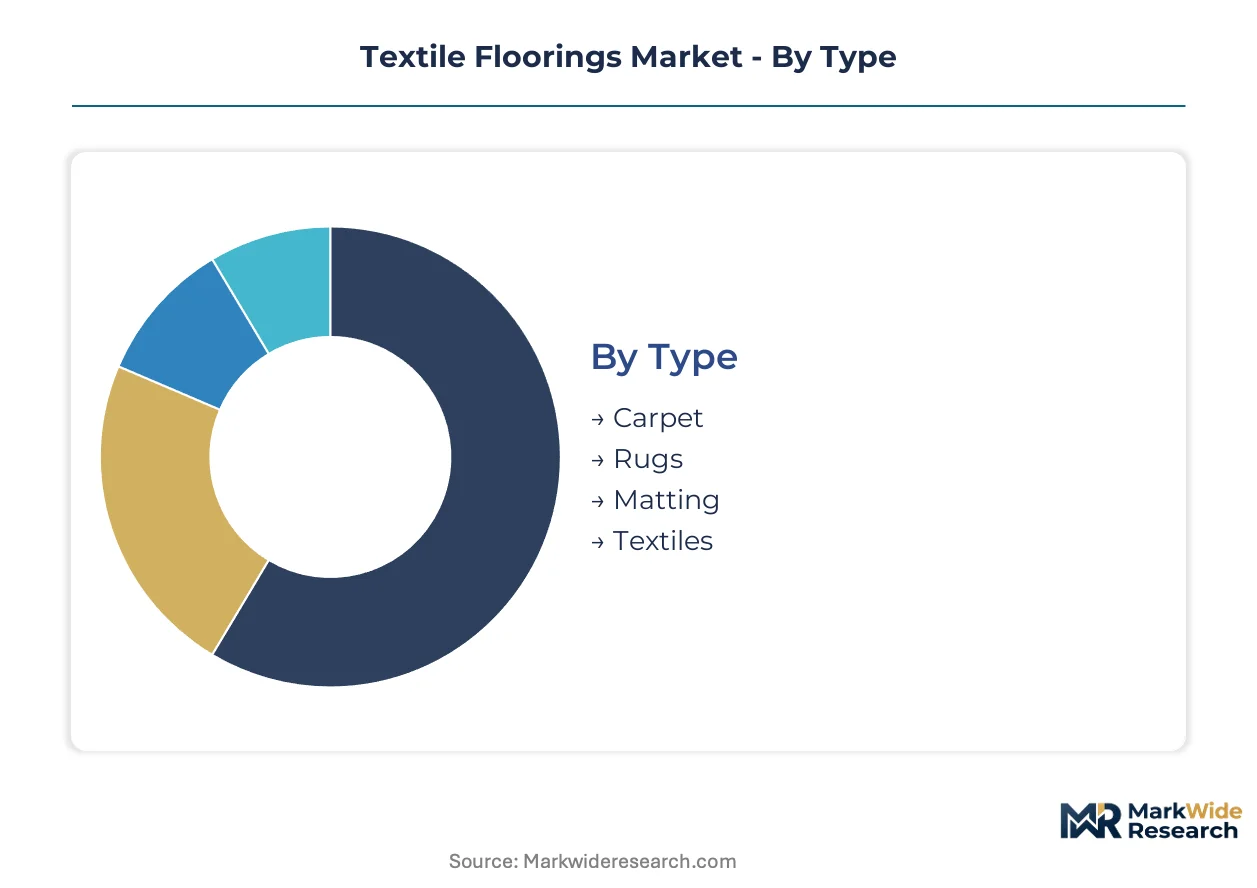
Textile flooring specifications diverge sharply across construction methods, fiber chemistry, and end-use environments. Procurement teams segment purchases by traffic load, maintenance protocols, and embodied carbon thresholds rather than aesthetics alone.
Type:
Carpet manufacturing demands the heaviest capital commitment among type segments, with tufting and weaving lines requiring continuous multi-million-dollar equipment refresh cycles.
- Carpet:Tufted broadloom and modular tile constructions dominate commercial fit-outs, with solution-dyed nylon face fibers specified for Germany's LEED-equivalent certified office corridors. Hospitality operators in urban centers compress replacement cycles to seven-year intervals, sustaining specification volume despite hard surface encroachment.
- Rugs:Hand-tufted and power-loomed accent pieces serve residential replacement and commercial softening applications where acoustic absorption outweighs wall-to-wall coverage needs. Persian and Moroccan patterning retains premium positioning in US and UK residential markets despite pressure from machine-made alternatives.
- Matting:Entrance and anti-fatigue systems prioritize crush resistance and moisture retention for high-traffic thresholds. Commercial facilities specify polypropylene or rubber-backed constructions for compliance with OSHA slip resistance protocols.
- Textiles:Specialty woven wall coverings and acoustic panels extend fiber applications beyond horizontal surfaces. Healthcare and education sectors specify these for sound absorption in corridor and common area treatments.
Carpet absorbs the bulk of installed capacity; matting is expanding most quickly as facility managers prioritize entrance system investments.
Material:
Material selection stratifies by performance tier and petrochemical exposure, with bio-based alternatives gaining specification share where REACH and EPA constraints tighten.
- Nylon:Solution-dyed nylon 6,6 delivers colorfastness and resilience under rolling loads, anchoring premium positioning in airports, hospitals, and corporate headquarters. The fiber's petrochemical feedstock exposure compresses margin predictability during propylene price volatility.
- Polypropylene:Olefin fibers occupy value-tier hospitality and residential segments where stain resistance outweighs longevity requirements. The material's lower melting point restricts specification in high-friction commercial environments.
- Wool:Natural fiber constructions satisfy bio-based procurement criteria in Northern European public tenders, though higher first cost and maintenance requirements limit penetration. New Zealand and British wool supply chains face pressure from synthetic alternatives.
- Polyester:Recycled PET face fibers derived from post-consumer bottles converge with bio-based backings for LEED-equivalent certification compliance. Corporate office buyers in Germany and France specify these constructions for ESG reporting alignment.
Nylon commands the highest unit economics; polyester is climbing the fastest as recycled content ratios become mandatory in public procurement.
End User:
End-user segmentation reflects diverging replacement cycles, with commercial and hospitality compressing timelines while institutional extends amortization periods.
- Commercial:Office and retail fit-outs specify modular carpet tile for flexibility during tenant churn, with glue-down installation dominating new construction. Germany's commercial real estate corridors drive concentration as LEED-equivalent certification governs material selection.
- Hospitality:Hotel operators accelerate renovation cycles to seven-to-ten-year intervals, sustaining demand for high-performance broadloom in guest rooms and corridors. Brand standards increasingly mandate PFAS-free chemistries ahead of regulatory deadlines.
- Residential:Stretch-in installation retains share in replacement markets where subfloor irregularities complicate adhesive application. UK and US housing turnover sustains volume despite hard surface substitution in kitchens and bathrooms.
- Institutional:Healthcare and education facilities prioritize slip resistance and infection control, filtering low-pile-density products from bidding pools through OSHA and JIS testing protocols. Aging demographics in Japan and Western Europe drive hospital construction demand.
Commercial absorbs the bulk of specification volume; hospitality is gaining share fastest as renovation waves concentrate in Germany's urban corridors.
Installation:
Installation method selection varies structurally by building age, substrate condition, and facility type, with skill availability constraining specification flexibility.
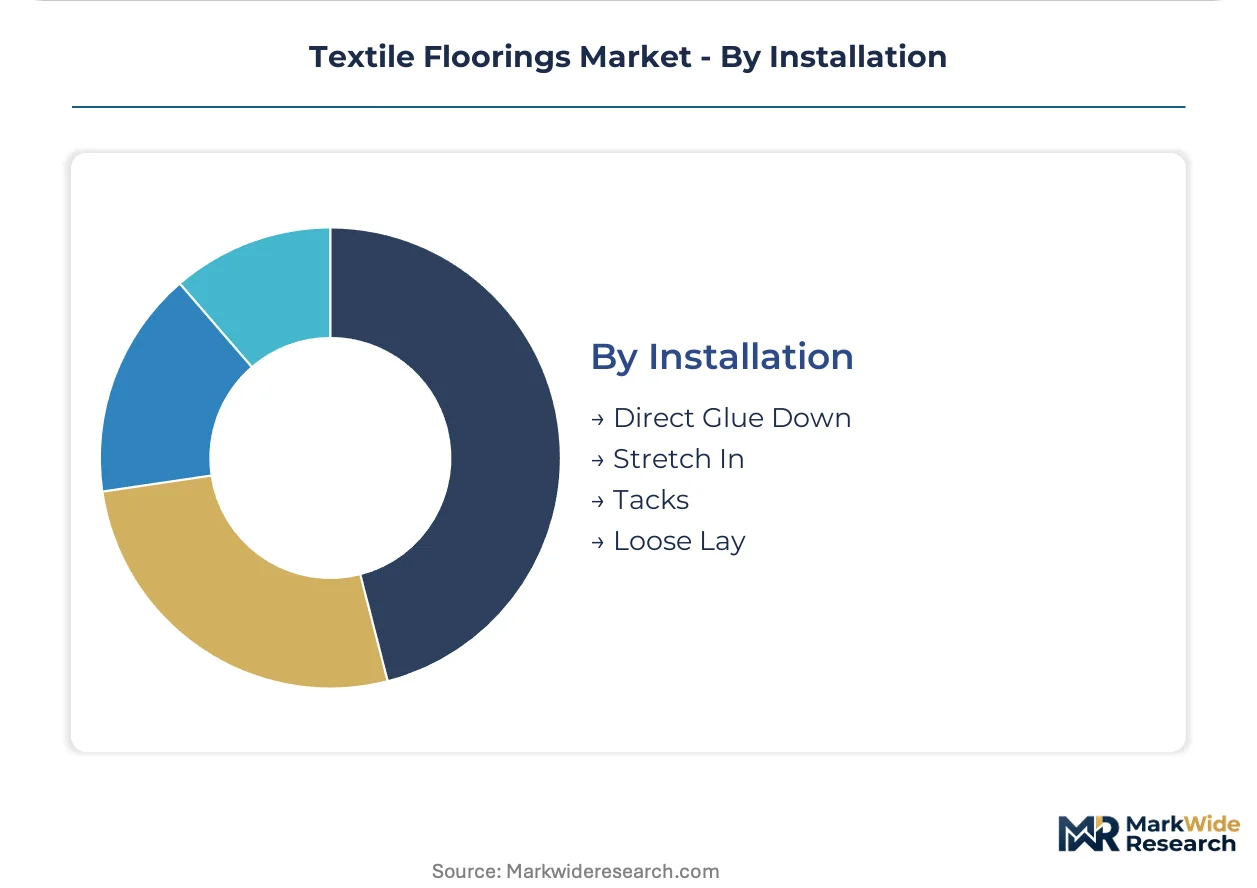
- Direct Glue Down:Adhesive application dominates new commercial construction and institutional fit-outs where dimensional stability and heavy rolling loads demand secure anchoring. Substrate preparation expertise is thinning across aging contractor networks.
- Stretch In:Tackless strip installation retains residential replacement share where subfloor moisture or irregularities preclude adhesive specification. The method enables faster turnaround between tenants in multifamily housing.
- Tacks:Direct mechanical fastening persists in specialty applications and temporary installations where removability outweighs permanence requirements.
- Loose Lay:Friction-based systems with weighted or interlocking edges serve event and exhibition environments requiring rapid deployment and removal without substrate modification.
Direct glue down commands the majority of commercial specification; stretch in retains defensive positioning in residential channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's commercial real estate corridors concentrate specification demand as LEED-equivalent certification tightens material selection criteria. Hotel renovation waves across urban centers amplify high-performance textile flooring procurement. Regulatory pressure from Brussels reconfigures supply chains toward low-embodied-carbon alternatives.
Germany
Hospitality operators in Berlin, Munich, and Hamburg accelerate seven-year renovation cycles to maintain brand positioning against new supply. The EU Green Deal's building performance standards mandate systematic replacement of floor finishes in existing commercial stock. Frankfurt and Düsseldorf office corridors drive concentration as facility managers prioritize modular carpet tile for tenant flexibility.
United States
Corporate office buyers specify solution-dyed nylon for high-traffic institutional environments from Atlanta to Chicago. EPA indoor air quality guidelines constrain adhesive and backing chemistries available to domestic manufacturers. The Southeast and Midwest manufacturing belts anchor production capacity serving commercial construction recovery.
United Kingdom
Healthcare facility expansion driven by aging demographics prioritizes slip-resistant constructions meeting OSHA-equivalent testing protocols. REACH restrictions on PFAS-based stain repellents force reformulation of contract-grade products ahead of regulatory deadlines. London's commercial fit-out sector leads adoption of virtual material libraries compressing specification timelines.
Japan
Hospital construction demand surges as demographic shifts require new healthcare infrastructure across Kanto and Kansai regions. JIS testing protocols filter low-pile-density products from institutional bidding pools. Tokyo and Osaka metropolitan areas concentrate procurement for acoustic absorption in corridor and common area treatments.
France
Public procurement tenders now require third-party certification of PFAS-free chemistries in commercial carpet specifications. ECHA's 2023 restriction proposal accelerates investment across broadloom and modular lines. Paris and Lyon urban corridors drive hospitality refurbishment sustaining specification volume.
Textile Floorings Market Competitive Environment
Premium-margin players sit above commodity-margin players across fiber technology and reclamation infrastructure dimensions. The vendor base organizes into three tiers: integrated fiber-to-finish manufacturers controlling recycled content ratios, closed-loop reclamation specialists capturing end-of-life material flows, and regional fabricators competing on installation proximity. Dominant competitive moves include capacity expansion into bio-based polyurethane formulations and strategic partnerships securing castor oil-derived polyol supply chains.
Within the integrated manufacturing tier, Mohawk Industries, Inc. and Shaw Industries Group, Inc. exemplify archetypes of backward integration into fiber production and captive reclamation infrastructure respectively. Tarkett S.A. occupies a position representing bio-based backing formulation specialization. These three entities anchor the competitive structure through distinct approaches to embodied carbon reduction and circular material flows.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Tarkett S.A. |
| Interface, Inc. |
| Beaulieu International Group |
| Forbo Holding AG |
| Mannington Mills, Inc. |
| Balta Group |
| Milliken & Company |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's embodied carbon thresholds gate qualified supply access and compress premium-tier pricing power toward manufacturers with closed-loop reclamation infrastructure. Buyers without LEED-equivalent certification pathways face shrinking supplier pools as reformulation costs pass through to contract structures.
Pricing Analysis
Performance-based pricing anchors contract negotiations, with solution-dyed nylon constructions commanding premiums tied to rolling-load resilience and UV colorfastness warranties. Three-tier pricing structure across premium, standard, and economy levels separates LEED-certified bio-based systems from REACH-compliant mid-tier alternatives and commodity polypropylene. Cost compression in the value tier intensifies because petrochemical feedstock volatility compresses margin buffers. Hospitality procurement teams exhibit highest price sensitivity due to compressed seven-year renovation cycles, while healthcare facility managers prioritize performance guarantees over first cost.
Supply Chain Analysis
REACH qualification and ECHA PFAS restrictions gate supplier participation, forcing systematic reformulation investment that thins the qualified vendor base. Manufacturing concentrates in the United States, Germany, and Belgium, with fiber production anchored in the Southeast US manufacturing belt and finishing operations clustering near Frankfurt and Ghent. Nylon 6,6 polymer and castor oil-derived polyol inputs draw from petrochemical and agricultural chemical supply chains respectively. Single-source vulnerability runs through adipic acid intermediates for premium face fiber. Distribution runs through commercial flooring contractor networks with direct specification relationships to facility managers and architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA's PFAS restriction proposal erects barrier-to-entry moats favoring incumbents with reformulation capital reserves.
For Market Incumbents: Deploy closed-loop reclamation infrastructure to capture extended producer responsibility value pools before EU member states shift collection cost liability. Consolidate position through backward integration into bio-based polyurethane feedstocks, specifically castor oil-derived polyol supply chains. Hard surface substitution from luxury vinyl tile demands defensive specification partnerships with acoustic engineering consultants. For New Entrants and Emerging Players: Healthcare facility managers in Japan's Kanto region represent an underserved buyer archetype where JIS slip-resistance testing filters legacy competitors. Target modular carpet tile for rapid-turn tenant churn environments in Germany's Frankfurt corridor, where LEED-equivalent certification mandates create specification velocity. Lead with virtual material library integration to compress architect decision cycles against showroom-dependent incumbents. For Investors and Strategic Acquirers: ECHA's 2023 restriction proposal advancing to implementation is the leading indicator that PFAS-free chemistry portfolios will command acquisition premiums. Long-term viability centers on fiber-to-finish manufacturing control with captive recycled content streams. The signal to monitor is public procurement tender language shifting from voluntary to mandatory third-party PFAS-free certification.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Reclamation Infrastructure | Captures EU extended producer responsibility value pools before cost liability shifts. |
| Bio-Based Backing Formulation | Castor oil-derived polyols satisfy LEED-equivalent thresholds without dimensional stability trade-offs. |
| Virtual Material Library Integration | Compresses architect specification cycles from weeks to days against showroom-dependent rivals. |
| PFAS-Free Chemistry Certification | Third-party validation unlocks German and French public procurement tender participation. |
| Solution-Dyed Nylon Capacity Expansion | Resilience under rolling loads sustains premium positioning in airport and hospital segments. |
Study Parameters
Document review covered customs trade databases, SEC manufacturing disclosures, and EU regulatory filings, complemented by interviews with commercial flooring contractors, facility managers at German office portfolios, hospitality procurement directors, and ECHA compliance consultants. Primary fieldwork triangulated specification behavior patterns with secondary validation against EPA indoor air quality guidelines and REACH restriction proposals. Bottom-up volume estimates from fiber production capacity and top-down demand calibration from commercial construction permits were reconciled.
Output metrics span value and volume across the projection horizon, with segmentation dimensions covering construction method, fiber chemistry, end-use environment, and installation protocol. CAGRs derive from regression against commercial real estate renovation cycle data and embodied carbon threshold adoption curves. Key inputs include petrochemical feedstock price volatility indices and EU member state extended producer responsibility implementation timelines.
Revisions become necessary when ECHA restriction proposals accelerate to binding implementation or when EU Green Deal building renovation targets shift mandatory compliance dates. Forecasts reflect assumptions about REACH chemical restriction scope and adhesive VOC compliance pathways. A model refresh is warranted upon material change in commercial real estate capital availability or PFAS-free chemistry certification cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Germany Home Textile Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Bath Towel Market
Home Textiles
North America Home Textile Market
Home Textiles
Japan Home Textile Market
Home Textiles
Towel Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
China Home Textiles Market
Home Textiles
Blanket Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
UAE Home Textiles Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Latin America Home Textiles Market