
 Global Industrial Fabric Market | 2026-2036
Global Industrial Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Fabric Market Outlook
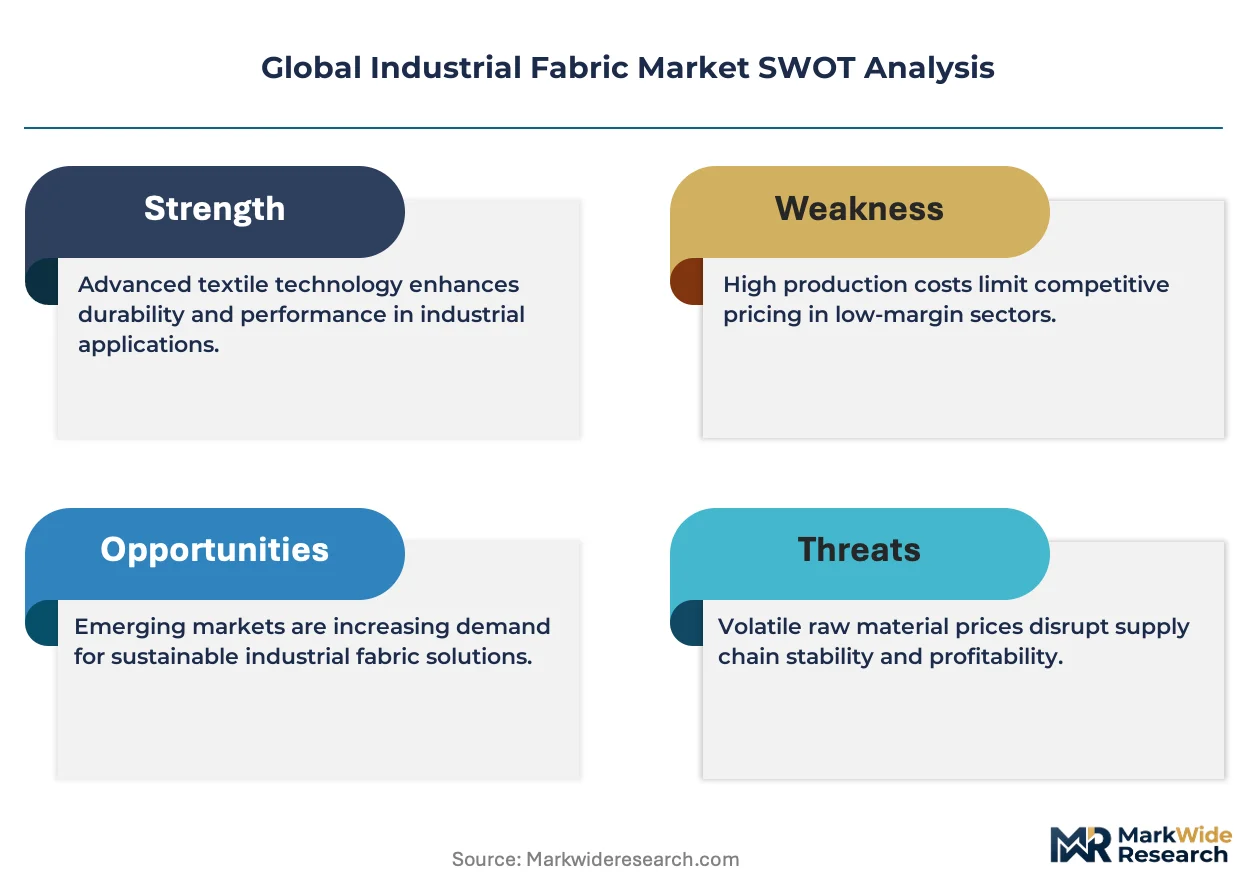
Capital-intensity divergence between integrated polymer producers and downstream converters is collapsing as resin volatility compresses margin buffers at every tier. Toray Industries anchors its position through captive filament production and carbon fiber composite integration for aerospace-grade fabrics. Freudenberg Performance Materials SE & Co KG differentiates via membrane-lamination expertise that serves automotive and filtration end users with specification-tight supply contracts. Berry Global Inc. extends its reach through blown-film and non-woven platform scale that spans geotextile and protective-clothing applications.
Industrial fabrics are engineered textile structures manufactured from high-tenacity fibers such as polyester, nylon, or fiberglass, typically exceeding 200 denier and designed to withstand mechanical stress, chemical exposure, or thermal loads in demanding operational environments. These materials function as load-bearing substrates, barrier membranes, or protective interfaces across manufacturing, infrastructure, and transportation systems. Non-woven fabrics lead volume throughput due to spunbond and meltblown process efficiencies that lower unit costs for disposable and semi-durable applications. Woven fabrics retain premium positioning in conveyor belts and industrial linings where tensile strength and dimensional stability command specification-driven pricing. Specialty fabrics, including aramid and PTFE-coated constructions, occupy concentrated margin pools in aerospace and military protective clothing where certification barriers limit supplier entry.
The EPA enforces emissions controls on textile coating and finishing operations that elevate compliance costs for U.S.-based manufacturers serving automotive and construction segments. REACH and the EU Green Deal impose substance-restriction and recycled-content thresholds that reshape material sourcing for European industrial fabric producers exporting to regulated end markets. China's MEE administers dual carbon goals that tighten energy-intensity standards for polyester and nylon filament production, affecting feedstock availability for domestic weavers and non-woven converters. Stakeholders must monitor how fragmented regulatory timelines across these jurisdictions alter total cost of ownership calculations for global specification contracts.
Market Dynamics
Polyester and nylon filament supply concentration in Zhejiang and Jiangsu provinces is compressing margin buffers for downstream converters across every tier of the industrial fabric value chain.
Growth Catalysts
- EU Green Deal recycled-content mandates:Specification requirements for construction geotextiles and automotive interior fabrics are redirecting procurement toward certified recycled-content suppliers, creating tiered qualification barriers that favor early movers.
- China state-backed infrastructure corridors:Belt and Road Initiative spending on transportation networks is pulling geotextile volume toward domestic spunbond and needle-punch producers with captive resin supply.
- Filament winding automation:Advanced tension control systems are reducing defect rates in fiberglass roving for wind blade fabrics, enabling specification entry into aerospace-qualified supply chains.
Market Restraints
- PTA and MEG feedstock volatility:Purified terephthalic acid and monoethylene glycol price swings transmit directly into polyester industrial fabric margins, with no hedging instruments available to mid-scale converters.
- Carbon fiber precursor concentration:PAN-based precursor supply locks in Japan and the United States create chokepoints for aerospace-grade composite fabric qualification timelines.
- REACH substance restriction friction:ECHA's expanding SVHC candidate list forces reformulation of coating chemistries for automotive and filtration membranes, extending R&D cycles by 18-24 months.
Strategic Opportunities
- India technical textile corridors:PLI scheme incentives for geotextile and agro-textile manufacturing are attracting filament investment to Tamil Nadu and Gujarat, creating alternative supply bases to China-centric sourcing.
- Aramid-PBI blend convergence:Military protective clothing specifications are converging toward hybrid thermal barrier fabrics that exceed single-fiber performance limits, opening margin pools for specialty weavers with lamination expertise.
- Digital specification platforms:Blockchain-traceable fiber certification is emerging as a procurement gate for EU and North American automotive tier-1 contracts, rewarding suppliers with integrated quality systems.
Industry Challenges
- Multiaxial loom operator scarcity:Advanced warp knitting for carbon fiber preforms requires 3-5 year training cycles that outpace vocational pipeline output in Germany and the United States.
- Flame-retardant certification fragmentation:Divergent NFPA 701, EN 13501, and GB 8624 test protocols force redundant testing spend for suppliers serving multiple end-use verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Fabric Market |
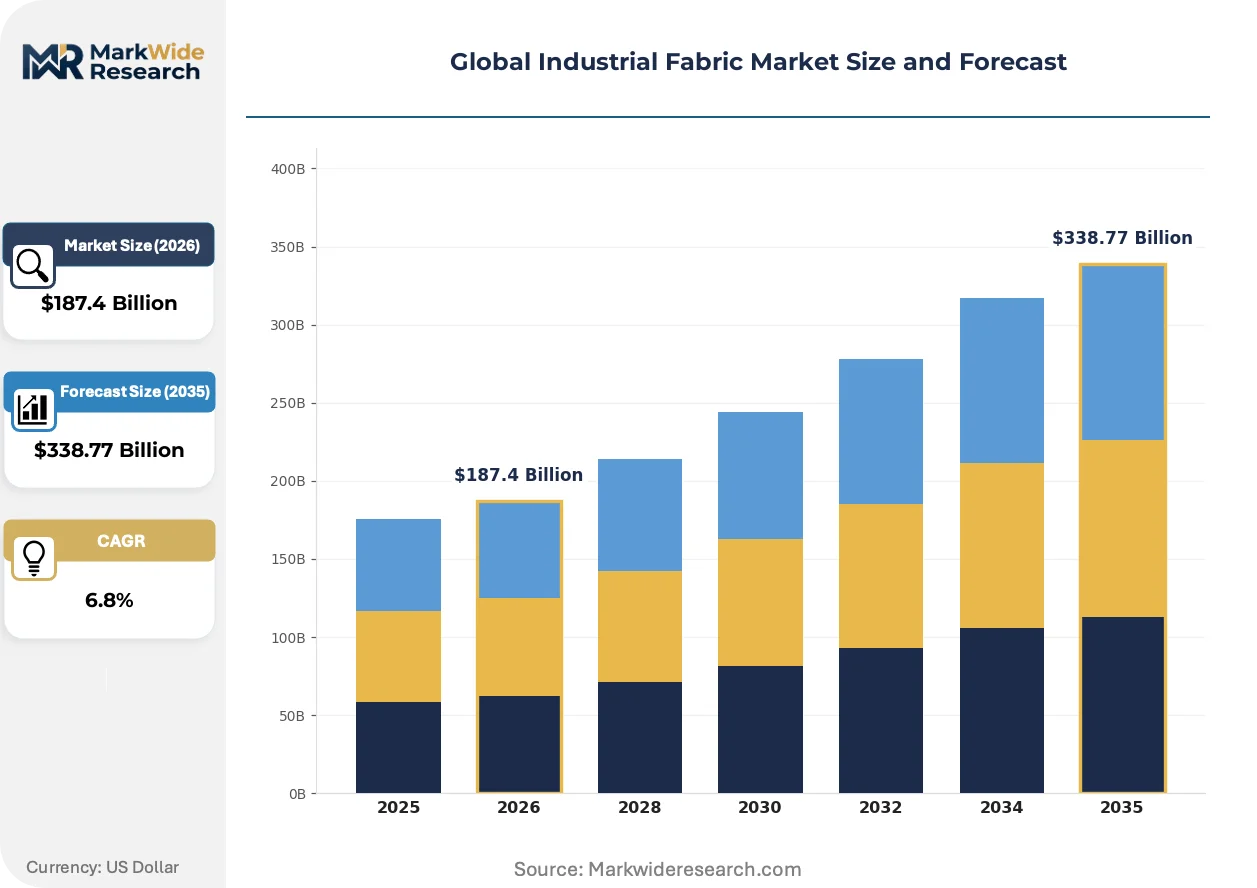
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Specialty Fabrics End User: Automotive, Construction, Aerospace, Military Application: Geotextiles, Protective Clothing, Industrial Linings, Conveyor Belts Material: Polyester, Nylon, Cotton, Fiberglass |
| Companies Covered | Berry Global Inc., Saint-Gobain S.A., Toray Industries Inc., Ahlstrom-Munksjö Oyj, Bridgestone Corporation, Milliken & Company, Freudenberg Performance Materials SE & Co KG, Donaldson Company Inc., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Fabric Market Strategic Shifts
Material science convergence with digital manufacturing is collapsing traditional boundaries between fiber production, fabric formation, and functional finishing in industrial textile supply chains.
Carbon nanotube-doped conductive yarns are miniaturizing static-dissipative functions into lightweight woven structures for cleanroom and explosive-handling environments. Semiconductor fabrication facilities in South Korea and Taiwan are specifying these fabrics for personnel grounding systems at sub-50 ohm resistance thresholds. The technology is miniaturizing what previously required metal fiber blends or external grounding straps into seamless garment integration.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing phase-out of legacy stain-resistant coatings for industrial protective fabrics. ECHA's 2023 restriction proposal covers C9-C14 PFCAs in textiles, compelling reformulation toward silicone and hydrocarbon-based alternatives for oil-repellent workwear. European converters serving the German automotive sector are accelerating qualification of fluorine-free membrane laminates to maintain CE marking compliance.
Specification bundling by infrastructure EPC contractors is consolidating geotextile procurement into multi-year framework agreements with integrated installation services. Design-build contracts in Australia and Canada are displacing spot-market purchasing for transportation and landfill projects, locking out smaller converters without civil works capabilities. This pattern concentrates volume among suppliers with geotechnical engineering subsidiaries or joint venture partnerships.
Global Industrial Fabric Market Segmentation
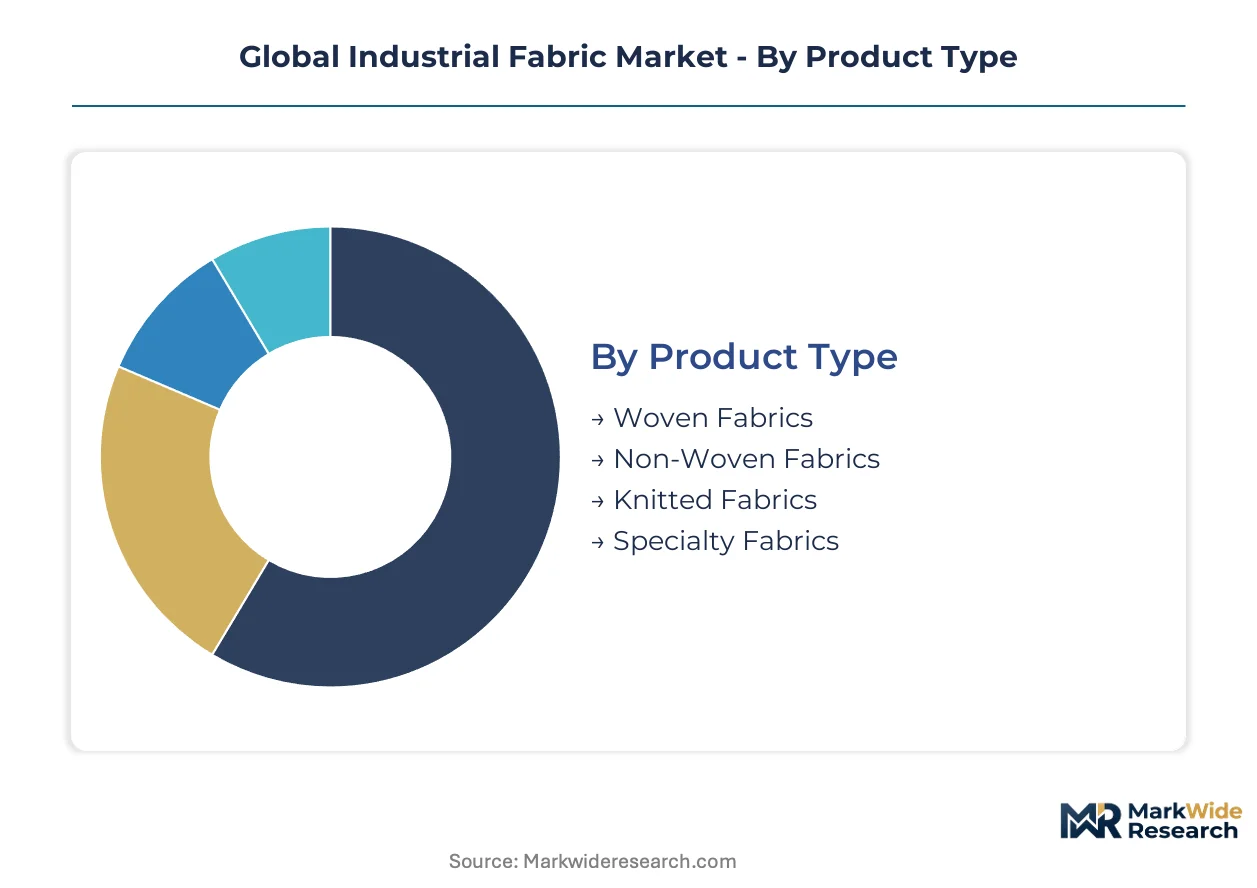
Industrial fabric procurement splits across multiple technical dimensions that determine specification authority and margin capture. Product construction, end-use certification requirements, and material chemistry each create distinct competitive arenas with divergent barriers to entry.
Product Type:
Premium margin pools concentrate in engineered constructions with certification-intensive qualification timelines, while commodity-grade formats compete on throughput scale.
- Non-Woven Fabrics:Spunbond and meltblown processes deliver high-throughput output for disposable and semi-durable applications. State-backed infrastructure corridors in China are pulling geotextile volume toward domestic needle-punch producers with captive resin supply, compressing margin buffers for importers.
- Woven Fabrics:Warp and weft interlacing provides tensile strength and dimensional stability for load-bearing industrial applications. Conveyor belt and industrial lining specifications in Germany and Japan command qualification-driven pricing tiers that resist commoditization pressure.
- Knitted Fabrics:Loop-structured constructions offer elasticity for protective apparel and filtration substrates.
- Specialty Fabrics:Aramid, PTFE-coated, and carbon fiber composite constructions serve aerospace and military protective clothing with certification barriers limiting supplier entry.
The dominant share belongs to Non-Woven Fabrics, while Specialty Fabrics is closing the gap fastest.
End User:
Procurement authority varies sharply across customer verticals, with specification gatekeepers in regulated industries extracting compliance investments from suppliers.
- Construction:Geotextile and protective membrane demand accelerates across Belt and Road Initiative transportation networks. EPC contractors in Australia and Canada are consolidating procurement into multi-year framework agreements that displace spot-market purchasing.
- Automotive:Interior fabric and filtration membrane specifications are redirecting toward recycled-content suppliers under EU Green Deal mandates. Tier-1 suppliers in Germany now require blockchain-traceable fiber certification as a procurement gate.
- Aerospace:Carbon fiber preform and composite fabric qualification timelines lock in PAN-based precursor dependencies from Japan and the United States.
- Military:Protective clothing specifications are converging toward aramid-PBI hybrid thermal barrier fabrics that exceed single-fiber performance limits.
Construction commands the largest procurement volume, though Automotive is expanding most quickly as electrification reshapes interior material specifications.
Application:
Functional performance requirements determine whether applications compete on unit cost or specification-locked premium positioning.
- Geotextiles:Load-bearing and barrier membrane functions for soil stabilization and drainage. Infrastructure corridors in China and specification bundling by EPC contractors are concentrating volume among suppliers with integrated installation capabilities.
- Protective Clothing:Thermal, chemical, and mechanical hazard protection for industrial and military personnel. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oil-repellent coatings toward silicone and hydrocarbon-based alternatives.
- Industrial Linings:Chemical-resistant barriers for storage tanks and processing equipment.
- Conveyor Belts:High-tensile substrates for material handling systems in mining and manufacturing.
Geotextiles generate the highest absolute volume, while Protective Clothing is gaining share fastest as regulatory complexity deepens qualification barriers.
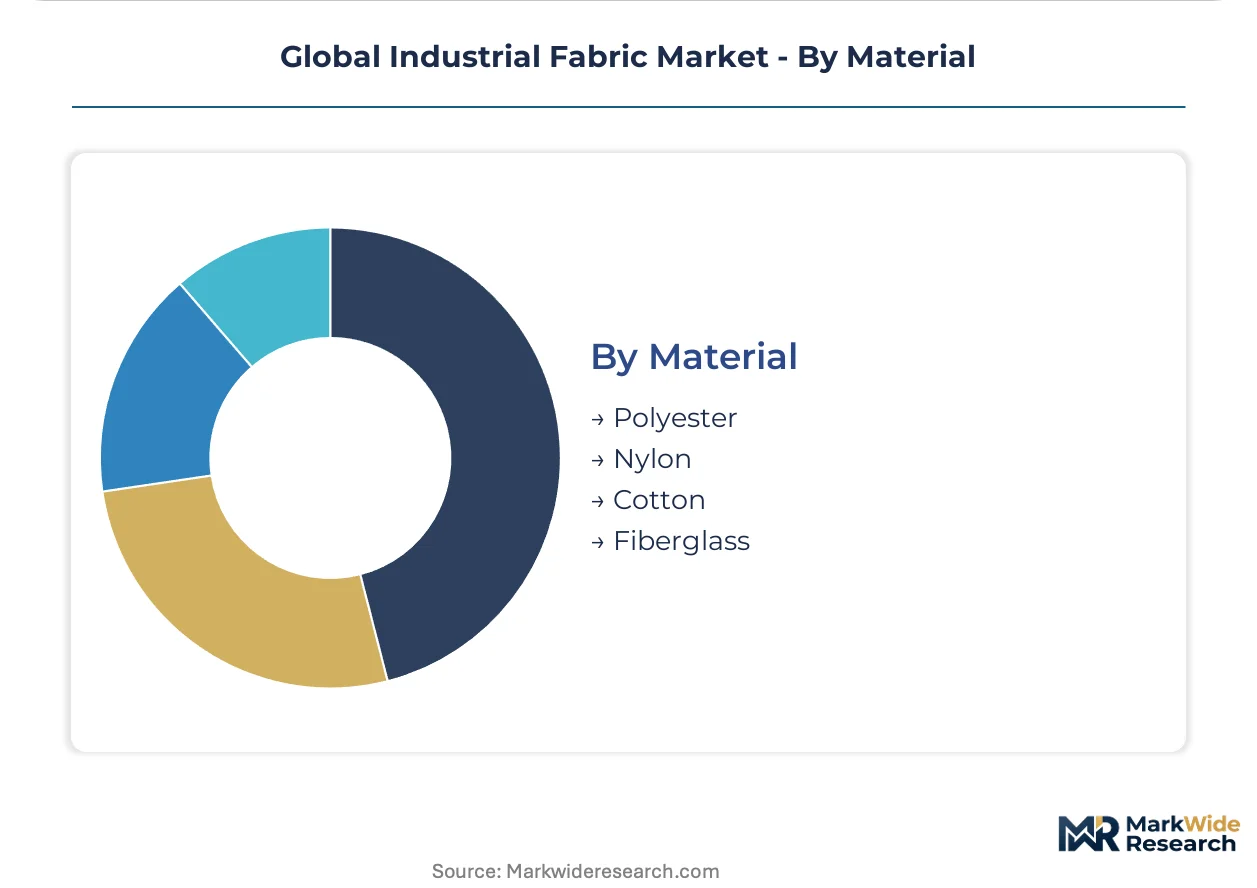
Material:
Feedstock chemistry dictates exposure to petrochemical volatility and regional supply concentration risks.
- Polyester:High-tenacity filament derived from PTA and MEG monomers dominates volume throughput. Supply concentration in Zhejiang and Jiangsu provinces transmits feedstock price swings directly into converter margins with limited hedging availability.
- Nylon:Polyamide constructions offer superior abrasion resistance for industrial linings and conveyor belts. China's MEE dual carbon goals are tightening energy-intensity standards for filament production, affecting domestic weaver feedstock access.
- Cotton:Natural fiber retains niche positioning in breathable protective apparel with limited chemical exposure requirements.
- Fiberglass:Silica-based roving provides thermal and electrical insulation for wind blade fabrics and aerospace composites. Advanced tension control systems in automated filament winding are reducing defect rates for specification entry into aerospace-qualified supply chains.
Polyester holds the dominant material position, though Fiberglass is climbing the fastest as wind energy and aerospace composite demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward net outflows from Asian filament production clusters while European and North American markets absorb specialty fabric volumes for regulated end uses. Currency volatility and freight rate fluctuations are compressing margin buffers for converters without captive resin supply or regional manufacturing presence.
China
State-backed infrastructure corridors along Belt and Road Initiative routes are pulling geotextile procurement toward domestic spunbond producers. MEE dual carbon goals tighten energy-intensity standards for polyester and nylon filament manufacturing in Zhejiang province. The Yangtze River Delta concentration of PTA-MEG refining and downstream weaving creates chokepoints that transmit feedstock volatility directly into converter margins.
Germany
Automotive interior fabric specifications from Stuttgart and Munich-based tier-1 suppliers now require blockchain-traceable fiber certification as a procurement gate. REACH substance restrictions and EU Green Deal recycled-content mandates reshape coating chemistry formulation cycles. The Baden-Württemberg industrial belt hosts warp knitting specialists serving conveyor belt and industrial lining applications with qualification-driven pricing.
United States
EPA emissions controls on textile coating operations elevate compliance costs for manufacturers serving automotive and construction segments. Aerospace composite fabric demand concentrates around Seattle and Wichita production clusters dependent on PAN-based precursor imports. The Southeast textile corridor is attracting non-woven investment to bypass resin volatility exposure from Asian supply chains.
India
PLI scheme incentives for geotextile and agro-textile manufacturing are drawing filament investment to Tamil Nadu and Gujarat. BIS certification requirements for technical textiles create qualification barriers favoring early movers with integrated quality systems. The Coimbatore-Tiruppur belt is emerging as an alternative needle-punch supply base to China-centric sourcing for Middle East infrastructure projects.
Japan
Carbon fiber precursor and aerospace-grade composite fabric qualification timelines lock in supply dependencies for domestic weavers. METI industrial policy supports filament winding automation investment to reduce defect rates in wind blade fabric production. The Nagoya-Toyota industrial corridor maintains premium positioning in automotive filtration membrane specifications requiring JIS-standard compliance.
Global Industrial Fabric Market Competitive Environment
Concentration sits with integrated polymer producers possessing captive filament supply and downstream converters with specification-locked certification authority. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into resin production, mid-scale specialists with membrane-lamination or coating expertise, and regional non-woven converters competing on throughput scale. Dominant competitive moves include capacity expansion in India and Southeast Asia to bypass China-centric supply risks, and portfolio diversification toward fluorine-free coating chemistries to maintain EU market access.
Among diversified industrial conglomerates, Toray Industries Inc., Saint-Gobain S.A., and DuPont de Nemours Inc. exemplify archetypes spanning carbon fiber composites, construction materials, and specialty chemicals respectively. Toray represents integrated filament-to-fabric production with aerospace qualification authority. Saint-Gobain occupies a position bridging construction geotextiles and protective membrane systems. DuPont sits within the specialty materials tier where aramid and fluoropolymer expertise commands specification premiums in military and industrial protective clothing.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Saint-Gobain S.A. |
| Toray Industries Inc. |
| Ahlstrom-Munksjö Oyj |
| Bridgestone Corporation |
| Milliken & Company |
| Freudenberg Performance Materials SE & Co KG |
| Donaldson Company Inc. |
| DuPont de Nemours Inc. |
| Others |
Value Chain & Pricing Dynamics
Filament winding automation scale in Zhejiang province compresses unit production costs for polyester and nylon feedstock, concentrating supply power among integrated producers while transmitting price volatility directly to downstream converters without captive resin supply. This scale asymmetry creates divergent margin buffers across the value chain, with specification-locked specialty weavers defending premium positioning against commodity-grade non-woven competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as primary differentiation drivers. Cost compression in commodity spunbond geotextiles is intensifying because state-backed infrastructure corridors in China are consolidating procurement into framework agreements that favor domestic producers with captive PTA-MEG supply. Tier-1 automotive suppliers in Germany exhibit lowest price sensitivity due to blockchain-traceable fiber certification requirements, while Middle East infrastructure contractors show highest sensitivity as they arbitrage between Indian and Chinese needle-punch supply bases.
Supply Chain Analysis
China, India, and Germany anchor industrial fabric manufacturing across distinct tier positions, with China dominating filament production, India emerging as alternative needle-punch supply, and Germany retaining warp knitting specialization for conveyor belts. Raw material dependencies draw from PTA-MEG refining clusters in the Yangtze River Delta, PAN-based carbon fiber precursor from Japan and the United States, and aramid fiber from DuPont's domestic production. Single-source vulnerability sits with aerospace-grade composite fabric qualification timelines locked to Japanese and American precursor supply. Distribution runs through EPC contractor framework agreements in infrastructure, tier-1 supplier direct contracts in automotive, and spot-market purchasing for protective clothing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lamination expertise and automated multiaxial loom operation represent acute capability gaps that constrain supply expansion in aerospace and military protective clothing segments. The market rewards backward-integrated producers with qualification authority while marginalizing converters without fiber certification traceability.
For Market Incumbents: Shield specification-locked positions in aerospace carbon fiber preforms and automotive filtration membranes by accelerating fluorine-free coating chemistry qualification ahead of REACH SVHC expansion. Prioritize captive filament investment in Tamil Nadu and Gujarat to bypass China-centric resin volatility exposure. Defensive consolidation should target membrane-lamination specialists in Germany's Baden-Württemberg belt to reinforce tier-1 supplier relationships. For New Entrants and Emerging Players: Anchor in India's technical textile corridors under PLI scheme incentives, specifically targeting geotextile supply for Middle East infrastructure projects where BIS certification creates first-mover qualification barriers. Military protective clothing offers penetrable white space as aramid-PBI blend specifications converge and incumbent capacity remains constrained by multiaxial loom operator scarcity. Go-to-market should emphasize blockchain-traceable fiber certification as procurement gate for EU and North American automotive contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane-lamination specialists with fluorine-free chemistry pipelines and integrated quality systems over commodity non-woven converters exposed to resin volatility. Long-term viability hinges on qualification authority in regulated end uses rather than throughput scale in disposable applications. Watch carbon fiber precursor supply diversification signals from Japanese and American producers as inflection indicator for aerospace fabric margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filament Production | Captive PTA-MEG supply in Zhejiang and Jiangsu insulates converters from feedstock volatility transmitted through spot resin markets. |
| Fluorine-Free Coating Chemistry Qualification | REACH restrictions on per- and polyfluoroalkyl substances force reformulation to maintain CE marking access for EU automotive and protective clothing. |
| Blockchain-Traceable Fiber Certification | Tier-1 automotive suppliers in Germany and North America now require digital specification platforms as procurement gate for contract eligibility. |
| Multiaxial Loom Operator Training Investment | Three-to-five year vocational cycles for advanced warp knitting create defendable moats in carbon fiber preform supply for aerospace. |
| Geotechnical Engineering Subsidiary Acquisition | EPC contractors in Australia and Canada consolidate procurement into design-build frameworks that exclude pure-play converters without installation capabilities. |
Study Parameters
The analysis maps non-woven, woven, knitted, and specialty fabric constructions, each validated through procurement directors at EPC contractors, tier-1 automotive supplier quality managers, and military protective clothing specification officers. Primary interviews with plant managers at Zhejiang filament facilities, R&D directors at German membrane-lamination specialists, and distribution channel partners in Middle East infrastructure combined with secondary validation from customs trade data, EPA emissions filings, REACH SVHC candidate lists, and SEC 10-K disclosures for diversified industrial conglomerates. Bottom-up segment sizing and top-down macroeconomic triangulation ensured consistency across volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation dimensions spanning product construction, end-use vertical, application function, and material chemistry. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements, incorporating wind energy composite demand acceleration, EU Green Deal recycled-content mandate compliance timelines, and China MEE dual carbon goal implementation as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure spending in Belt and Road corridors and stable REACH regulatory timelines; material deviation in petrochemical feedstock volatility or carbon fiber precursor supply disruption would warrant model refresh. Recalibration cycles align with material shifts in dual carbon goal enforcement intensity, ECHA SVHC list expansion, and filament winding automation adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Sewing Machine Market