
 Tobacco Drying Machines Market | 2026-2036
Tobacco Drying Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Drying Machines Market Insights
Leaf curing operations within contract manufacturing are rebalancing toward continuous-flow systems as independent growers shrink in relative share. Körber Technologies GmbH leverages its European installed base to sustain aftermarket service revenue across aging batch dryer fleets. CPM Wolverine Proctor anchors North American supply through specialized rotary dryer engineering for high-throughput processors. Qinhuangdao Tobacco Machinery dominates domestic retrofit demand with localized control systems that compete on total cost of ownership.
Tobacco drying machines are thermal processing systems engineered to reduce leaf moisture content from 80-85% to 12-15% through controlled heat application, typically operating at 45-75°C with precise humidity management to preserve combustibility and aromatic compounds. Continuous dryers command the largest installed base due to throughput economics at processing mills, while microwave drying represents the fastest-expanding technology segment as energy efficiency mandates intensify operational scrutiny. Vacuum dryers occupy a narrow premium niche serving aroma-sensitive specialty leaf grades where oxidation control determines product value.
EPA emissions standards constrain thermal dryer designs in the United States, while EU F-Gas Regulation phases out refrigerants used in heat pump-based curing systems, forcing equipment redesigns across European installations. China's GB standards and MIIT energy efficiency directives shape domestic manufacturing compliance thresholds for export-bound machinery. Stakeholders must monitor regulatory divergence between thermal efficiency mandates and refrigerant transition timelines when configuring regional product portfolios and service networks.
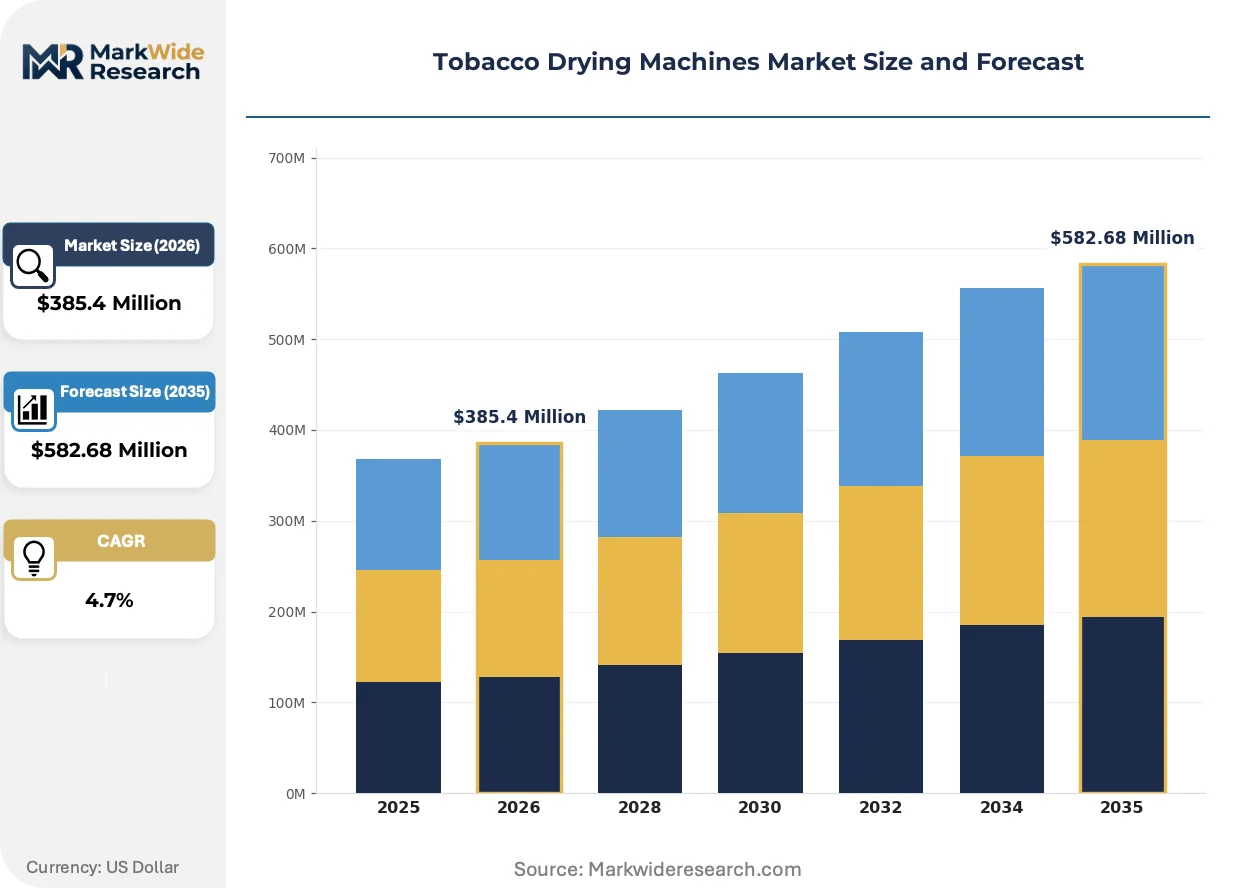
Market Dynamics
Contract manufacturers are consolidating leaf processing capacity and replacing aging batch dryers with continuous-flow thermal systems that cut energy consumption per kilogram of cured tobacco. This capital rotation is compressing equipment replacement cycles from fifteen years toward eight-year refresh timelines.
Growth Catalysts
- EPA emissions standards:US processors face mandatory thermal efficiency upgrades that accelerate capital expenditure on modern curing infrastructure with integrated emission controls.
- Microwave drying technology:Energy-intensive processors in Brazil and China adopt radio-frequency systems that reduce curing time by sixty percent while preserving aromatic compound profiles.
- Contract manufacturing concentration:Vertically integrated tobacco processors in Brazil are modernizing curing infrastructure to capture economies of scale as independent growers exit.
Market Restraints
- Natural gas price volatility:Thermal dryer operating costs fluctuate with European and Asian energy markets, compressing processor margins and deferring equipment upgrades.
- Heat pump refrigerant phase-out:EU F-Gas Regulation forces redesign of energy-efficient curing systems, extending equipment certification timelines and raising development costs.
- Batch dryer fleet inertia:Aging but functional equipment in Eastern Europe and Central Asia delays replacement demand despite efficiency disadvantages.
Strategic Opportunities
- Vacuum drying niche expansion:Premium cigar and specialty pipe tobacco processors pay price premiums for oxidation-controlled curing that preserves volatile aromatic compounds.
- India leaf processing modernization:Domestic contract manufacturers seek automated curing systems as BIS energy efficiency directives tighten compliance thresholds for export-bound machinery.
- Heat pump technology convergence:Integration of industrial heat pumps with smart humidity controls opens retrofit markets in EU member states facing F-Gas transition deadlines.
Industry Challenges
- Thermal process engineering talent scarcity:Equipment manufacturers struggle to hire specialists who understand both leaf biochemistry and industrial heat transfer optimization.
- Legacy control system integration:Continuous-flow dryers must interface with decades-old SCADA architectures at processing mills, complicating commissioning and raising project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Drying Machines Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $582.68 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Dryers, Batch Dryers, Fluidized Bed Dryers, Rotary Dryers, Vacuum Dryers Technology: Hot Air Drying, Microwave Drying, Infrared Drying, Solar Drying, Freeze Drying Application: Leaf Curing, Moisture Removal, Color Conditioning, Aroma Development End User: Contract Manufacturers, Independent Growers, Processing Mills, Tobacco Traders, Leaf Dealers |
| Companies Covered | Ksec Intelligent Technology, China Tobacco Zhejiang Industrial, Qinhuangdao Tobacco Machinery, Shandong Longertek Technology, TONGYI Heat Pump, Zhejiang AMA and HIEN Technology, Körber Technologies GmbH, ITM Group, CPM Wolverine Proctor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Drying Machines Market Trends and Innovations
Equipment vendors are re-engineering thermal systems around energy recovery and precision humidity management as regulatory pressure intensifies and processor margins compress. The competitive frontier has shifted from raw throughput toward total cost of ownership optimization.
Radio-frequency microwave drying is decentralizing curing capacity away from centralized processing mills toward satellite facilities closer to leaf-growing regions. Mid-scale processors in Brazil and Indonesia are piloting modular microwave units that eliminate the logistics cost of transporting wet leaf to distant curing barns. This distributed architecture is compressing the historical advantage of large-scale continuous dryers by reducing transport spoilage and enabling just-in-time processing.
EU F-Gas Regulation is forcing refrigerant transitions in heat pump-based curing systems that European OEMs must complete before phase-out deadlines tighten. Equipment redesigns now prioritize natural refrigerants with lower global warming potential, extending product development cycles by twelve to eighteen months. German and Italian manufacturers are absorbing these compliance costs into premium pricing for new installations while aftermarket service revenue from aging fleets sustains near-term margins.
After-sales service unbundling is disrupting traditional equipment procurement as contract manufacturers negotiate predictive maintenance contracts separately from capital purchases. Brazilian and Chinese processors now benchmark vendors on spare parts availability and remote diagnostic capability rather than upfront equipment cost alone. This shift favors suppliers with established regional service networks over low-cost entrants lacking localized technical support infrastructure.
Tobacco Drying Machines Market Segmentation
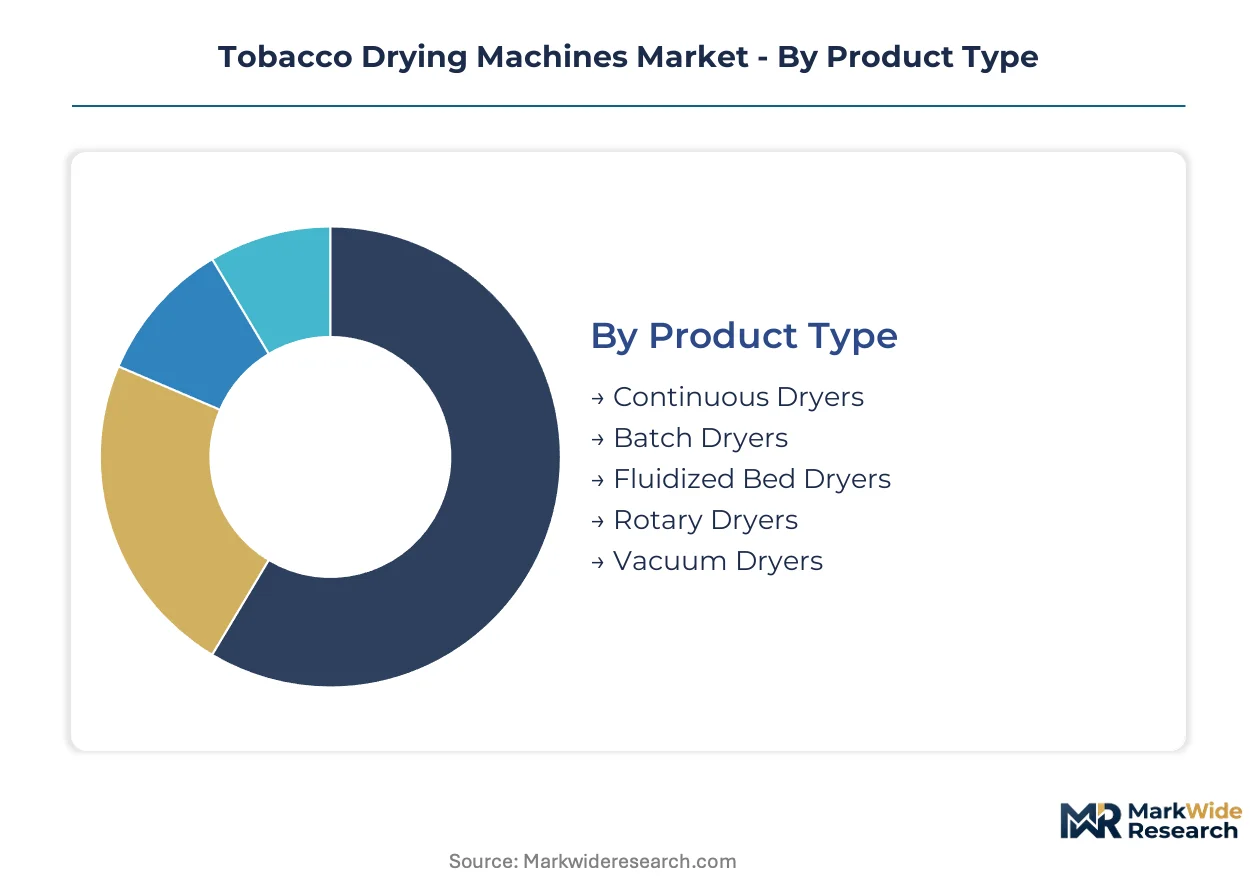
Equipment selection in tobacco drying hinges on throughput requirements, energy cost structures, and regulatory compliance timelines. Processors weigh capital intensity against operating economics as leaf consolidation reshapes demand concentration across buyer categories.
Product Type:
Procurement decisions center on throughput scale and energy recovery capabilities as contract manufacturers consolidate processing capacity.
- Continuous Dryers:These systems move leaf through heated zones on conveyor mechanisms, enabling uninterrupted processing at industrial scale. Brazilian and Chinese contract manufacturers dominate demand as vertically integrated processors replace aging batch infrastructure to capture economies of scale.
- Batch Dryers:Chamber-based systems cure discrete leaf loads in controlled cycles, offering flexibility for mixed-grade operations. Eastern European and Central Asian processors maintain substantial installed bases despite efficiency disadvantages, deferring replacement cycles amid functional fleet inertia.
- Fluidized Bed Dryers:Air suspension systems suspend particles in upward-flowing heated gas for rapid, uniform moisture reduction.
- Rotary Dryers:Cylindrical drums rotate leaf through heated environments, serving high-throughput processors with established maintenance capabilities.
- Vacuum Dryers:Reduced-pressure chambers enable low-temperature moisture removal that preserves volatile aromatic compounds. Premium cigar and specialty pipe tobacco processors in Nicaragua and the Dominican Republic absorb price premiums for oxidation-controlled curing where aromatic preservation determines product value.
Volume sits with continuous systems; growth tilts toward vacuum configurations as premium tobacco segments expand.
Technology:
Energy efficiency mandates and operating cost pressures are reconfiguring technology adoption curves across processing regions.
- Hot Air Drying:Convective thermal systems remain the dominant installed technology, utilizing fossil fuel or biomass combustion for heated air circulation. Natural gas price volatility in European and Asian markets compresses processor margins and defers upgrade decisions despite regulatory pressure.
- Microwave Drying:Radio-frequency energy penetrates leaf structure to vaporize moisture from within, reducing curing duration substantially. Brazilian mid-scale processors pilot modular units that eliminate wet leaf transport costs and enable satellite facility deployment closer to growing regions.
- Infrared Drying:Radiant heat transfer systems target surface moisture with precise wavelength control.
- Solar Drying:Ambient energy capture systems serve small-scale operations in sun-intensive growing regions with limited capital access.
- Freeze Drying:Sublimation-based moisture removal preserves cellular structure at ultra-low temperatures. Aroma-sensitive specialty grades in premium segments command this technology where conventional thermal methods degrade volatile compound profiles.
Installed base concentrates in hot air systems; steepest expansion trajectory belongs to microwave configurations as energy scrutiny intensifies.
Application:
Functional requirements vary sharply across the value chain, from commodity bulk processing to precision aroma engineering.
- Leaf Curing:The foundational moisture reduction process transforms harvested leaf from 80-85% moisture to storable levels. Contract manufacturers in Brazil and Indonesia drive capital deployment as independent grower exit accelerates processing consolidation.
- Moisture Removal:Precision finishing operations achieve final specification moisture of 12-15% for commercial readiness.
- Color Conditioning:Controlled thermal profiles develop visual grading characteristics that determine auction and contract pricing tiers.
- Aroma Development:Maillard reaction engineering during controlled heating builds volatile compound portfolios that differentiate product positioning. Vacuum and microwave systems gain traction here as oxidation control and rapid processing preserve aromatic signatures that conventional methods degrade.
Capacity concentrates in leaf curing; margin capture tilts toward aroma development as premiumization deepens.
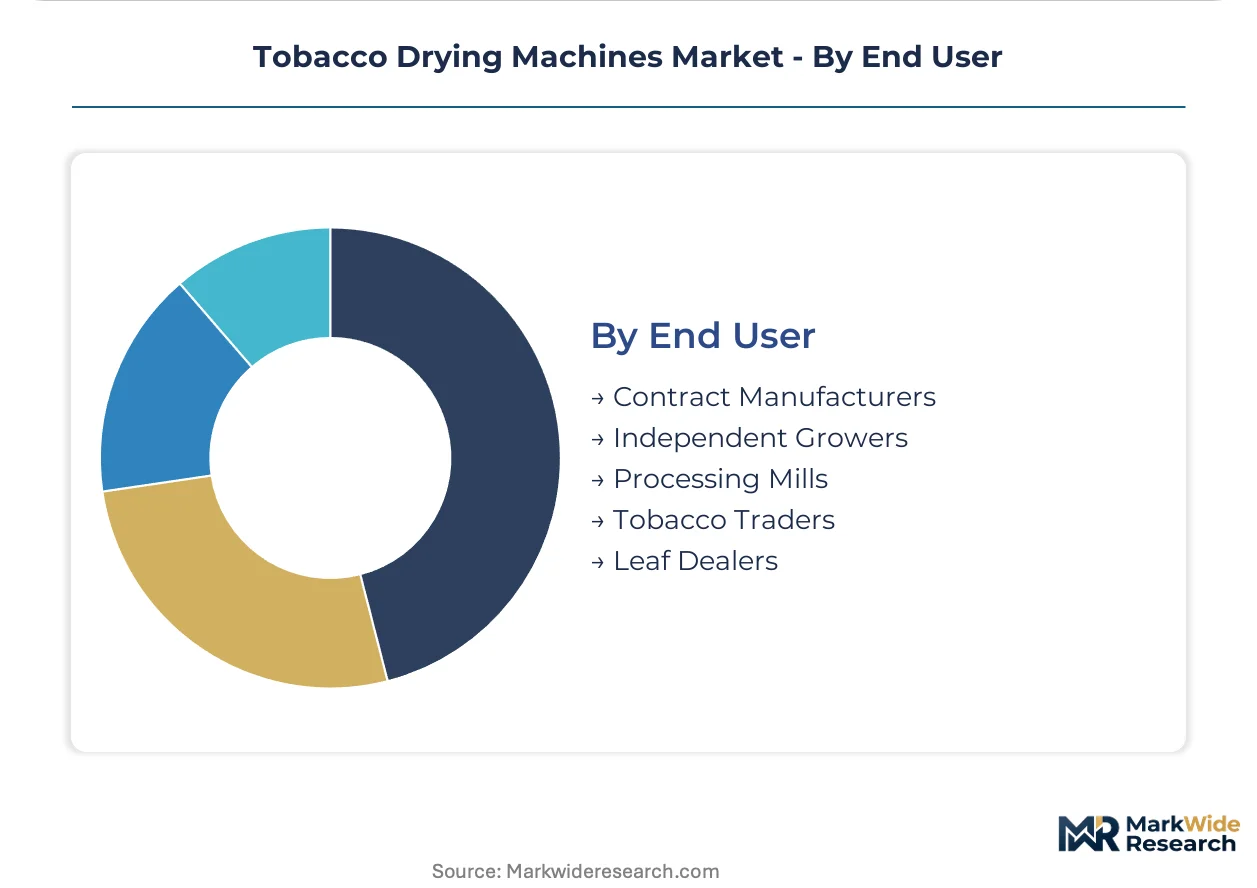
End User:
Buyer concentration patterns reflect structural shifts in leaf supply chain governance and capital access.
- Contract Manufacturers:Vertically integrated processors with captive leaf supply and brand relationships command the largest equipment procurement budgets. Brazilian operations modernize curing infrastructure most aggressively as domestic consolidation eliminates independent processing alternatives.
- Independent Growers:Small-scale agricultural operators with limited capital access maintain aging batch equipment or outsource curing entirely. Their relative share of processing capacity shrinks as contract manufacturing concentrates volume and investment capability.
- Processing Mills:Dedicated toll-processing facilities serve multiple leaf suppliers with standardized curing services.
- Tobacco Traders:Merchant intermediaries with speculative inventory positions require flexible curing capacity for grade arbitrage.
- Leaf Dealers:Regional aggregators with established grower networks coordinate curing logistics across dispersed supply bases.
Procurement volume sits with contract manufacturers; equipment demand growth tilts toward processing mills as toll-service outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing modernization concentrates in Brazil's Free Economic Zone of Manaus, where contract manufacturers cluster to capture tax-advantaged curing infrastructure investments. Equipment procurement patterns diverge sharply across regulatory jurisdictions as energy efficiency mandates tighten thermal system specifications.
Brazil
Vertically integrated processors in Santa Cruz do Sul and Rio Grande do Sul drive continuous-flow dryer procurement as independent grower exit accelerates consolidation. ANVISA pharmaceutical-grade manufacturing standards indirectly shape equipment hygiene specifications for export-bound leaf. São Paulo-based contract manufacturers anchor South American demand with eight-year equipment refresh cycles replacing aging batch infrastructure.
China
Domestic leaf processing consolidation in Yunnan and Guizhou provinces sustains retrofit demand for localized control systems. MIIT energy efficiency directives and GB standards tighten compliance thresholds for machinery exports to Belt and Road markets. Qinhuangdao equipment fabricators dominate northern retrofit activity with total-cost-of-ownership positioning against European imports.
United States
North Carolina and Kentucky processing mills face EPA emissions standards mandating thermal efficiency upgrades with integrated emission controls. Contract manufacturers benchmark equipment on predictive maintenance capability and spare parts availability rather than upfront capital cost. Richmond and Winston-Salem clusters anchor domestic curing infrastructure with fifteen-year fleet replacement accelerating toward eight-year timelines.
Germany
EU F-Gas Regulation forces refrigerant transitions in heat pump-based curing systems before phase-out deadlines tighten. Bavarian and Baden-Württemberg OEMs absorb compliance costs into premium pricing while aftermarket service revenue from aging fleets sustains near-term margins. Körber Technologies leverages its European installed base to sustain service revenue across aging batch dryer fleets.
India
Andhra Pradesh and Karnataka contract manufacturers seek automated curing systems as BIS energy efficiency directives tighten compliance for export-bound machinery. Domestic processing modernization lags Brazil and China but accelerates as tobacco traders consolidate toll-processing capacity. Guntur and Mysuru clusters represent emerging procurement pockets for continuous-flow thermal systems.
Tobacco Drying Machines Market Competitive Landscape
Top-tier vendors anchor premium-tier thermal engineering, while mid-scale fabricators compete on localized control integration and aftermarket service density. Market structure tilts toward regional concentration as procurement decisions weight spare parts availability and remote diagnostic capability over upfront equipment cost. Two strategic archetypes dominate: European OEMs with aging installed bases monetizing service revenue, and Chinese fabricators capturing domestic retrofit demand through total-cost-of-ownership positioning. Competitive moves center on predictive maintenance contract unbundling and heat pump technology convergence for EU F-Gas compliance.
Within the European service-revenue tier, Körber Technologies GmbH exemplifies aftermarket-dependent positioning anchored to aging batch dryer fleets. Chinese fabricators including Qinhuangdao Tobacco Machinery and Shandong Longertek Technology occupy the domestic retrofit vector with localized control system offerings. CPM Wolverine Proctor represents North American rotary dryer specialization serving high-throughput processors with established maintenance capabilities. These three archetypes illustrate competitive divergence across regulatory jurisdictions without overlapping customer segments.
| Leading Market Players |
|---|
| Ksec Intelligent Technology |
| China Tobacco Zhejiang Industrial |
| Qinhuangdao Tobacco Machinery |
| Shandong Longertek Technology |
| TONGYI Heat Pump |
| Zhejiang AMA and HIEN Technology |
| Körber Technologies GmbH |
| ITM Group |
| CPM Wolverine Proctor |
| Others |
Pricing and Supply Chain Analysis
Natural gas futures volatility in European and Asian markets cascades through thermal dryer manufacturing into tiered equipment pricing, where contract manufacturers absorb fuel-indexed surcharges while independent growers defer capital commitments entirely.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to continuous-flow systems with sub-six-month delivery windows, while spot inventory of standardized batch dryers trades at modest discounts. Pricing stratifies across premium, standard, and economy tiers based on automation depth and after-sales bundling density. Cost compression in the standard tier is intensifying because Chinese fabricators are exporting localized control systems at total-cost-of-ownership positions below European OEM baselines. Contract manufacturers demonstrate lowest price sensitivity due to captive volume and tax-advantaged financing access; independent growers exhibit acute sensitivity, driving secondhand equipment arbitrage.
Supply Chain Analysis
MIIT domestic-content mandates in China and BIS local-value-add requirements in India are reshaping sourcing patterns, forcing European and North American OEMs to establish regional assembly partnerships or forfeit public procurement eligibility. Component supply concentrates in China, Germany, and Italy for precision thermal engineering; control system fabrication rests on semiconductor inputs from Taiwan and South Korea. Steel and aluminum price volatility represents the dominant supply chain risk, compressing fabricator margins when hedging coverage proves insufficient. Distribution runs through authorized dealer networks in mature markets and direct mill relationships in Brazil and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around contract manufacturers with capital access, as independent grower exit eliminates marginal processing capacity and equipment demand concentrates among fewer, larger buyers.
For Market Incumbents: Cement service revenue dominance by unbundling predictive maintenance contracts from capital sales and establishing regional spare parts hubs in São Paulo and Yunnan. Invest in heat pump engineering capability before EU F-Gas phase-out deadlines tighten, as refrigerant transition competence becomes a procurement discriminator. Threat substitution from microwave drying technology demands counter-positioning through energy recovery integration in continuous-flow designs.
For New Entrants and Emerging Players: EPA emissions standards in the United States open a window for emission-control subsystem specialists to partner with established OEMs rather than compete on complete equipment. Target India's domestic retrofit segment, where BIS energy efficiency directives are accelerating replacement demand ahead of local fabricator capacity expansion. Go-to-market traction requires aftermarket service density commitments that match or exceed incumbent response times.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European batch dryer service specialists with aging installed bases and recurring revenue visibility in Germany and Eastern Europe. Long-term viability hinges on heat pump technology convergence capability and regional regulatory compliance depth. Monitor EU F-Gas implementation pace as the inflection signal—accelerated phase-out timelines would compress acquisition windows and reward early positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Convergence | EU F-Gas Regulation compliance secures European market access before refrigerant phase-out deadlines. |
| Predictive Maintenance Contract Unbundling | Brazilian and Chinese processors now benchmark vendors on remote diagnostic capability and spare parts availability. |
| Regional Assembly Partnership Formation | MIIT and BIS local-content mandates require domestic manufacturing presence for public procurement eligibility. |
| Microwave Drying Modular Deployment | Satellite facility architecture reduces wet leaf transport costs and enables just-in-time processing in Indonesia. |
| Vacuum Drying Niche Expansion | Premium cigar processors in Nicaragua and the Dominican Republic absorb price premiums for oxidation-controlled curing. |
Research Methodology
Trade association filings, customs and export records, and equipment registration databases formed the secondary backbone, cross-referenced against primary interviews with plant engineers at contract manufacturing facilities, procurement leads at vertically integrated processors, and aftermarket service heads at regional distributor networks. Bottom-up triangulation across installed base estimates and top-down validation against capital expenditure disclosures ensured methodological robustness.
Historical trendline analysis of equipment replacement cycles and energy efficiency upgrade patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include dryer type, heating technology, automation tier, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized capital intensity trajectories, with specific inputs including natural gas price scenarios and F-Gas implementation pace assumptions.
The model assumes a particular technology adoption path; alternative pathways for microwave drying penetration would alter the outlook if energy recovery integration in conventional thermal systems lags cost-parity thresholds. Forecasts reflect documented assumptions regarding regulatory implementation timelines and commodity price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Cassava Processing Market