
 Sun Protection Products Market | 2026-2036
Sun Protection Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Protection Products Market Outlook
A capital-intensity divergence between integrated chemical producers and brand marketers is rotating competitive advantage toward firms with captive UV-filter supply chains. L'Oréal S.A. leverages its in-house photoprotection research campus in France to sustain patent positions on next-generation organic filters. Beiersdorf AG anchors its portfolio through dermatological testing partnerships that differentiate NIVEA SUN formulations in European pharmacy channels.
Sun protection products encompass topical formulations engineered with organic or inorganic UV filters—such as avobenzone, octocrylene, or zinc oxide dispersed at particle sizes below 100 nanometers—to absorb or scatter ultraviolet radiation in the 290–400 nanometer range, thereby preventing erythema, photoaging, and carcinogenic DNA damage. The primary commercial purpose spans consumer skincare, outdoor occupational safety, and post-procedure dermatological care. Cream and lotion formulations dominate unit volume in mature Western markets where daily facial application habits are entrenched, while spray formats represent the fastest-growing configuration in sports and water-resistant applications due to convenience demands among active outdoor users. Specialty stores and pharmacy chains capture margin-rich premium segments, whereas online retailers are displacing traditional supermarkets in repeat-purchase sunscreen categories through subscription mechanics.
The FDA governs sunscreen active ingredients through its over-the-counter monograph system, while the EU's Cosmetics Regulation and REACH framework impose stricter hazard assessment protocols on nanoscale mineral filters, forcing dual-track formulation strategies for multinational suppliers. Australia's Therapeutic Goods Administration maintains the world's most stringent UVA testing standards through its broad-spectrum labeling mandate, which shapes product development priorities for brands targeting high-UV index geographies. Stakeholders must monitor pending FDA monograph finalization decisions, as these will determine which long-pending UV filter petitions gain market access and reshape competitive formulation portfolios.
Market Dynamics
The FDA's monograph modernization process is forcing manufacturers into dual-track formulation investments, splitting R&D budgets between defending legacy portfolios and advancing next-generation UV filter petitions through prolonged regulatory review cycles.
Growth Catalysts
- UV Index Exposure Patterns:Brazil's coastal urban corridors sustain year-round consumption habits that flatten seasonal revenue volatility for suppliers with established distribution in Rio de Janeiro and São Paulo metropolitan zones.
- REACH Framework Advancements:The EU's stricter hazard assessment protocols on nanoscale mineral filters are accelerating substitution toward organic filter innovation pipelines among European formulators seeking preemptive compliance positions.
- Dermatology Channel Expansion:Professional-grade sunscreen dispensing programs at United States dermatology clinics are creating institutional prescription volumes that bypass retail margin compression.
Market Restraints
- Active Ingredient Supply Concentration:Captive production of avobenzone and octocrylene concentrates among integrated chemical producers in Germany and China limits formulation flexibility for brand marketers without backward integration.
- Regulatory Timeline Friction:Pending FDA monograph finalization decisions have trapped seventeen long-pending UV filter petitions in administrative limbo since 2002, freezing market access for novel photoprotection technologies.
- Mineral Filter Technical Limitations:Zinc oxide particle dispersion below 100 nanometers remains susceptible to photoreactivity degradation under high-UV index conditions, constraining broad-spectrum efficacy claims in Australian TGA testing protocols.
Strategic Opportunities
- Subscription Commerce Penetration:Online retailers are displacing traditional supermarkets in repeat-purchase sunscreen categories through automated replenishment mechanics that capture lifetime value from facial-application daily users.
- Sports Format Innovation:Spray configurations represent underexploited white space in water-resistant applications where convenience demands among active outdoor users command price premiums over cream and lotion equivalents.
- Post-Procedure Dermatological Care:Partnerships with cosmetic surgery clinics and laser treatment centers in South Korea and the United Arab Emirates are opening institutional procurement channels for medical-grade photoprotection with reimbursement-adjacent pricing.
Industry Challenges
- Photoprotection Formulation Expertise Scarcity:The specialized knowledge required for stable avobenzone-octocrylene photostabilization complexes remains concentrated among legacy cosmetic chemists approaching retirement, creating talent pipeline gaps.
- Dual-Track Certification Burden:Manufacturers must simultaneously maintain FDA OTC monograph compliance and EU Cosmetics Regulation dossiers, doubling regulatory affairs headcount requirements without corresponding revenue expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Protection Products Market |
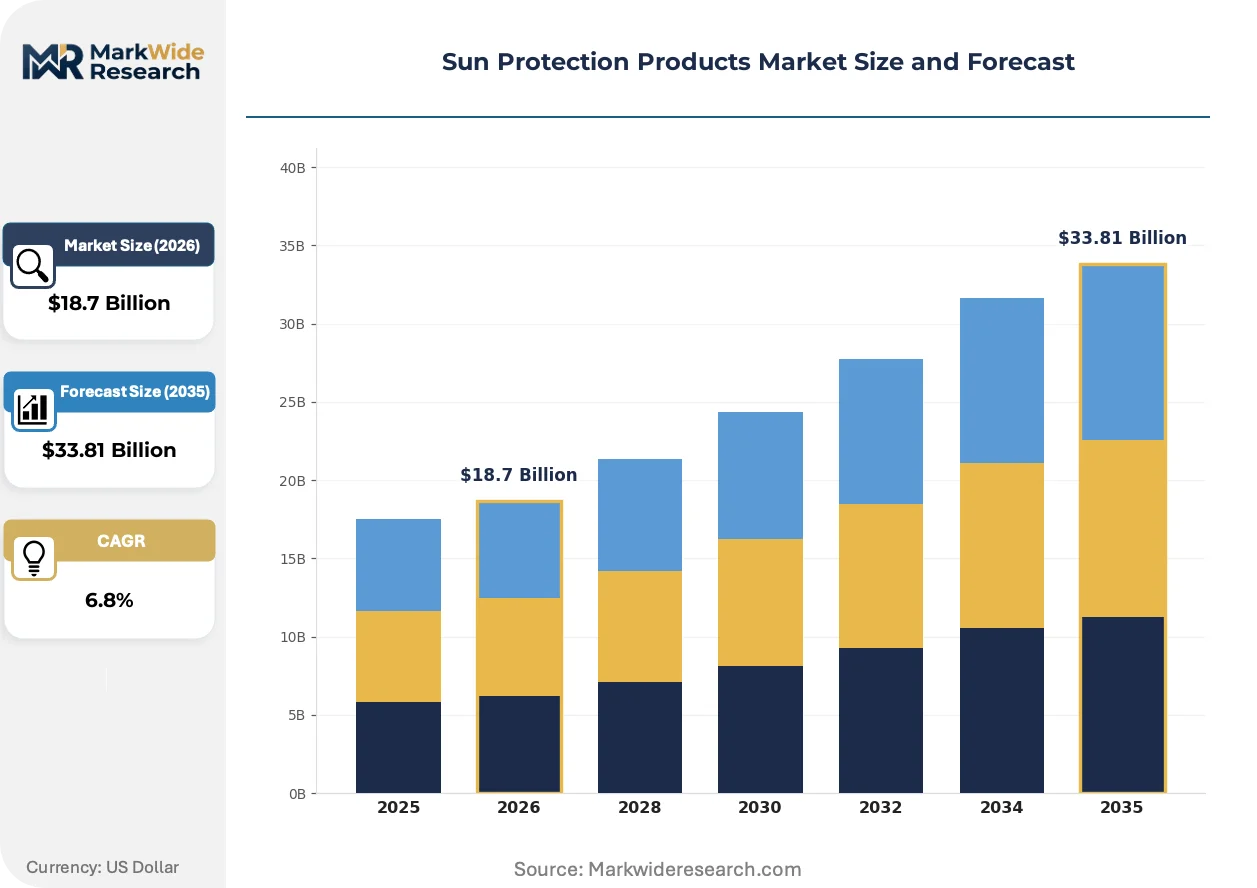
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreen, Sunblock, After-sun Care, Tanning Oils Application: Facial, Body, Sports, Water-resistant Formulation: Gel, Cream, Lotion, Spray Distribution Channel: Online Retailers, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Johnson & Johnson, L'Oréal S.A., Beiersdorf AG, Unilever PLC, Procter & Gamble Company, Shiseido Company, Limited, Edgewell Personal Care, Kao Corporation, The Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Protection Products Market Strategic Shifts
Reformulation pressures are fragmenting competitive advantage away from marketing scale toward captive UV-filter supply chains and in-house photoprotection research capabilities. Three forces are actively restructuring how value is created and captured.
Encapsulated organic UV filter technologies are fragmenting the traditional trade-off between cosmetic elegance and photostability. Microsphere delivery systems that isolate avobenzone from skin contact while maintaining SPF performance are attracting adoption among premium facial skincare brands seeking to bypass mineral filter whitening complaints. This technology is fragmenting R&D resource allocation across the industry, diverting investment from conventional emulsion chemistry toward polymer science competencies.
REACH authorization requirements for nanoscale titanium dioxide are compressing the viable supplier base for mineral-only formulations in European pharmacy channels. ECHA's 2020 classification of certain nanoforms as suspected carcinogens by inhalation has triggered reformulation mandates that favor coated particle variants with enhanced surface stability. German and French formulators are responding by vertically integrating into particle surface modification capabilities previously outsourced to specialty chemical distributors.
Daily facial application habits among urban professionals are displacing seasonal beach-centric purchasing patterns in mature Western markets. Pharmacy chains in France and Switzerland report SPF moisturizer hybrids outselling standalone sunscreen SKUs by unit volume, compressing the addressable market for traditional lotion formats. This behavioral pivot is most visible in metropolitan clusters where dermatologist consultation rates correlate with year-round UV protection adherence.
Sun Protection Products Market Segmentation
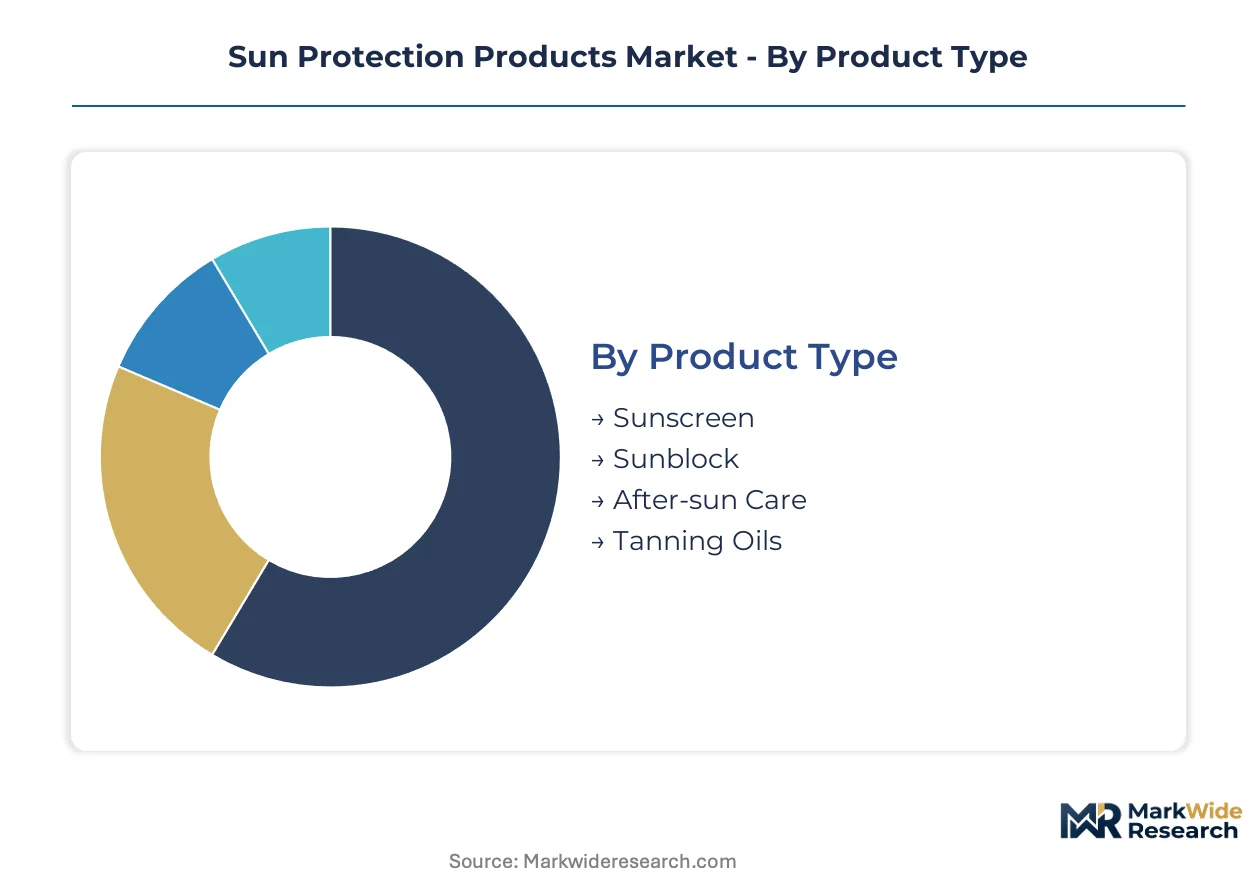
Sun protection products fragment across four distinct category axes that determine formulation chemistry, channel economics, and customer lifetime value. Understanding how these segments intersect reveals where margin concentrates versus where volume scales.
Product Type:
Pharmacy chains and dermatology clinics capture premium pricing on photoprotection products with clinical positioning, while mass retail channels move high-volume SKUs with recreational positioning.
- Sunscreen:Organic and inorganic UV filter formulations engineered for daily photoprotection against UVA and UVB radiation in the 290–400 nanometer range. Demand concentrates in Brazil's coastal urban corridors where year-round UV index exposure flattens seasonal purchasing patterns and sustains consistent replenishment cycles.
- Sunblock:Mineral-dominant formulations utilizing zinc oxide or titanium dioxide dispersed at particle sizes optimized for broad-spectrum scattering. The United States dermatology clinic channel is expanding professional-grade dispensing programs that bypass retail margin compression for this category.
- After-sun Care:Post-exposure formulations with soothing agents targeting erythema reduction and barrier repair.
- Tanning Oils:Low-SPF or SPF-free formulations marketed for accelerated melanin production with minimal photoprotection claims.
Sunscreen dominates installed base. Sunblock is where expansion concentrates.
Application:
Cost tier stratification separates medical-grade facial applications from mass-market body coverage, with sports and water-resistant commanding formulation premiums for polymer film-forming technologies.
- Facial:Lightweight emulsions with cosmetic elegance priorities and non-comedogenic positioning for daily urban professional use. Pharmacy chains in France and Switzerland report SPF moisturizer hybrids in this application climbing the fastest as year-round habits displace seasonal beach-centric purchasing.
- Body:Higher-volume formats with cost-optimized emulsion chemistry for intermittent recreational exposure.
- Sports:Sweat-resistant and friction-stable formulations engineered for elevated physical activity conditions. Demand concentrates among active outdoor users in Australian metropolitan clusters where Therapeutic Goods Administration broad-spectrum mandates shape product development priorities.
- Water-resistant:Film-forming polymer systems maintaining SPF performance through immersion and towel-drying cycles.
Facial applications dominate installed base. Sports is where expansion concentrates.
Formulation:
Volume concentration favors cream and lotion emulsions in mature Western markets, while spray configurations exploit convenience premiums in active-use segments with higher replenishment frequency.
- Gel:Alcohol-based or aqueous systems with rapid dry-down characteristics for oily skin types and tropical climates.
- Cream:Oil-in-water emulsions with rich sensorial profiles dominating unit volume in European pharmacy channels where daily facial application habits are entrenched.
- Lotion:Lower-viscosity emulsions optimized for body coverage efficiency and pump-dispenser compatibility.
- Spray:Aerosol or mechanical pump configurations representing the steepest expansion trajectory in water-resistant applications where convenience demands among active outdoor users command price premiums over cream and lotion equivalents.
Cream dominates installed base. Spray is where expansion concentrates.
Distribution Channel:
Margin structure inverts between high-touch pharmacy channels with clinical credibility and automated online replenishment capturing lifetime value from habitual daily users.
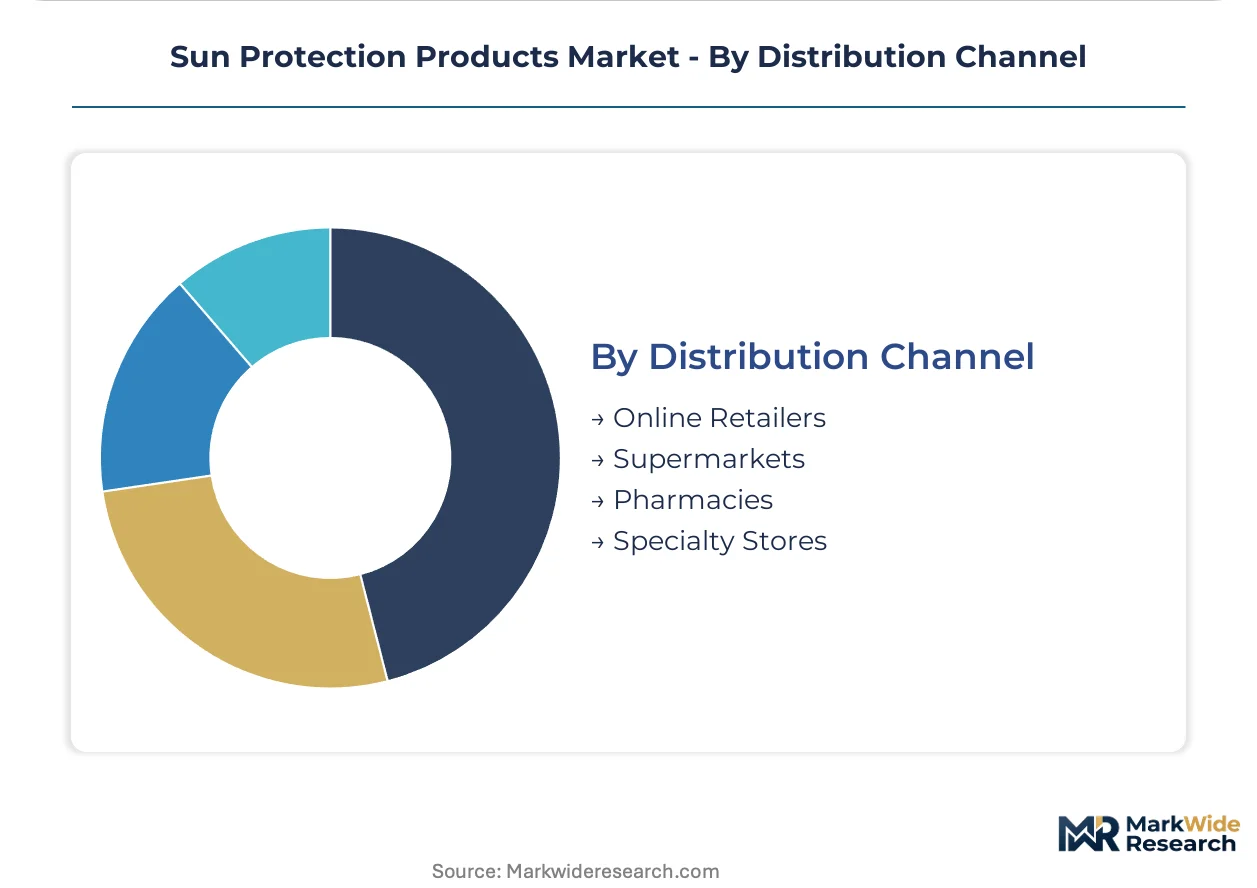
- Online Retailers:E-commerce platforms with subscription mechanics displacing traditional supermarkets in repeat-purchase categories. Automated replenishment captures lifetime value from facial-application daily users in metropolitan France and Switzerland.
- Supermarkets:High-velocity mass retail with promotional-driven purchasing concentrated in seasonal peaks.
- Pharmacies:Professional consultation environments capturing margin-rich premium segments through dermatological testing partnerships and clinical credibility positioning in European markets.
- Specialty Stores:Beauty-focused retail with experiential merchandising and premium brand curation.
Pharmacies dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Switzerland and Australia where pharmacy channel premiums and regulatory stringency sustain margin structures unavailable in mass-market economies. Brazil's coastal corridors command volume premiums through year-round UV exposure patterns. Germany anchors European formulation innovation through integrated chemical production clusters.
United States
Dermatology clinic dispensing programs and sports-format convenience demands drive institutional procurement growth. FDA monograph modernization traps novel UV filter petitions in administrative review since 2002, freezing market access for next-generation technologies. Miami and Los Angeles metropolitan clusters concentrate professional-grade sunscreen distribution through medical spa and cosmetic surgery channels.
Brazil
Year-round UV index exposure in Rio de Janeiro and São Paulo coastal zones flattens seasonal revenue volatility for established suppliers. ANVISA maintains alignment with international photoprotection standards while permitting faster novel ingredient approval pathways than FDA timelines. The Southeast region concentrates consumption volume through urban professional daily-application habits displacing beach-centric purchasing.
Germany
Integrated chemical producers with captive avobenzone and octocrylene supply chains rotate competitive advantage toward backward-integrated formulators. ECHA REACH protocols on nanoscale mineral filters accelerate substitution toward organic filter innovation pipelines. The Rhine-Ruhr industrial corridor anchors UV filter production concentration with particle surface modification capabilities expanding among domestic formulators.
Australia
Therapeutic Goods Administration broad-spectrum labeling mandates shape product development priorities for brands targeting high-UV index geographies. Stringent UVA testing standards exceed FDA and EU baseline requirements, creating compliance premiums for certified formulations. Sydney and Melbourne metropolitan clusters concentrate pharmacy channel distribution where clinical credibility commands price differentiation over supermarket alternatives.
Switzerland
Pharmacy chains in Geneva and Zurich report SPF moisturizer hybrids outselling standalone sunscreen SKUs by unit volume through entrenched daily facial application habits. Swissmedic maintains alignment with EU Cosmetics Regulation while permitting faster market access for innovative encapsulated filter technologies. The Romandy region concentrates premium segment distribution through dermatological testing partnerships and medical-grade positioning.
Sun Protection Products Market Competitive Environment
Concentration sits with integrated personal care conglomerates possessing captive R&D infrastructure and established pharmacy channel relationships. Market structure tilts toward tiered competition where patent-protected organic filter portfolios command premium positioning against commodity mineral formulations. Three archetypes dominate: multinational beauty conglomerates with in-house photoprotection research campuses, dermatology-focused specialists leveraging clinical testing partnerships, and mass-market brand marketers dependent on outsourced UV filter supply. Competitive moves concentrate on M&A to secure formulation expertise and strategic partnerships with dermatology clinic networks to bypass retail margin compression.
Within the multinational conglomerate tier, L'Oréal S.A. and Beiersdorf AG occupy positions defined by captive research infrastructure and European pharmacy channel dominance. L'Oréal S.A. exemplifies the integrated innovation archetype through its France-based photoprotection research campus sustaining patent positions on next-generation organic filters. Beiersdorf AG anchors the dermatological credibility vector through testing partnerships that differentiate NIVEA SUN formulations in pharmacy channels. Johnson & Johnson represents the institutional dispensing archetype through professional-grade sunscreen programs at United States dermatology clinics. Shiseido Company, Limited and Kao Corporation occupy positions within the Asia-Pacific innovation corridor, though their strategic emphasis diverges between premium facial skincare integration and mass-market format expansion.
| Leading Market Players |
|---|
| Johnson & Johnson |
| L'Oréal S.A. |
| Beiersdorf AG |
| Unilever PLC |
| Procter & Gamble Company |
| Shiseido Company, Limited |
| Edgewell Personal Care |
| Kao Corporation |
| The Estée Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Organic UV filter substitution for nanoscale mineral alternatives is redrawing procurement geography and compressing formulation economics across European pharmacy channels. REACH authorization requirements for titanium dioxide nanoforms have triggered supplier consolidation in Germany and France, while accelerating R&D reallocation toward patented organic filter portfolios that command premium positioning.
Pricing Analysis
The customization-premium spread between standard mineral formulations and encapsulated organic filter systems now exceeds three-to-one in Swiss and Australian pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and dermatological testing depth, with TGA broad-spectrum certified SKUs capturing the widest spreads. Pricing pressure stems from supermarket channel compression as online subscription mechanics erode seasonal promotional volumes. Mass-market body formulations exhibit highest price sensitivity, while post-procedure dermatological SKUs show inelastic demand.
Supply Chain Analysis
Inventory lead times for avobenzone and octocrylene concentrates have extended as backward-integrated German and Chinese chemical producers prioritize captive formulator relationships. Supply geography centers on the Rhine-Ruhr corridor for organic filter synthesis and Australia's mineral refinement hubs for zinc oxide processing. Raw material dependencies include petroleum-derived octocrylene feedstocks, surface-modified zinc oxide particles, and polymer encapsulation resins. Single-source vulnerability concentrates in avobenzone photostabilization complex production. Distribution runs through pharmacy chains for premium facial SKUs and automated e-commerce replenishment for daily-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sun protection products are approaching a platform-economics inflection where subscription infrastructure and dermatology clinic dispensing networks create two-sided marketplace dynamics between habitual users and institutional prescribers.
For Market Incumbents: Secure captive UV-filter supply chains through upstream partnerships or in-house production investments before REACH authorization timelines further constrain mineral filter sourcing. Deepen dermatology clinic dispensing relationships to insulate margin from supermarket channel erosion. Prioritize polymer science R&D capabilities for encapsulated filter differentiation as legacy emulsion chemists retire. For New Entrants and Emerging Players: Anchor in sports-format spray configurations where convenience premiums and water-resistant polymer film-forming technologies remain underexploited white space. Target Australian metropolitan clusters where TGA broad-spectrum mandates create compliance barriers for established mass-market brands. Pursue direct-to-consumer subscription mechanics with automated replenishment to capture lifetime value from facial-application daily users. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulators with backward-integrated organic filter production and established European pharmacy channel relationships. Long-term viability hinges on patent-protected filter portfolios that withstand FDA monograph modernization uncertainty. Watch for FDA finalization decisions on seventeen pending UV filter petitions as the inflection signal determining competitive formulation access.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Filter Technology Licensing | Polymer science partnerships bypass mineral filter whitening complaints in premium facial segments. |
| Dermatology Clinic Network Partnership | Institutional dispensing programs capture reimbursement-adjacent pricing outside retail margin compression. |
| Subscription Commerce Infrastructure | Automated replenishment mechanics capture lifetime value from habitual daily facial application users. |
| Backward Integration into Organic Filter Synthesis | Captive avobenzone-octocrylene supply insulates against German and Chinese producer concentration. |
| Sports Format Spray Expansion | Water-resistant polymer film-forming configurations command convenience premiums in active-use segments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cosmetic chemists, regulatory affairs directors, pharmacy chain category managers, and dermatology clinic procurement officers; and secondary validation against FDA monograph filings, ECHA REACH authorization databases, ANVISA ingredient approval records, and customs trade data for UV filter raw material flows. Bottom-up triangulation across formulation chemistry inputs and top-down reconciliation against channel shipment patterns anchored volume estimates.
Across the analysis window, forecasts model product type, application, formulation, and distribution channel segmentation with regional regulatory cluster overlays. CAGRs derive from trend extrapolation of daily facial application habit formation, sports format adoption curves, and subscription commerce penetration rates. Industry-specific inputs include UV index exposure pattern data for Brazilian coastal corridors and TGA broad-spectrum certification timelines for Australian market access.
Decision-makers should treat outputs as directional under assumptions of FDA monograph finalization within standard administrative windows and no catastrophic supply disruption in organic filter precursor chemicals; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market