
 Arbutin for Cosmetics Market | 2026-2036
Arbutin for Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Arbutin for Cosmetics Market Insights
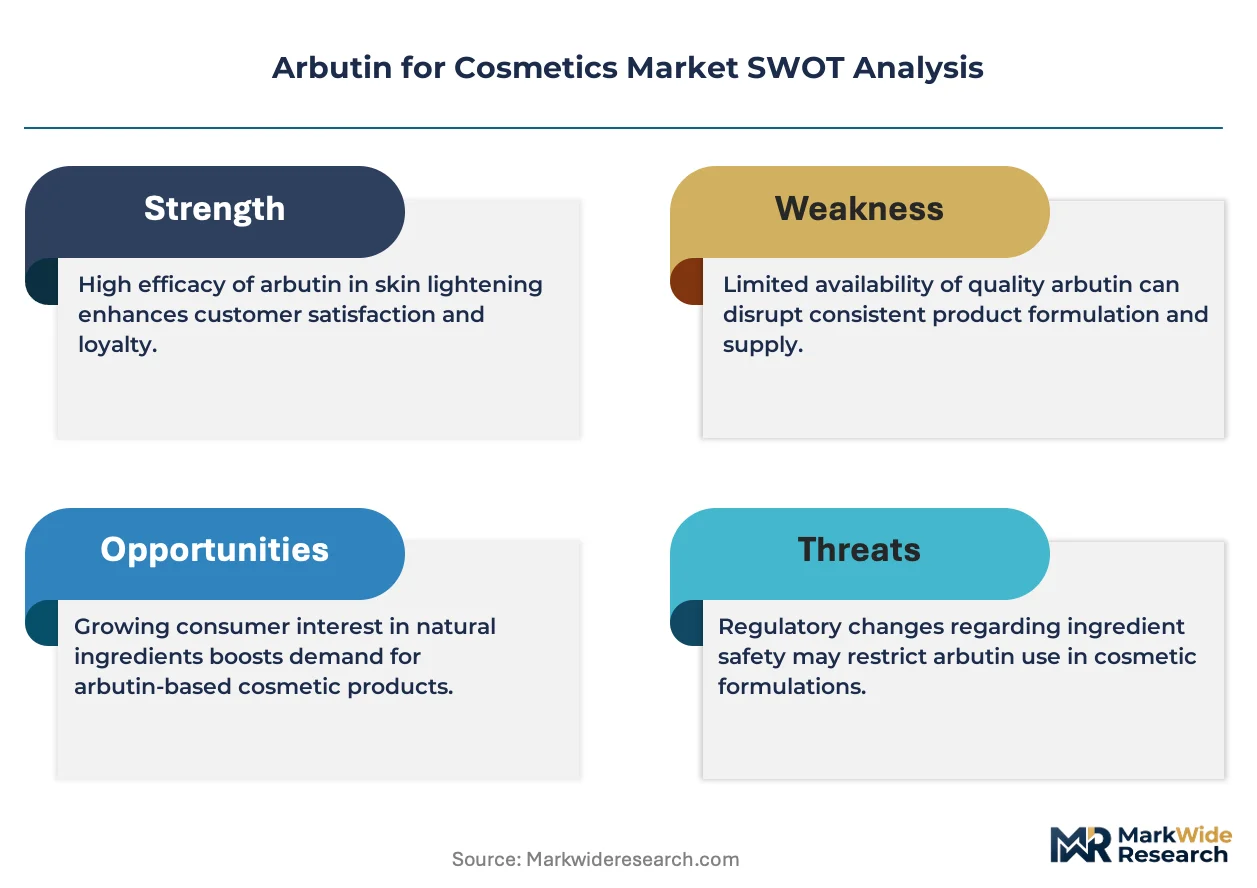
Prestige skincare is decoupling from mass-market whitening as dermatological clinics and professional channels command premium positioning for arbutin-based treatments. Symrise AG leverages its botanical extraction heritage to anchor supply security for natural-derived grades. BASF competes through synthetic process efficiency and scale economies in alpha arbutin production. Evonik differentiates via specialty delivery system integration that enhances dermal penetration profiles.
Arbutin is a hydroquinone glycoside, either biosynthesized from bearberry leaf extract or manufactured through acetobromglucose condensation, functioning primarily as a tyrosinase inhibitor that suppresses melanin formation in cosmetic applications. Synthetic arbutin dominates volume throughput due to cost parity and batch consistency, while alpha arbutin captures expanding margin pools as formulators prioritize stability and lower irritation potential over legacy beta-arbutin grades. Serum formulations lead value concentration given higher active loading and consumer willingness to pay for concentrated delivery systems.
Europe's REACH framework and the EU Cosmetics Regulation enforce stringent purity and safety dossier requirements that filter substandard suppliers from market access. China's NMPA and SAMR impose parallel registration and labeling standards that shape export competitiveness for foreign manufacturers. South Korea's MFDS maintains rigorous whitening functional cosmetic approvals that elevate compliance costs but reinforce quality premiums. Stakeholders must monitor evolving regulatory divergence between major cosmetic markets to optimize formulation and registration strategies.
Market Dynamics
The Arbutin for Cosmetics Market is undergoing structural recalibration as dermatological channels displace mass retail for high-purity active distribution, forcing suppliers to reconfigure certification and logistics capabilities around clinic-grade specifications.
Growth Catalysts
- MFDS whitening functional approvals:South Korea's stringent cosmetic registration pathway elevates quality premiums and filters low-grade competitors from professional channels.
- Tyrosinase inhibitor biosynthesis:Enzymatic production methods reduce residual hydroquinone content below detectable thresholds, satisfying ECHA purity dossier requirements.
- K-beauty export pipeline:Seoul-based formulators are scaling arbutin-loaded serum production for Southeast Asian and Middle Eastern distribution networks.
Market Restraints
- Synthetic precursor cost volatility:Acetobromglucose feedstock prices fluctuate with pharmaceutical sector demand, compressing alpha arbutin margins.
- REACH dossier concentration:ECHA registration costs and toxicology study requirements favor incumbent suppliers with existing substance volumes.
- Hydroquinone substitution pressure:Kojic acid and tranexamic acid alternatives capture price-sensitive segments in mass-market whitening.
Strategic Opportunities
- Saudi aesthetic clinic expansion:MOHAP cosmetic procedure licensing growth creates demand for professional-grade melanin inhibitors in Gulf Cooperation Council markets.
- Encapsulation-delivery convergence:Liposome and niosome technologies enable time-release arbutin formulations with enhanced epidermal penetration profiles.
- SAMR cross-border e-commerce:China's pilot programs for imported functional cosmetics streamline registration for foreign arbutin serum brands.
Industry Challenges
- Analytical method standardization:Inconsistent alpha/beta arbutin ratio testing protocols across ISO, JIS, and GB reference materials create batch release disputes.
- Cold chain integrity:Temperature excursions during serum distribution degrade active stability, requiring validated logistics investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arbutin for Cosmetics Market |
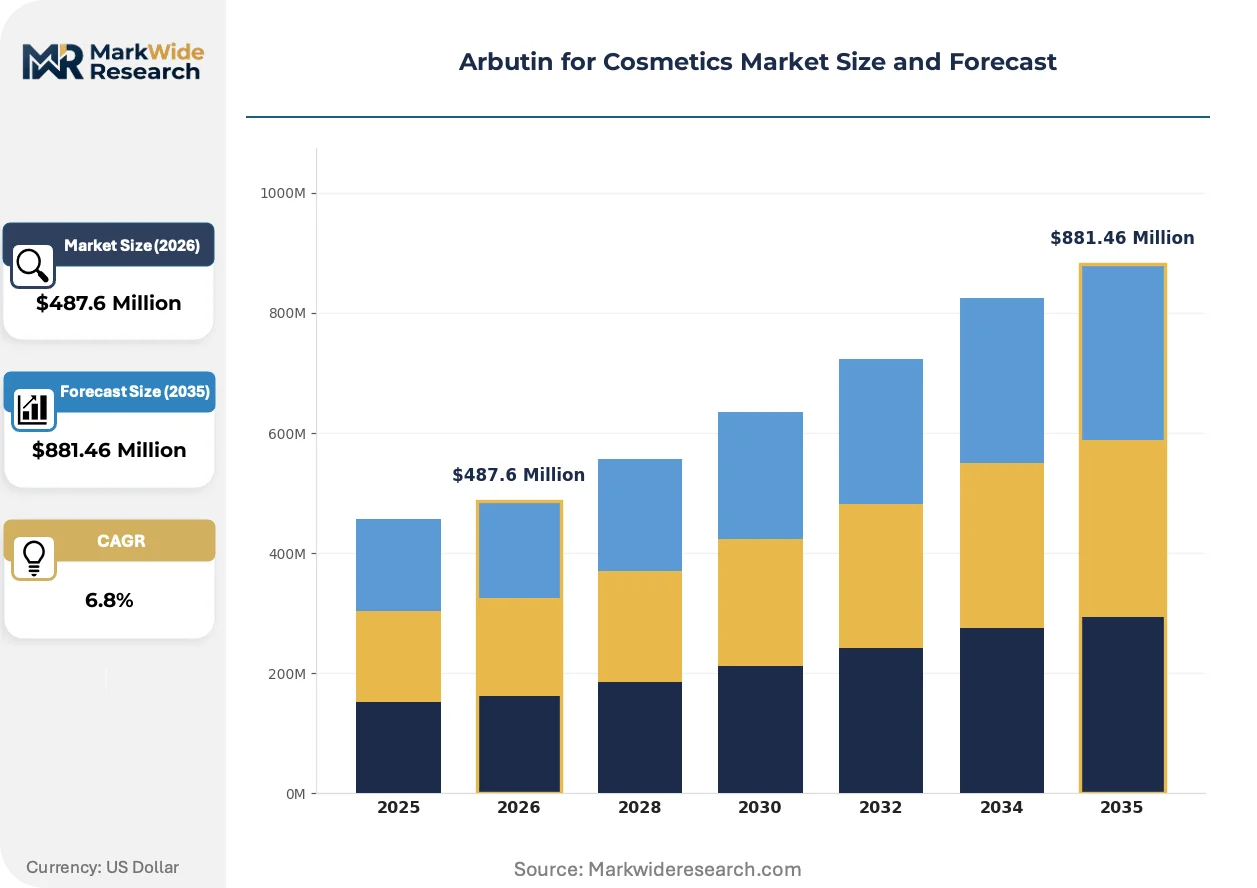
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Arbutin, Natural Arbutin, Alpha Arbutin, Beta Arbutin Application: Skin Whitening, Anti-Aging, Sun Protection, Moisturizing Formulation Type: Serums, Creams, Lotions, Masks End User: Skincare Brands, Cosmetic Manufacturers, Retail Consumers, Dermatological Clinics |
| Companies Covered | Symrise AG, Ashland Global Holdings Inc., BASF, Lonza, Evonik, Dow, Plamed Green Science, Hefei TNJ Chemical Industry, KRAEBER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arbutin for Cosmetics Market Trends and Innovations
Formulation science and channel economics are reshaping how arbutin reaches end-users, with biotechnology and regulatory compliance emerging as the primary axes of competitive differentiation.
Biofermentation-derived arbutin is converging with precision extraction protocols to yield stereochemically pure alpha isomers. Premium dermatological brands in Seoul and Tokyo are adopting these grades for post-procedure hyperpigmentation protocols. This convergence is compressing the viability window for legacy beta-arbutin suppliers dependent on bearberry leaf sourcing.
REACH authorization requirements for hydroquinone precursors are tightening substance volume thresholds and extended safety data mandates. European formulators must now document full supply chain contamination controls from synthesis to finished goods. Small-scale serum manufacturers without captive synthesis capabilities face registration cost barriers that favor integrated producers.
Clinic-direct procurement models are displacing traditional distributor networks for high-concentration arbutin treatments. Seoul's Gangnam and Apgujeong aesthetic clusters now source actives through manufacturer-affiliated technical service representatives rather than wholesale beauty suppliers. This pattern is replicating in Dubai's Jumeirah medical district and Bangkok's Sukhumvit clinic corridor.
Arbutin for Cosmetics Market Segmentation
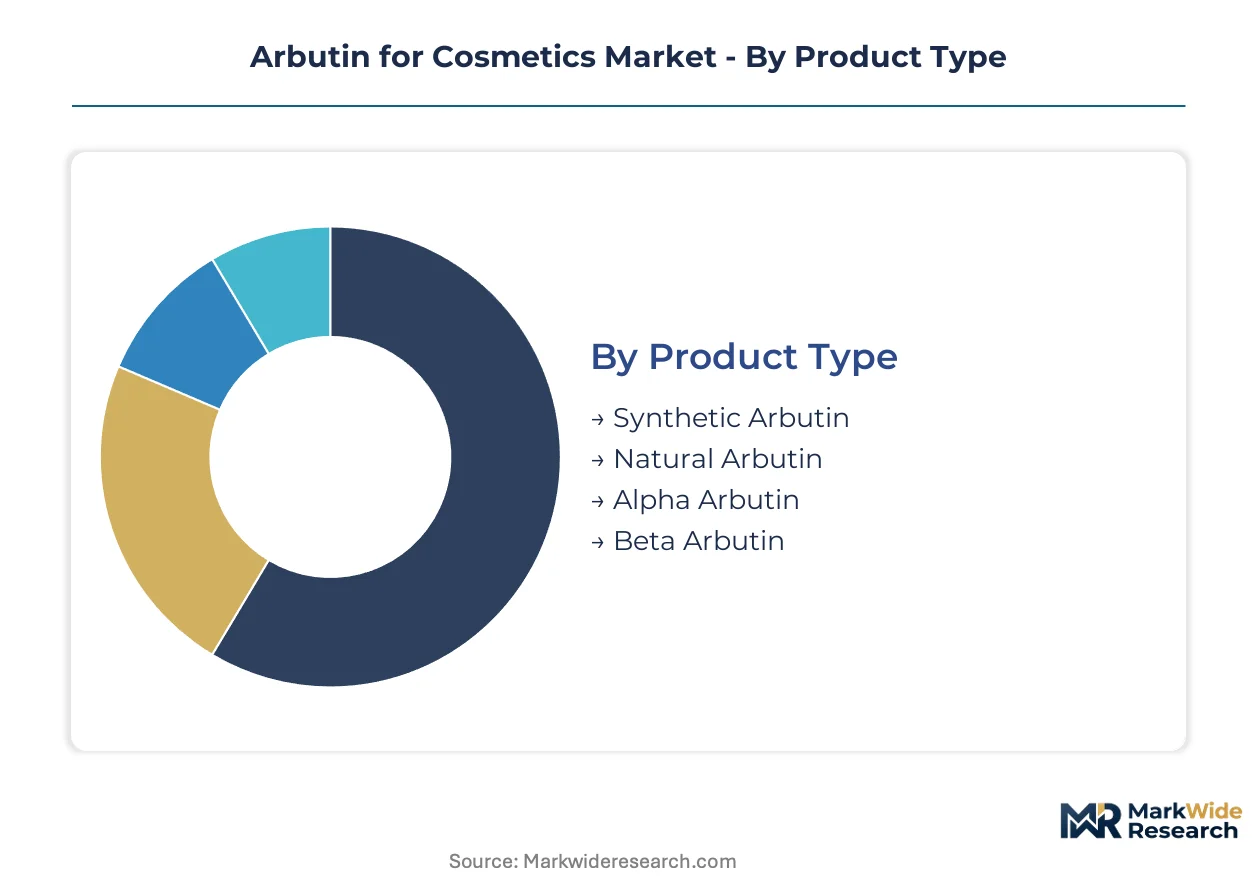
Arbutin segmentation reflects divergent purity standards and channel economics across cosmetic applications. Formulators select grades based on regulatory dossier requirements, stability profiles, and end-user price elasticity.
Product Type:
Integration depth varies sharply: alpha and synthetic grades anchor standalone professional treatments, while natural and beta forms embed in mass-market formulations.
- Alpha Arbutin:Stereochemically pure isomer synthesized through enzymatic glycosylation delivers superior tyrosinase inhibition with minimal hydroquinone residue. Seoul's Gangnam dermatological cluster specifies this grade for post-laser hyperpigmentation protocols, with MFDS functional cosmetic approvals reinforcing premium positioning over legacy alternatives.
- Synthetic Arbutin:Manufactured via acetobromglucose condensation with pharmaceutical-grade batch consistency dominates volume throughput. Guangdong and Zhejiang cosmetic OEMs source this grade for cost-competitive serum exports to Southeast Asian e-commerce channels, though acetobromglucose feedstock volatility compresses margin stability.
- Natural Arbutin:Bearberry leaf extraction preserves botanical marketing claims for clean beauty positioning in European prestige channels.
- Beta Arbutin:Legacy glycoside form faces substitution pressure as formulators migrate toward alpha isomer stability profiles.
Volume placements concentrate in synthetic arbutin; the faster expansion belongs to alpha arbutin.
Application:
Cost tier stratification separates clinic-grade hyperpigmentation protocols from accessible daily-use positioning.
- Skin Whitening:Tyrosinase inhibition for melanin suppression commands the highest active loading concentrations and regulatory scrutiny. South Korea's MFDS whitening functional category and China's NMPA registration pathway filter competitors, creating margin premiums for dossier-compliant suppliers serving Gangnam and Shanghai clinic networks.
- Anti-Aging:Antioxidant and collagen-support claims in arbutin formulations target premium serum positioning for mature skin demographics. Tokyo's Aoyama aesthetic retailers and Dubai's Jumeirah medical district source these combinations for combination therapy protocols alongside retinoids and peptides.
- Sun Protection:Melanin suppression complements UV filter actives in preventive formulations for Southeast Asian tropical climates.
- Moisturizing:Lower-concentration inclusion supports hydration marketing in mass-market K-beauty sheet mask exports.
Skin whitening captures the steepest margin tiers; anti-aging is climbing the fastest as aging demographics expand clinic visitation.
Formulation Type:
Customer type alignment distinguishes professional-channel concentrates from retail-accessible delivery formats.
- Serums:High active loading in aqueous or hydrogel bases enables precise dosing for dermatological protocols. Bangkok's Sukhumvit clinic corridor and Riyadh's MOHAP-licensed aesthetic centers specify manufacturer-direct serum procurement with validated cold chain documentation, displacing traditional wholesale distribution.
- Creams:Emulsion-based delivery suits daily-use whitening regimens in China's Tmall and Douyin cross-border e-commerce channels.
- Lotions:Lower viscosity formats target body care applications in humid climate markets.
- Masks:Single-use sheet and wash-off formats dominate K-beauty export volume to Southeast Asian convenience retail.
Serums dominate value concentration; masks lead unit volume through export pipeline scale.
End User:
Supply concentration bifurcates between integrated cosmetic manufacturers and specialized clinic procurement networks.
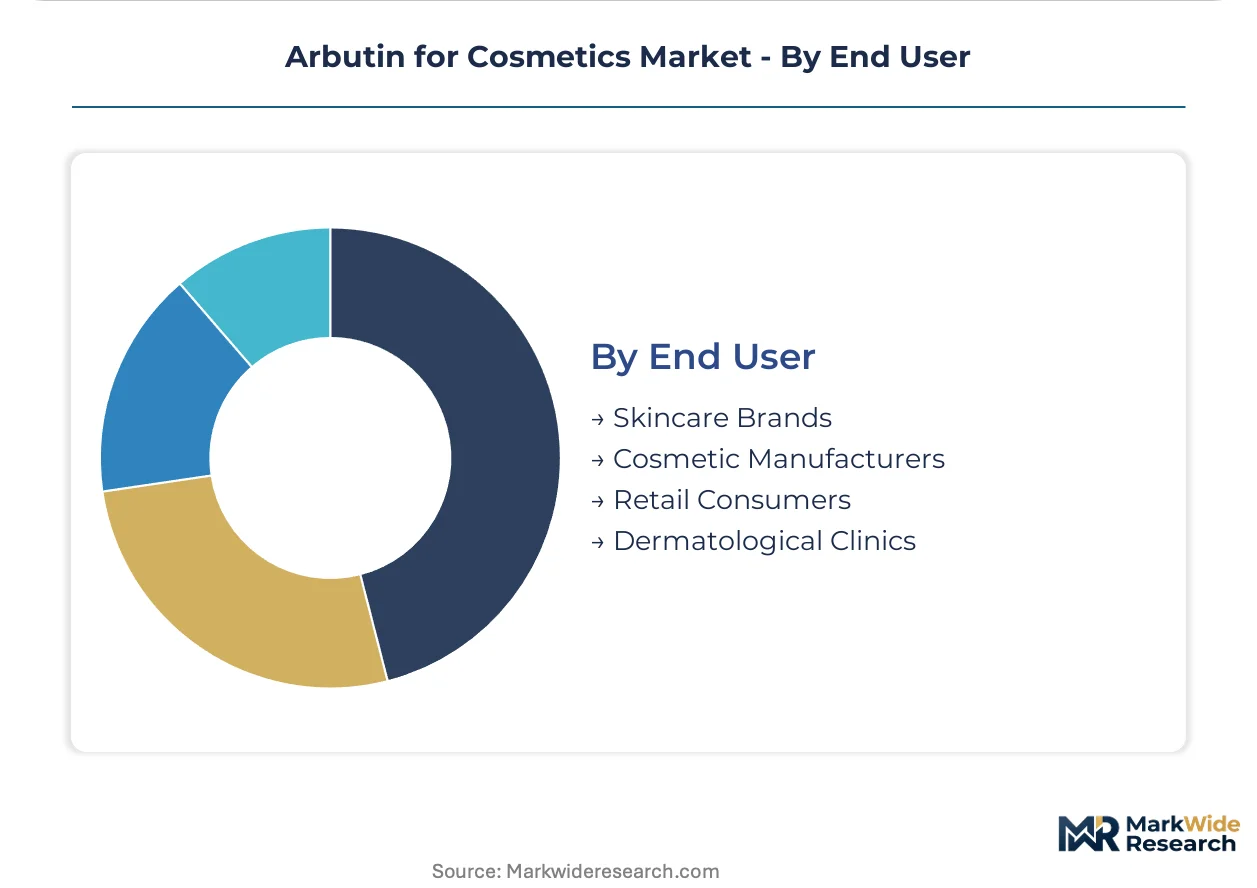
- Dermatological Clinics:Professional-channel purchasers specify certificate-of-analysis documentation, cold chain validation, and technical service support for high-concentration arbutin treatments. Dubai's Jumeirah medical district and Seoul's Apgujeong cluster source through manufacturer-affiliated representatives rather than distributors, compressing margin capture for intermediaries.
- Skincare Brands:Prestige and masstige formulators balance alpha arbutin stability claims against synthetic grade cost parity for competitive positioning in Sephora and Douglas retail networks.
- Cosmetic Manufacturers:Contract OEMs in Guangdong and Incheon Free Economic Zone aggregate volume demand for private-label serum production.
- Retail Consumers:Direct-to-consumer channels through Xiaohongshu and Shopee drive mask and lotion volume with price-sensitive grade tolerance.
Dermatological clinics command the highest purity premiums; skincare brands represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic arbutin production concentrates in China's chemical manufacturing zones, while consumption gravitates toward South Korea's dermatological channels and premium skincare export pipelines. This geographic split shapes trade flows, regulatory compliance investments, and cold chain logistics requirements across the value chain.
South Korea
Gangnam and Apgujeong aesthetic clusters drive demand for MFDS-approved whitening functional cosmetics with alpha arbutin loading above industry norms. Seoul-based formulators maintain direct procurement relationships with enzymatic synthesis specialists, bypassing traditional wholesale intermediaries. K-beauty export pipelines extend these formulations to Southeast Asian and Middle Eastern clinic networks through validated cold chain documentation.
China
Guangdong and Zhejiang cosmetic OEMs aggregate synthetic arbutin volume for private-label serum production targeting cross-border e-commerce channels. NMPA and SAMR registration requirements for imported functional cosmetics filter competitor entry, creating compliance premiums for dossier-complete suppliers. Shanghai's Pudong and Yangpu districts host technical service operations supporting foreign brand localization.
Germany
REACH dossier concentration and ECHA substance volume thresholds favor incumbent suppliers with existing hydroquinone precursor registrations. BASF's Ludwigshafen operations anchor European synthetic production scale, while specialty distributors serve clinic-grade demand from Düsseldorf's aesthetic medicine corridor. German formulators prioritize alpha isomer stability profiles for post-procedure hyperpigmentation protocols.
United States
FDA cosmetic ingredient oversight and state-level professional licensing shape distribution pathways for high-concentration arbutin treatments. California's Los Angeles and San Francisco aesthetic clusters source through manufacturer-direct technical service models. Prestige skincare brands balance stability claims against cost parity for Sephora and Ulta Beauty retail positioning.
United Arab Emirates
MOHAP cosmetic procedure licensing growth in Dubai's Jumeirah medical district creates demand for professional-grade melanin inhibitors. Riyadh-based clinic networks replicate Seoul's direct procurement patterns, compressing distributor margins. Gulf Cooperation Council markets import validated cold chain shipments from South Korean and European synthesis operations.
Arbutin for Cosmetics Market Competitive Landscape
Top-tier vendors anchor integrated synthesis and formulation capabilities, while mid-scale specialists concentrate on regional distribution and technical service differentiation. The supplier base stratifies between pharmaceutical-grade batch consistency providers and botanical extraction heritage firms serving clean beauty positioning. Strategic archetypes include enzymatic synthesis specialists, precision extraction operators, and delivery system integrators. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as firms secure MFDS and NMPA registration pathways.
Among European chemical conglomerates, Symrise AG exemplifies botanical extraction heritage positioning, while BASF occupies the scale-driven synthetic production tier. Evonik represents the specialty delivery system integration archetype. These three firms anchor distinct competitive vectors: natural-derived supply security, process efficiency at volume, and enhanced dermal penetration technologies respectively.
| Leading Market Players |
|---|
| Symrise AG |
| Ashland Global Holdings Inc. |
| BASF |
| Lonza |
| Evonik |
| Dow |
| Plamed Green Science |
| Hefei TNJ Chemical Industry |
| KRAEBER |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Guangdong and Zhejiang provinces anchor synthetic arbutin production, linking upstream acetobromglucose procurement discipline to downstream pricing power over Southeast Asian OEMs. Their concentrated ownership structures enable rapid feedstock cost pass-through to serum manufacturers while resisting margin compression from Korean clinic-direct buyers.
Pricing Analysis
Margin tightening in alpha arbutin reflects enzymatic synthesis capacity scarcity and MFDS registration cost recovery requirements. Three-tier pricing structure across MFDS-certified premium, industrial-grade standard, and unregistered economy levels separates Gangnam clinic procurement from Guangdong OEM volume. Price differentiation hinges on hydroquinone residual thresholds and cold chain documentation depth. Cost-down pressure on synthetic grades accelerates because acetobromglucose pharmaceutical demand diverts feedstock supply. Mass-market K-beauty exporters exhibit highest price sensitivity; Seoul dermatological clinics tolerate premium positioning for alpha isomer stability.
Supply Chain Analysis
Regional distribution centers in Busan and Shanghai coordinate hub-and-spoke patterns for temperature-validated serum shipments to Dubai and Bangkok clinic corridors. Manufacturing concentrates in China, South Korea, and Germany, with enzymatic synthesis specialists clustering near Seoul's Gangnam district. Feedstock supply draws from acetobromglucose producers, bearberry leaf extractors in Alpine regions, and biofermentation substrate suppliers. Single-source vulnerability pervades alpha arbutin enzymatic capacity, where Seoul-based specialists control stereochemical purity yields. Distribution runs through manufacturer-affiliated technical service representatives displacing wholesale intermediaries for clinic-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbutin suppliers face a vertical-integration race, with backward control over enzymatic synthesis capacity emerging as the decisive lever for margin defense against hydroquinone-free biosynthesis entrants.
For Market Incumbents: Deepen captive enzymatic synthesis capabilities to secure alpha isomer supply security against biofermentation disruptors. Expand cold chain-validated logistics infrastructure in Riyadh and Bangkok clinic corridors to defend distributor-displacement patterns. Prioritize MFDS and NMPA registration maintenance as regulatory moats against unregistered economy-grade competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in Southeast Asian e-commerce channels enables private-label serum positioning below Seoul clinic-direct premiums. Target Guangdong OEM aggregation demand with synthetic-grade volume plays. Pursue SAMR cross-border pilot program eligibility as streamlined market entry mechanism. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic specialists with stranded alpha arbutin capacity and incomplete REACH dossiers. Long-term viability centers on biofermentation convergence with precision extraction protocols. Watch MFDS whitening functional approval backlogs as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzymatic Synthesis | Captive alpha isomer production secures margin pools against acetobromglucose volatility. |
| Cold Chain Logistics Expansion | Validated temperature-controlled distribution enables clinic-direct procurement in Gulf Cooperation Council markets. |
| MFDS Functional Cosmetic Registration | Whitening category approval unlocks premium positioning in Seoul's Gangnam aesthetic cluster. |
| Biofermentation Capacity Buildout | Precision-derived arbutin yields stereochemical purity for post-procedure hyperpigmentation protocols. |
| Cross-Border E-Commerce Licensing | SAMR pilot program participation streamlines serum entry into China's Tmall and Douyin channels. |
Research Methodology
Document review covered ECHA substance volume registrations, MFDS whitening functional approvals, and NMPA cross-border e-commerce regulations, complemented by interviews with cosmetic OEM procurement managers, dermatological clinic technical buyers, enzymatic synthesis R&D directors, and cold chain logistics operators. Secondary sources included customs trade data, REACH dossier filings, and K-beauty export pipeline manifests. Bottom-up volume aggregation across alpha and synthetic grade tiers triangulated against top-down market sizing from synthesis capacity assessments.
Segment-level outputs across product type, application, formulation format, and end-user channel were generated through demand-side modeling and supply-side capacity reconciliation. CAGRs were derived from enrollment trajectories in functional cosmetic registrations and clinic procurement volume trends. Forecast inputs incorporated acetobromglucose feedstock price elasticity and enzymatic synthesis yield improvement curves.
Inputs from ECHA, MFDS, and SAMR regulatory databases were available through the study window; gaps in real-time clinic procurement pricing introduce uncertainty bands around premium-tier assumptions. Forecasts reflect documented enrollment and capacity assumptions. Substitution risk from tranexamic acid and kojic acid alternatives, plus REACH authorization tightening for hydroquinone precursors, could revise trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Emollients Market