
 Sodium Methylparaben Market | 2026-2036
Sodium Methylparaben Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Methylparaben Market Analysis
Asset-light toll manufacturing and third-party leasing of GMP-certified production suites is fragmenting competitive dynamics among sodium methylparaben suppliers. Merck KGaA leverages its pharmaceutical-grade certification infrastructure to sustain premium positioning in European supply chains. BASF SE anchors volume availability through backward integration into para-hydroxybenzoic acid feedstock. Zhejiang Shengxiao Chemical competes on cost-optimized powder grades for Asian personal care contract manufacturers.
Sodium methylparaben is the sodium salt of methylparaben, typically supplied as a white crystalline powder with solubility exceeding 100 g/L in water at 25°C, functioning as a broad-spectrum antimicrobial preservative against Gram-positive bacteria and molds in aqueous formulations. Cosmetics and personal care applications dominate current offtake, with skincare formulations representing the deepest margin pool due to sensitivity-grade purity requirements. Pharmaceutical-grade powder commands pricing premiums over standard technical grades, while food processing applications face structural headwinds from clean-label substitution pressures. Liquid emulsion forms are gaining share in automated manufacturing lines despite higher logistics costs.
FDA oversight of cosmetic preservatives under the Modernization of Cosmetics Regulation Act intersects with EPA chemical substance reviews to shape permissible exposure thresholds and labeling obligations for US-market products. ECHA REACH restrictions on paraben concentrations in leave-on cosmetics directly constrain formulation flexibility for European personal care brands. Stakeholders must monitor evolving preservative approval pathways in China under NMPA cosmetic safety technical specifications as domestic brands seek export parity with Western regulatory standards.
Market Dynamics
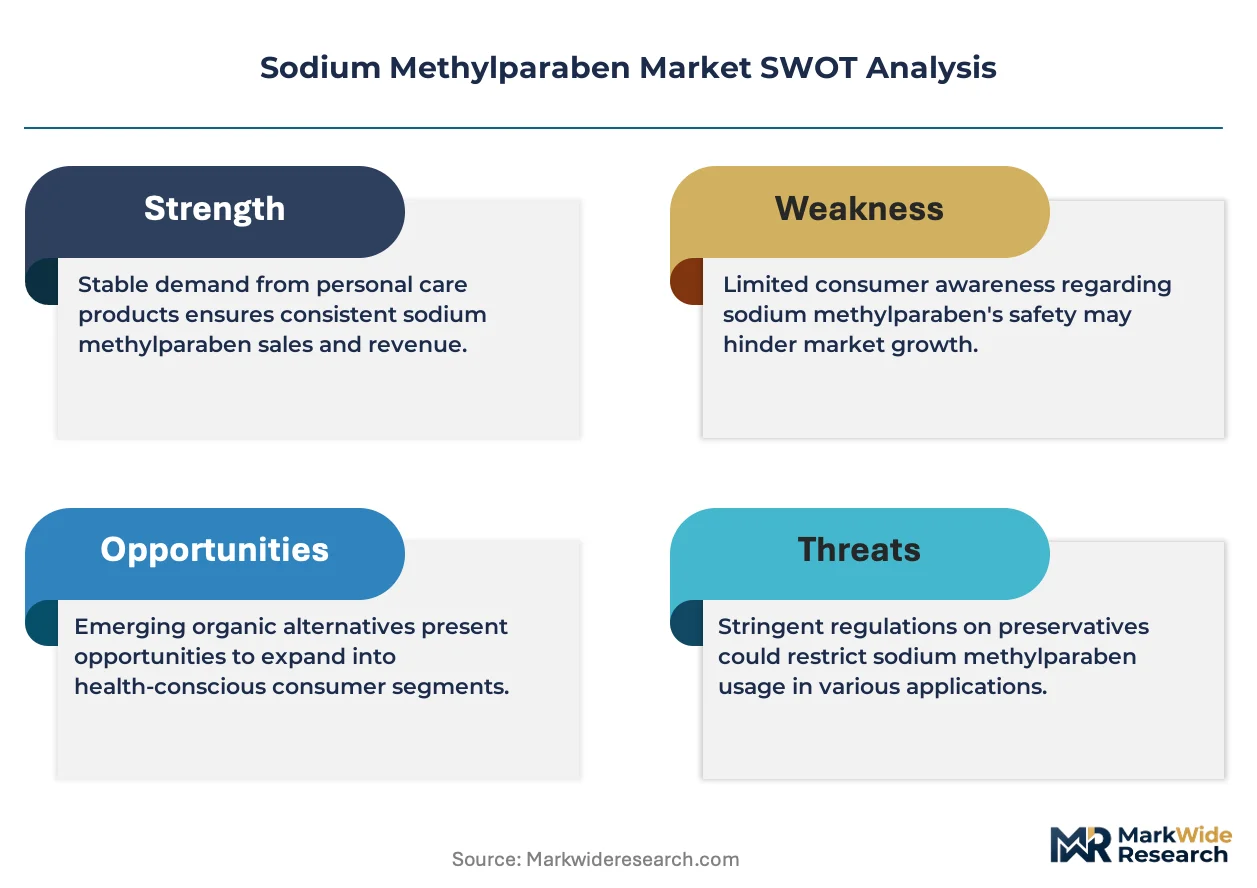
Clean-label formulation pressures are bifurcating sodium methylparaben demand between high-purity pharmaceutical grades and cost-optimized technical powders, forcing suppliers to recalibrate certification investments against margin compression in Asian contract manufacturing.
Growth Catalysts
- REACH concentration limits:ECHA restrictions on paraben levels in leave-on cosmetics are accelerating demand for high-efficacy sodium methylparaben grades that achieve preservation at lower dosage rates.
- Skincare formulation expansion:Sensitivity-grade purity requirements in premium dermocosmetics are deepening margin pools for certified pharmaceutical-grade powder suppliers.
- China domestic brand scaling:NMPA cosmetic safety technical specifications are driving procurement upgrades among Chinese personal care manufacturers seeking export parity with Western regulatory standards.
Market Restraints
- Para-hydroxybenzoic acid feedstock volatility:Backward-integrated producers capture margin stability while toll manufacturers face input cost squeezes during petrochemical cycle swings.
- Clean-label substitution momentum:Phenoxyethanol and organic acid blends are displacing parabens in mass-market personal care, constraining volume growth in food processing applications.
- Zhejiang supply concentration:Cost-optimized Asian powder production clusters create price-floor pressure that compresses returns for European pharmaceutical-grade specialists.
Strategic Opportunities
- Automated manufacturing liquid emulsions:Personal care contract manufacturers in South Korea are adopting pumpable preservative forms despite higher logistics costs, opening formulation service revenue streams.
- Pharmaceutical aseptic packaging:Injectable and ophthalmic applications with sterility-grade sodium methylparaben requirements remain underpenetrated relative to topical cosmetics.
- India PLI scheme alignment:Domestic personal care ingredient manufacturing incentives are creating localized supply chain anchoring opportunities for quality-certified producers.
Industry Challenges
- GMP certification timeline compression:Pharmaceutical-grade facility qualification cycles extend 18-24 months, creating working capital intensity for mid-cap suppliers pursuing dual-use cosmetic-pharmaceutical positioning.
- Legacy formulation revalidation:Cosmetic brands with decades-old paraben-dependent product lines face reformulation costs and stability testing burdens under evolving FDA Modernization of Cosmetics Regulation Act labeling obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Methylparaben Market |
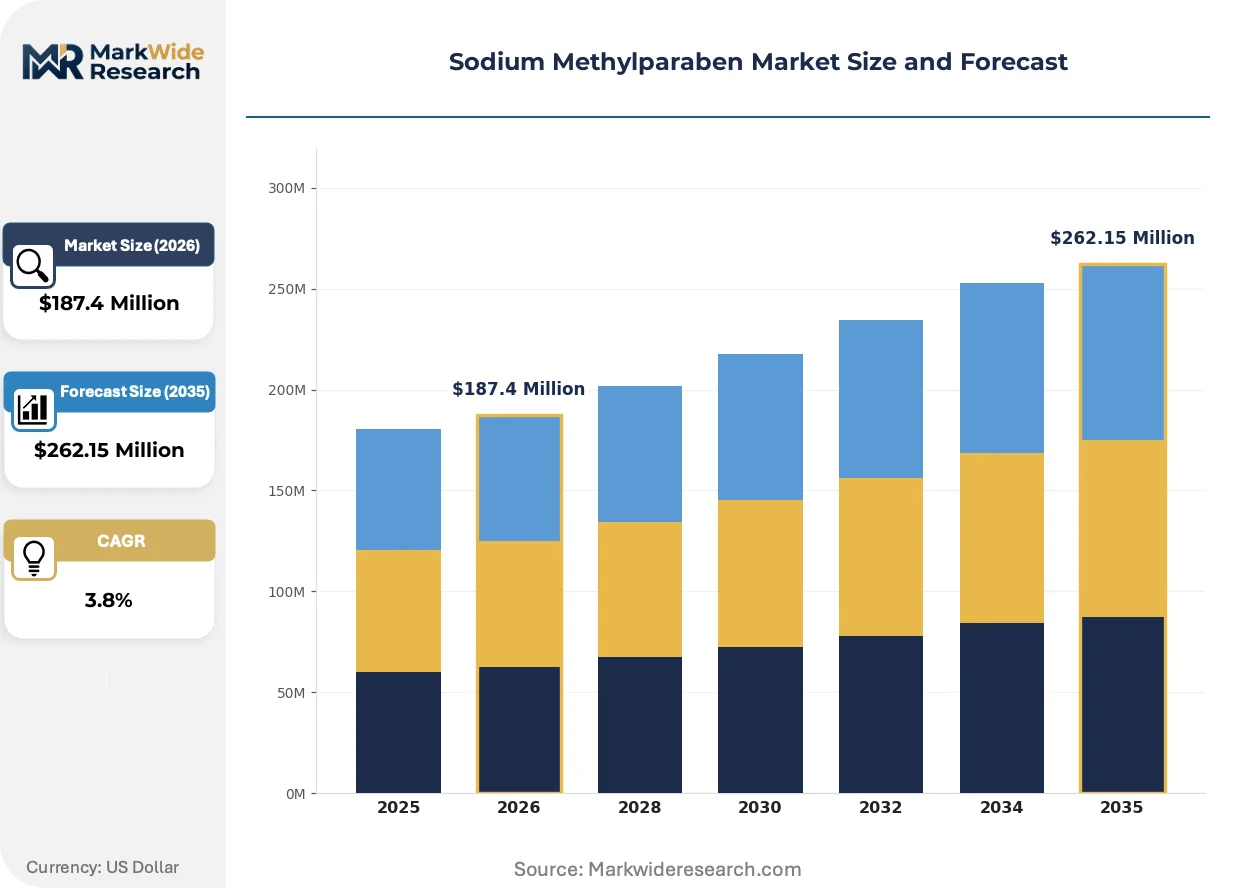
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Personal Care, Pharmaceuticals, Food Preservatives Application: Skincare, Haircare, Makeup, Food Processing End User: Manufacturers, Retailers, Distributors, Wholesalers Form: Powder, Liquid, Granule, Emulsion |
| Companies Covered | Sigma-Aldrich Co. LLC, Merck KGaA, BASF SE, Clariant AG, Ueno Fine Chemicals Industry, Alta Laboratories, Mubychem, Hefei TNJ Chemical Industry Co., Ltd., Zhejiang Shengxiao Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Methylparaben Market Emerging Trajectories
Preservative efficacy testing methodologies and delivery form factors are converging to reshape supplier value propositions beyond commodity powder supply toward integrated formulation services.
Encapsulated sodium methylparaben systems using lipid or polymer matrices are enabling triggered-release preservation in waterless and anhydrous cosmetic formats. Premium skincare brands in France and Germany are piloting these systems for sensitive-skin positioning. The technology is rendering obsolete conventional solubility-limited powder incorporation methods in high-oil-content formulations.
REACH Annex XVII amendments tightening paraben concentration ceilings in leave-on cosmetics are forcing reformulation toward combination preservative systems. European personal care brands are diversifying antimicrobial portfolios to maintain label compliance. Rinse-off product categories face lighter regulatory burdens and are absorbing displaced paraben volumes from restricted leave-on segments.
Direct procurement relationships between sodium methylparaben producers and multinational cosmetic brand technical teams are compressing traditional distributor layers. Regional specialty chemical distributors in Southeast Asia are losing share to manufacturer-hosted technical service programs. This pattern is most visible in Thailand and Vietnam where domestic personal care contract manufacturers scale technical capabilities.
Sodium Methylparaben Market Segmentation
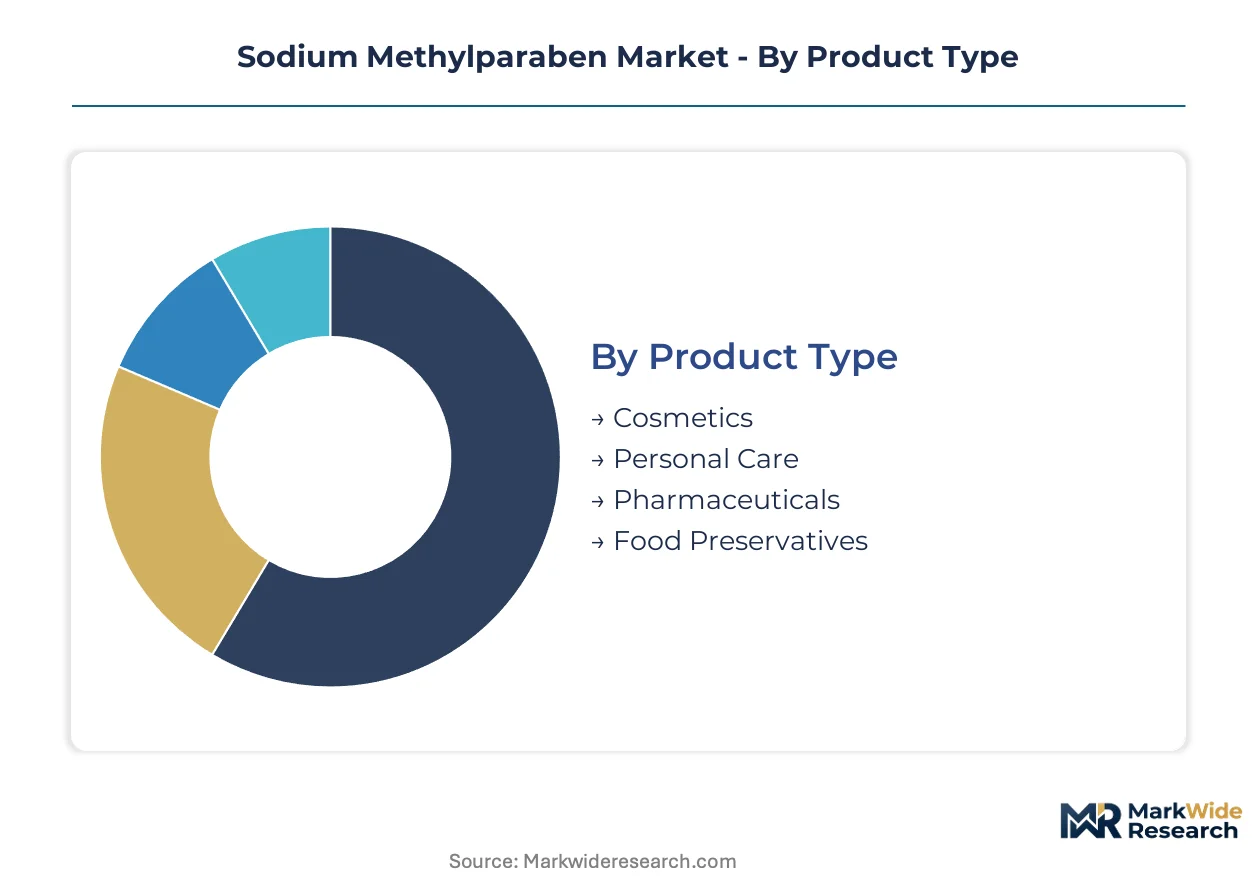
Sodium methylparaben procurement patterns diverge sharply across purity grades and delivery forms, with pharmaceutical certification requirements fragmenting what appears chemically homogeneous. Formulators select grades based on regulatory exposure rather than antimicrobial efficacy alone.
Product Type:
Mature cosmetic applications anchor volume offtake while pharmaceutical and food segments occupy divergent growth trajectories shaped by regulatory stringency.
- Cosmetics:Broad-spectrum preservation in aqueous formulations demands sensitivity-grade purity for facial and body products. European leave-on cosmetics under ECHA REACH Annex XVII concentration limits are accelerating demand for high-efficacy grades that achieve microbial control at reduced dosage rates.
- Personal Care:Shampoos, conditioners, and oral care formulations utilize standard technical grades where rinse-off classification lightens regulatory burdens. Procurement concentrates among Asian contract manufacturers serving multinational brand owners.
- Pharmaceuticals:Injectable and ophthalmic applications require sterility-grade sodium methylparaben with extended GMP certification documentation.
- Food Preservatives:Clean-label substitution pressures from phenoxyethanol and organic acid blends constrain volume expansion in processed food applications.
Cosmetics handles the majority of throughput; Pharmaceuticals is the fastest mover on share.
Application:
Cost tier differentiation separates premium dermocosmetic positioning from mass-market personal care, with formulation complexity driving grade selection.
- Skincare:Premium serums and moisturizers command pharmaceutical-grade powder premiums due to sensitivity-grade purity requirements and extended skin contact duration. French and German dermocosmetic brands pilot encapsulated sodium methylparaben systems for triggered-release preservation in waterless formats.
- Haircare:Shampoos and conditioners absorb displaced paraben volumes from restricted leave-on segments, with rinse-off classification preserving formulation flexibility under ECHA frameworks.
- Makeup:Color cosmetics with high oil content increasingly specify liquid emulsion forms for automated manufacturing line compatibility.
- Food Processing:Beverage and sauce applications face structural headwinds as consumer preference shifts toward preservative-free labeling claims.
Skincare commands the deepest margin pool; Makeup is expanding most quickly as anhydrous formats proliferate.
End User:
Customer type determines procurement sophistication, with direct technical relationships compressing traditional distributor layers in mature markets.
- Manufacturers:Multinational cosmetic brand technical teams engage sodium methylparaben producers directly for formulation development and regulatory documentation support. South Korean and Vietnamese contract manufacturers scale technical capabilities to bypass regional specialty chemical distributors.
- Retailers:Private-label personal care brands source through consolidated procurement platforms with standardized technical grade specifications.
- Distributors:Regional specialty chemical distributors in Southeast Asia lose share to manufacturer-hosted technical service programs.
- Wholesalers:Volume-aggregated spot market transactions serve smaller domestic personal care brands with limited formulation expertise.
Manufacturers handle the majority of throughput; Retailers are gaining share fastest as private-label portfolios expand.
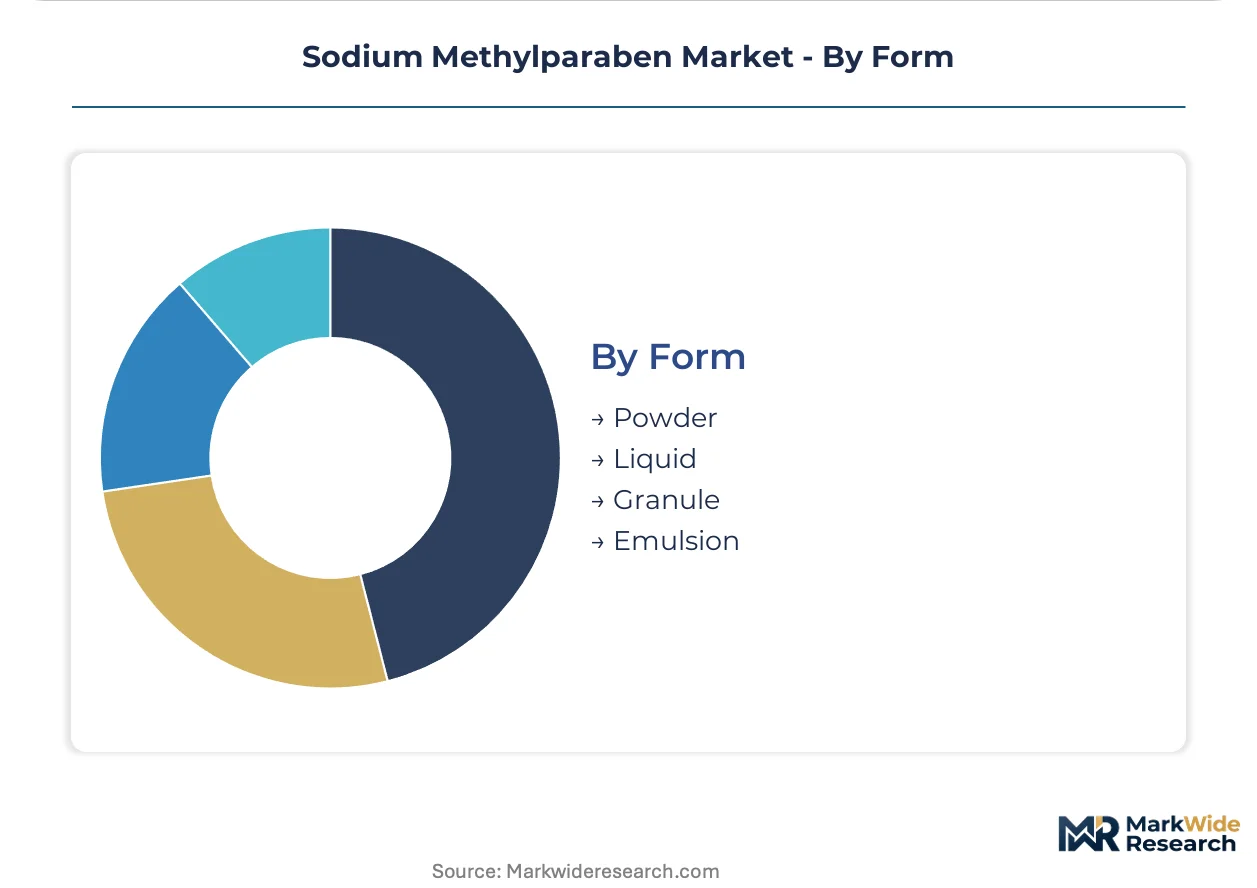
Form:
Supply concentration in powder production creates price-floor pressure, while liquid and emulsion forms capture premium positioning through formulation service integration.
- Powder:White crystalline crystalline material with water solubility exceeding 100 g/L at 25°C remains the default specification for manual incorporation processes. Zhejiang production clusters dominate cost-optimized powder supply for Asian contract manufacturers.
- Liquid:Pumpable preservative solutions enable automated dosing in high-throughput manufacturing lines despite elevated logistics costs for aqueous shipments.
- Granule:Free-flowing agglomerated forms reduce dust exposure during handling for mid-scale batch operations.
- Emulsion:Lipid or polymer matrix systems enable triggered-release preservation in high-oil-content cosmetic formats, rendering obsolete conventional solubility-limited incorporation methods.
Powder handles the majority of throughput; Emulsion is climbing the fastest as waterless skincare formats gain formulation share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory tightening across major consuming jurisdictions is redrawing procurement patterns for sodium methylparaben, with compliance-grade differentiation now determining supplier access rather than commodity pricing alone.
United States
FDA oversight under the Modernization of Cosmetics Regulation Act is elevating documentation requirements for preservative suppliers serving multinational personal care brands. EPA chemical substance reviews intersect with state-level disclosure mandates in California to shape permissible exposure thresholds. New Jersey and Pennsylvania chemical manufacturing corridors host toll production facilities serving East Coast contract manufacturers.
Germany
ECHA REACH Annex XVII concentration limits on parabens in leave-on cosmetics are accelerating demand for high-efficacy grades that achieve preservation at reduced dosage rates. The country's pharmaceutical-grade certification infrastructure sustains premium positioning for suppliers serving dermocosmetic brands. Frankfurt-Rhine-Main chemical clusters anchor formulation technical service programs that bypass traditional distributor layers.
China
NMPA cosmetic safety technical specifications are driving procurement upgrades among domestic personal care manufacturers seeking export parity with Western regulatory standards. Provincial manufacturing incentives in Zhejiang and Jiangsu are scaling cost-optimized powder production for Asian contract manufacturers. Shanghai-based technical teams from multinational brands engage sodium methylparaben producers directly for regulatory documentation support.
France
ANSM oversight of cosmetic preservatives reinforces the country's position as a premium dermocosmetic formulation hub. Paris-region skincare brands pilot encapsulated sodium methylparaben systems for triggered-release preservation in waterless formats. Lyon chemical engineering clusters support lipid-matrix encapsulation technology development for sensitive-skin positioning.
South Korea
MFDS cosmetic safety frameworks align with export-market compliance requirements for personal care contract manufacturers serving global brand owners. Seoul Capital Area manufacturing facilities are adopting pumpable liquid emulsion preservative forms for automated dosing in high-throughput lines. Busan-Ulsan chemical processing zones host GMP-certified production suites leased on asset-light terms to mid-cap suppliers.
Sodium Methylparaben Market Vendor Landscape
On the supply side, the industry is bifurcating between pharmaceutical-grade certification holders and cost-optimized technical powder specialists, with backward integration into para-hydroxybenzoic acid feedstock separating margin-stable producers from toll manufacturers exposed to petrochemical cycle volatility. Two strategic archetypes dominate: integrated chemical majors leveraging captive raw material supply, and regional specialists competing on certification agility for export-market compliance. Capacity expansion in Asian production clusters and direct technical service relationships with brand formulation teams represent the dominant competitive vectors reshaping channel economics.
Among European-integrated chemical majors, Merck KGaA and BASF SE exemplify divergent positioning strategies within the same regulatory environment. Merck KGaA occupies the pharmaceutical-grade tier where GMP certification infrastructure sustains premium supply relationships with dermocosmetic and aseptic packaging applications. BASF SE anchors volume availability through upstream control over para-hydroxybenzoic acid feedstock, capturing margin stability during input cost swings that compress returns for non-integrated competitors. Zhejiang Shengxiao Chemical Co., Ltd. represents the cost-optimized Asian specialist archetype, with production concentration in Zhejiang province creating price-floor pressure that constrains returns for European certification-heavy suppliers in standard technical grade segments.
| Leading Market Players |
|---|
| Sigma-Aldrich Co. LLC |
| Merck KGaA |
| BASF SE |
| Clariant AG |
| Ueno Fine Chemicals Industry |
| Alta Laboratories |
| Mubychem |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Zhejiang Shengxiao Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII concentration limits on parabens in leave-on cosmetics determine both pricing tier spreads and supply chain shape, forcing European formulators toward high-efficacy pharmaceutical grades while Asian contract manufacturers absorb cost-optimized technical powder volumes.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade premiums and technical-grade commodity floors. Three-tier pricing structure across pharmaceutical, sensitivity-grade cosmetic, and standard technical levels stratifies procurement budgets. Cost compression in technical powder segments is intensifying because Zhejiang production clusters flood Asian contract manufacturing channels. Mass-market personal care brands exhibit highest price sensitivity; dermocosmetic and aseptic pharmaceutical buyers accept premiums for GMP documentation depth.
Supply Chain Analysis
South Korean and Vietnamese contract manufacturers hold expanding toll-manufacturing capacity for liquid emulsion forms. Supply concentrates in China, Germany, and South Korea for differentiated grades. Para-hydroxybenzoic acid feedstock, lipid encapsulation matrices, and GMP-certified production suites constitute critical input dependencies. Single-source vulnerability runs through Zhejiang powder production clusters exposed to environmental compliance shutdowns. Distribution runs through direct technical service relationships that displace regional specialty chemical distributors in Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation service attach rates for encapsulated preservative systems and regulatory documentation packages expand faster than commodity powder offtake, creating recurring-revenue layers that decouple supplier economics from raw material cycles.
For Market Incumbents: Entrench pharmaceutical-grade certification moats through GMP facility investments in Frankfurt-Rhine-Main and Busan-Ulsan corridors. Deepen backward integration into para-hydroxybenzoic acid feedstock to capture margin stability during petrochemical volatility. Channel control through manufacturer-hosted technical service programs defends against Zhejiang cost-optimized powder encroachment in Asian contract manufacturing. For New Entrants and Emerging Players: Establish a beachhead in liquid emulsion forms for South Korean automated manufacturing lines, where formulation service integration commands premium positioning. Target India PLI scheme-aligned domestic production incentives for localized supply chain anchoring. Deploy regulatory documentation specialization as go-to-market angle to bypass established distributor relationships. For Investors and Strategic Acquirers: The market sits at a bifurcation phase that favors certification-heavy pharmaceutical-grade specialists over commodity powder exposed to clean-label substitution. Long-term viability centers on dual-use cosmetic-pharmaceutical positioning with GMP infrastructure leverage. Watch NMPA cosmetic safety technical specification evolution as inflection indicator for China export-parity procurement upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive para-hydroxybenzoic acid supply insulates BASF from petrochemical cycle volatility. |
| GMP Certification Investment | Eighteen-month qualification cycles at Merck KGaA sustain premium dermocosmetic relationships. |
| Encapsulation Technology Licensing | Lyon chemical engineering clusters enable triggered-release preservation for waterless formats. |
| Direct Technical Service Programs | Manufacturer-hosted support displaces Southeast Asian distributors in Vietnam and Thailand. |
| India PLI Scheme Alignment | Domestic personal care ingredient incentives create localized supply chain anchoring opportunities. |
Methodological Framework
Cross-validation between regulatory filing analysis and supply chain mapping anchors the qualitative findings in this study. Primary interviews with cosmetic formulation chemists, pharmaceutical regulatory affairs leads, contract manufacturing procurement managers, and specialty chemical distribution channel heads combined with secondary validation from ECHA REACH Annex XVII amendments, NMPA cosmetic safety technical specifications, FDA Modernization of Cosmetics Regulation Act guidance documents, and customs trade flow data. Bottom-up grade-tier demand modeling and top-down regional consumption estimates triangulate volume figures.
Calibration against historical price spreads between pharmaceutical and technical grades, certification timeline data, and feedstock cost indices shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, delivery form, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating clean-label substitution rates and export-parity procurement upgrade patterns in China domestic brands.
Stress conditions across para-hydroxybenzoic acid feedstock volatility, REACH concentration limit amendments, and NMPA specification evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity or technological substitution acceleration. Quarterly review of ECHA Annex XVII amendment proposals, NMPA draft technical specifications, and India PLI scheme disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Minoxidil Market