
 E-Commerce of Agricultural Products Market | 2026-2036
E-Commerce of Agricultural Products Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce of Agricultural Products Market Insights
Direct-to-farm digital procurement channels is reconfiguring how agricultural inputs and fresh produce flow from origin to end user. Alibaba Group leverages its rural Taobao service centers to embed marketplace access deep into county-level supply chains across China. JD.com anchors its competitive stance through proprietary cold-chain logistics networks that guarantee perishable delivery windows. Amazon competes by extending its B2B procurement infrastructure into agrifood vendor onboarding programs.
E-commerce of agricultural products encompasses digital platforms facilitating the sale, procurement, and distribution of farm inputs and outputs through internet-based transaction systems, typically incorporating traceability protocols, quality grading algorithms, and integrated payment settlement mechanisms. The commercial purpose centers on reducing intermediary layers between agricultural producers and downstream buyers while enabling price discovery through transparent bidding mechanisms. Online marketplaces currently dominate transaction volume by aggregating fragmented supply from smallholder farms, though direct-to-consumer channels are capturing margin pools through subscription-based fresh produce deliveries. Mobile payment infrastructure represents the fastest-growing settlement modality across emerging agricultural economies, displacing traditional bank transfer reliance among rural buyers.
India's FSSAI and China's SAMR impose divergent labeling and residue-testing standards that platform operators must reconcile for cross-border seed and fertilizer listings. The EU Green Deal's Farm-to-Fork strategy tightens digital traceability requirements for agricultural imports, compelling marketplace operators to invest in blockchain-based provenance tracking. Stakeholders must monitor how divergent national data localization mandates reshape cloud architecture decisions for agritech platforms serving multiple regulatory jurisdictions.
Market Dynamics
Restaurant and foodservice procurement teams are bypassing traditional cooperative purchasing layers, forcing digital platforms to embed cold-chain logistics and blockchain traceability directly into farm-to-table sourcing workflows.
Growth Catalysts
- India's PLI scheme for agritech:Production-linked incentives for digital marketplace infrastructure are accelerating platform penetration into tier-3 and tier-4 districts.
- Mobile payment settlement:Unified Payments Interface adoption among rural buyers is displacing cash-on-delivery and bank transfer friction in fresh produce transactions.
- Brazil's Mato Grosso soybean belt:Digital procurement platforms are capturing volume previously locked in cooperative purchasing structures.
Market Restraints
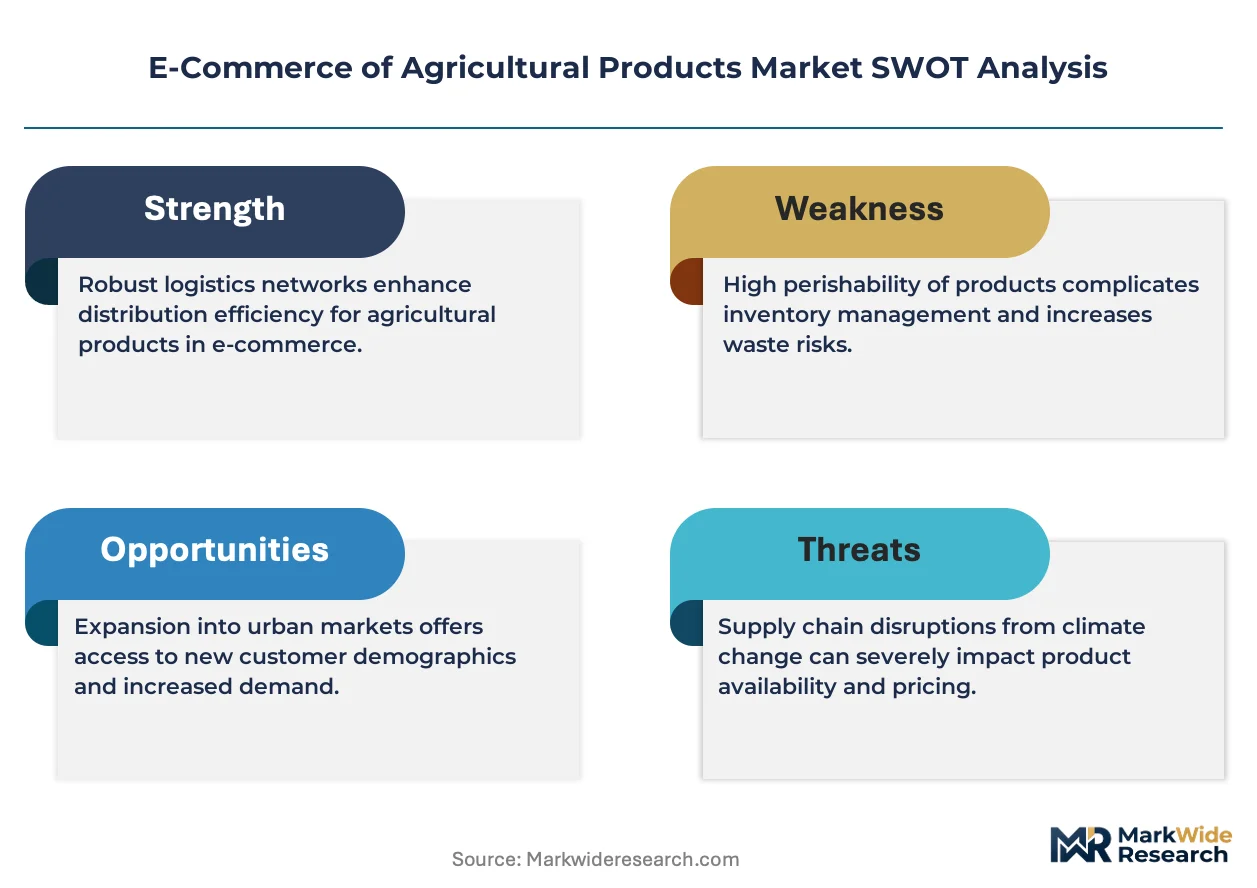
- Input cost volatility:Diesel and refrigerant price swings compress margins for perishable logistics operators running last-mile cold chains.
- Regulatory friction:India's BIS certification requirements for agricultural inputs create cross-border listing delays for fertilizer and seed vendors.
- Supply concentration risk:Cold-chain warehousing capacity clusters around São Paulo and Shanghai, leaving interior production zones underserved.
Strategic Opportunities
- Subscription-based fresh produce:Direct-to-consumer channels are capturing margin pools previously absorbed by wholesale intermediaries.
- EU Green Deal Farm-to-Fork:Blockchain-based provenance tracking mandates are creating first-mover advantages for platforms with embedded traceability.
- County-level supply chain embedding:Rural service center networks in underpenetrated Chinese provinces offer platform density gains.
Industry Challenges
- Refrigeration technician scarcity:Cold-chain equipment maintenance talent gaps in rural India and Brazil delay perishable delivery window guarantees.
- Legacy ERP integration:Cooperative purchasing systems in mature agricultural economies resist API connectivity with digital marketplace backends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce of Agricultural Products Market |
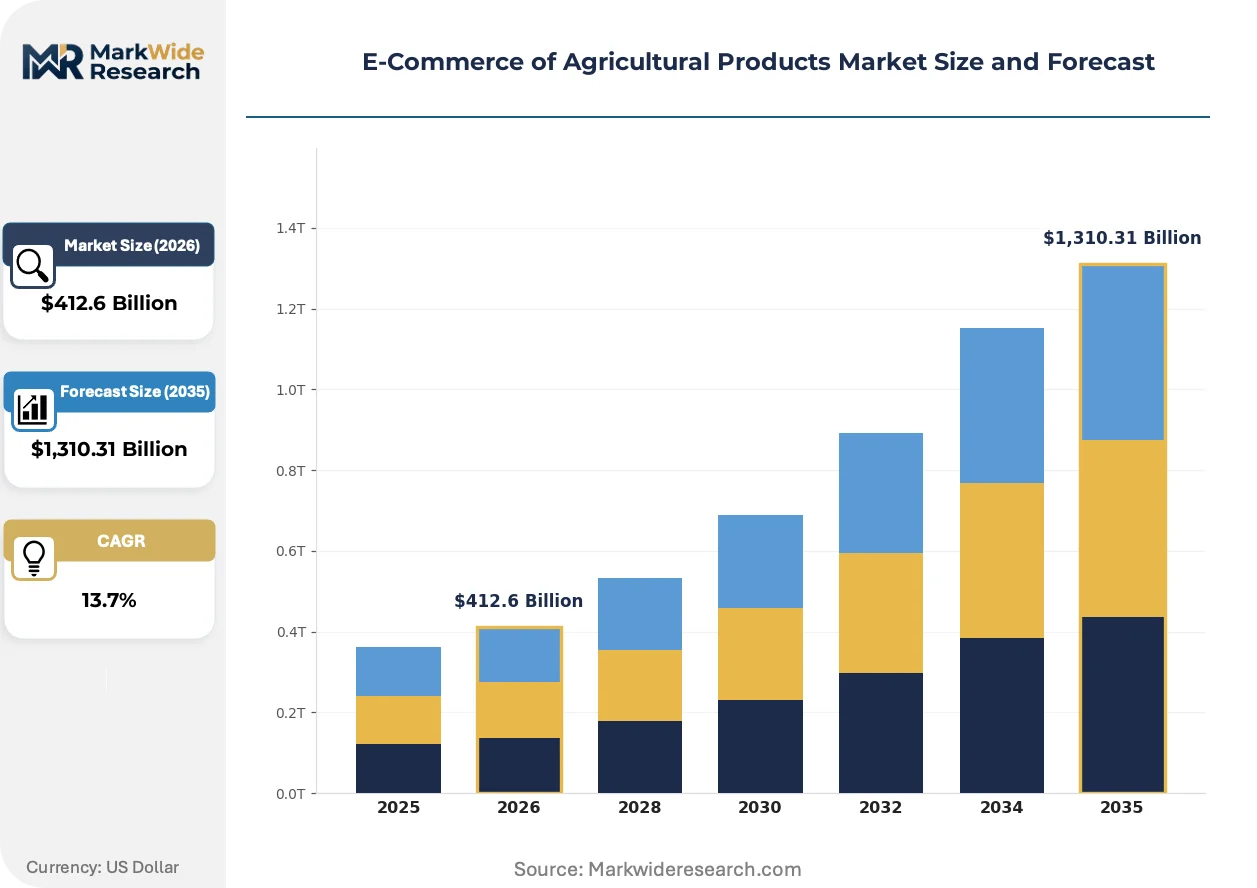
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,310.31 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Seeds, Fertilizers, Pesticides Distribution Channel: Online Retailers, Marketplaces, Direct-to-Consumer, Aggregators End User: Farmers, Distributors, Retailers, Exporters Payment Method: Credit Card, Mobile Payment, Bank Transfer, E-Wallets |
| Companies Covered | Alibaba Group, JD.com, Amazon, Pinduoduo, Agrofy, ProducePay, Farmers Business Network, Tridge, Olam Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce of Agricultural Products Market Trends and Innovations
Digital infrastructure is compressing intermediary layers between agricultural producers and downstream buyers while embedding quality verification and payment settlement into single-platform workflows.
Blockchain-based provenance tracking is hybridizing with IoT sensor networks to create immutable temperature and humidity logs for perishable shipments. Restaurant procurement teams in São Paulo and Shanghai are adopting these integrated systems fastest. This convergence is compressing insurance premiums and dispute resolution cycles for cross-border agricultural transactions.
EU Green Deal's Farm-to-Fork strategy is tightening digital traceability requirements for agricultural imports entering European customs zones. Marketplace operators must now reconcile residue-testing protocols across India's FSSAI, China's SAMR, and EFSA standards simultaneously. Seed and fertilizer listings face the steepest compliance recertification timelines.
Direct farm-to-table sourcing is displacing traditional cooperative purchasing among foodservice buyers seeking price transparency and origin verification. Digital platforms are capturing this volume by offering subscription-based procurement with embedded quality grading algorithms. Brazil's Mato Grosso and India's Punjab belt show the clearest channel migration patterns.
E-Commerce of Agricultural Products Market Segmentation
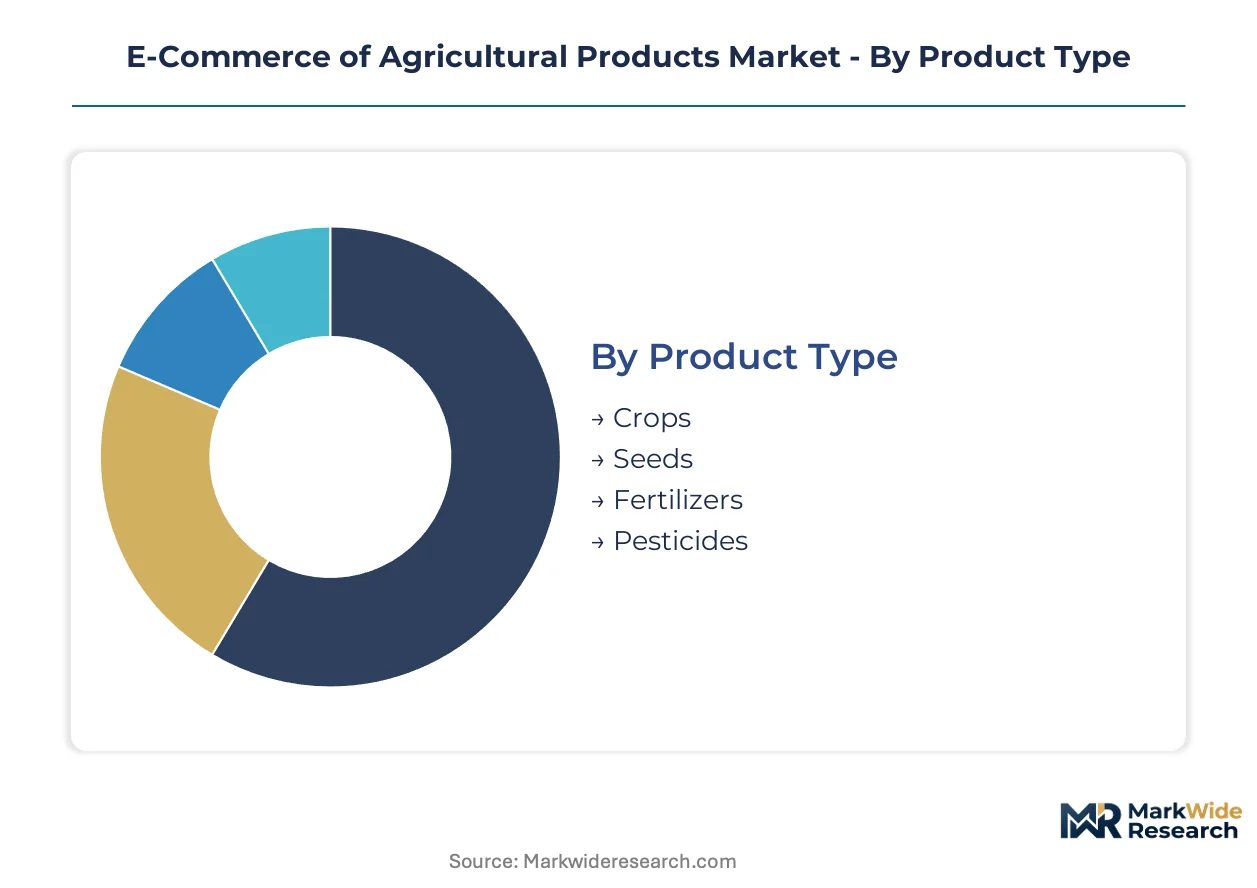
Segmentation in agricultural e-commerce reveals divergent inventory velocities and margin structures across product categories. Cycle-time differentials between perishable outputs and durable inputs dictate platform architecture, logistics partnerships, and working capital requirements.
Product Type:
Crops turn over fastest with harvest-window constraints, while pesticides and fertilizers move slowest due to seasonal application cycles and regulatory shelf-life protocols.
- Crops:Fresh produce and grain commodities with strict perishability windows. Restaurant procurement teams in São Paulo and Shanghai drive demand for same-day harvest verification and cold-chain guarantees. India's UPI settlement infrastructure accelerates spot purchasing during peak harvest windows.
- Seeds:Genetically certified planting stock with varietal purity documentation requirements. Brazil's Mato Grosso soybean belt concentrates demand for trait-verified seed with embedded blockchain provenance tracking.
- Fertilizers:Bulk nutrient inputs with BIS certification mandates in India and residue-testing protocols under EU Green Deal Farm-to-Fork standards.
- Pesticides:Crop protection chemicals requiring cross-border regulatory reconciliation between India's FSSAI, China's SAMR, and EFSA residue limits.
Crops anchor the volume base while seeds gain share at the steepest rate.
Distribution Channel:
Cost tiers separate capital-intensive proprietary logistics from asset-light marketplace models, with margin compression deepest in aggregator-dependent segments.
- Online Retailers:Vertically integrated platforms controlling inventory and fulfillment. JD.com's proprietary cold-chain networks in China guarantee perishable delivery windows that command premium positioning.
- Marketplaces:Transaction-fee models aggregating fragmented supply from smallholder farms. Alibaba's rural Taobao service centers embed marketplace access into county-level supply chains.
- Direct-to-Consumer:Subscription-based fresh produce channels capturing margin pools previously absorbed by wholesale intermediaries. Brazil's interior production zones show fastest adoption.
- Aggregators:Demand-aggregation platforms matching buyers to distributed suppliers. Cold-chain warehousing capacity gaps in rural India and Brazil constrain service guarantees.
Marketplaces anchor the volume base while direct-to-consumer channels expand most quickly.
End User:
Application maturity varies sharply, with foodservice procurement teams adopting digital workflows faster than legacy cooperative members.
- Farmers:Smallholder producers accessing inputs and selling outputs through mobile-first platforms. India's PLI scheme for agritech accelerates tier-3 and tier-4 district penetration.
- Distributors:Wholesale intermediaries integrating digital procurement into legacy ERP systems. Cooperative purchasing structures in mature agricultural economies resist API connectivity.
- Retailers:Grocery and specialty food vendors sourcing traceable produce. EU Green Deal traceability mandates drive blockchain adoption for import compliance.
- Exporters:Cross-border traders reconciling divergent national standards. Seed and fertilizer listings face steepest recertification timelines across regulatory jurisdictions.
Farmers anchor the volume base while exporters climb the fastest despite regulatory friction.
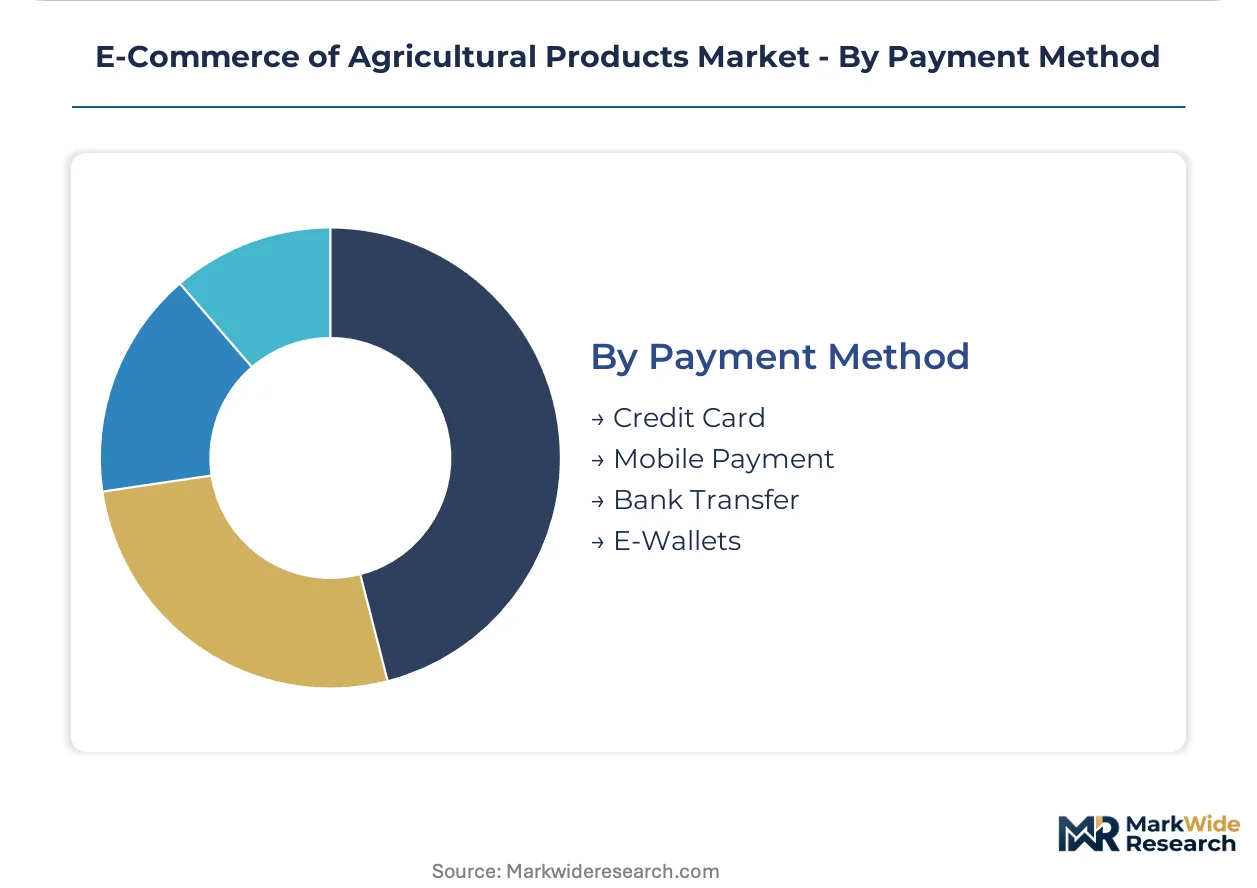
Payment Method:
Settlement velocity correlates with rural financial infrastructure depth, displacing cash-dependent legacy systems.
- Credit Card:Established instrument for commercial buyers and large transactions. Urban foodservice procurement teams in São Paulo prefer card-based settlement for invoice reconciliation.
- Mobile Payment:Unified Payments Interface adoption among rural Indian buyers displaces cash-on-delivery friction. Fastest-growing settlement modality across emerging agricultural economies.
- Bank Transfer:Traditional corporate settlement with documentation requirements. Declining share as real-time alternatives proliferate.
- E-Wallets:Closed-loop and open-wallet systems embedding loyalty and credit features. Alibaba and JD.com ecosystems drive concentration in China.
Mobile payment anchors the volume base in emerging markets while e-wallets gain share fastest in digitally mature economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's high-speed rail freight network underwrites China's dominance in perishable agricultural logistics, while Brazil's North-South railway corridor anchors South American soybean belt connectivity.
China
JD.com's proprietary cold-chain infrastructure and Alibaba's rural Taobao service centers drive platform penetration into county-level supply chains. SAMR's residue-testing standards for cross-border seed listings tighten compliance timelines. The Yangtze River Delta cluster around Shanghai concentrates cold-chain warehousing capacity for premium fresh produce exports.
India
Unified Payments Interface adoption among rural buyers accelerates spot purchasing during harvest windows. The PLI scheme for agritech infrastructure subsidizes marketplace expansion into tier-3 and tier-4 districts. Punjab's agricultural belt shows the clearest migration from cooperative purchasing to digital procurement platforms.
Brazil
Digital platforms capture volume previously locked in Mato Grosso's soybean cooperative purchasing structures. ANVISA's phytosanitary certification requirements create cross-border listing friction for seed vendors. São Paulo's foodservice procurement teams drive fastest adoption of farm-to-table traceability systems.
United States
Farmers Business Network exemplifies the input-aggregator archetype consolidating fragmented farm supply purchasing. USDA's organic certification harmonization with EU Green Deal standards streamlines export platform listings. California's Central Valley clusters cold-chain logistics investment for direct-to-retail produce channels.
Germany
EU Green Deal Farm-to-Fork traceability mandates compel blockchain provenance investment for import compliance. EFSA's residue-testing protocols diverge from India's FSSAI standards, forcing multi-jurisdictional platform architecture. The Rhine-Ruhr logistics corridor anchors cross-border agricultural e-commerce settlement infrastructure.
E-Commerce of Agricultural Products Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated logistics operators and asset-light marketplace aggregators. Capital intensity separates players controlling cold-chain infrastructure from those dependent on third-party fulfillment. Three archetypes dominate: proprietary logistics platforms, transaction-fee marketplaces, and input-focused farmer networks. Competitive moves concentrate on rural service center expansion and blockchain traceability integration.
Within the integrated logistics tier, JD.com and Alibaba Group anchor divergent geographic strategies, with the former emphasizing captive cold-chain networks and the latter embedding marketplace access through county-level service centers. Amazon occupies a position bridging B2B procurement infrastructure with agrifood vendor onboarding. Among farmer-centric platforms, Farmers Business Network exemplifies the input-aggregator archetype consolidating fragmented supply purchasing in North American agricultural markets.
| Leading Market Players |
|---|
| Alibaba Group |
| JD.com |
| Amazon |
| Pinduoduo |
| Agrofy |
| ProducePay |
| Farmers Business Network |
| Tridge |
| Olam Group |
| Others |
Pricing and Supply Chain Analysis
Brazil's Mato Grosso soybean cooperative purchasing concentration feeds margin compression downstream into foodservice procurement tiers, while diesel and refrigerant cost volatility squeezes cold-chain operators running last-mile delivery guarantees.
Pricing Analysis
Volume-discount tiering structures separate spot-market commodity transactions from subscription-based fresh produce channels with embedded quality verification. Three-tier pricing stratifies across premium certified-organic grades, standard commercial grades, and economy bulk lots without traceability documentation. Price differentiation hinges on blockchain-verified provenance and cold-chain delivery window guarantees. Foodservice buyers in São Paulo and Shanghai show lowest price sensitivity, while smallholder farmers accessing inputs through mobile platforms exhibit highest sensitivity to per-unit fertilizer and seed costs.
Supply Chain Analysis
Tariff exposure between India and EU member states dominates supply chain risk for seed and fertilizer vendors navigating divergent BIS and EFSA residue-testing protocols. Geographic supply concentration centers on China's Yangtze River Delta cold-chain clusters, India's Punjab agricultural belt, and Brazil's Mato Grosso soybean corridor. Raw material dependencies include diesel fuel for refrigerated transport, refrigerant gases for cold-chain equipment, and polymer packaging for perishable protection. Distribution runs through vertically integrated platform logistics in China, marketplace-aggregator hybrids in India, and cooperative-displacing digital procurement in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural e-commerce penetration remains in early-cycle expansion, with India's PLI scheme for agritech infrastructure and Brazil's cooperative purchasing displacement representing named adoption tailwinds accelerating platform density gains.
For Market Incumbents: Insulate margin pools by embedding proprietary cold-chain logistics deeper into county-level supply chains and investing in blockchain traceability ahead of EU Green Deal Farm-to-Fork compliance deadlines. Threat vectors include input cost volatility compressing perishable logistics margins and emerging aggregator platforms capturing smallholder farm supply. Vertical integration into refrigerated warehousing capacity anchors defensive positioning. For New Entrants and Emerging Players: Pursue white-space opportunities in tier-3 and tier-4 Indian districts where UPI payment infrastructure has matured but platform penetration remains sparse, and Brazil's interior production zones beyond São Paulo's cold-chain cluster. The most penetrable segment combines subscription-based fresh produce with direct farm-to-table sourcing for foodservice procurement teams. Go-to-market execution should anchor on mobile-first onboarding workflows for smallholder farmers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marketplace aggregators in emerging agricultural economies that have achieved scale but require cold-chain infrastructure investment to reach profitability. Long-term viability over a 5-10 year window rests on platforms capturing cooperative-displaced volume while embedding traceability compliance. The signal to watch is regulatory harmonization progress between India's FSSAI and EU EFSA standards as inflection indicator for cross-border seed and fertilizer listing expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | JD.com's proprietary refrigerated networks in China guarantee perishable delivery windows that command premium positioning. |
| Blockchain Traceability Integration | EU Green Deal Farm-to-Fork mandates compel investment in immutable provenance tracking for agricultural import compliance. |
| Rural Service Center Embedding | Alibaba's county-level Taobao centers embed marketplace access deep into China's underpenetrated interior provinces. |
| Mobile Payment Settlement Infrastructure | India's UPI adoption among rural buyers displaces cash-on-delivery friction in fresh produce transactions. |
| Direct-to-Consumer Channel Launch | Subscription-based fresh produce captures margin pools previously absorbed by wholesale intermediaries in Brazil. |
Research Methodology
Initial hypotheses were tested against primary input from agritech platform executives, cold-chain logistics operators, foodservice procurement directors, and smallholder farmer cooperative leaders and refined through secondary validation. Primary fieldwork combined structured interviews with marketplace operators in China, India, and Brazil alongside input-supply chain assessments. Secondary sources included customs and trade flow databases, agricultural input regulatory filings with India's BIS and China's SAMR, and platform transaction volume disclosures. Bottom-up farmer adoption modeling and top-down market sizing triangulated volume estimates.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, distribution channel architecture, end-user application maturity, and payment settlement modality. CAGRs derived from trajectory analysis of platform penetration rates, cooperative purchasing displacement curves, and cold-chain infrastructure investment cycles. Industry-specific inputs incorporated UPI transaction growth curves in India, EU Green Deal implementation timelines, and diesel price volatility assumptions affecting perishable logistics margins.
Sensitivities concentrate around regulatory harmonization delays between India's FSSAI and EU EFSA standards, refrigerant price spikes compressing cold-chain operator margins, and mobile payment adoption deceleration in rural agricultural economies. Forecasts reflect documented assumptions subject to revision from these factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Alfalfa Pellets Market