
 Gabon Power Market | 2026-2036
Gabon Power Market Size, Share, and Industry Trends Forecast 2026-2036
Gabon Power Market Foresight
Industrial mining offtake is restructuring Gabon's power demand profile as extractive firms pursue dedicated supply agreements. Wärtsilä Oyj Abp leverages its dual-fuel engine portfolio to anchor remote mine electrification projects. Eranove SA sustains its position through concession-based distribution management in urban load centers. China Gezhouba Group Company Limited dominates hydropower engineering, having delivered the Grand Poubara dam complex.
Power in Gabon encompasses electricity generation, transmission, and distribution infrastructure operating across voltage classes from low-tension residential networks to high-voltage industrial interconnects, with thermal plants burning natural gas and heavy fuel oil alongside run-of-river hydropower stations. Hydropower generation leads installed capacity due to the Ogooué River basin's substantial hydraulic potential, while solar deployment accelerates fastest as modular photovoltaic arrays address off-grid mining camps and rural settlements. Transmission and distribution services capture recurring revenue through concession structures, whereas generation assets concentrate margin pools where independent power producers negotiate long-term offtake with industrial anchors.
Gabon's Ministry of Energy and Water Resources, the national regulator ARSEL, and the Central African Power Pool regulatory framework collectively shape market access through licensing requirements and cross-border trading protocols. Environmental compliance under Gabon's Emerging Gabon Strategic Plan mandates environmental impact assessments for new thermal capacity, tilting developer preference toward run-of-river and solar configurations. Stakeholders must monitor how regional integration through the Central African Power Pool redraws investment priority between domestic supply security and export-oriented generation.
Market Dynamics
Mining electrification in Haut-Ogooué province is restructuring Gabon's power procurement architecture, as extractive firms abandon grid dependency for dedicated captive supply arrangements that reshape investment flows across generation and transmission infrastructure.
Growth Catalysts
- Rural Electrification Mandate:Gabon's Energy Transition Plan accelerates grid extension timelines into previously unserved provinces, opening new addressable load centers for concessionaires.
- Run-of-River Hydropower:The Ogooué River basin's hydraulic potential attracts development capital seeking lower environmental compliance burdens than thermal alternatives.
- Off-Grid Mining Camps:Modular solar photovoltaic arrays capture demand from remote extraction sites where transmission extension proves economically unviable.
Market Restraints
- Natural Gas Supply Concentration:Thermal plant operators face feedstock vulnerability tied to domestic gas field depletion rates and import dependency risks.
- Heavy Fuel Oil Price Volatility:Existing thermal fleets burn HFO, exposing operators to bunker fuel price swings that compress operating margins unpredictably.
- Transmission Losses:Distribution infrastructure across Gabon's forested terrain suffers technical and non-technical losses that erode concessionaire returns.
Strategic Opportunities
- Central African Power Pool Integration:Cross-border trading protocols enable export-oriented generation investments with regional offtake security.
- Solar-Diesel Hybridization:Converging photovoltaic and thermal technologies address intermittency while reducing fuel consumption at isolated industrial loads.
- Concession Restructuring:Eranove SA's urban distribution model offers template for private participation in underserved secondary cities.
Industry Challenges
- Grid Integration Complexity:Distributed renewable assets require frequency regulation and voltage stabilization investments that strain legacy network architecture.
- Environmental Assessment Timelines:Emerging Gabon Strategic Plan impact assessment protocols extend project development cycles for new thermal capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gabon Power Market |
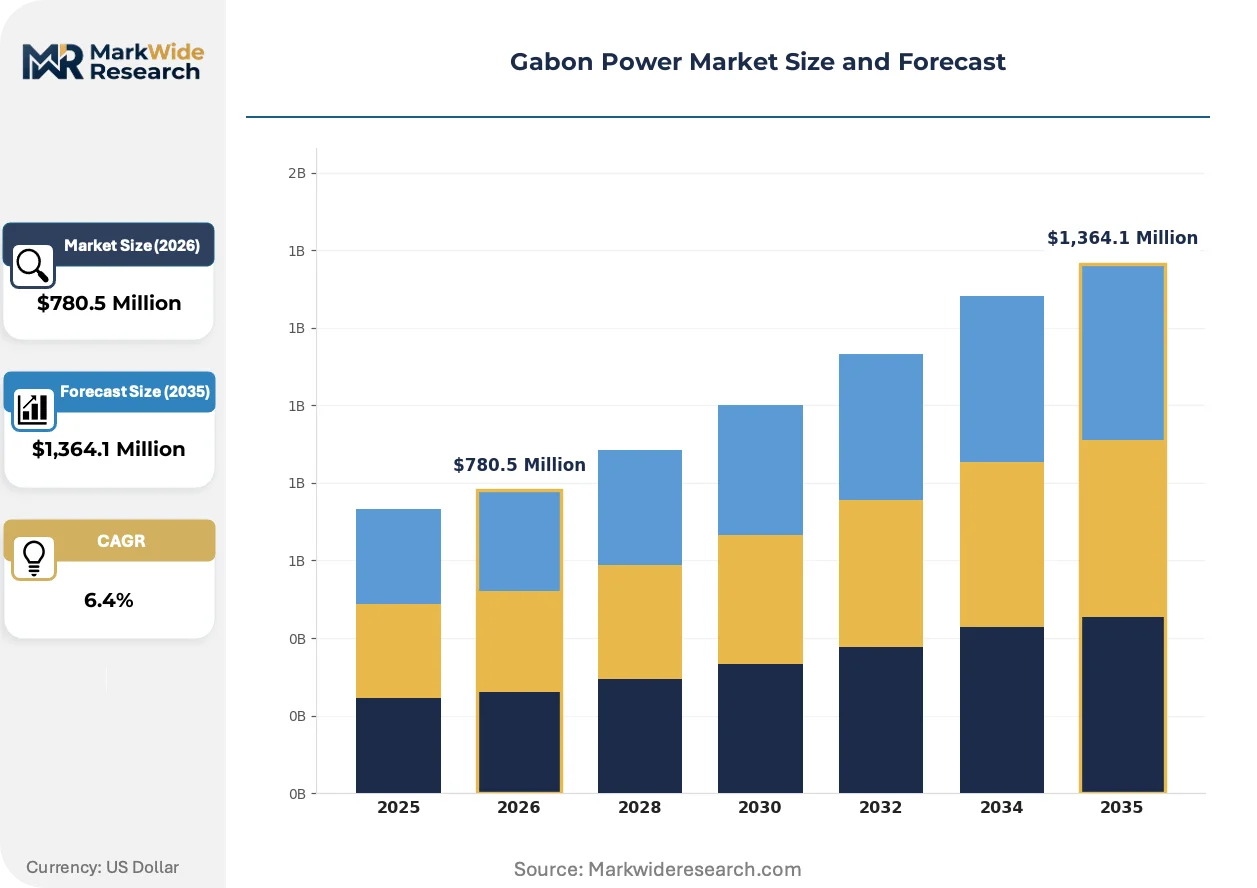
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,364.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydropower, Thermal, Solar, Wind End User: Residential, Commercial, Industrial, Government Service Type: Generation, Transmission, Distribution, Maintenance Technology: Smart Grid, Renewable Energy, Conventional Power, Storage |
| Companies Covered | China Gezhouba Group Company Limited, Wärtsilä Oyj Abp, Eranove SA, Asonha Energie SA, Solen SA Gabon, Engie SA, TBEA Co. Ltd, SEEG, Genser Energy Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gabon Power Market Shifts & Advancements
Dual-fuel engine technology and modular renewable systems are compressing the dominance of conventional thermal baseload, while regulatory pressure under Gabon's energy transition framework accelerates technology substitution timelines.
Containerized dual-fuel engines capable of burning natural gas and heavy fuel oil interchangeably are overtaking single-fuel thermal installations at remote mine sites. Mining operators in Haut-Ogooué province specify these units for procurement flexibility amid gas supply uncertainty. The technology is overtaking fixed-fuel alternatives by eliminating stranded asset risk where pipeline infrastructure remains undeveloped.
Gabon's Ministry of Energy and Water Resources mandates environmental impact assessments for new thermal capacity under the Emerging Gabon Strategic Plan. This regulatory friction tilts developer preference toward run-of-river hydropower and solar configurations with streamlined approval pathways. Industrial anchor customers now specify renewable supply quotas in long-term offtake negotiations.
Power purchase agreements with industrial mining anchors are displacing traditional utility-of-record contracting for large-load connections. Extractive firms in Port-Gentil and Franceville negotiate directly with independent power producers for dedicated supply, bypassing national utility intermediation. This bilateral contracting concentrates most visibly in the Haut-Ogooué mining belt where load scale justifies captive infrastructure investment.
Gabon Power Market Segmentation
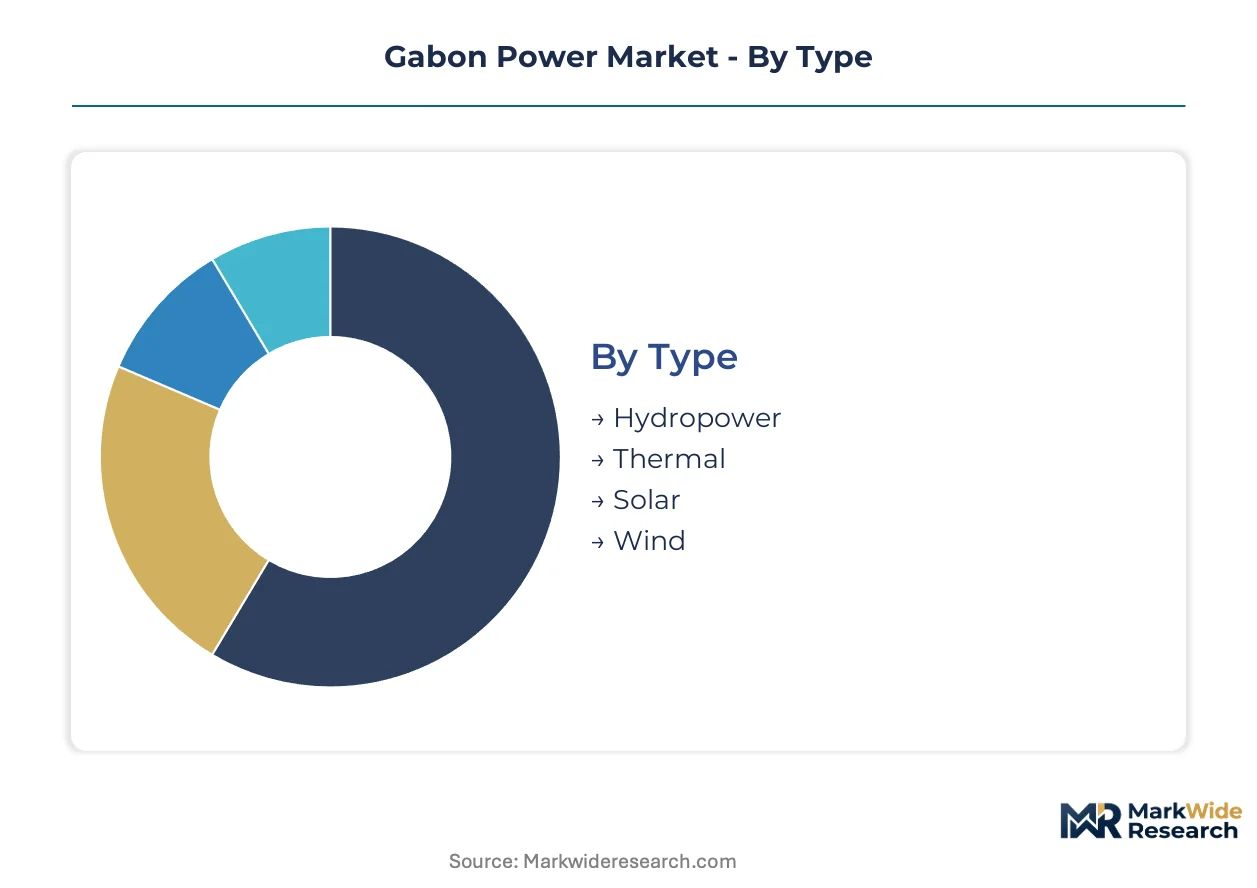
Power market segmentation in Gabon reveals distinct investment profiles across generation technologies and service categories. Each segment carries unique regulatory exposure, capital intensity, and customer concentration patterns that determine competitive positioning.
Type:
Upgrade cycles in Gabon's generation fleet are accelerating as aging thermal assets face environmental compliance deadlines and hydropower infrastructure reaches mid-life refurbishment thresholds.
- Hydropower:Run-of-river installations on the Ogooué River basin deliver baseload capacity with lower environmental compliance burdens than thermal alternatives. Mining operators in Haut-Ogooué province increasingly specify renewable supply quotas in procurement negotiations.
- Thermal:Natural gas and heavy fuel oil plants provide dispatchable backup, though operators face feedstock vulnerability from domestic gas field depletion and bunker fuel price volatility that compress margins unpredictably.
- Solar:Modular photovoltaic arrays address off-grid mining camps and rural settlements where transmission extension proves economically unviable.
- Wind:Coastal wind resources remain underdeveloped due to grid integration complexity and limited resource assessment data.
Hydropower sits at the top of the volume ranking, with solar climbing the fastest.
End User:
Customer concentration patterns in Gabon concentrate revenue pools where load scale justifies dedicated infrastructure investment and long-term offtake security.
- Industrial:Mining electrification in Haut-Ogooué and Port-Gentil is restructuring procurement architecture as extractive firms abandon grid dependency for captive supply arrangements.
- Residential:Grid extension under the Energy Transition Plan opens new addressable load centers in previously unserved provinces.
- Commercial:Urban load centers in Libreville and Franceville generate recurring revenue through concession-based distribution management.
- Government:Public sector demand concentrates in administrative capitals with priority grid access and subsidized tariff structures.
Industrial offtake commands the highest margin pool, with residential expansion showing the steepest trajectory.
Service Type:
Revenue stability varies sharply across the value chain, with capital-intensive generation assets contrasting against recurring-concession transmission and distribution services.
- Generation:Independent power producers negotiate long-term offtake with industrial anchors, concentrating margin pools where bilateral contracts displace utility intermediation.
- Transmission:High-voltage interconnects face technical losses across forested terrain that erode concessionaire returns.
- Distribution:Concession structures in urban load centers sustain Eranove SA's market position through recurring revenue streams.
- Maintenance:Service contracts for dual-fuel engine fleets at remote mine sites capture lifecycle revenue as mining operators prioritize uptime guarantees.
Generation assets absorb the largest capital deployment, with maintenance services gaining share fastest as installed capacity ages.
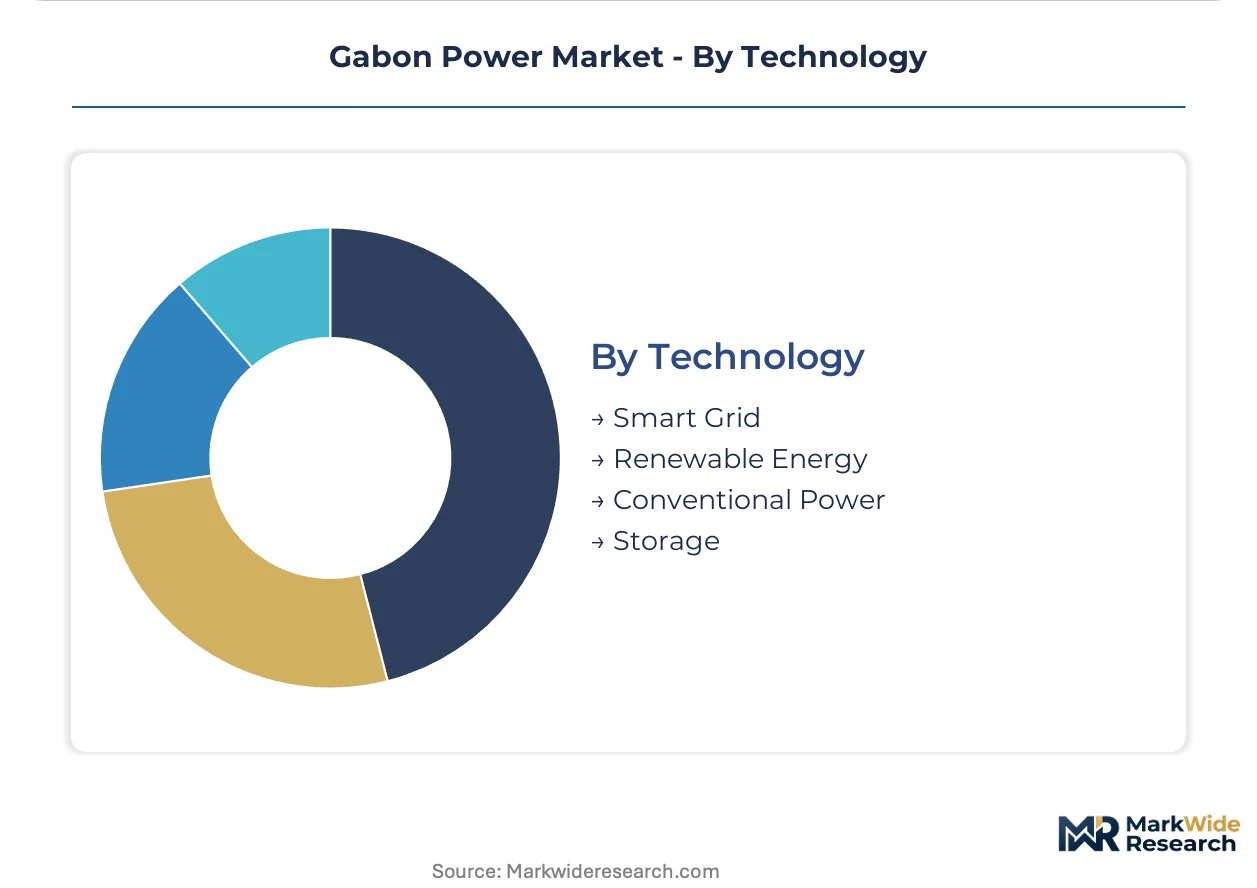
Technology:
Technology substitution timelines are compressing as regulatory pressure under Gabon's energy transition framework accelerates displacement of conventional configurations.
- Smart Grid:Frequency regulation and voltage stabilization investments strain legacy network architecture as distributed renewable assets proliferate.
- Renewable Energy:Run-of-river and solar configurations benefit from streamlined approval pathways under Emerging Gabon Strategic Plan environmental protocols.
- Conventional Power:Fixed-fuel thermal installations face stranded asset risk where pipeline infrastructure remains undeveloped.
- Storage:Battery systems address intermittency at isolated industrial loads, though deployment remains limited by capital constraints.
Conventional power retains installed capacity leadership, with renewable energy expanding most quickly as developer preference tilts toward lower-compliance pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in Central Africa are redirecting power infrastructure investment toward jurisdictions with streamlined environmental permitting and concession frameworks, as developers seek cost-of-compliance advantages in cross-border project development.
Cameroon
Grid interconnection projects with Gabon are advancing under Central African Power Pool protocols, with transmission infrastructure spanning forested border regions. The country's water resources ministry oversees run-of-river licensing on the Sanaga River basin. Industrial load concentration in Douala anchors regional power trading negotiations.
Republic of the Congo
Offshore oil operations in Pointe-Noire are driving captive generation demand that mirrors Gabon's mining electrification pattern. The national energy utility manages distribution concessions with tariff structures subject to petroleum revenue volatility. Brazzaville's administrative load competes with industrial anchors for dispatch priority.
Equatorial Guinea
Natural gas export infrastructure creates feedstock competition for domestic power generation, with Malabo's island grid dependent on liquefied natural gas regasification. The ministry of mines and hydrocarbons regulates gas allocation between export commitments and thermal plant supply. Bioko Island's isolated network configuration limits regional integration opportunities.
Democratic Republic of the Congo
Grand Inga hydropower planning attracts development capital seeking regional export capacity, though transmission infrastructure gaps delay commercialization. The national electricity company manages distribution in Kinshasa with technical loss rates exceeding regional benchmarks. Copperbelt mining demand in Haut-Katanga Province structures bilateral offtake negotiations similar to Gabon's Haut-Ogooué pattern.
Gabon Power Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment suppliers align with engineering contractors to capture integrated project mandates. The vendor base concentrates around three archetypes: European technology licensors with dual-fuel engine portfolios, Chinese engineering-procurement-construction contractors with hydropower delivery capabilities, and African concession operators with urban distribution footprints. Competitive positioning hinges on technology licensing agreements and concession tenure extensions rather than price-based rivalry.
Among the technology-provider tier, Wärtsilä Oyj Abp and China Gezhouba Group Company Limited occupy distinct positioning vectors. Wärtsilä represents the European equipment-licensing archetype with combustion-engine technology applicable to remote industrial loads. China Gezhouba exemplifies the integrated EPC contractor model with hydropower infrastructure delivery experience. Eranove SA anchors the concession-based distribution archetype with urban network management capabilities. These three entities collectively illustrate the tripartite competitive structure governing project origination and asset operation.
| Leading Market Players |
|---|
| China Gezhouba Group Company Limited |
| Wärtsilä Oyj Abp |
| Eranove SA |
| Asonha Energie SA |
| Solen SA Gabon |
| Engie SA |
| TBEA Co. Ltd |
| SEEG |
| Genser Energy Holdings Inc. |
| Others |
Supply & Pricing Matrix
Mining operators in Haut-Ogooué province anchor pricing power through long-term offtake negotiations that bypass national utility intermediation, compressing margins for thermal generators exposed to heavy fuel oil volatility while rewarding independent power producers with bilateral contract security.
Pricing Analysis
Concessionaire margin structures dominate urban distribution in Libreville and Port-Gentil, with Eranove SA's recurring revenue model contrasting against project-based generation tariffs. Price differentiation hinges on fuel source security and environmental compliance tier, with run-of-river hydropower commanding premium rates over heavy fuel oil alternatives. Cost compression in thermal generation is intensifying because bunker fuel price swings erode operator predictability. Industrial mining anchors exhibit lowest price sensitivity due to captive supply imperatives, while residential segments under rural electrification mandates face tariff caps that constrain concessionaire returns.
Supply Chain Analysis
Heavy fuel oil supply rests on import terminals at Port-Gentil and Libreville, with feedstock logistics tethered to Singapore and Rotterdam trading hubs. Dual-fuel engine manufacturing draws from Finland and Switzerland, while photovoltaic module sourcing centers on Chinese producers. Single-source vulnerability concentrates in gas turbine spare parts, where European OEMs control critical component availability. Distribution runs through concessionaire-managed networks in urban load centers, with remote mine sites relying on captive logistics chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gabon's power market offers geographic-arbitrage value through regulatory cost differentials between domestic environmental assessment timelines and streamlined run-of-river approval pathways under the Emerging Gabon Strategic Plan.
For Market Incumbents: Extend concession tenure through proactive grid modernization investments that address technical losses eroding returns across forested terrain. Defend against solar-diesel hybridization threats by anchoring dual-fuel engine maintenance contracts with uptime guarantees. Prioritize backward integration into fuel supply logistics to mitigate heavy fuel oil price volatility exposure.
For New Entrants and Emerging Players: The Emerging Gabon Strategic Plan in Gabon opens a window for modular solar developers targeting off-grid mining camps where transmission extension proves economically unviable. White-space concentration sits in secondary city distribution concessions beyond Eranove SA's urban footprint. Penetrate through power purchase agreement structures that bypass national utility intermediation, mirroring Haut-Ogooué mining procurement patterns.
For Investors and Strategic Acquirers: Chinese engineering-procurement-construction contractors are the most active acquirer in this space, seeking hydropower development platforms with regional export capacity. Long-term viability frames around Central African Power Pool integration timelines and cross-border transmission infrastructure maturation. Target acquisition archetypes include independent power producers with secured mining offtake and concession operators with secondary city expansion rights. Monitor regulatory clarity on environmental impact assessment streamlining as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Bilateral contracts with Haut-Ogooué mining operators displace utility intermediation and secure long-term revenue. |
| Capacity Buildout | Run-of-river installations on the Ogooué River basin leverage streamlined environmental approval pathways. |
| Technology Licensing | Dual-fuel engine portfolios from European licensors address fuel supply uncertainty at remote industrial loads. |
| Vertical Integration into Storage | Battery systems at isolated mining camps reduce diesel consumption and address photovoltaic intermittency. |
| Green Certification Program | Renewable supply quotas in mining procurement negotiations align with Emerging Gabon Strategic Plan mandates. |
Research Methodology
Coverage spans Central Africa, with primary inputs from each national regulatory jurisdiction and cross-border trading framework. The analysis combines structured interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators with secondary validation against EIA data, IEA reports, and project development databases. Bottom-up capacity installation tracking and top-down demand modeling triangulate market sizing across generation, transmission, and distribution segments.
Segmentation granularity extends to fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. Value projections incorporate industrial offtake concentration patterns, concession structure maturities, and rural electrification mandate timelines across the analysis window. CAGRs derive from capacity addition schedules, demand elasticity assumptions, and tariff trajectory modeling. Hydropower refurbishment cycles and solar deployment cost curves inform technology-specific growth rates.
Revisions become necessary when Central African Power Pool integration protocols shift, domestic gas field depletion accelerates, or environmental assessment timelines extend beyond current baselines. Forecasts reflect documented assumptions regarding mining production forecasts, concession renewal probabilities, and renewable cost reduction trajectories. Regulatory clarity on cross-border trading, fuel subsidy structures, and distributed generation interconnection standards warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Solar Inverter Market
Power
Europe Frequency Converter Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Vietnam Power Market
Power
Substation Automation System Market
Power
Brazil Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
LNG Power Barge Market
Power
Compact Substation Market
Power
Distributed Buoyancy Modules Market
Power
Power Shelf Market
Power
Argentina Power Market
Power
Asia-Pacific Microturbine Market
Power
Gas Freeing Fan Market
Power
Solar Plants Controllers Market
Power
North America CHP Market