
 Content Services Platforms Market | 2026-2036
Content Services Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Content Services Platforms Market Intelligence
Composable microservices architecture is fragmenting the traditional monolithic enterprise content management stack into discrete, API-driven capabilities. Madison Logic leverages its intent data infrastructure to anchor account-based content delivery within B2B marketing stacks. Contently specializes in creator marketplace models that sustain brand governance at scale. Writesonic competes through generative AI writing assistance positioned for mid-market content velocity.
Content services platforms are software environments that orchestrate the creation, management, and delivery of structured and unstructured information across distributed workforces, typically exposing functionality through REST APIs and supporting metadata schemas such as Dublin Core or custom taxonomies for enterprise search and retrieval. Their primary commercial purpose is to eliminate content silos by unifying document lifecycles, digital assets, and collaborative workflows within a single governance layer. Cloud-based deployment now leads solution adoption as enterprises prioritize elastic capacity for remote collaboration, while workflow automation represents the fastest-expanding segment as organizations seek to reduce manual routing in approval-heavy processes. Document management remains the most mature solution category, though margin pools are shifting toward AI-powered content collaboration tools that integrate machine learning for automatic classification.
The EU AI Act and GDPR jointly shape product standards for automated content generation and personal data handling across European deployments, forcing vendors to embed explainability controls and consent management into platform architectures. In the United States, the SEC's escalating disclosure requirements for marketing communications drive financial services firms toward auditable content lifecycle platforms. Stakeholders must monitor how divergent regulatory timelines for AI transparency in Brussels and Washington reshape vendor certification roadmaps and customer procurement criteria.
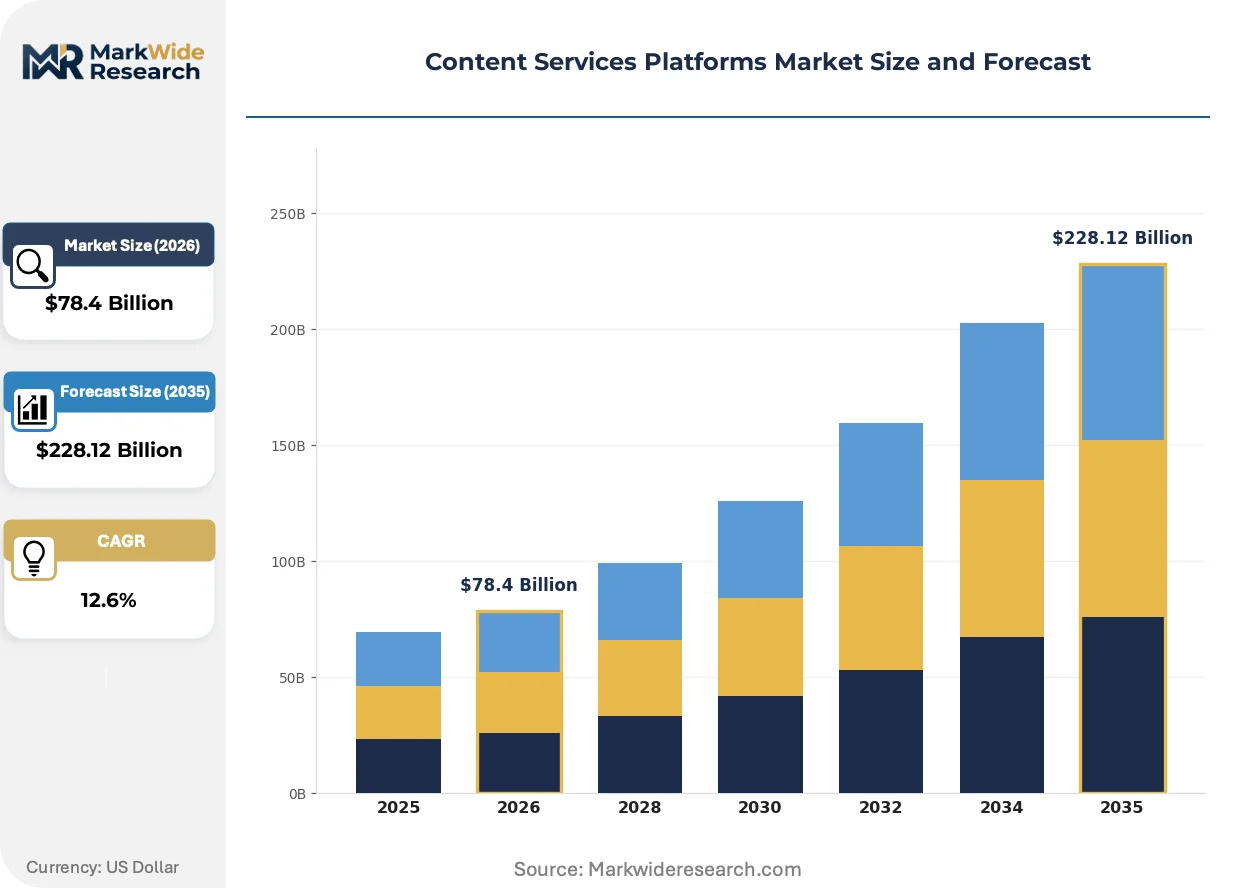
Market Dynamics
Composable microservices architecture is fragmenting monolithic enterprise content management stacks into discrete API-driven capabilities, forcing vendors to unbundle document management, digital asset handling, and workflow automation into separately licensable modules.
Growth Catalysts
- EU AI Act transparency mandates:Automated content generation tools in enterprise settings must embed explainability controls, creating upgrade cycles across European deployments.
- Healthcare cloud migration:Providers are unifying patient records through cloud-based content repositories to eliminate departmental silos and enable real-time clinical collaboration.
- German industrial automation:Manufacturers deploy workflow automation to manage technical documentation across distributed engineering teams, compressing approval cycles for product releases.
Market Restraints
- Legacy system integration costs:Enterprises face substantial capital outlays to connect modern REST API architectures with decades-old document repositories and proprietary metadata schemas.
- GDPR consent management complexity:The regulation's personal data handling requirements force platform vendors to rebuild data lineage tracking, extending sales cycles for European deployments.
- Specialized talent scarcity:Shortages of developers skilled in Dublin Core taxonomies and enterprise search architecture limit vendor delivery capacity.
Strategic Opportunities
- Mid-market content velocity:Generative AI writing assistance tools address underserved mid-market buyers seeking rapid content production without enterprise governance overhead.
- SEC disclosure compliance:Escalating marketing communications audit requirements drive financial services firms toward platforms with immutable content lifecycle records.
- API-first distribution:Headless content services embedded via REST APIs into existing SaaS stacks bypass traditional procurement bottlenecks.
Industry Challenges
- Machine learning classification accuracy:Automatic content categorization models require continuous training on domain-specific corpora, demanding ongoing data science investment.
- Multi-tenant security architecture:Cloud-native platforms must isolate tenant data while enabling cross-organizational collaboration workflows, complicating engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Services Platforms Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $228.12 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Healthcare, BFSI, Retail, Government Solution: Document Management, Workflow Automation, Digital Asset Management, Content Collaboration Technology: Artificial Intelligence, Machine Learning, Blockchain, Robotic Process Automation |
| Companies Covered | Madison Logic, Jasper, Contently, ClearVoice, Writesonic, SalesboxAI, TechTarget Priority Engine, Verblio, NetLine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Services Platforms Market Strategic Shifts & Innovations
Generative AI capabilities are compressing content creation timelines while regulatory frameworks force architectural redesigns around transparency and consent. Vendors must simultaneously accelerate output velocity and embed governance controls.
Headless content management systems are collapsing the distinction between content creation and delivery layers. Industrial manufacturers in Germany adopt these architectures to push technical documentation directly into field service applications without intermediary formatting steps. This compression eliminates traditional web content management intermediaries and shifts margin pools toward API infrastructure providers.
The EU AI Act's transparency obligations for automated content generation are forcing vendors to rebuild product architectures around explainability controls and audit trails. Financial services firms face parallel pressure from SEC disclosure requirements for marketing communications. European deployments now prioritize platforms with built-in consent management, while US financial institutions demand immutable content lifecycle records for regulatory examination.
Intent data infrastructure now anchors account-based content delivery within B2B marketing technology stacks. Madison Logic's approach exemplifies how buyer signal capture reshapes content distribution, with messaging triggered by research activity rather than demographic segmentation. This behavioral pivot concentrates demand among mid-market SaaS vendors seeking to compress sales cycles without expanding field marketing headcount.
Content Services Platforms Market Segmentation
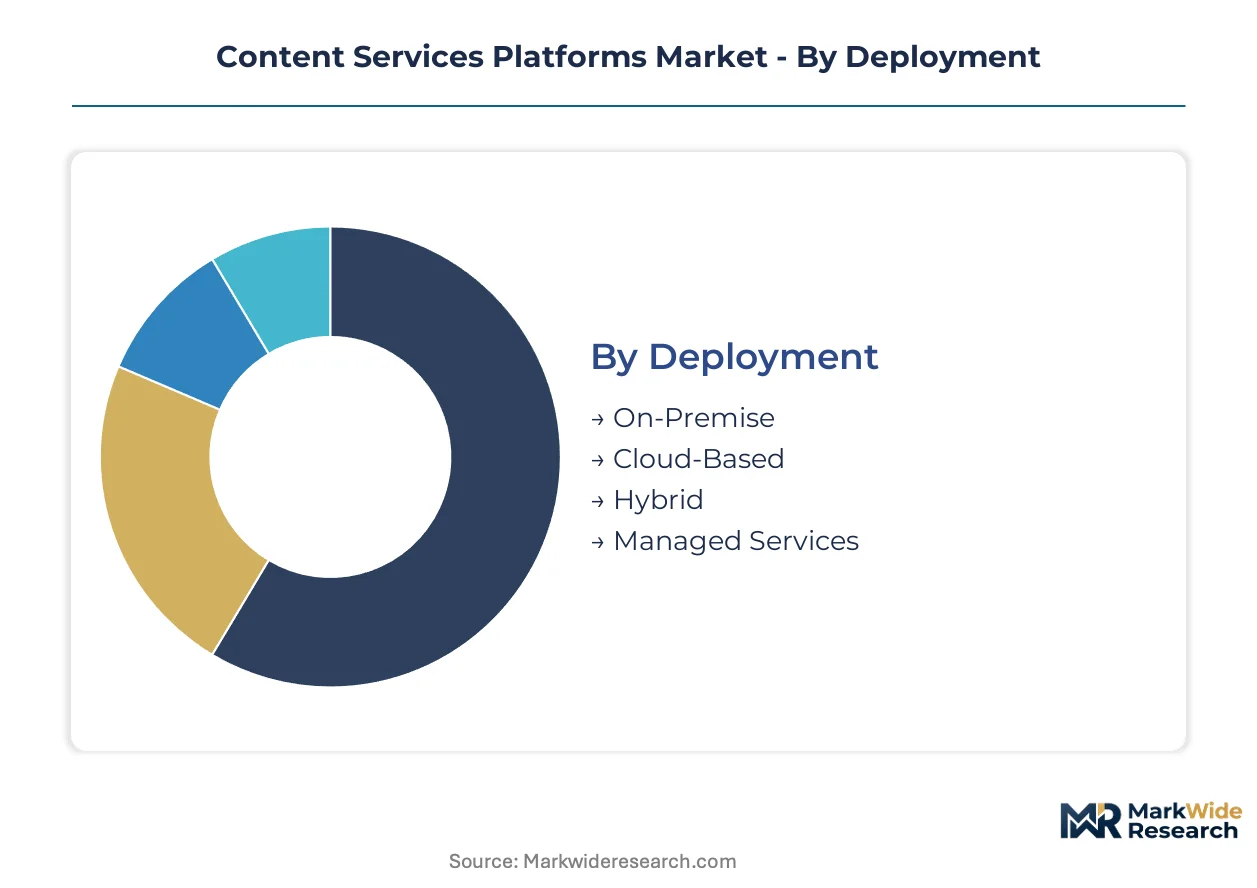
Segmentation in content services platforms reveals how deployment architectures, vertical requirements, and technology stacks reshape procurement patterns. Buyers prioritize elastic capacity for remote collaboration while workflow automation compresses approval cycles in regulated industries.
Deployment:
Use-case spectrum spans legacy compliance workloads to cloud-native collaboration environments with distinct infrastructure obligations.
- Cloud-Based:Elastic capacity provisioning supports distributed engineering teams across German industrial manufacturers. Real-time clinical collaboration in healthcare drives consolidation of departmental silos into unified patient record repositories. Cloud architectures dominate new procurement as enterprises prioritize remote workforce enablement.
- On-Premise:Air-gapped installations persist in financial services firms facing SEC audit requirements for immutable content lifecycle records. Capital intensity and dedicated infrastructure teams limit expansion to compliance-bound incumbents.
- Hybrid:Split architectures accommodate GDPR data residency mandates while enabling cloud-based collaboration for non-sensitive workflows. European deployments favor this model to satisfy cross-border transfer restrictions.
- Managed Services:Outsourced operations reduce internal taxonomy expertise requirements for mid-market buyers. Vendor accountability for Dublin Core schema maintenance addresses talent scarcity constraints.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
End User:
Vertical specialization determines feature prioritization across regulatory intensity and collaboration patterns.
- Healthcare:Cloud-based content repositories unify patient records across departmental silos. German hospital networks and US health systems drive demand for real-time clinical collaboration with HIPAA-compliant audit trails.
- BFSI:SEC disclosure requirements for marketing communications mandate immutable content lifecycle records. Workflow automation compresses compliance review cycles for asset managers and retail banks.
- Government:Procurement bottlenecks favor API-first distribution models that embed headless content services into existing SaaS stacks. Transparency mandates from the EU AI Act reshape automated content generation procurement.
- Retail:Digital asset management for omnichannel product content requires high-velocity creative production. Generative AI writing assistance addresses mid-market content velocity without enterprise governance overhead.
Regulatory intensity concentrates revenue in BFSI; workflow automation gains share fastest in Healthcare.
Solution:
Functional modules unbundle from monolithic stacks as composable microservices fragment traditional enterprise content management.
- Workflow Automation:Approval-heavy processes in German manufacturing compress product release cycles. Robotic routing eliminates manual handoffs across distributed engineering teams with technical documentation requirements.
- Document Management:Mature category with shifting margin pools toward AI-powered classification. REST API exposure enables integration with decades-old proprietary metadata schemas despite legacy system integration costs.
- Digital Asset Management:Brand governance at scale sustains creator marketplace models. Metadata schemas such as Dublin Core support enterprise search and retrieval across unstructured media libraries.
- Content Collaboration:Machine learning classification demands continuous training on domain-specific corpora. Multi-tenant security architecture complicates engineering roadmaps for cross-organizational workflows.
Maturity concentration favors Document Management; AI integration drives steepest expansion trajectory in Content Collaboration.
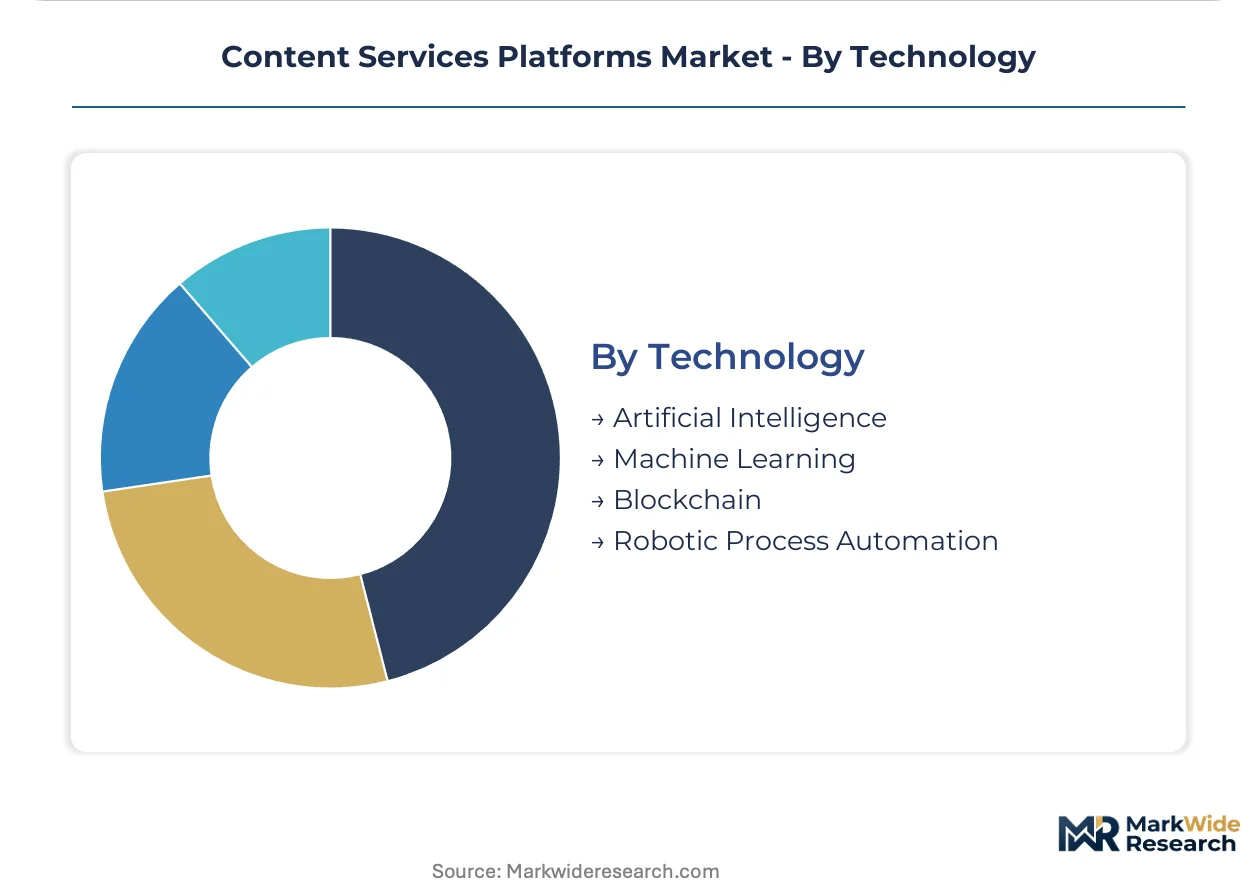
Technology:
Capability layers reshape competitive positioning through automatic classification accuracy and explainability controls.
- Artificial Intelligence:Generative AI capabilities compress content creation timelines while EU AI Act transparency mandates force architectural redesigns. Explainability controls and audit trails embed directly into platform architectures for European deployments.
- Machine Learning:Automatic content categorization requires ongoing data science investment for domain-specific corpus training. Classification accuracy limits determine procurement decisions in document-intensive verticals.
- Robotic Process Automation:Rules-based automation handles structured workflow routing without cognitive classification. Mid-market buyers deploy RPA for rapid implementation without machine learning model training cycles.
- Blockchain:Immutable content lifecycle records satisfy SEC examination requirements for financial services marketing communications. Distributed ledger adoption remains narrow due to integration complexity with REST API architectures.
Deployment scale favors Machine Learning; regulatory tailwinds accelerate Artificial Intelligence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial software vendors export workflow automation platforms to North American manufacturing subsidiaries, while US cloud providers supply healthcare content repositories to hospital networks across Western Europe.
United States
SEC disclosure requirements for marketing communications drive financial services firms toward auditable content lifecycle platforms. HIPAA compliance mandates shape procurement criteria for healthcare cloud repositories. Boston-area health systems and New York financial institutions lead enterprise adoption of AI-powered content classification.
Germany
Industrial manufacturers deploy workflow automation to compress technical documentation approval cycles across distributed engineering teams. The EU AI Act transparency obligations force architectural redesigns for automated content generation tools. Bavarian automotive suppliers and Baden-Württemberg machinery producers anchor demand for API-driven document management.
United Kingdom
BFSI institutions prioritize immutable content lifecycle records for regulatory examination readiness. GDPR consent management requirements extend sales cycles for European deployments. London-based asset managers and Edinburgh insurance operations drive workflow automation adoption for compliance review compression.
India
Mid-market SaaS vendors seek generative AI writing assistance to compress sales cycles without expanding field marketing headcount. The country's data localization policies influence cloud deployment architecture decisions. Bangalore technology parks and Mumbai financial services clusters sustain demand for creator marketplace models.
Japan
Manufacturing conglomerates integrate headless content services into field service applications for technical documentation delivery. METI industrial digitization programs accelerate API-first platform procurement. Nagoya automotive hubs and Osaka industrial machinery producers drive adoption of machine learning classification for document-intensive workflows.
Content Services Platforms Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiers. The vendor base spans intent data infrastructure providers, creator marketplace operators, and generative AI writing assistance developers. Strategic archetypes include account-based marketing platforms, brand governance specialists, and mid-market content velocity tools. Dominant competitive moves encompass API-first distribution partnerships and vertical workflow automation expansion.
Within the intent data infrastructure tier, Madison Logic and TechTarget Priority Engine anchor account-based content delivery architectures. Among generative AI specialists, Writesonic occupies a position addressing mid-market content production velocity. Contently represents the creator marketplace archetype sustaining brand governance at scale. These three exemplify how unbundled microservices fragment traditional monolithic enterprise content management stacks.
| Leading Market Players |
|---|
| Madison Logic |
| Jasper |
| Contently |
| ClearVoice |
| Writesonic |
| SalesboxAI |
| TechTarget Priority Engine |
| Verblio |
| NetLine |
| Others |
Cost & Logistics Intelligence
API infrastructure providers in Germany and cloud hyperscalers in the United States capture downstream margin pools as composable microservices displace monolithic enterprise content management stacks. Pricing power concentrates with vendors controlling REST API distribution channels and Dublin Core taxonomy expertise.
Pricing Analysis
Next-generation AI-powered content collaboration tools command premium subscription tiers against mature document management modules and legacy on-premise licensing. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with cloud-native SaaS offerings priced above managed services and perpetual licenses. Cost compression in mid-market generative AI writing assistance stems from open-source model proliferation. Healthcare providers and financial services firms show lowest price sensitivity due to HIPAA and SEC compliance mandates, while retail digital asset management buyers prioritize volume discounts over feature depth.
Supply Chain Analysis
Export controls on advanced GPU clusters and AI training infrastructure limit vendor access to computational resources for machine learning classification models. Cloud infrastructure supply concentrates in the United States, Germany, and Ireland, with compute capacity expansion in India addressing data localization requirements. Platform architectures rest on hyperscaler partnerships, open-source search libraries, and proprietary metadata schema development. Single-source vulnerability in NVIDIA GPU supply chains threatens AI feature roadmaps for automatic content categorization. Distribution runs through direct enterprise sales, systems integrator partnerships, and API-first embedded deployments within existing SaaS stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of developers skilled in Dublin Core taxonomies and enterprise search architecture constrain vendor delivery capacity and inflate implementation costs across European deployments. Capability scarcity favors incumbents with captive talent pipelines.
For Market Incumbents: Insulate workflow automation revenue in German manufacturing by embedding proprietary technical documentation templates that increase switching costs. Deepen API-first distribution partnerships with healthcare cloud providers to lock out challenger platforms. Madison Logic's intent data infrastructure and Contently's creator marketplace models represent substitute threats requiring defensive feature parity investments. For New Entrants and Emerging Players: Mid-market SaaS vendors in India seeking generative AI writing assistance without enterprise governance overhead represent the most penetrable entry point. API-first headless content services embedded into existing marketing technology stacks bypass traditional procurement bottlenecks. Target financial services firms facing SEC disclosure audit requirements with immutable content lifecycle records as a compliance-first wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed workflow automation specialists serving German automotive and machinery verticals. Long-term viability hinges on AI-powered classification accuracy and multi-tenant security architecture differentiation. Watch for EU AI Act certification completion as an inflection signal separating compliant platforms from stranded legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | REST API embedding into Salesforce and ServiceNow consolidates procurement influence. |
| Acquisition of Specialist Firm | Dublin Core taxonomy boutiques address talent scarcity in European deployments. |
| Geographic Expansion | Bavarian automotive supplier relationships anchor German workflow automation growth. |
| Product Launch | EU AI Act-compliant explainability controls unlock European public sector procurement. |
| Strategic Partnership | Hyperscaler alliances secure GPU capacity for machine learning classification roadmaps. |
Research Approach
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists and secondary sources including SEC filings, hyperscaler capex disclosures, and EU regulatory databases anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure spend data and enterprise software procurement records.
Calibration against historical adoption curves for document management and workflow automation modules shapes the analytical framework across the analysis window. Deployment model, organization size, vertical regulatory intensity, and regional adoption pattern segment the projection. CAGR derivation incorporates technology diffusion rates, compliance mandate enforcement timelines, and API penetration metrics from SaaS integration marketplaces.
Practitioners should monitor EU AI Act implementation timelines, SEC marketing communications disclosure enforcement, and GPU export control expansion for early signals. Forecasts reflect assumptions regarding cloud migration velocity and generative AI feature adoption curves. Material shifts in regulatory certification requirements or hyperscaler partnership exclusivity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Hypervisor Market
Software & Services
Global Architecture Design Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
HPC Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Association Management Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
PCB Layout Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Live Software Market
Software & Services
Automated Testing Software Market