
 HPC Software Market | 2026-2036
HPC Software Market Size, Share, and Industry Trends Forecast 2026-2036
HPC Software Market Outlook
GPU-native codebases are restructuring traditional CPU-bound licensing economics across the HPC software stack. NVIDIA Corporation dominates accelerator-optimized middleware development. Intel Corporation sustains x86-centric parallel programming toolchains through oneAPI investments. Microsoft Corporation extends cloud HPC reach via Azure CycleCloud integration with enterprise procurement systems.
High-performance computing software encompasses parallel execution frameworks, numerical libraries, and workload schedulers designed to distribute computations across clusters exceeding petaflop throughput. These tools orchestrate message-passing interface protocols and memory-optimized kernels to accelerate computationally intensive tasks in climate prediction, genomic sequencing, and derivatives pricing. Cloud-based deployment is capturing the fastest expansion as enterprises shift capital expenditure to operational models. Scientific research applications anchor the largest revenue pool within the application dimension. Optimization solutions command premium pricing due to scarcity of operations-research expertise.
FDA validation requirements govern HPC software deployed in pharmaceutical trial simulations, while EU GDPR frameworks constrain cross-border data movement for cloud-based European workloads. The Securities and Exchange Commission mandates audit trails for financial modeling tools used in stress testing, narrowing vendor qualification pools. Stakeholders must monitor divergence between sovereign AI infrastructure mandates and commercial cloud portability standards.
Market Dynamics
GPU-native acceleration is restructuring licensing economics across the HPC software stack, forcing vendors to abandon perpetual CPU-bound models for consumption-based pricing tied to accelerator throughput.
Growth Catalysts
- Pharmaceutical molecular dynamics:Drug developers deploy HPC clusters for protein folding simulation and virtual screening pipelines. FDA validation pathways for in-silico trial data accelerate software procurement cycles.
- EU AI Act compliance:Algorithmic risk classification mandates drive European enterprises toward auditable HPC infrastructure. Data centers in Germany and France upgrade workload schedulers to meet documentation requirements.
- Cloud operational models:Enterprises shift capital expenditure to subscription-based HPC access. Financial services firms in London and Singapore lead this transition for derivatives pricing workloads.
Market Restraints
- Accelerator supply concentration:NVIDIA dominates GPU middleware development, creating single-source dependency for performance-optimized codebases. Buyers face vendor lock-in across compiler and profiling toolchains.
- Cross-border data friction:GDPR frameworks constrain workload migration between European and non-European cloud regions. Pharmaceutical firms cannot seamlessly burst genomic data to offshore compute nodes.
- Operations research talent scarcity:Optimization solution vendors command premium pricing due to limited expertise in mixed-integer programming and stochastic modeling. Universities produce fewer specialists than industrial demand absorbs.
Strategic Opportunities
- Climate prediction modernization:National meteorological agencies in Japan and Australia upgrade legacy Fortran codebases to GPU-native frameworks. Government procurement windows favor vendors with weather-domain expertise.
- Quantum-classical hybrid interfaces:Convergence of quantum annealers with classical HPC schedulers creates new middleware categories. Early deployments focus on portfolio optimization in quantitative finance.
- Sovereign AI infrastructure mandates:France and Germany allocate public funds for domestically controlled compute clusters. Local software vendors capture preference in public-sector tenders.
Industry Challenges
- MPI expertise attrition:Message-passing interface programming skills diminish as younger developers favor Python-based abstractions. Legacy climate and defense codes require specialized maintenance.
- Multi-cloud orchestration complexity:Enterprises struggle to normalize workload schedulers across AWS ParallelCluster, Azure CycleCloud, and on-premise Slurm deployments. Integration projects consume 18-24 month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPC Software Market |
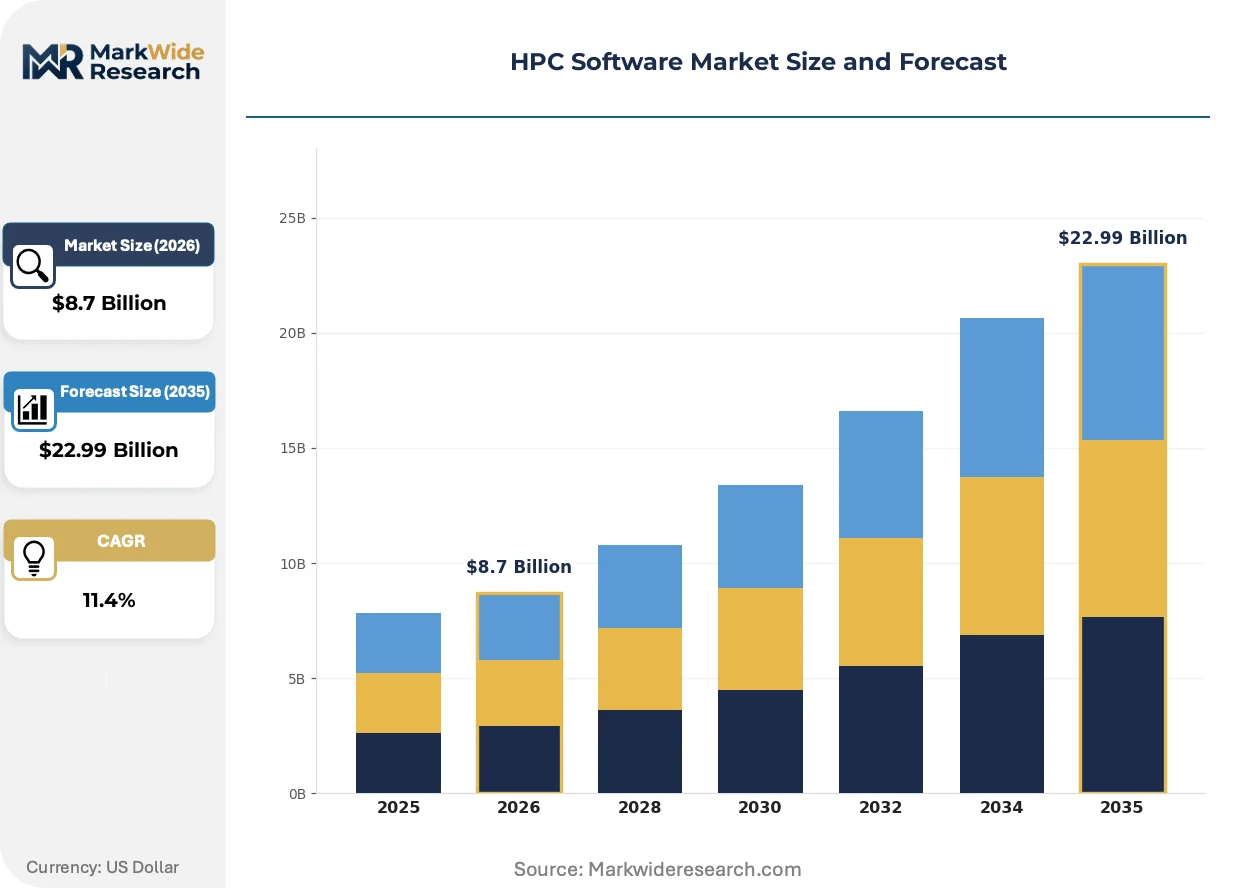
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Scientific Research, Financial Modeling, Weather Simulation, Data Analysis Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Education, Government, Healthcare, Manufacturing Solution: Data Management, Modeling Tools, Simulation Software, Optimization |
| Companies Covered | IBM Corporation, Hewlett Packard Enterprise, Dell Technologies, Intel Corporation, NVIDIA Corporation, Microsoft Corporation, Oracle Corporation, Atos SE, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPC Software Market Strategic Shifts
Containerization and Kubernetes orchestration are penetrating HPC environments previously resistant to cloud-native patterns, forcing traditional workload managers to adapt their architectures.
Container-based HPC environments package MPI dependencies and library versions into portable images. Research consortia in materials science and genomics adopt these formats to reproduce computational experiments across institutional boundaries. This packaging approach is modularizing the software stack into interchangeable components that reduce environment configuration overhead.
The EU AI Act imposes documentation and risk-management obligations on high-performance systems processing algorithmic decisions. European data centers must retrofit workload schedulers with audit logging and model provenance tracking. Financial stress-testing applications face the steepest compliance burden, narrowing qualified vendor pools to those with regulatory expertise.
Enterprise buyers now unbundle software procurement from hardware acquisition, favoring subscription licenses portable across cloud and on-premise infrastructure. Pharmaceutical firms in Switzerland and the United States lead this behavioral shift, negotiating enterprise agreements that decouple seat counts from physical cluster size. This consumption-pattern shift compresses traditional three-year capital cycles into annual renewal negotiations with usage-based true-ups.
HPC Software Market Segmentation
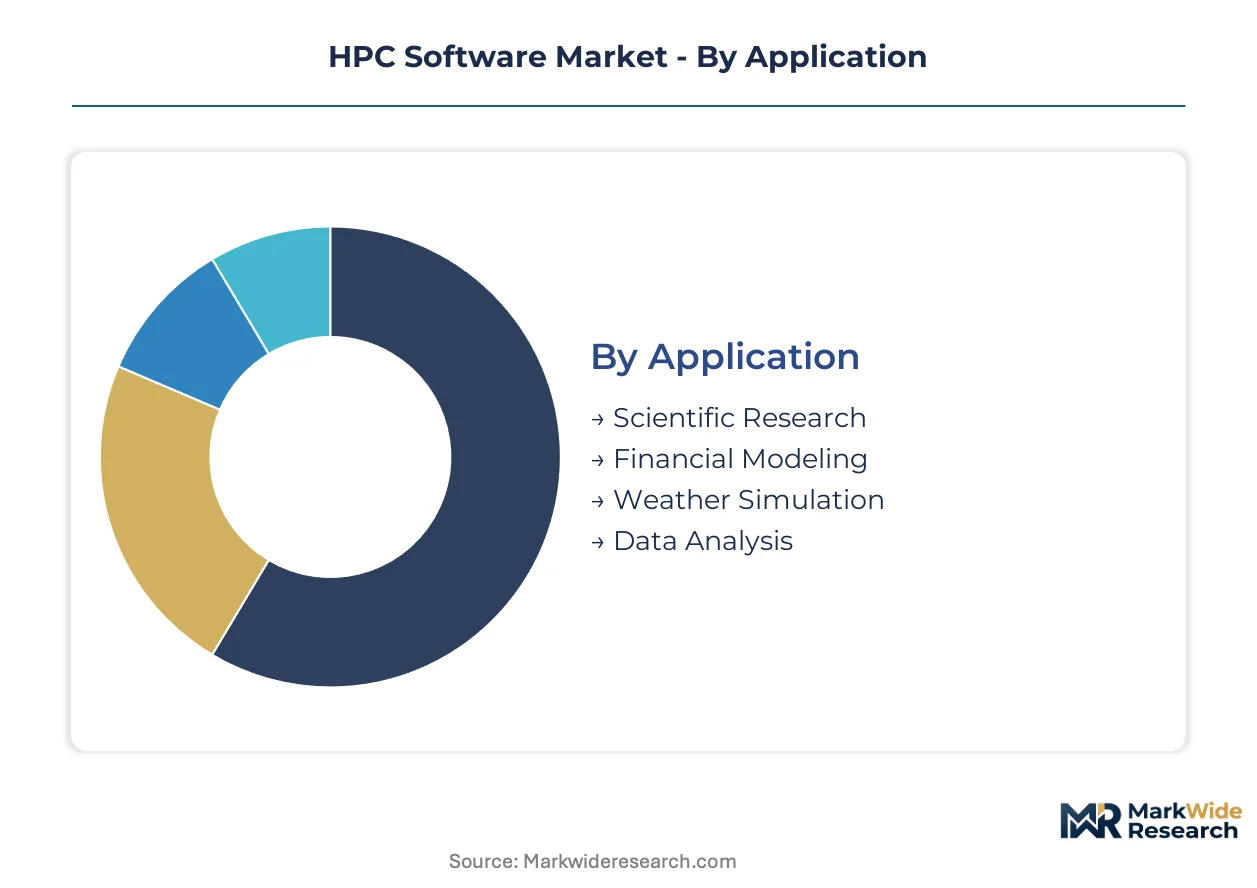
HPC software procurement patterns diverge sharply across deployment models and application domains. Understanding these fault lines reveals where vendor pricing power concentrates and where standardization pressures mount.
Application:
Supply concentration in accelerator-optimized codebases favors vendors with domain-specific compiler expertise.
- Scientific Research:Parallel execution frameworks and numerical libraries dominate institutional procurement at national laboratories and university consortia. Demand concentrates in materials science and genomics workflows where reproducibility requirements drive subscription renewal rates.
- Financial Modeling:Derivatives pricing and risk analytics engines require deterministic execution paths for regulatory audit trails. Banks in London and Singapore prioritize workload schedulers with sub-millisecond latency guarantees for trading floor integration.
- Weather Simulation:Legacy Fortran modernization projects consume GPU-native middleware upgrades at meteorological agencies.
- Data Analysis:Python-based abstraction layers displace hand-tuned MPI implementations for exploratory workloads.
Today's leader: Scientific Research. Tomorrow's challenger: Financial Modeling.
Deployment:
Cost tier stratification separates capital-intensive on-premise builds from operational expenditure models favored by mid-market enterprises.
- Cloud-Based:Subscription licensing portable across AWS ParallelCluster, Azure CycleCloud, and Google Cloud HPC enables workload bursting without hardware ownership. Pharmaceutical firms in Switzerland and the United States negotiate enterprise agreements with usage-based true-ups.
- Hybrid:Burst capacity to cloud during peak simulation windows while retaining sensitive data on sovereign infrastructure. European pharmaceutical firms deploy this architecture to satisfy GDPR constraints on genomic data residency.
- On-Premise:Perpetual licenses tied to physical cluster size dominate defense and intelligence agency procurement.
- Edge Computing:Containerized MPI workloads deploy to remote sensor networks for real-time inference.
Cloud-Based deployment is expanding most quickly as procurement shifts from three-year capital cycles to annual renewals.
End User:
Customer type determines compliance burden and integration timeline complexity.
- Government:Sovereign AI infrastructure mandates in France and Germany allocate public funds for domestically controlled compute clusters. National tenders favor vendors with security clearance and local support presence.
- Healthcare:FDA validation requirements govern software deployed in pharmaceutical trial simulations, narrowing qualified vendor pools to those with regulatory documentation libraries.
- Manufacturing:Digital twin deployments for automotive and aerospace stress testing drive demand for real-time co-simulation platforms.
- Education:Research consortia adopt containerized environments to reproduce computational experiments across institutional boundaries.
Government end users anchor procurement volume. Healthcare end users command premium pricing through compliance-driven vendor selection.
Solution:
Margin concentration follows scarcity of specialized expertise rather than software commoditization.
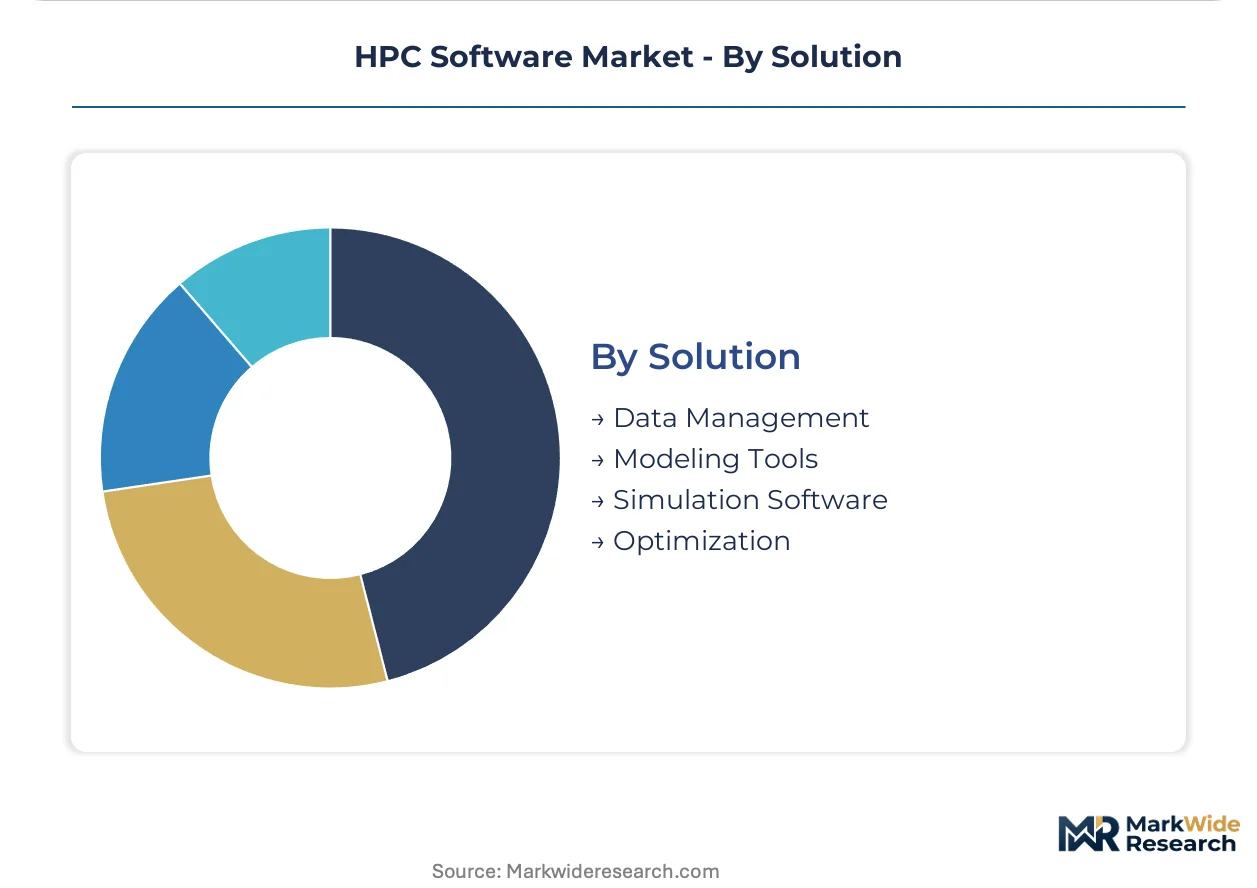
- Optimization:Mixed-integer programming and stochastic modeling toolkits command premium pricing due to limited operations research talent production at universities. Quantitative finance and logistics planning absorb the majority of specialist capacity.
- Simulation Software:Molecular dynamics and computational fluid dynamics packages anchor pharmaceutical and automotive R&D budgets. Protein folding pipelines at drug developers drive recurring license expansion.
- Data Management:Provenance tracking and audit logging capabilities retrofit existing schedulers to meet EU AI Act documentation obligations.
- Modeling Tools:Pre-built numerical kernels accelerate climate and materials science workflows without custom MPI development.
Optimization solutions capture the steepest pricing premiums. Data Management solutions face the fastest standardization pressure from open-source alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Stuttgart anchor the European industrial computing corridor where pharmaceutical and automotive firms concentrate HPC procurement. Government-funded sovereign clusters in France and Germany reshape vendor qualification requirements. Cloud migration accelerates in Switzerland and the United Kingdom as financial services firms operationalize derivatives workloads.
United States
Pharmaceutical molecular dynamics and FDA-validated in-silico trials drive software procurement at drug developers clustered in Boston and San Francisco. The SEC mandates audit trails for financial stress-testing tools, narrowing vendor pools for Wall Street quantitative desks. National laboratories in Oak Ridge and Argonne modernize legacy Fortran climate codes through GPU-native middleware upgrades.
Germany
Automotive digital twin deployments and EU AI Act compliance obligations concentrate demand in Baden-Württemberg and Bavaria. The KBA coordinates with federal data protection authorities on cross-border workload documentation standards. Munich-based pharmaceutical firms retrofit schedulers with audit logging to satisfy algorithmic risk classification mandates.
United Kingdom
London financial services firms lead cloud HPC adoption for derivatives pricing and regulatory stress testing. The Financial Conduct Authority aligns with emerging EU AI Act documentation expectations for algorithmic trading infrastructure. Edinburgh and Cambridge research consortia adopt containerized MPI environments for reproducible genomics workflows.
Japan
METI-funded quantum-classical hybrid initiatives converge with national meteorological agency Fortran modernization programs. Pharmaceutical regulators at PMDA accelerate validation pathways for protein folding simulation software. Tokyo and Osaka industrial computing centers upgrade workload schedulers to support containerized burst capacity for materials science research.
Switzerland
Swissmedic validation requirements govern HPC procurement at Basel-based pharmaceutical headquarters for clinical trial simulation. Roche and Novartis negotiate enterprise licensing agreements decoupled from physical cluster size. Geneva financial institutions deploy subscription-based optimization toolkits for quantitative portfolio management under FINMA oversight.
HPC Software Market Competitive Environment
Global majors compete with regional champions across compiler toolchains, workload schedulers, and domain-specific middleware layers. Accelerator-optimized codebases concentrate pricing power with vendors possessing GPU-native expertise, while x86-centric parallel programming ecosystems sustain alternative procurement channels. Three archetypes dominate: semiconductor-integrated software stacks, cloud-native orchestration platforms, and vertical specialists in regulatory-compliant scientific computing. Competitive moves center on strategic partnerships with national research laboratories and geographic expansion into sovereign AI infrastructure tenders.
Within the semiconductor-integrated tier, NVIDIA Corporation and Intel Corporation exemplify divergent architectural bets on accelerator versus x86 optimization. Microsoft Corporation occupies a position bridging cloud orchestration and enterprise procurement system integration. Atos SE anchors European vendor participation in France and Germany's public-sector sovereign computing initiatives.
| Leading Market Players |
|---|
| IBM Corporation |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Intel Corporation |
| NVIDIA Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Atos SE |
| Fujitsu Limited |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement clusters in Basel, Boston, and San Francisco anchor pricing power for FDA-validated molecular dynamics suites, locking vendors into consumption-based accelerator licensing rather than perpetual CPU-bound models.
Pricing Analysis
Accelerator silicon costs pass through directly to software licensing economics, with NVIDIA GPU-optimized middleware commanding premium subscription tiers against Intel oneAPI alternatives. Price differentiation rests on FDA validation tier and MPI optimization depth for legacy Fortran workloads. Pricing pressure intensifies in cloud-native segments as AWS ParallelCluster and Azure CycleCloud compress margins through bundled orchestration. Mid-market financial services firms in Singapore and London exhibit highest price sensitivity, while defense agencies tolerate cost premiums for air-gapped deployment security.
Supply Chain Analysis
Dual-sourcing requirements from European pharmaceutical and automotive buyers mandate qualification of both NVIDIA CUDA and Intel SYCL compiler stacks to mitigate accelerator lock-in risk. Software development concentrates in the United States, Taiwan, and Germany, with kernel optimization talent pools feeding from national laboratory ecosystems. The supply chain draws from specialized operations research PhD pipelines, GPU hardware availability, and open-source MPI distribution maintenance. Single-source vulnerability concentrates in NVIDIA's profiling and debugging toolchain dominance. Distribution runs through direct enterprise licensing for on-premise clusters and hyperscaler marketplaces for cloud burst capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance costs in Germany and France run 40-60% above equivalent UK implementation, creating arbitrage opportunity for vendors with modular audit-logging architectures portable across regulatory regimes.
For Market Incumbents: Deepen compiler toolchain integration with sovereign AI infrastructure tenders in France and Germany, where Atos SE and local champions currently capture public procurement preference. Defend position against cloud-native entrants by embedding workload schedulers directly into pharmaceutical FDA validation pathways, creating switching costs through regulatory documentation libraries. Prioritize GPU-native Fortran modernization partnerships with Japan's meteorological agencies to anchor climate simulation market share. For New Entrants and Emerging Players: Launch via containerized MPI distribution models targeting research consortia in materials science and genomics, where reproducibility requirements favor portable environment packaging. Exploit white-space in quantum-classical hybrid scheduler middleware for quantitative finance applications, a segment where incumbent toolchains lack optimization depth. Target Swiss pharmaceutical headquarters with subscription licensing decoupled from physical cluster size, matching Roche and Novartis procurement preferences. For Investors and Strategic Acquirers: Cloud hyperscalers are the most active acquirer in this space, seeking to verticalize HPC orchestration layers into bundled compute offerings. Long-term viability favors vendors with domain-specific compiler expertise in molecular dynamics or climate simulation rather than generic workload schedulers. Acquisition target archetype: vertical specialists with FDA-validated codebases and existing pharmaceutical enterprise agreements. Watch for inflection in EU sovereign AI infrastructure tender awards as signal for regional vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Native Compiler Migration | Fortran modernization at Japan's meteorological agencies opens government procurement windows for middleware vendors. |
| EU AI Act Compliance Integration | Audit-logging retrofit contracts at Munich pharmaceutical firms capture recurring data management revenue streams. |
| Quantum-Classical Hybrid Platform | Portfolio optimization interfaces for Tokyo quantitative desks create new middleware category between annealers and schedulers. |
| Containerized MPI Distribution | Reproducible environment packaging penetrates materials science consortia resistant to traditional cloud-native patterns. |
| Sovereign Cloud Partnership | French and German public-sector tenders favor vendors with security clearance and localized support infrastructure. |
Study Parameters
Multiple input streams — primary interviews with HPC procurement officers and platform engineers, secondary validation through hyperscaler capex disclosures and national laboratory budget allocations, and trade data on accelerator hardware shipments — were reconciled to construct market estimates. Stakeholder roles included CTOs at pharmaceutical firms, workload scheduler architects at financial services firms, and research computing directors at university consortia. Secondary sources encompassed SEC filings from semiconductor vendors, EU tender documentation for sovereign AI infrastructure, and FDA validation pathway records for in-silico trial software. Bottom-up cluster deployment counts and top-down software licensing revenue estimates were triangulated to verify segment sizing.
Historical spending patterns from national meteorological agencies and pharmaceutical R&D budgets were cross-referenced against panel input from procurement officers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include deployment model, application domain, end-user vertical, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cloud migration rates and accelerator adoption curves, with specific inputs from derivatives pricing workload growth in London and Singapore and molecular dynamics simulation expansion at Basel and Boston drug developers.
Several conditions sit outside the modeled scope, including quantum computing hardware breakthrough timelines, export control restrictions on GPU accelerators, and sovereign AI infrastructure funding allocation shifts. Forecasts assume continuation of current EU AI Act implementation trajectories and FDA validation pathway stability. Deviation in accelerator supply availability or cross-border data residency enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Reference Check Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Global Referral Software Market
Software & Services
Automated Testing Software Market
Software & Services
Software Licensing Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Movie Editing Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Attendance Tracking Software Market