
 Hypervisor Market | 2026-2036
Hypervisor Market Size, Share, and Industry Trends Forecast 2026-2036
Hypervisor Market Outlook
The capital-intensity divergence between proprietary stack vendors and open-source platform providers is unwinding competitive dynamics across the hypervisor landscape. VMware sustains premium positioning through deep integration with enterprise storage and networking fabrics. Red Hat leverages its upstream Linux control to shape KVM development roadmaps and capture public-cloud-adjacent workloads. Huawei anchors Asian infrastructure buildouts with hardware-software co-designed virtualization stacks for telecom edge deployments.
A hypervisor is a thin software layer that abstracts physical compute resources—CPU cores, memory blocks, storage controllers, and network interfaces—into multiple isolated virtual machines, each executing independent operating systems with dedicated resource quotas enforced through hardware privilege rings. Type 1 bare-metal hypervisors achieve sub-five-percent overhead by running directly on processor silicon, while Type 2 hosted variants rely on host operating system scheduling and incur higher latency penalties suitable for development environments rather than production loads. Hardware-assisted virtualization segments command the deepest margin pools as Intel VT-x and AMD-V extensions become mandatory for secure enclave provisioning, whereas OS-level virtualization through containers is displacing traditional hypervisors in stateless microservice workloads but remains structurally limited for multi-tenant legacy application hosting.
FCC guidelines on critical infrastructure cybersecurity and the EU Cybersecurity Act's certification frameworks for ICT products are reshaping procurement criteria for data center operators and cloud service providers. NIST SP 800-53 controls and ISO 27001 audit requirements further constrain vendor selection to platforms with validated secure boot chains and measured runtime integrity. Stakeholders must monitor whether emerging quantum-resistant encryption standards will force hypervisor rebuilds or create replacement windows for incumbent architectures.
Market Dynamics
Hardware-assisted virtualization is compressing the performance gap between bare-metal and containerized workloads, forcing incumbent vendors to rebuild their memory isolation architectures around encrypted enclaves and attestation protocols demanded by European data protection frameworks.
Growth Catalysts
- EU AI Act compliance mandates:Article 10 requirements for high-risk AI systems are accelerating procurement of hypervisors with hardware-backed isolation and audit logging across Frankfurt, Amsterdam, and Dublin data center clusters.
- Telecom edge virtualization:5G standalone core deployments are pulling Type 1 hypervisors into radio access network sites to host network functions with sub-10ms latency guarantees.
- Legacy infrastructure refresh cycles:German industrial manufacturers are replacing VMware estates with hybrid KVM-based stacks to reduce per-socket licensing exposure while maintaining SAP HANA certification.
Market Restraints
- Silicon supply concentration:Intel VT-x and AMD-V extension availability remains tethered to fab capacity at TSMC Arizona and Samsung Austin, creating procurement bottlenecks for encrypted memory features.
- Skill scarcity in kernel-level debugging:Enterprise IT organizations report 18-month average hiring timelines for engineers capable of troubleshooting nested page table faults in production environments.
- Container substitution pressure:Kubernetes-native workloads are displacing traditional VM-based orchestration for stateless microservices, compressing addressable volume in cloud-native application segments.
Strategic Opportunities
- India data center buildouts:The country's PLI scheme for IT hardware is attracting hyperscale investment in Noida and Chennai, creating greenfield demand for localized hypervisor distributions with BIS certification.
- Confidential computing convergence:Integration of AMD SEV-SNP with Intel TDX is opening attestation-as-a-service revenue streams for cloud providers serving financial services and healthcare verticals.
- Automotive software-defined vehicle architectures:Zonal E/E designs are embedding hypervisors for mixed-criticality consolidation, with German OEMs specifying ISO 26262-certified virtualization layers for domain controllers.
Industry Challenges
- Firmware supply chain attestation:NIST SP 800-193 requirements for measured boot are forcing vendors to rebuild update pipelines around cryptographic provenance tracking for UEFI and BMC components.
- Cross-platform migration complexity:Enterprise IT teams face six-to-nine-month project timelines to revalidate storage multipath drivers and network SR-IOV configurations when switching hypervisor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypervisor Market |
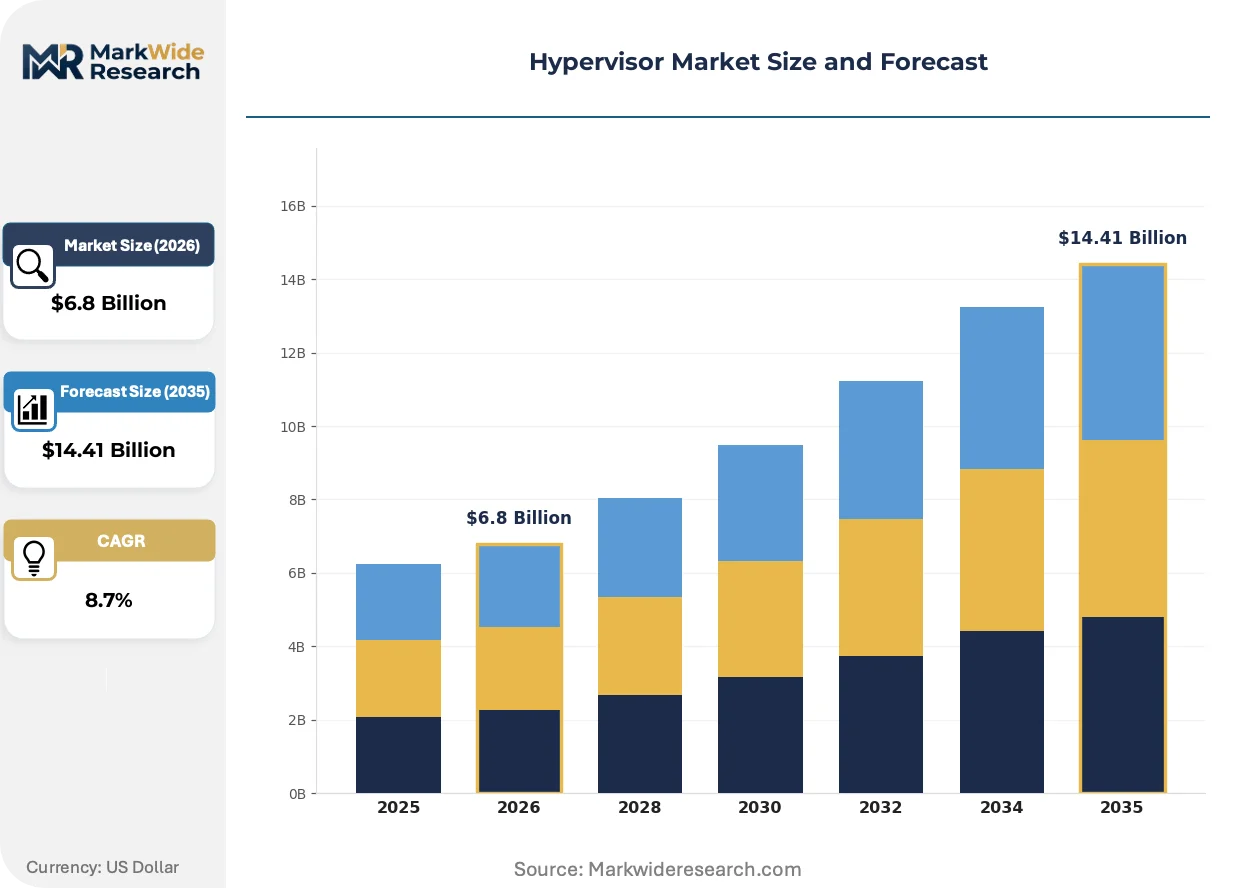
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Type 1 (Bare Metal), Type 2 (Hosted), Hybrid, Embedded Technology: Hardware-Assisted Virtualization, Full Virtualization, Paravirtualization, OS-Level Virtualization Application: Server Consolidation, Desktop Virtualization, Cloud Computing, Network Virtualization End User: Data Centers, Cloud Service Providers, Enterprise IT, Telecommunication Operators |
| Companies Covered | Red Hat, Huawei, VMware, Proxmox, SUSE, Microsoft, Oracle, Parallels, Citrix Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypervisor Market Strategic Shifts
Virtualization architectures are fragmenting along workload-specific optimization paths, with confidential computing, embedded automotive stacks, and cloud-native abstractions diverging from the general-purpose hypervisor designs that dominated the previous decade.
Confidential computing extensions are miniaturizing the trusted computing base for multi-tenant environments. Cloud providers in Frankfurt and Singapore are deploying AMD SEV-SNP and Intel TDX-enabled instances to host regulated workloads. This technology is miniaturizing the attack surface for memory-extraction exploits, compressing insurance premiums for cyber coverage in financial services deployments.
The EU Cybersecurity Act's Common Criteria certification framework is mandating formal verification for hypervisors processing personal data. Vendors must submit to EAL4+ evaluation at French ANSSI or German BSI labs to qualify for public sector procurement. European health data spaces and digital identity wallets are driving the deepest compliance investments, with French hospital systems already specifying certified stacks for electronic patient record hosting.
Automotive procurement patterns are unbundling perpetual licenses in favor of per-vehicle royalty models. Tier 1 suppliers including Bosch and Continental are negotiating consumption-based terms for hypervisor software integrated into zonal gateway controllers. This shift is most pronounced in German premium OEM programs, where software-defined vehicle roadmaps require decade-long supply agreements with usage-scaled pricing mechanics.
Hypervisor Market Segmentation
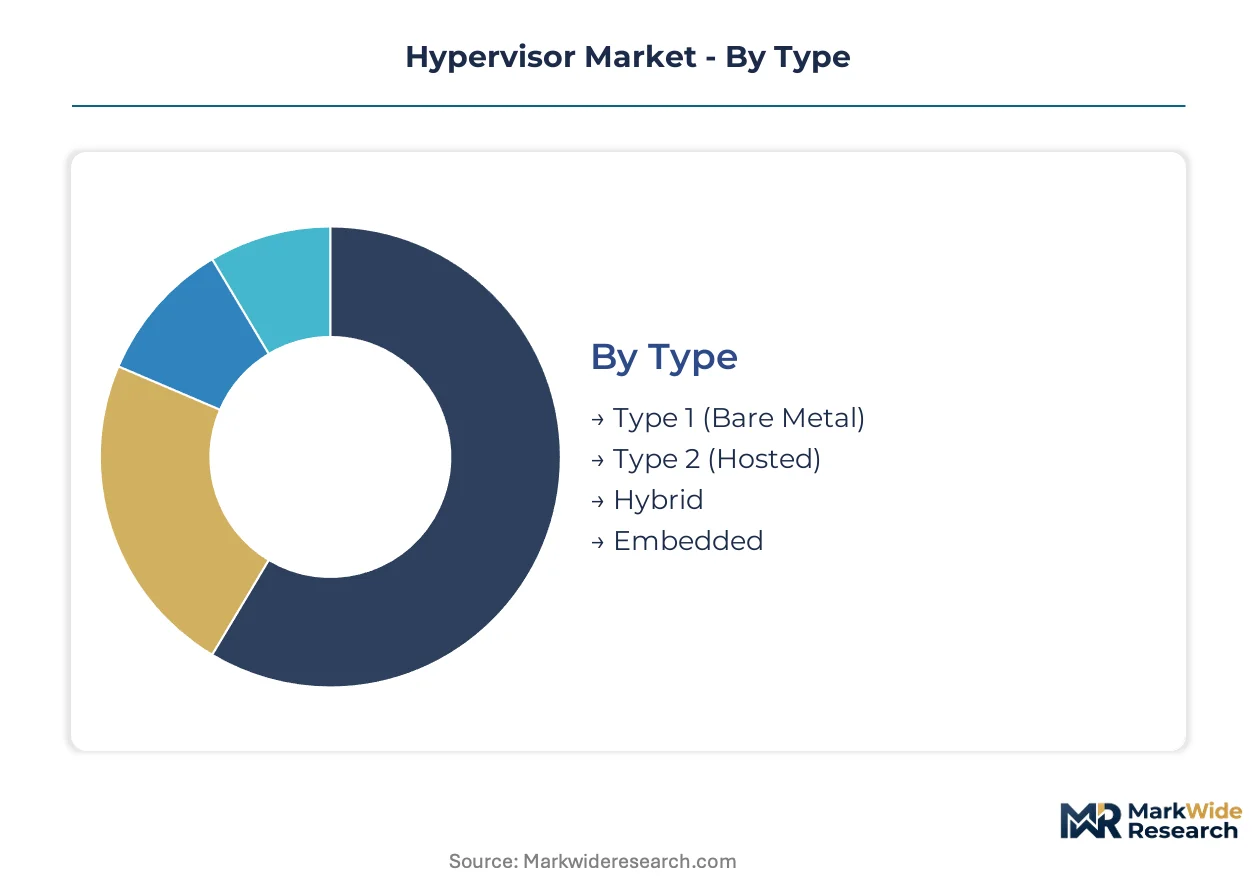
Hypervisor procurement patterns diverge sharply across deployment contexts, with regulatory frameworks in Frankfurt, Dublin, and Singapore dictating isolation requirements that reshape segment priorities. Understanding these fault lines reveals where margin pools concentrate and which technical specifications command premium positioning.
Type:
EU AI Act Article 10 mandates for high-risk AI systems are driving hardware-backed isolation requirements that favor bare-metal architectures over hosted alternatives in European data center clusters.
- Type 1 (Bare Metal):Direct execution on processor silicon eliminates host OS scheduling overhead, achieving sub-five-percent performance penalty. Frankfurt and Amsterdam cloud providers are expanding deployments to meet GDPR-compliant encrypted memory isolation requirements for financial services workloads.
- Type 2 (Hosted):Relies on underlying host operating system for resource scheduling, incurring latency penalties acceptable only in development and testing environments. German industrial manufacturers retain limited instances for legacy application compatibility during hybrid migration phases.
- Hybrid:Combines bare-metal performance for production workloads with hosted flexibility for non-critical functions, enabling gradual infrastructure transitions without forklift replacements.
- Embedded:Purpose-built for constrained environments including automotive zonal controllers and telecom edge nodes, where ISO 26262 and 5G latency specifications dictate deterministic resource partitioning.
Established volume favors Type 1; emerging adoption favors Embedded.
Technology:
Cost tier differentiation separates mandatory hardware extensions from legacy software-only approaches, with encrypted enclave capabilities commanding substantial procurement premiums.
- Hardware-Assisted Virtualization:Intel VT-x and AMD-V extensions enable privileged instruction interception at silicon level, forming the foundation for confidential computing deployments. Cloud providers in Singapore and Frankfurt are standardizing on AMD SEV-SNP and Intel TDX for regulated healthcare and financial workloads.
- Full Virtualization:Binary translation and trap-and-emulate techniques allow unmodified guest operating systems, though performance overhead limits deployment to legacy compatibility scenarios rather than performance-sensitive production.
- Paravirtualization:Requires guest OS modification to use hypercall interfaces, trading compatibility for efficiency in specialized high-performance computing environments.
- OS-Level Virtualization:Container-based isolation through shared kernel architectures displaces traditional hypervisors in stateless microservice workloads, though multi-tenant legacy hosting remains structurally out of reach.
Procurement budgets concentrate on Hardware-Assisted; container substitution pressure accelerates OS-Level expansion.
Application:
Customer type maturity determines whether deployments prioritize density optimization, end-user experience, or network function latency.
- Server Consolidation:Workload aggregation onto shared physical infrastructure remains the foundational use case, with German automotive suppliers deploying hybrid stacks to reduce per-socket licensing exposure while maintaining SAP HANA certification.
- Desktop Virtualization:Centralized desktop delivery to thin clients demands graphics acceleration and low-latency protocol optimization, finding traction in healthcare and financial services with strict data residency requirements.
- Cloud Computing:Multi-tenant resource pooling with API-driven orchestration represents the dominant growth vector, though Kubernetes-native workloads are compressing VM-based orchestration for stateless segments.
- Network Virtualization:5G standalone core deployments pull Type 1 hypervisors into radio access network sites to host network functions with sub-10ms latency guarantees for telecom operators.
Cloud Computing captures the steepest expansion trajectory; Server Consolidation retains the largest installed base.
End User:
Supply concentration among Intel and AMD fab capacity creates procurement bottlenecks that affect each buyer category differently based on volume leverage and certification urgency.
- Data Centers:Colocation and enterprise facilities prioritize density and energy efficiency, with NIST SP 800-53 controls constraining vendor selection to platforms with validated secure boot chains.
- Cloud Service Providers:Hyperscale operators drive roadmap influence through direct silicon vendor collaboration, with India PLI scheme investments in Noida and Chennai creating localized demand for BIS-certified distributions.
- Enterprise IT:German industrial manufacturers face six-to-nine-month revalidation timelines when switching platforms, creating stickiness around incumbent storage multipath and SR-IOV configurations.
- Telecommunication Operators:5G edge virtualization requirements are pulling Type 1 deployments into distributed radio access network sites with strict latency and reliability specifications.
Cloud Service Providers dictate technology roadmaps; Telecommunication Operators are expanding most quickly at the network edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate the lowest price elasticity, absorbing premium licensing for certified stacks, while Indian and Brazilian procurement teams prioritize per-socket cost reduction in greenfield deployments.
United States
FCC cybersecurity guidelines for critical infrastructure and NIST SP 800-53 controls drive hyperscale operators toward validated secure boot chains. Cloud providers in Northern Virginia and Oregon data center clusters negotiate directly with Intel and AMD for silicon roadmaps. The SEC's disclosure rules for material cybersecurity incidents are accelerating hardware-assisted virtualization procurement.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria refresh VMware estates with hybrid KVM stacks to reduce licensing exposure while maintaining SAP HANA certification. BSI evaluation requirements under the EU Cybersecurity Act mandate EAL4+ certification for public sector procurement. Frankfurt's financial services cluster specifies AMD SEV-SNP and Intel TDX for confidential computing deployments.
India
The PLI scheme for IT hardware attracts hyperscale investment in Noida and Chennai, creating localized demand for BIS-certified hypervisor distributions. TRAI's data localization recommendations push cloud providers toward domestic infrastructure buildouts. Karnataka's Bangalore cluster hosts engineering centers optimizing open-source stacks for tropical data center thermal constraints.
Singapore
Monetary Authority of Singapore technology risk management guidelines enforce hardware-backed isolation for financial workloads hosted in Marina Bay and Jurong data centers. The country's cybersecurity certification scheme aligns with Common Criteria frameworks, privileging vendors with ANSSI or BSI lab validation. Temasek-backed infrastructure funds are consolidating regional cloud capacity.
Japan
METI's data free flow with trust initiatives shape procurement criteria for hybrid cloud architectures serving automotive and electronics manufacturers. Tokyo and Osaka financial institutions specify FISC-compliant virtualization layers for core banking system consolidation. Domestic semiconductor equipment makers are embedding hypervisors into lithography control systems.
Hypervisor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the hypervisor landscape. Proprietary stack vendors sustain premium positioning through deep storage and networking fabric integration, while open-source platform providers capture public-cloud-adjacent workloads through upstream development influence. The market structure separates into three strategic archetypes: enterprise incumbents with certification depth, Linux-native distributors with kernel control, and hardware-software co-design specialists. Dominant competitive moves include strategic partnerships with silicon vendors and geographic expansion through localized certification programs.
Among enterprise virtualization incumbents, VMware and Citrix Systems occupy positions emphasizing deep integration with legacy infrastructure, while Red Hat and SUSE exemplify the open-source archetype leveraging upstream Linux control to shape KVM roadmaps. Huawei anchors Asian infrastructure buildouts as a hardware-software co-design specialist.
| Leading Market Players |
|---|
| Red Hat |
| Huawei |
| VMware |
| Proxmox |
| SUSE |
| Microsoft |
| Oracle |
| Parallels |
| Citrix Systems |
| Others |
Value Chain & Pricing Dynamics
Per-socket licensing contracts with multi-year enterprise agreements lock in supply access for certified hypervisor stacks while anchoring price visibility against volatile silicon roadmaps. German automotive manufacturers and Frankfurt financial institutions absorb premium positioning for EAL4+-validated distributions, whereas Indian hyperscale operators negotiating BIS-certified localized editions extract per-unit concessions through volume scale.
Pricing Analysis
Support and professional services revenue tiers now drive lifetime value for hypervisor vendors, with annual maintenance contracts representing the dominant pricing model across enterprise deployments. Price differentiation hinges on Common Criteria certification grade and hardware-assisted virtualization feature depth, with AMD SEV-SNP and Intel TDX-enabled stacks commanding substantial premiums. Cost compression in standard-tier licensing is intensifying because open-source KVM distributions are displacing proprietary sockets in German industrial refresh cycles. Cloud service providers exhibit the lowest price sensitivity, absorbing premium confidential computing instances, while Brazilian and Indian greenfield procurement teams prioritize per-socket cost reduction.
Supply Chain Analysis
Just-in-time silicon procurement preferences dominate hypervisor hardware sourcing, with strategic stockpiles reserved for encrypted memory controller components facing extended fab queues. Supply concentrates in Taiwan, the United States, and South Korea, where TSMC Arizona and Samsung Austin output feeds Intel and AMD extension availability. The stack draws from x86 processor silicon, encrypted memory modules, and UEFI firmware as critical inputs. Single-source vulnerability in EUV lithography capacity creates structural risk for hardware-assisted virtualization feature rollouts. Distribution runs through direct silicon vendor partnerships and regional systems integrators serving certified deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EAL4+ certification requirements and six-to-nine-month migration revalidation timelines create structural switching costs that protect incumbent positions.
For Market Incumbents: Secure certification depth in European health data spaces and automotive ISO 26262 programs to defend against open-source substitution pressure. Deepen upstream control over silicon vendor roadmaps through confidential computing co-development agreements. Channel control through localized systems integrator networks in India and Singapore reinforces sticky enterprise relationships.
For New Entrants and Emerging Players: Anchor in Indian PLI scheme data center buildouts where BIS certification creates a localized procurement window with limited incumbent presence. Target telecom edge virtualization for 5G standalone core deployments as the most penetrable segment, with sub-10ms latency specifications favoring purpose-built Type 1 stacks over generalist alternatives. A consumption-based per-vehicle royalty model for automotive zonal controllers offers viable go-to-market differentiation.
For Investors and Strategic Acquirers: Kernel-level engineering specialists with upstream Linux influence represent the priority acquisition archetype, given eighteen-month hiring timelines for nested page table debugging expertise. Long-term viability hinges on confidential computing convergence and quantum-resistant encryption standard readiness. Revision becomes warranted when AMD SEV-SNP and Intel TDX attestation-as-a-service revenue crosses materiality thresholds in financial services verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Platform Integration | AMD SEV-SNP and Intel TDX convergence opens attestation revenue streams for regulated healthcare workloads. |
| Automotive Certification Investment | ISO 26262 validation for zonal E/E architectures secures decade-long German OEM supply agreements. |
| Localized Distribution Expansion | BIS-certified Indian editions capture PLI scheme hyperscale investment in Noida and Chennai clusters. |
| Silicon Vendor Strategic Partnership | Direct Intel and AMD collaboration ensures encrypted memory feature priority allocation amid fab constraints. |
| Open-Source Platform Acquisition | Upstream KVM control shapes public-cloud-adjacent workload capture against proprietary stack incumbents. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with virtualization platform engineers, data center procurement officers, cloud infrastructure architects, and automotive embedded systems leads; and secondary validation through SEC hyperscaler capex disclosures, ETSI NFV specifications, NIST SP 800-53 documentation, and Common Criteria certification registries. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against silicon vendor shipment data anchored the market sizing framework.
Across the analysis window, the forecasting framework modeled segmentation dimensions including hypervisor type, virtualization technology tier, application workload, and end-user deployment context. CAGRs were derived through regression analysis of historical infrastructure refresh cycles and forward projection of regulatory compliance mandates. Confidential computing adoption curves and 5G edge virtualization deployment timelines served as industry-specific forecast inputs.
Material uncertainties — quantum-resistant encryption standard finalization, EU AI Act enforcement interpretation, and TSMC Arizona capacity allocation — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and silicon feature availability. Revision becomes warranted when encrypted memory isolation requirements cross adoption thresholds in European public sector procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Journal App Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Productivity Software Publishing Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Sales Coaching Software Market
Software & Services
Lawn Care Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Global Brand Management Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Interior Design Software Market
Software & Services
Global PEO Software Market
Software & Services
Streaming Server Software Market
Software & Services
App Building Software Market
Software & Services
Ad Creation Software Market
Software & Services
Legal Practice Management Software Market