
 Global Trade Promotion Management Software Market | 2026-2036
Global Trade Promotion Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trade Promotion Management Software Market Foresight
API-first microservices architecture is broadening the functional perimeter of trade promotion platforms beyond traditional rebate management. SAP leverages deep ERP integration to anchor enterprise deployments across multinational consumer goods networks. Oracle sustains competitive pressure through database-layer connectivity that unifies trade spend with financial planning systems.
Trade promotion management software comprises cloud-native and on-premise applications that automate planning, execution, and reconciliation of manufacturer-to-retailer incentive programs, typically processing volumetric thresholds, scan-back validations, and lump-sum funding agreements through configurable workflow engines. The primary commercial purpose centers on reducing phantom trade spend leakage while improving return-on-investment visibility across fragmented retail channels. Cloud-based deployment leads solution delivery due to lower total cost of ownership and faster implementation cycles, though on-premise retains footholds among manufacturers with restrictive data sovereignty requirements. Trade spend optimization commands disproportionate margin attention as algorithms replace manual spreadsheet allocation across multi-retailer portfolios.
FDA scrutiny of pharmaceutical marketing expenditures shapes compliance modules within trade promotion suites serving drug manufacturers, while EU GDPR constraints force cloud providers to localize data residency for European consumer goods clients. China's SAMR enforcement against unfair trade practices is prompting multinational brands to audit promotion claims through auditable software trails rather than offline documentation. Stakeholders must evaluate whether their current platforms can absorb emerging AI-driven demand forecasting without fragmenting trade spend accountability across separate systems.
Market Dynamics
Cloud migration is compressing implementation cycles for trade promotion platforms while API-first architectures dissolve functional boundaries between rebate management, demand forecasting, and financial planning systems.
Growth Catalysts
- EU GDPR data residency mandates:Cloud providers localize European infrastructure, accelerating replacement of legacy on-premise installations among consumer goods manufacturers with cross-border retail networks.
- Consumer packaged goods digitization:Manufacturers automate volumetric threshold processing and scan-back validations to reduce phantom trade spend leakage across fragmented retail channels.
- China SAMR enforcement:Multinational brands adopt auditable software trails for promotion claims documentation rather than offline record-keeping, driving compliance module adoption.
Market Restraints
- Data sovereignty requirements:On-premise retention among pharmaceutical manufacturers with FDA-mandated audit trails limits pure-cloud deployment penetration in drug marketing expenditure tracking.
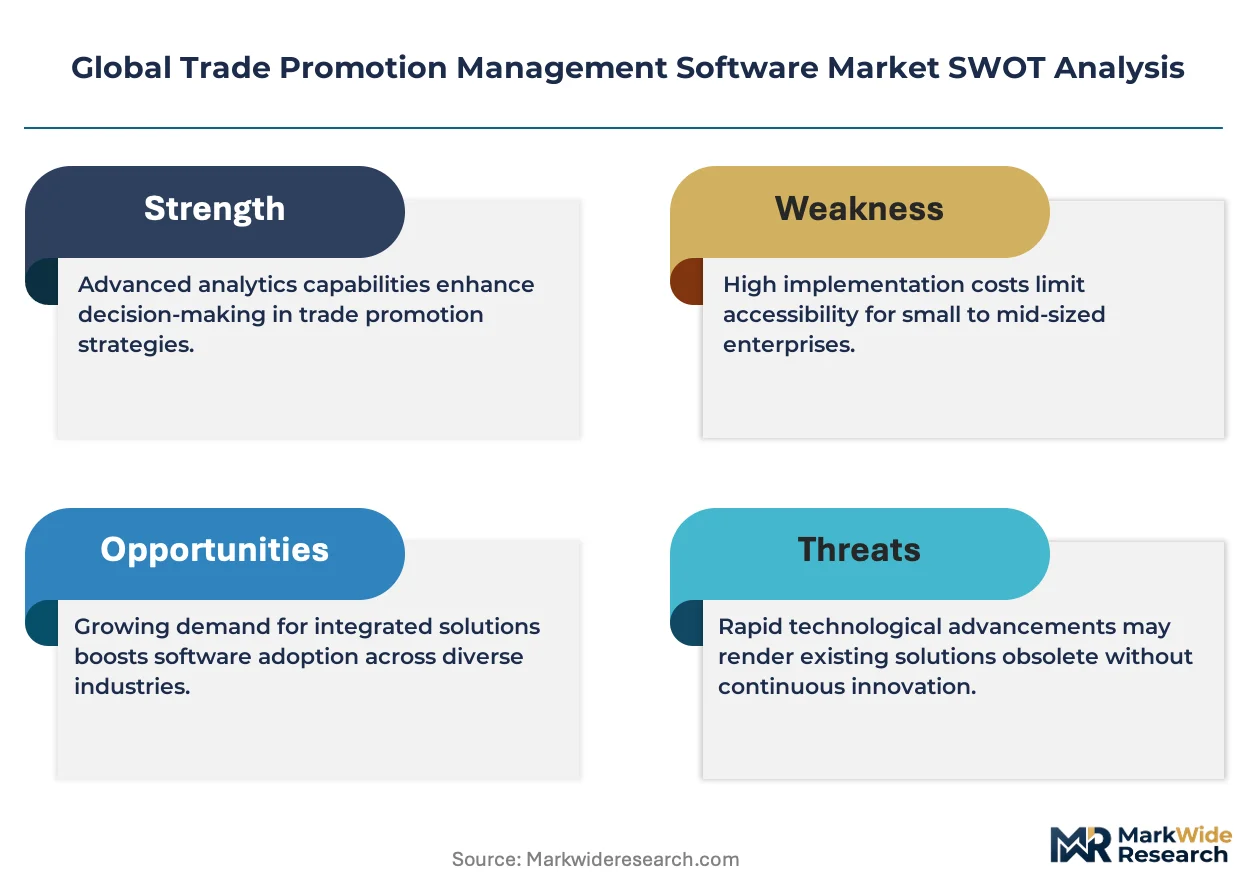
- Integration complexity:ERP-layer connectivity demands from SAP and Oracle environments extend implementation timelines and require specialized technical resources.
- Skill scarcity:Shortage of professionals combining trade spend domain expertise with cloud-native architecture proficiency constrains enterprise rollout velocity.
Strategic Opportunities
- AI-driven demand forecasting convergence:Machine learning algorithms embedded within promotion platforms enable real-time ROI optimization without fragmenting accountability across separate systems.
- India PLI scheme tailwinds:Domestic manufacturing incentives expand the addressable base of consumer goods producers requiring trade spend automation for modern retail penetration.
- Microservices architecture:Modular deployment allows mid-market manufacturers to adopt specific capabilities—claims processing, deduction management—without full-suite commitment.
Industry Challenges
- Legacy system coexistence:Hybrid environments combining decades-old financial systems with cloud-native promotion engines create reconciliation friction and data latency.
- Cross-functional alignment:Sales, finance, and supply chain teams maintain conflicting KPI definitions for trade spend effectiveness, complicating unified platform adoption.
- Algorithmic transparency requirements:Procurement teams demand explainable AI for promotion optimization decisions, slowing black-box model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trade Promotion Management Software Market |
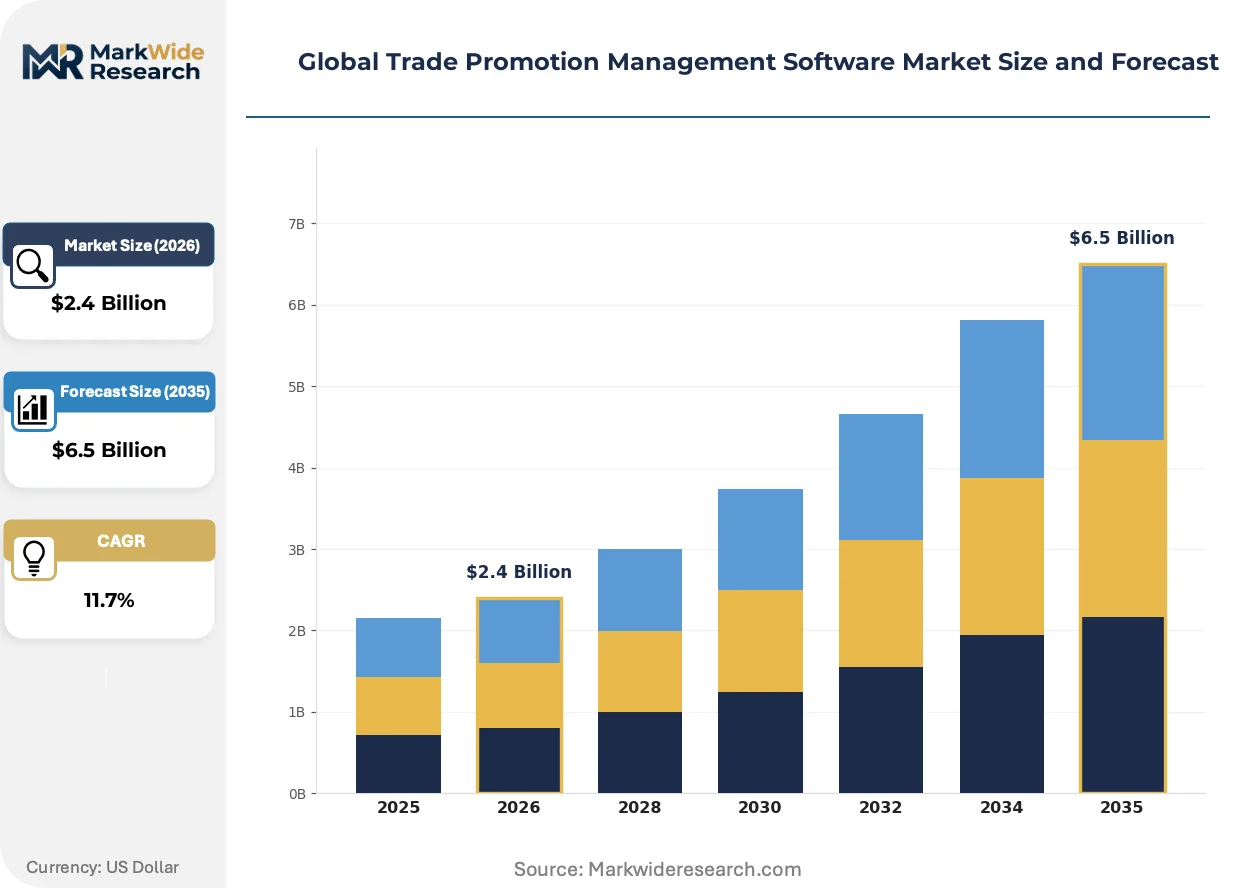
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Campaign Planning, Budget Management, Trade Spend Optimization, Performance Analysis, Claims Management Use Case: Consumer Goods, Electronics Distribution, Telecommunications Services, Food & Beverages, Pharmaceutical Marketing Customer Type: Manufacturers, Distributors, Retail Chains, Wholesalers, Logistics Providers |
| Companies Covered | Visualfabriq, Infor, SAP, Vividly, Anaplan, Oracle, Aforza, XTEL, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trade Promotion Management Software Market Shifts & Advancements
Functional boundaries between trade promotion, demand planning, and financial systems are dissolving as microservices architectures enable modular capability assembly. Three forces are actively reshaping platform development and buyer expectations.
API-first microservices architecture is consolidating previously discrete software categories into unified workflow engines. Consumer packaged goods manufacturers deploy configurable modules for lump-sum funding agreements alongside rebate management without standalone systems. This compression reduces vendor count and integration overhead while accelerating implementation timelines.
EU AI Act risk classification requirements are reshaping algorithmic feature roadmaps. Promotion optimization tools incorporating machine learning must demonstrate human oversight mechanisms and decision traceability. Pharmaceutical manufacturers with FDA-regulated marketing expenditures face compounded compliance layers, driving demand for built-in audit documentation and model governance frameworks.
Buyer concentration among consolidated retail networks is shifting negotiation leverage toward data-sharing requirements. Walmart, Carrefour, and JD.com demand granular promotion performance visibility from supplier software platforms. German and Chinese manufacturers are responding with embedded analytics modules that preempt retailer-specific reporting demands rather than reactive customization.
Global Trade Promotion Management Software Market Segmentation
Trade promotion management software segments reflect divergent technical architectures and commercial workflows across buyer ecosystems. Deployment models, solution depth, and customer scale determine platform configuration requirements and vendor selection criteria.
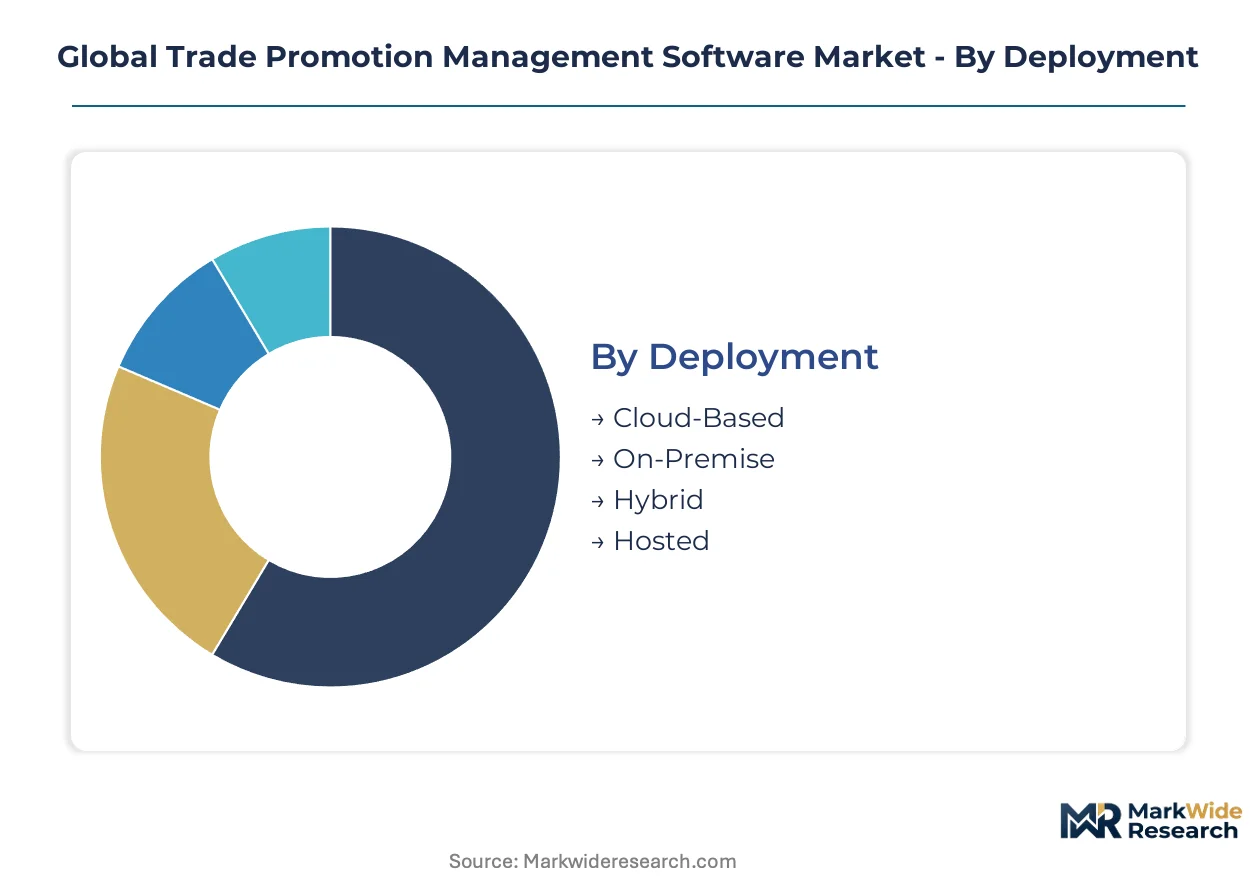
Deployment:
Cloud-native microservices architectures are displacing legacy infrastructure across enterprise software procurement decisions.
- Cloud-Based:Multi-tenant SaaS platforms with API-first integration layers dominate new implementations among consumer packaged goods manufacturers seeking reduced total cost of ownership. United States-based retailers with consolidated supplier networks are mandating cloud-native data exchange protocols for promotion performance visibility.
- On-Premise:Single-tenant installations with localized database layers persist among pharmaceutical manufacturers subject to FDA-mandated audit trail requirements for marketing expenditure documentation. Germany maintains significant on-premise retention due to GDPR data sovereignty constraints forcing domestic server localization.
- Hybrid:Split architectures with cloud-based analytics and on-premise transaction processing address manufacturers with mixed regulatory exposure across product lines.
- Hosted:Dedicated private cloud deployments managed by third-party infrastructure providers serve mid-market distributors lacking internal DevOps capabilities.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Solution Offering:
Functional module adoption correlates with trade spend complexity and retailer negotiation leverage.
- Trade Spend Optimization:Algorithmic allocation engines replacing spreadsheet-based volumetric threshold calculations command premium positioning among multinational consumer goods networks. China SAMR enforcement against unfair trade practices is accelerating adoption of auditable optimization trails in lieu of offline documentation.
- Claims Management:Automated scan-back validation and deduction reconciliation workflows reduce phantom spend leakage across fragmented retail channels. United States distributors with high transaction volumes prioritize this capability for cash flow protection.
- Campaign Planning:Configurable workflow engines for lump-sum funding agreement structuring serve manufacturers with seasonal promotion calendars.
- Budget Management:Real-time accrual tracking and cross-functional approval routing address finance teams seeking consolidated trade spend visibility.
- Performance Analysis:Embedded analytics modules preempting retailer-specific reporting demands from Walmart and Carrefour are gaining traction among German suppliers.
Deep functional adoption clusters around Trade Spend Optimization. Entry-level procurement concentrates in Campaign Planning.
Use Case:
Industry-specific compliance layers and channel structures shape solution customization requirements.
- Consumer Goods:Volumetric threshold processing and multi-retailer portfolio management dominate implementations among digitizing manufacturers. This segment is expanding most quickly as CPG producers automate legacy rebate management workflows.
- Pharmaceutical Marketing:FDA scrutiny of drug promotion expenditures necessitates built-in audit documentation and model governance frameworks for algorithmic optimization tools. Compliance module depth exceeds other verticals.
- Food & Beverages:Perishable inventory coordination with trade promotion calendars drives demand for supply chain-aligned planning modules.
- Electronics Distribution:High-velocity product cycles and channel price protection agreements require rapid promotion adjustment capabilities.
- Telecommunications Services:Subscription-based revenue models with hardware subsidy programs create unique accrual complexity for trade spend tracking.
Regulatory intensity peaks in Pharmaceutical Marketing. Volume scale concentrates in Consumer Goods.
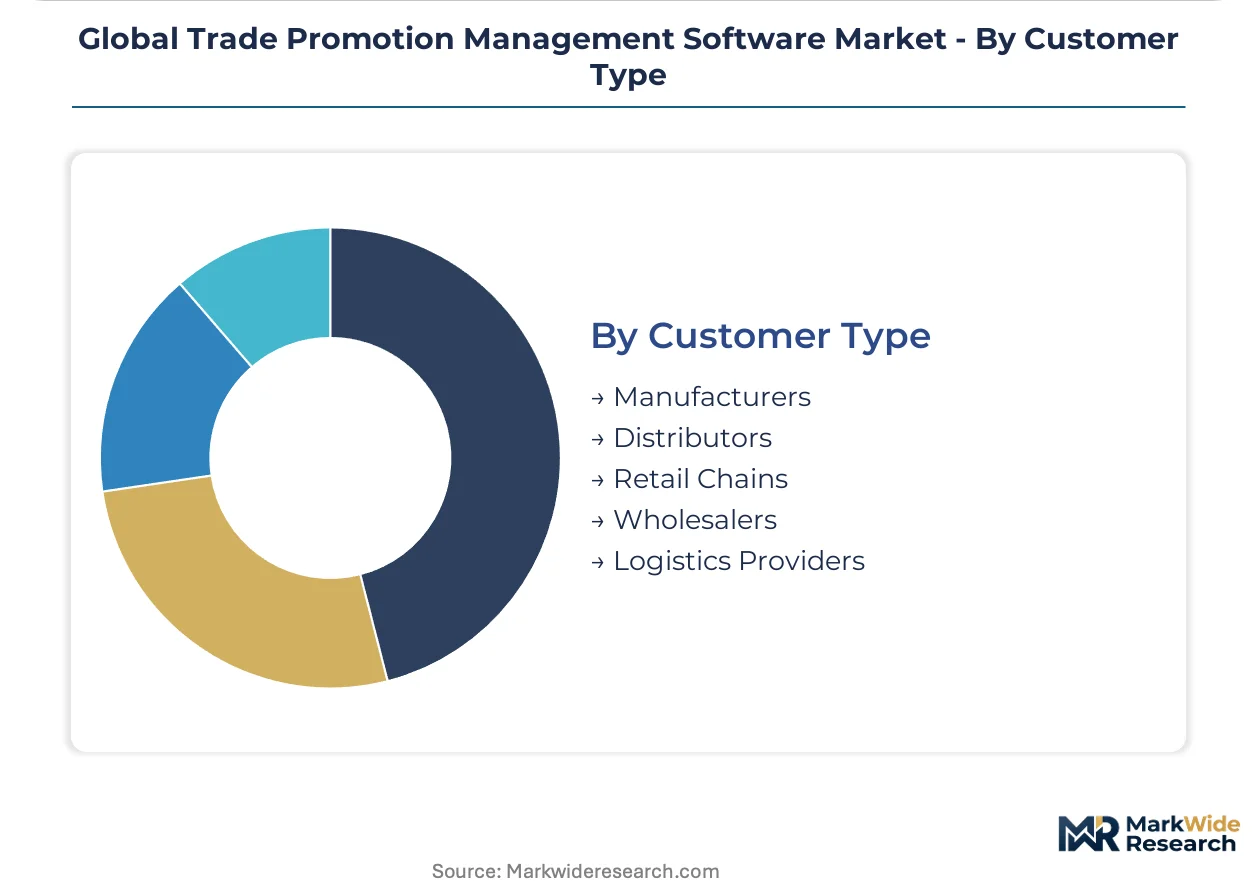
Customer Type:
Organizational scale and channel position determine platform sophistication thresholds and integration requirements.
- Manufacturers:Enterprise-grade deployments with ERP-layer connectivity from SAP and Oracle environments anchor the highest-value contracts. These buyers command the steepest expansion trajectory as direct-to-retailer digitization accelerates.
- Retail Chains:Reverse-demand for supplier data transparency is shifting negotiation leverage toward embedded analytics requirements. Walmart and JD.com specifications increasingly dictate platform feature roadmaps.
- Distributors:Mid-market buyers with multi-manufacturer portfolios prioritize claims processing automation over full-suite capabilities.
- Wholesalers:Inventory-positioning incentives with downstream retailers create unique promotion structure complexity.
- Logistics Providers:Emerging demand for trade spend visibility in omnichannel fulfillment networks is nascent but accelerating.
Platform maturity concentrates with Manufacturers. Feature innovation is driven by Retail Chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software procurement concentrates in markets where retail consolidation and channel complexity create acute trade spend visibility demands. The United States, Germany, and China anchor current investment flows. Regulatory enforcement patterns in each jurisdiction are accelerating cloud migration timelines.
United States
FDA scrutiny of pharmaceutical marketing expenditures drives compliance module adoption among drug manufacturers. Cloud-native deployments dominate as Walmart and other consolidated retailers mandate supplier data transparency protocols. Chicago and New York metro areas host dense clusters of consumer packaged goods headquarters digitizing rebate management workflows.
Germany
German manufacturers prioritize ERP-layer connectivity from SAP environments for trade spend optimization. GDPR data residency constraints force domestic server localization, sustaining hybrid deployment architectures. The Rhine-Ruhr industrial corridor anchors pharmaceutical and automotive supplier networks requiring auditable promotion documentation.
China
SAMR enforcement against unfair trade practices prompts multinational brands to adopt software-based audit trails. Domestic cloud providers localize infrastructure to meet data sovereignty requirements for European and American consumer goods clients. Shanghai and Shenzhen manufacturing hubs drive demand for real-time promotion ROI visibility across fragmented retail channels.
India
The PLI scheme expands the addressable base of domestic manufacturers requiring trade spend automation for modern retail penetration. BIS standards for software interoperability shape procurement specifications among mid-market consumer goods producers. Mumbai and Bangalore technology corridors host emerging SaaS adoption clusters among digitizing distributors.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for multinational consumer goods networks operating across EU and UK jurisdictions. London-based financial services expertise supports sophisticated trade spend analytics implementations. The Southeast England logistics corridor drives demand for claims processing automation among high-volume distributors.
Global Trade Promotion Management Software Market Competitive Landscape
ERP integration partnerships dominate the current landscape as vendors anchor enterprise deployments through financial system connectivity. The market structures around three tiers: multinational software conglomerates with deep ERP integration, specialized trade promotion pure-plays with configurable workflow engines, and emerging cloud-native entrants with API-first architectures. Consolidation pressure intensifies as buyers reduce vendor counts. Strategic archetypes include platform consolidators absorbing point solutions, vertical specialists serving pharmaceutical compliance requirements, and mid-market modular providers enabling capability-specific adoption.
Within the enterprise software tier, SAP and Oracle exemplify platform consolidation strategies through database-layer connectivity that unifies trade spend with financial planning systems. Salesforce occupies a position representing cloud-native entrants expanding functional boundaries through API-first microservices architecture. These three anchors illustrate divergent technical approaches to dissolving functional boundaries between promotion management, demand forecasting, and enterprise resource planning.
| Leading Market Players |
|---|
| Visualfabriq |
| Infor |
| SAP |
| Vividly |
| Anaplan |
| Oracle |
| Aforza |
| XTEL |
| Salesforce |
| Others |
Supply & Pricing Matrix
Walmart's supplier data transparency mandates are forcing cloud-native platform investments that compress implementation margins while elevating compliance costs for non-compliant vendors. This buyer-driven specification shift rewards established providers with pre-certified architectures and erodes price competitiveness of legacy on-premise installations.
Pricing Analysis
Volume-based SaaS subscriptions anchor the mid-market while enterprise ERP-integrated deployments command premium positioning. Price differentiation rests on integration complexity and audit-grade compliance certification, with FDA-validated pharmaceutical modules carrying the steepest premiums. Cost compression in standard cloud tiers is intensifying as hyperscaler infrastructure commoditizes base compute resources. Mid-market distributors exhibit highest price sensitivity, whereas multinational consumer goods networks prioritize total cost of ownership over license fees.
Supply Chain Analysis
China's data localization requirements and India's PLI domestic-content mandates are reshaping cloud infrastructure sourcing for Asia-Pacific deployments. Software development capacity concentrates in the United States, India, and Germany, with implementation services drawing from specialized partner networks in each jurisdiction. Single-source vulnerability sits with hyperscaler infrastructure dependencies, particularly for EU GDPR-compliant hosting. Distribution runs through direct enterprise sales teams supplemented by systems integrator channels for ERP-layer deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Trade Promotion Management Software Market functions as a cost-of-compliance arena where EU AI Act algorithmic governance requirements erect substantial barrier-to-entry moats for audit-capable incumbents.
For Market Incumbents: Anchor enterprise retention through SAP and Oracle ERP-layer connectivity that embeds trade spend workflows into financial planning systems. Deepen compliance module investment to exploit FDA marketing expenditure scrutiny and EU AI Act risk classification mandates. Defensive consolidation of mid-market workflow specialists will preempt modular entrants from assembling full-suite alternatives. For New Entrants and Emerging Players: The price-point gap between hyperscaler-backed economy SaaS and SAP-anchored premium enterprise deployments creates viable white-space for mid-market modular providers. India's PLI-expanding domestic manufacturer base offers the most penetrable geography, with BIS interoperability standards lowering integration barriers. A microservices go-to-market targeting claims-processing automation specifically avoids full-suite competitive headwinds. For Investors and Strategic Acquirers: The window for entry favors cloud-native platforms with pre-built retailer data-exchange protocols. Long-term viability hinges on AI-driven demand forecasting convergence without fragmenting trade spend accountability. Acquisition targets should demonstrate embedded analytics modules preempting Walmart and JD.com specifications. The signal to watch is retailer-mandated API standardization accelerating vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-layer connectivity from SAP environments anchors multinational consumer goods deployments. |
| Compliance Module Development | FDA audit trail capabilities differentiate pharmaceutical marketing expenditure tracking solutions. |
| Acquisition of Specialist Firm | Claims processing pure-plays fill capability gaps in mid-market modular portfolios. |
| Geographic Expansion | India PLI scheme tailwinds expand addressable base for domestic manufacturer automation. |
| Strategic Partnership | Hyperscaler alliances localize GDPR-compliant infrastructure for EU data residency mandates. |
Research Methodology
Independent corroboration across primary interviews, regulatory filing analysis, and enterprise procurement databases underwrites the qualitative findings in this study. Conversations with trade promotion software executives, consumer goods category managers, pharmaceutical regulatory affairs leads, and cloud infrastructure procurement officers supplied forward-looking implementation timelines. Secondary validation drew from FDA marketing expenditure enforcement records, EU AI Act risk classification guidance, SAMR audit trail requirements, and SAP Oracle partnership disclosure filings. Bottom-up deployment modeling triangulated against top-down enterprise software spend estimates.
Rate-of-change decomposition separated cloud migration velocity from AI feature adoption curves across the projection horizon. Segmentation modeling incorporated deployment architecture, solution depth tier, customer scale bracket, and vertical compliance intensity. CAGR derivation weighted historical replacement cycle data against retailer-mandated data transparency acceleration. Forecast inputs included hyperscaler infrastructure pricing trajectories and ERP integration backlog durations reported by systems integrator partners.
Underlying measurement precision varies by segment; cloud-based deployment forecasts carry tighter precision than hybrid architecture projections given visibility into SaaS provider revenue disclosures. Pharmaceutical compliance module adoption reflects assumptions about FDA enforcement continuity. China SAMR audit trail mandates and EU AI Act implementation timelines represent primary forecast revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Train Reservation Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Global Business Card Software Market
Software & Services
Programming Language Market
Software & Services
Global PPC Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Data Conversion Services Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Global Roofing Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Decision Support System (DSS) Software Market