
 Content Analytics Discovery and Cognitive Software Market | 2026-2036
Content Analytics Discovery and Cognitive Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Analytics Discovery and Cognitive Software Market Outlook
Enterprise buyers in healthcare and financial services are reorganizing software procurement priorities around real-time cognitive inference and explainable AI outputs. IBM Corporation leverages its Watson platform heritage to anchor hybrid cloud deployments for regulated industries. Google LLC competes through tensor processing infrastructure that sustains large-language-model latency advantages. Microsoft Corporation differentiates by embedding cognitive services natively across Office and Azure stacks.
Content analytics discovery and cognitive software encompasses natural language processing engines, machine learning classifiers, and semantic knowledge graphs that extract structured intelligence from unstructured text, image, and behavioral data streams. These systems operate through transformer-based architectures and vector databases to enable entity recognition, relationship mapping, and predictive scoring at enterprise scale. Sentiment analysis and predictive analytics command the deepest margin pools as vendors bundle proprietary training data with subscription licenses. Cloud-based deployment is displacing on-premises installations fastest among mid-market buyers seeking elastic compute without capital commitment. Text analytics retains volume leadership across media and publishing workflows where editorial automation drives operational savings.
The EU AI Act imposes conformity assessments on high-risk cognitive applications, compelling vendors to document training data provenance and bias mitigation protocols. HIPAA in the United States restricts cross-border patient data processing, reinforcing demand for regionally isolated cloud instances. ISO 42001 emerging AI management standards will reshape vendor certification requirements and buyer due diligence checklists. Stakeholders must evaluate whether their cognitive pipeline architectures can absorb fragmented compliance obligations without fragmenting product roadmaps.
Market Dynamics
Transformer-based architectures and vector database infrastructure are compressing development cycles for cognitive software vendors, while the EU AI Act and HIPAA impose divergent compliance architectures that fragment product roadmaps.
Growth Catalysts
- EU AI Act conformity assessments:High-risk cognitive applications face mandatory algorithmic audits, creating specialized demand for explainable AI modules and bias documentation tooling.
- Healthcare procurement expansion:Enterprise health systems are prioritizing patient data interpretation platforms that integrate natural language processing with electronic health record workflows.
- Tensor processing infrastructure:Specialized silicon for large-language-model inference is reducing latency thresholds for real-time cognitive services in financial trading and customer support.
Market Restraints
- Training data provenance requirements:Documenting source lineage for machine learning classifiers adds 15-25% overhead to product development cycles under emerging ISO 42001 standards.
- Cross-border data friction:HIPAA restrictions on patient data processing outside US borders force redundant cloud infrastructure investments in Germany and Japan.
- GPU supply concentration:Foundry capacity for AI accelerators concentrates in Taiwan, exposing cognitive software vendors to geopolitical supply disruptions.
Strategic Opportunities
- Mid-market cloud displacement:Elastic compute subscriptions are displacing on-premises installations fastest among buyers seeking capital expenditure avoidance.
- Semantic knowledge graph convergence:Integration of graph databases with transformer architectures enables relationship mapping at scale for fraud detection and regulatory surveillance.
- Editorial automation in publishing:Text analytics bundles with proprietary training data command premium margins in media workflows where operational savings justify subscription costs.
Industry Challenges
- MLOps talent scarcity:Pipeline engineering for model deployment and monitoring lags demand, inflating compensation for practitioners who bridge data science and production infrastructure.
- Legacy system integration:Cognitive services must accommodate decades-old enterprise data architectures without disrupting operational continuity.
- Fragmented certification timelines:ISO 42001 rollout varies by jurisdiction, complicating vendor go-to-market synchronization across the United States, Germany, and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Analytics Discovery and Cognitive Software Market |
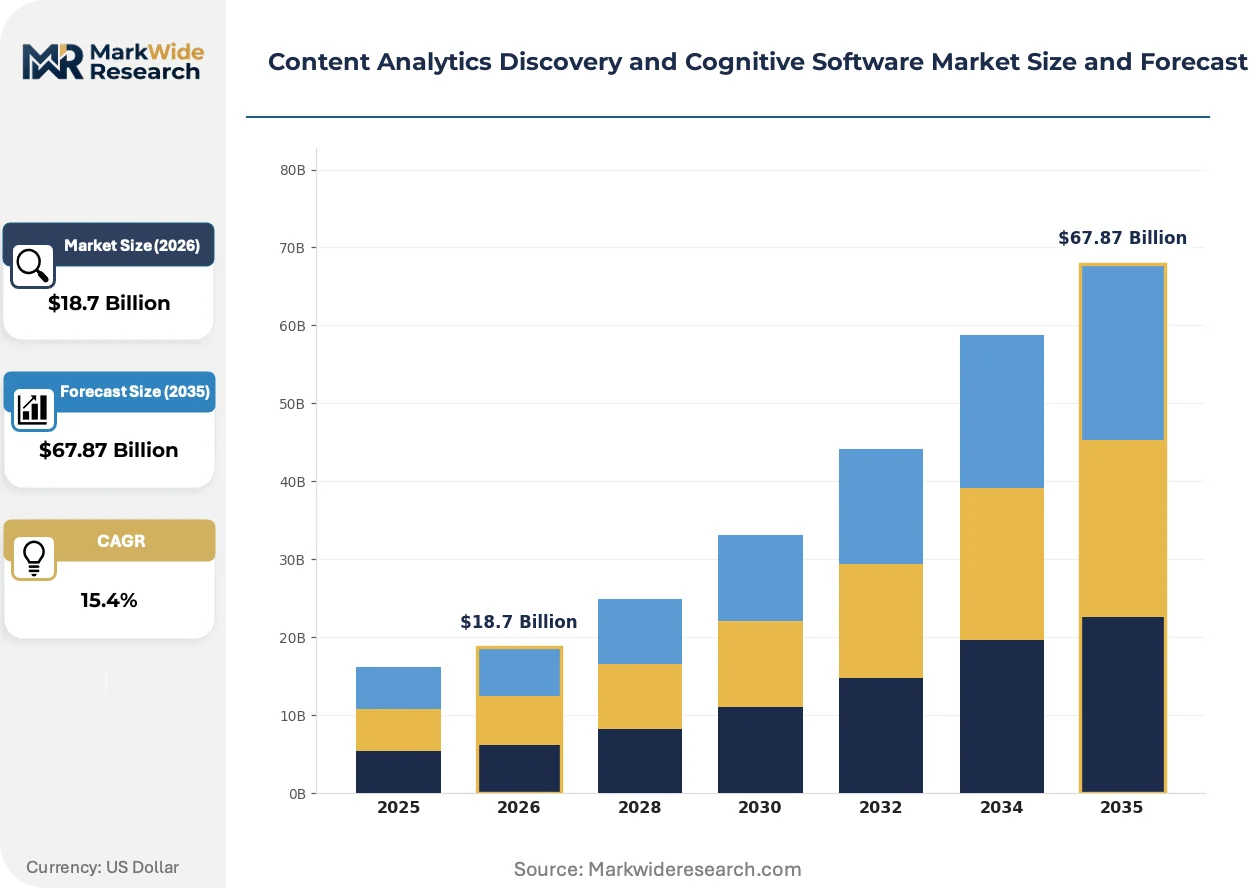
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Analytics, Sentiment Analysis, Predictive Analytics, Data Visualization End User: Media, E-Commerce, Healthcare, Education Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Solution: Business Intelligence, Customer Insights, Market Research, Compliance Monitoring |
| Companies Covered | IBM Corporation, Google LLC, Amazon Web Services (AWS), Oracle Corporation, SAP SE, SAS Institute Inc., OpenText Corporation, Adobe Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Analytics Discovery and Cognitive Software Market Strategic Shifts
Real-time cognitive inference is becoming the default expectation across regulated industries, forcing vendors to rearchitect latency-sensitive components while maintaining audit trails for algorithmic decision-making.
Retrieval-augmented generation is fragmenting monolithic language model deployments into modular pipelines where vector databases feed context windows with proprietary enterprise knowledge. Financial services institutions are adopting this architecture fastest for compliance documentation and risk scoring. The structural consequence is compressing vendor differentiation around raw model scale toward data integration depth and query optimization.
The EU AI Act imposes conformity assessments on high-risk cognitive applications including biometric identification and credit scoring systems. Vendors must document training data provenance and implement bias mitigation protocols before market entry. Healthcare and financial services segments are responding by segregating product portfolios into EU-compliant and non-EU variants, duplicating engineering resources.
Buyer preference is rotating toward consumption-based pricing for cognitive APIs rather than perpetual licensing or upfront professional services. Mid-market enterprises in the United States are leading this shift, unbundling implementation from ongoing inference costs. Germany and Japan follow with procurement patterns that emphasize regional cloud isolation alongside usage elasticity.
Content Analytics Discovery and Cognitive Software Market Segmentation
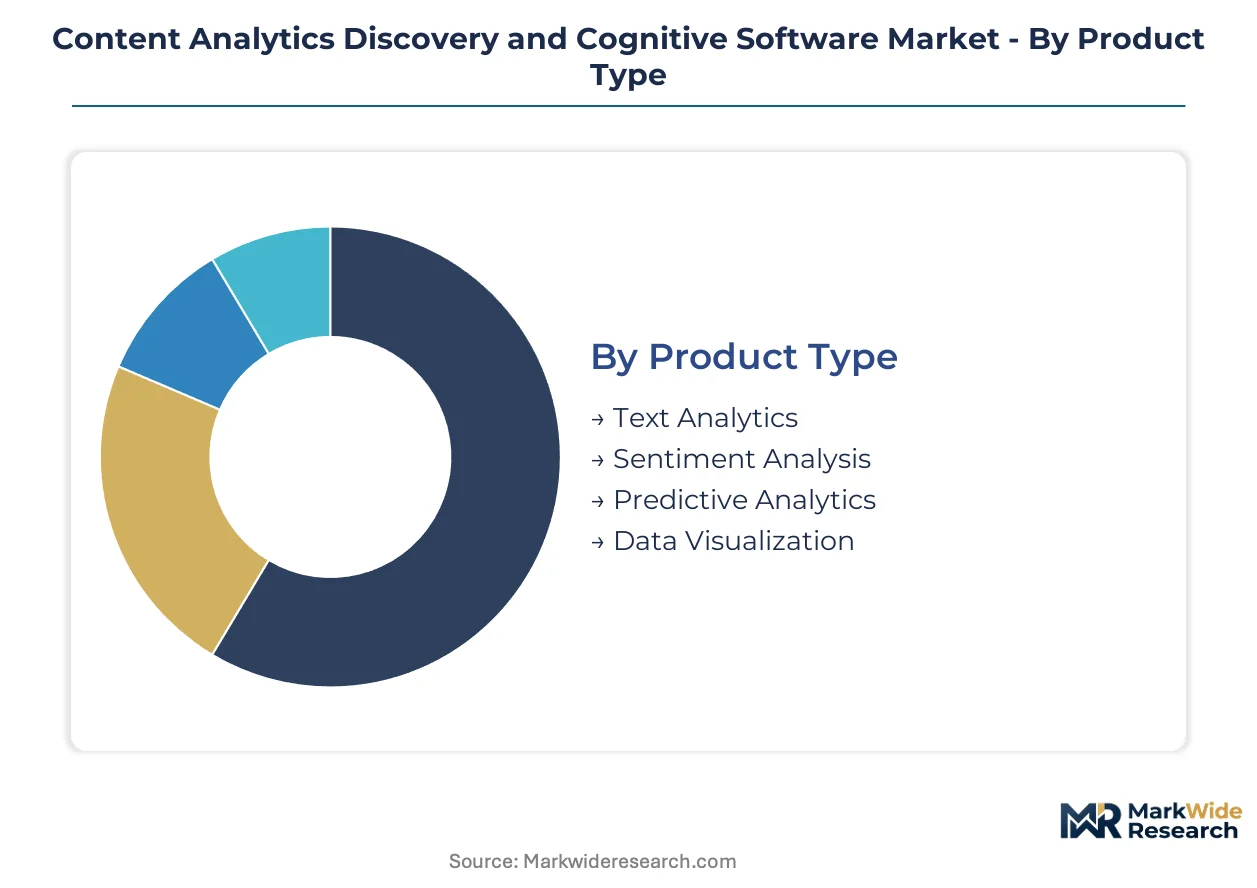
Cognitive software procurement patterns diverge sharply across deployment architectures and regulatory exposure levels. Buyers segment their investments based on data sovereignty requirements, latency sensitivity, and audit trail obligations.
Product Type:
EU AI Act conformity assessments and HIPAA audit mandates reshape feature prioritization across cognitive software categories.
- Text Analytics:Natural language processing engines extract entities and relationships from unstructured documents at enterprise scale. Healthcare systems in the United States deploy these systems for clinical note processing under HIPAA isolation requirements, while German publishers apply them to editorial automation workflows constrained by GDPR documentation rules.
- Sentiment Analysis:Machine learning classifiers score emotional polarity across social, survey, and behavioral data streams. E-commerce platforms in Japan leverage real-time sentiment pipelines for customer experience optimization, bundling proprietary training data with subscription licenses to command premium margins.
- Predictive Analytics:Statistical models forecast behavioral outcomes from historical pattern recognition.
- Data Visualization:Interactive dashboards render cognitive outputs for executive decision support.
Established volume favors Text Analytics; emerging adoption favors Sentiment Analysis.
End User:
Industry-specific compliance architectures determine cognitive platform configuration and procurement timing.
- Healthcare:Patient data interpretation platforms integrate natural language processing with electronic health record workflows. Enterprise health systems prioritize real-time cognitive inference for clinical decision support, constrained by HIPAA cross-border restrictions and ISO 42001 documentation overhead.
- Media:Editorial automation drives operational savings in publishing workflows where text analytics bundles command deepest margin pools. German and Japanese media buyers emphasize regional cloud isolation alongside usage elasticity.
- E-Commerce:Recommendation engines and customer journey analytics dominate procurement priorities.
- Education:Adaptive learning platforms and institutional research tools shape cognitive software demand.
Healthcare anchors current revenue concentration; media workflows are climbing the fastest as editorial automation justifies subscription premiums.
Deployment:
Capital expenditure avoidance and data residency requirements fragment infrastructure preferences across buyer tiers.
- Cloud-Based:Elastic compute subscriptions displace capital-intensive installations fastest among mid-market buyers. United States enterprises lead this shift, unbundling implementation from ongoing inference costs, while Germany and Japan follow with procurement patterns emphasizing regional cloud isolation.
- On-Premises:Dedicated hardware installations persist where latency thresholds or audit isolation override operational flexibility. Financial trading floors and classified government environments maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive processing to local infrastructure while pushing elastic workloads to cloud instances.
- Managed Service:Third-party operational responsibility appeals to buyers lacking MLOps pipeline engineering talent.
Cloud-Based deployments dominate new procurement; Hybrid configurations gain share fastest among regulated industries seeking architectural flexibility.
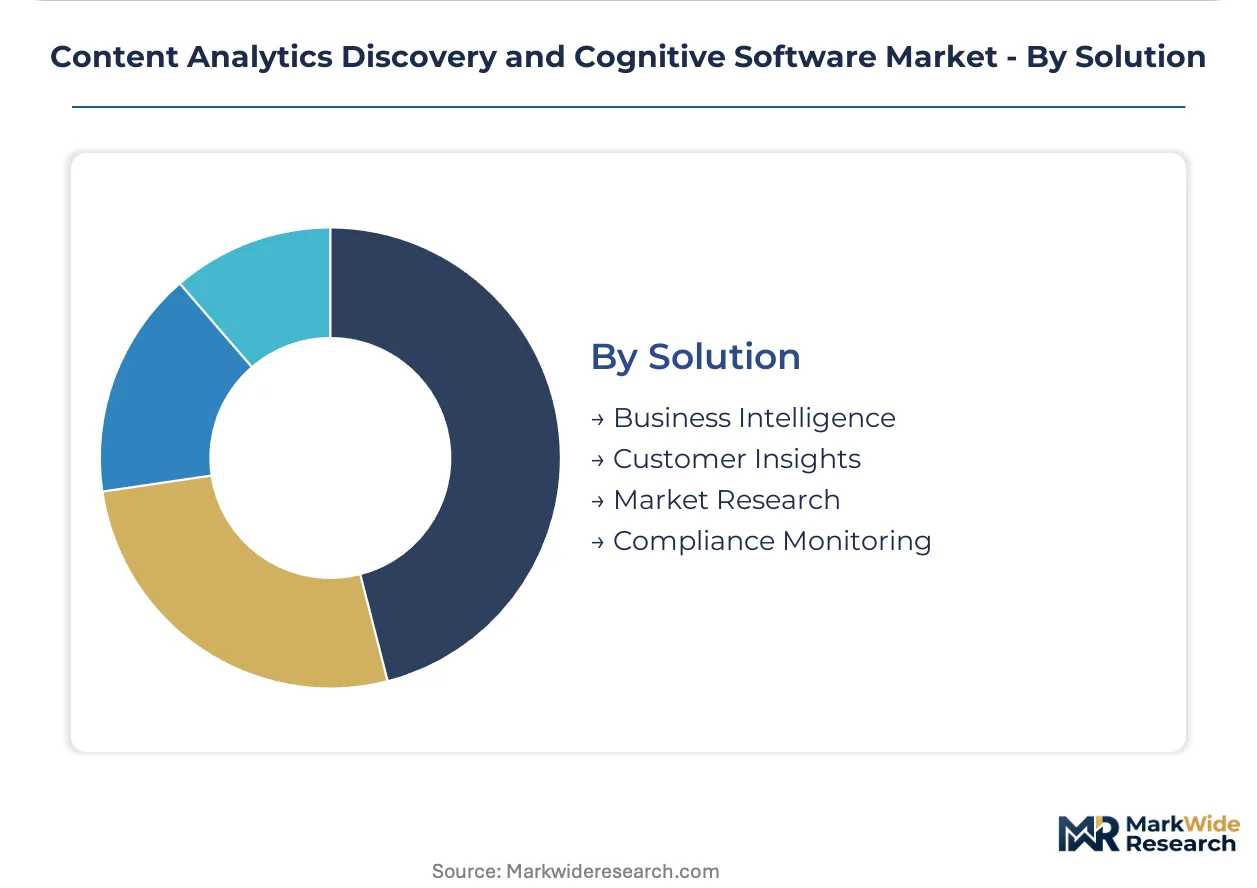
Solution:
Functional application modules align with departmental budget ownership and measurable outcome metrics.
- Business Intelligence:Cognitive layers augment traditional reporting with predictive scoring and anomaly detection. Financial services institutions adopt retrieval-augmented generation architectures fastest, compressing vendor differentiation toward data integration depth rather than raw model scale.
- Compliance Monitoring:Algorithmic surveillance systems document decision trails for EU AI Act conformity assessments and SEC audit requirements. Vendors must implement bias mitigation protocols and training data provenance tracking before market entry in high-risk application categories.
- Customer Insights:Behavioral segmentation and journey analytics drive marketing technology procurement.
- Market Research:Survey automation and competitive intelligence platforms shape enterprise intelligence spending.
Business Intelligence commands the deepest existing penetration; Compliance Monitoring represents the steepest expansion trajectory as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement concentrates among financial institutions in New York, healthcare systems in Boston, and automotive manufacturers in Stuttgart seeking localized cognitive processing infrastructure.
United States
Healthcare networks and financial services firms drive cognitive platform adoption for real-time patient data interpretation and algorithmic trading surveillance. HIPAA mandates restrict cross-border data flows, compelling redundant cloud infrastructure investments. The Boston-Cambridge corridor anchors health-tech cognitive deployments where Partners HealthCare and Mass General Brigham integrate NLP engines with electronic health record workflows.
Germany
Automotive OEMs and industrial machinery producers deploy semantic knowledge graphs for supply chain risk monitoring and predictive maintenance. The EU AI Act imposes conformity assessments on high-risk credit scoring and biometric applications, forcing documentation of training data provenance. Stuttgart and Munich host concentrated engineering teams where Bosch and Siemens Energy maintain regionally isolated cloud instances for sensitive manufacturing analytics.
Japan
E-commerce platforms and precision manufacturers prioritize sentiment analysis pipelines for customer experience optimization and quality control automation. METI guidelines on AI governance align with emerging ISO 42001 standards, reshaping vendor certification requirements. Tokyo and Osaka metropolitan areas concentrate procurement decisions where Rakuten and Panasonic Holdings deploy tensor processing infrastructure for low-latency recommendation engines.
United Kingdom
Financial services institutions and media publishers adopt retrieval-augmented generation architectures for compliance documentation and editorial automation. The Financial Conduct Authority's operational resilience rules intersect with EU AI Act extraterritorial provisions for firms serving continental clients. London's Square Mile and Manchester's MediaCityUK cluster cognitive software deployments where Bloomberg LP and BBC Studios route sensitive workloads through UK-sovereign cloud regions.
India
IT services exporters and domestic fintech platforms scale natural language processing for multilingual customer support and regulatory surveillance. The Digital Personal Data Protection Act imposes data localization requirements that favor indigenous cloud infrastructure providers. Bengaluru and Hyderabad anchor development centers where Infosys and TCS engineer cognitive pipelines for North American and European enterprise clients under contractual data residency clauses.
Content Analytics Discovery and Cognitive Software Market Competitive Environment
Player mix skews toward diversified technology conglomerates with hybrid cloud franchises, specialized analytics software vendors with vertical industry depth, and hyperscale infrastructure operators with tensor processing silicon advantages. Consolidation pressure intensifies as compliance documentation requirements and MLOps talent scarcity raise barriers for point-solution providers. Dominant competitive moves include strategic partnerships linking cognitive engines to legacy enterprise data architectures, and geographic expansion through regionally isolated cloud instance deployments.
Within the diversified technology conglomerate tier, IBM Corporation, Microsoft Corporation, and Google LLC occupy positions that exemplify divergent strategic anchors. IBM leverages Watson platform heritage and regulated-industry relationships. Microsoft embeds cognitive services natively across productivity and infrastructure stacks. Google competes through specialized inference hardware and large-language-model scale advantages.
| Leading Market Players |
|---|
| IBM Corporation |
| Google LLC |
| Amazon Web Services (AWS) |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| OpenText Corporation |
| Adobe Inc. |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for GPU accelerator procurement anchor pricing power among hyperscale infrastructure operators while compressing margins for software vendors lacking forward inventory positions. This inventory friction concentrates cost advantages with tensor processing incumbents who secured foundry allocation early, forcing mid-tier cognitive platform providers toward consumption-based pricing models that transfer capital risk to buyers.
Pricing Analysis
Transformer-generation cognitive services command 40-60% premiums over legacy NLP engine pricing, while next-generation multimodal pipelines face downward pressure from open-weight model competition. Three-tier pricing structure across premium, standard, and economy levels segments by inference latency guarantees and audit documentation depth. Cost compression in standard-tier subscriptions is intensifying because GPU spot market volatility feeds through to per-token inference costs. Mid-market healthcare buyers in the United States exhibit highest price sensitivity, whereas financial trading floors accept premium tiers for sub-10-millisecond latency guarantees.
Supply Chain Analysis
Ninety-day lead times for AI accelerators stretch to one hundred twenty days during foundry capacity crunches, exposing cognitive software vendors to delivery uncertainty that shapes procurement contracting terms. Taiwan, South Korea, and the United States anchor global supply for tensor processing units and high-bandwidth memory modules. Cognitive platform development draws from proprietary training data corpora, transformer architecture licenses, and vector database infrastructure. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity for advanced node production. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams, with regional cloud isolation requirements in Germany and Japan fragmenting fulfillment logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipeline engineering talent gap between MLOps practitioners and enterprise deployment demand creates asymmetric returns for organizations that anchor capability development early. This scarcity dynamic rewards incumbents with established training pipelines and entrants with novel automation approaches.
For Market Incumbents: Fortify hybrid cloud deployment architectures by embedding cognitive services natively across productivity stacks, neutralizing point-solution vendors who lack integration depth. Deepen ISO 42001 certification investments ahead of fragmented jurisdictional rollouts, converting compliance documentation into switching-cost moats. Prioritize captive supply arrangements for GPU accelerator allocation to secure inference cost advantages against emerging challengers. For New Entrants and Emerging Players: Lead with retrieval-augmented generation architectures targeting mid-market financial services compliance workflows, where incumbent bundling remains shallowest. Japan's precision manufacturing sector presents underexposed demand for sentiment analysis pipelines with regional cloud isolation. Pursue channel partnerships with systems integrators who bridge legacy electronic health record infrastructure, avoiding direct platform competition with hyperscale incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU AI Act conformity timelines will strand non-compliant point solutions and force consolidation toward documented, auditable platforms. Target acquisition profiles center on vertical-specific training data repositories paired with MLOps automation tooling, not raw model scale. Watch ISO 42001 certification velocity across vendor portfolios as the inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding cognitive services across Office and Azure stacks captures enterprise workflow lock-in. |
| Geographic Expansion | Regionally isolated cloud instances in Germany and Japan satisfy HIPAA and EU AI Act data sovereignty mandates. |
| Strategic Partnership | Alliances with electronic health record vendors accelerate clinical NLP deployment without legacy system replacement. |
| Acquisition of Specialist Firm | Vertical training data repositories in financial compliance command premium multiples amid provenance documentation requirements. |
| Product Launch | Explainable AI modules address EU AI Act algorithmic audit mandates for high-risk credit scoring applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with chief technology officers, healthcare information officers, financial services compliance leads, and MLOps platform engineers. Secondary validation incorporated SEC filings from hyperscale infrastructure providers, EU AI Act implementation guidance documents, HIPAA enforcement action records, and hospital procurement database extracts. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against cloud infrastructure capex disclosures anchored volume estimates.
Across the projection horizon, the analytical framework modeled cognitive software demand by deployment architecture, organization size tier, vertical industry exposure, integration complexity level, and regional regulatory cluster. CAGRs derived from segment-level adoption curve fitting and infrastructure capacity expansion trajectories. Forecast inputs incorporated GPU supply elasticity assumptions and ISO 42001 certification rollout schedules across the United States, Germany, and Japan.
Underlying assumptions cover sustained enterprise cloud migration momentum and stable foundry capacity expansion for AI accelerators, with deviation risk concentrated in geopolitical supply disruptions and divergent EU AI Act enforcement timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Embedded Analytics Software Market
Analytics
Manufacturing Analytics Market
Analytics
North America HR Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Big Data in Automotive Market
Analytics
Europe Emotion Analytics Market
Analytics
Italy ICT Market
Analytics
Cloud Performance Management Market
Analytics
Text Analytics Market
Analytics
Embedded Analytics Market
Analytics
Content Intelligence Market
Analytics
Geospatial Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Complex Event Processing Market