
 Cloud Performance Management Market | 2026-2036
Cloud Performance Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Performance Management Market Analysis
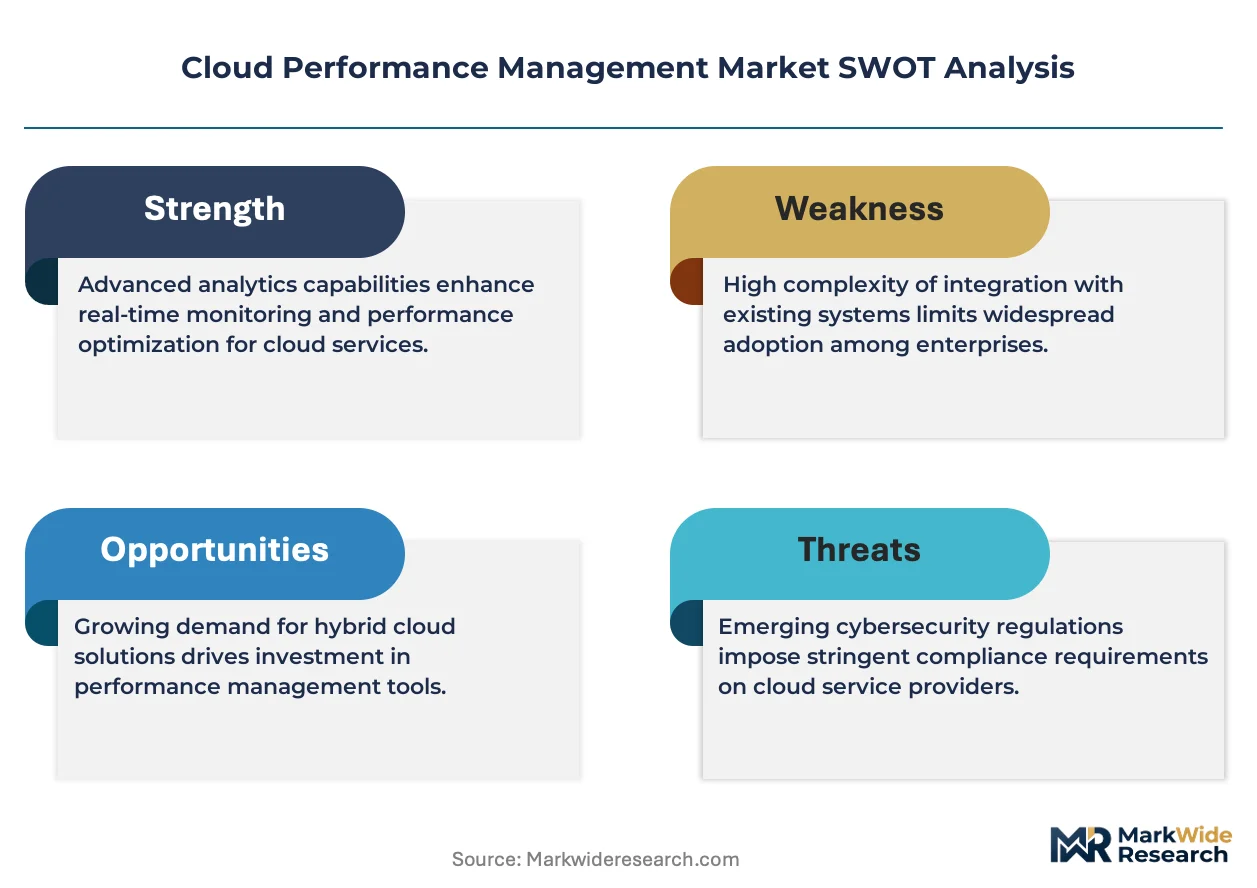
The EU Green Deal is restructuring procurement criteria for cloud infrastructure across European enterprises. Datadog leverages extensive SaaS monitoring integrations to sustain platform stickiness among DevOps teams. IBM Turbonomic anchors hybrid cloud optimization through AI-driven resource allocation algorithms. Dynatrace competes on full-stack observability with automated root-cause analysis capabilities.
Cloud performance management encompasses the systematic measurement, analysis, and optimization of compute, storage, and network resource behavior across distributed infrastructure, typically operating at millisecond-level granularity for latency metrics and sub-percent thresholds for availability SLAs. Its primary commercial purpose is to prevent revenue loss from application slowdowns and to eliminate wasteful over-provisioning in elastic environments. Public cloud deployment now captures the dominant margin pool as enterprises abandon capital-intensive on-premises instrumentation, while hybrid cloud configurations represent the fastest-expanding segment as regulated industries seek workload portability. The monitoring solution layer remains mature with compressed pricing, whereas analytics modules command premium positioning through predictive failure detection.
ISO 27001 certification requirements shape vendor selection criteria for enterprise buyers evaluating cloud performance platforms. The EU AI Act imposes algorithmic transparency obligations on automated optimization engines deployed within European jurisdictions. NIST cloud security frameworks influence procurement standards for US federal contractors and their supply chain partners. Stakeholders must monitor how emerging sovereign cloud mandates fragment data residency requirements across national boundaries.
Market Dynamics
Hyperscale cloud migration is forcing enterprises to abandon static capacity planning in favor of real-time elastic orchestration, fundamentally restructuring how infrastructure performance is measured and monetized across distributed environments.
Growth Catalysts
- EU AI Act compliance mandates:Automated resource orchestration engines deployed in European jurisdictions face new algorithmic transparency obligations, creating procurement urgency for explainable optimization platforms.
- Financial services latency requirements:Trading firms demand sub-millisecond monitoring granularity for cloud-hosted workloads, expanding the addressable market for specialized performance instrumentation.
- SAP S/4HANA cloud migrations:German enterprises migrating core ERP systems to hyperscale environments require granular performance baselining to validate SLA commitments.
Market Restraints
- Observability data gravity:Telemetry volume from containerized microservices grows exponentially faster than compression algorithms improve, inflating storage costs for retention-heavy compliance regimes.
- Skill concentration in DevOps hubs:Platform engineering expertise clusters in metropolitan technology corridors, leaving secondary markets dependent on managed service intermediaries.
- ISO 27001 certification timelines:Vendor security attestation processes stretch 8-14 months, freezing procurement cycles for risk-averse regulated buyers.
Strategic Opportunities
- Sovereign cloud fragmentation:National data residency mandates in France, Germany, and emerging EU member states create demand for jurisdiction-specific performance benchmarks.
- Carbon-aware workload scheduling:EU Green Deal procurement criteria reward platforms that correlate resource allocation with real-time grid carbon intensity data.
- Edge-to-cloud continuity monitoring:Industrial IoT deployments require unified performance visibility spanning factory floor gateways through hyperscale backends.
Industry Challenges
- Observability engineer scarcity:Organizations struggle to staff teams capable of interpreting distributed tracing data and constructing meaningful SLO frameworks.
- Legacy APM integration friction:Decades-old on-premises monitoring investments resist API-based consolidation with cloud-native telemetry pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Performance Management Market |
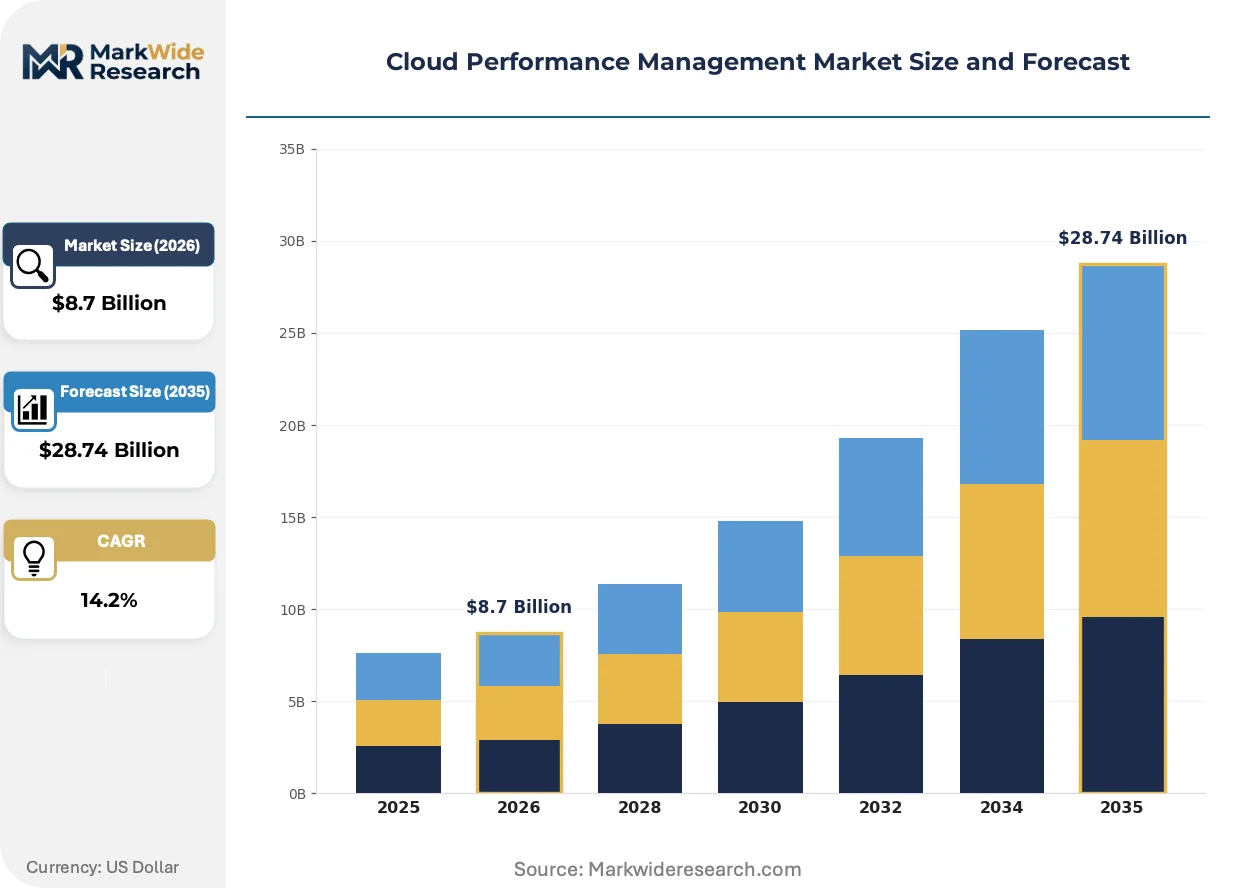
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Monitoring, Analytics, Optimization, Reporting Deployment: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud End User: IT Departments, Enterprises, SMBs, Service Providers Application: Performance Monitoring, Incident Management, Capacity Planning, Resource Allocation |
| Companies Covered | Datadog, Flexera, IBM Turbonomic, Morpheus Data, Apptio, Nutanix Cloud Platform, CloudHealth, CloudBolt, Dynatrace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Performance Management Market Emerging Trajectories
OpenTelemetry is consolidating telemetry standards across previously fragmented vendor ecosystems, reducing instrumentation lock-in while enabling portable observability pipelines that span multi-cloud deployments.
eBPF kernel instrumentation is electrifying how platforms capture system-level performance data without agent overhead. Cloud-native security teams adopt eBPF-based monitoring for zero-trust workload verification. This technology is electrifying competitive positioning for vendors offering agentless visibility into container runtime behavior.
The EU AI Act imposes documentation requirements on automated optimization algorithms that adjust resource allocation without human intervention. Platform vendors must now maintain audit trails for machine-driven scaling decisions. Financial services deployments in Frankfurt and Amsterdam face the steepest compliance adaptation curves.
Consumption-based pricing for observability platforms is displacing traditional per-host licensing as the dominant commercial model. Enterprise buyers negotiate indexed pricing tied to monthly active telemetry volume rather than provisioned infrastructure. This shift is most advanced among SaaS-native companies in the United States and Nordic enterprise software segments.
Cloud Performance Management Market Segmentation
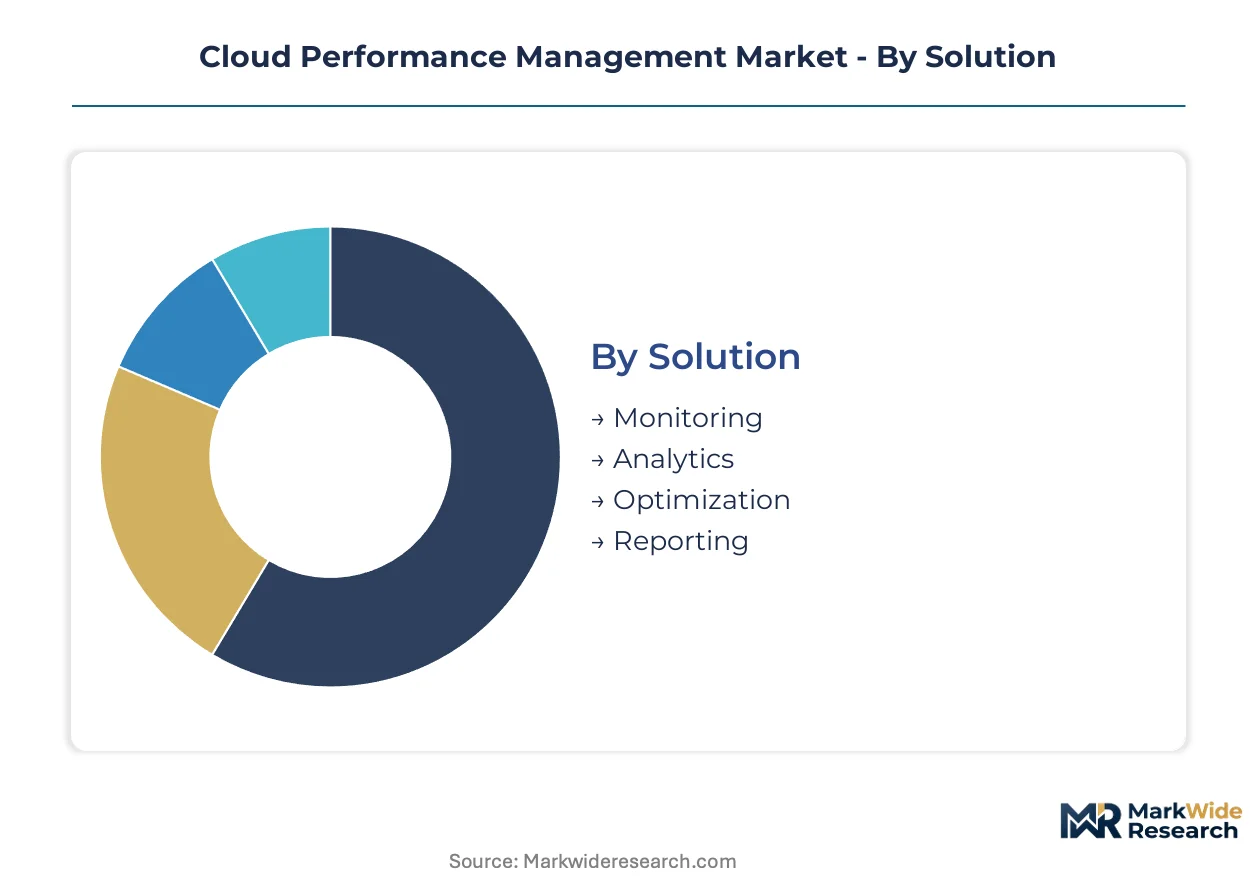
Cloud performance management platforms serve divergent operational maturity levels across enterprise IT estates. Solution architecture, deployment topology, and organizational scale collectively determine instrumentation depth and commercial commitment. Understanding segment boundaries clarifies where vendor specialization creates sustainable margin pools versus commodity pricing pressure.
Solution:
Standalone monitoring modules operate independently from resource orchestration systems, while embedded analytics engines integrate directly into cloud control planes.
- Monitoring:Real-time telemetry collection across compute, storage, and network layers with millisecond-level granularity for latency-sensitive workloads. Financial services firms in Frankfurt and Amsterdam deploy specialized instrumentation for trading infrastructure, driven by sub-millisecond SLA requirements under EU AI Act transparency mandates.
- Analytics:Predictive failure detection and pattern recognition algorithms processing historical performance baselines. German enterprises migrating SAP S/4HANA systems to hyperscale environments demand these capabilities to validate cloud provider commitments and optimize licensing costs.
- Optimization:Automated resource right-sizing and workload placement recommendations.
- Reporting:Compliance documentation and executive dashboards for stakeholder communication.
Volume placements concentrate in Monitoring; the faster expansion belongs to Analytics.
Deployment:
Cost tier structures separate capital-intensive on-premises instrumentation from elastic consumption models.
- Public Cloud:SaaS-delivered observability with consumption-based pricing indexed to telemetry volume. US federal contractors favor this model under NIST framework procurement standards, though data residency concerns limit adoption for classified workloads.
- Hybrid Cloud:Unified visibility spanning on-premises legacy systems and elastic cloud resources. Regulated industries across France, Germany, and Switzerland pursue this architecture to maintain workload portability while satisfying sovereign data requirements.
- Private Cloud:Dedicated infrastructure instrumentation within single-tenant environments.
- On-Premises:Traditional agent-based monitoring for legacy data center estates resisting cloud migration.
Public Cloud captures dominant commercial volume; Hybrid Cloud is climbing the fastest as compliance complexity deepens.
End User:
Customer type determines platform complexity tolerance and procurement authority concentration.
- Enterprises:Multi-divisional deployments with centralized platform engineering teams and formal SLO frameworks. Large German automotive and chemical conglomerates anchor demand in this segment, integrating performance data with ISO 27001-certified security operations centers.
- IT Departments:Functionally focused buyers prioritizing operational dashboards over strategic optimization.
- SMBs:Price-sensitive adopters relying on managed service intermediaries for technical implementation.
- Service Providers:Multi-tenant platforms requiring customer-isolated performance visibility.
Enterprise accounts dominate current revenue; IT Departments show steepest expansion trajectory as platform engineering practices diffuse.
Application:
Maturity stages separate reactive incident response from proactive capacity orchestration.
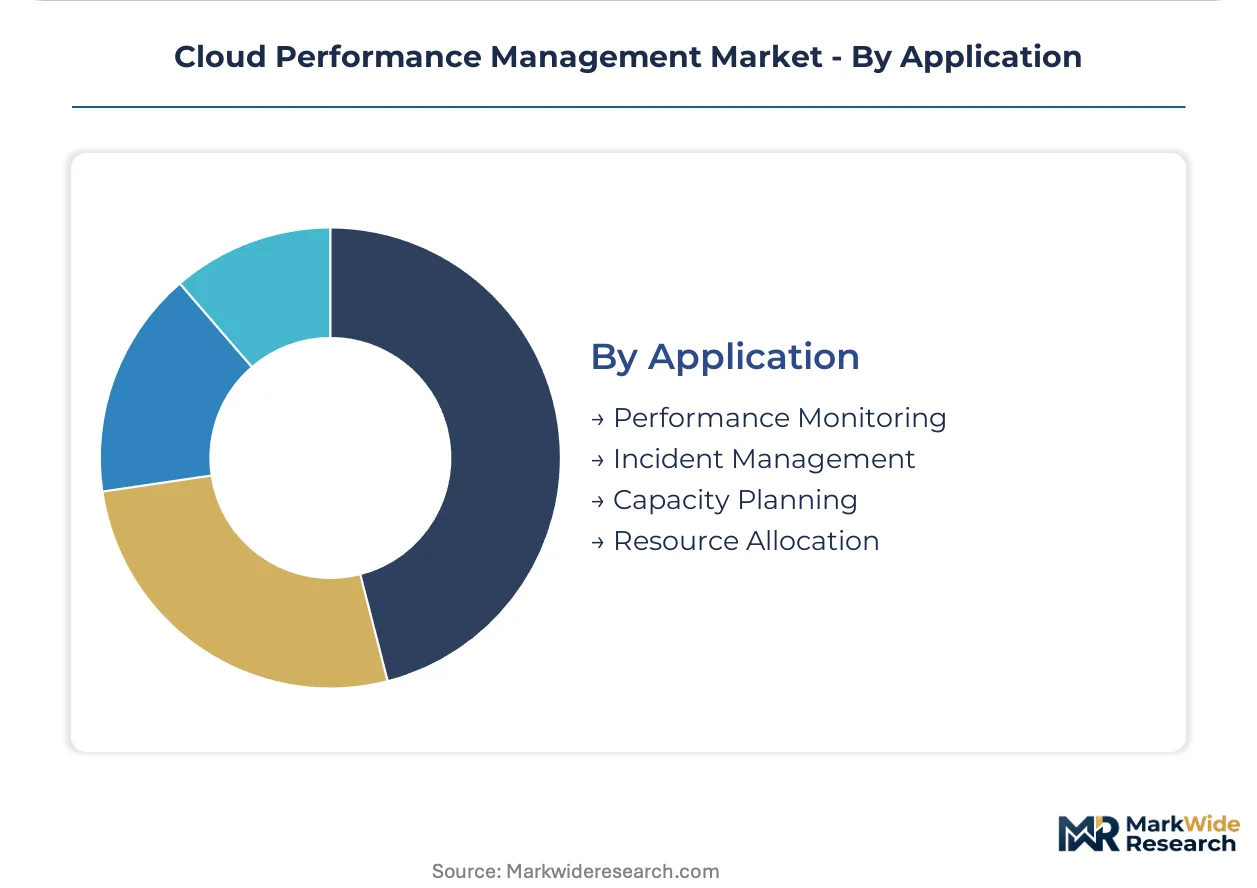
- Performance Monitoring:Continuous measurement of application response times, infrastructure utilization, and user experience metrics. DevOps teams in Nordic enterprise software segments prioritize this foundation before advancing to predictive capabilities.
- Capacity Planning:Forecast-driven resource provisioning balancing cost efficiency against availability risk. Organizations facing EU Green Deal procurement criteria leverage this application to correlate workload scheduling with real-time grid carbon intensity data.
- Incident Management:Alert correlation and automated escalation workflows for service degradation events.
- Resource Allocation:Dynamic compute and storage distribution across distributed environments.
Performance Monitoring holds established volume; Capacity Planning is gaining share fastest amid sustainability-linked procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European demand for cloud performance management as financial institutions migrate latency-sensitive trading infrastructure to hyperscale environments. The EU AI Act and EU Green Deal collectively reshape procurement criteria across the continent. Sovereign cloud mandates fragment data residency requirements, creating jurisdiction-specific optimization needs.
United States
Financial services firms in New York and Chicago deploy sub-millisecond monitoring for cloud-hosted trading workloads. NIST cloud security frameworks influence procurement standards for federal contractors and defense supply chain partners. Silicon Valley SaaS providers anchor consumption-based pricing innovation, displacing traditional per-host licensing models.
Germany
Automotive and chemical conglomerates migrating SAP S/4HANA systems to hyperscale environments demand granular performance baselining. EU AI Act algorithmic transparency obligations apply to automated resource orchestration engines deployed in Frankfurt and Munich data centers. Baden-Württemberg manufacturing clusters pursue edge-to-cloud continuity monitoring for industrial IoT deployments.
United Kingdom
London-based financial services firms expand adoption of explainable optimization platforms to satisfy emerging compliance requirements. ISO 27001 certification shapes vendor selection criteria for enterprise buyers evaluating cloud performance platforms. Fintech clusters in the Southeast prioritize real-time elastic orchestration over static capacity planning.
France
National data residency mandates create demand for jurisdiction-specific performance benchmarks separate from pan-European cloud architectures. EU Green Deal procurement criteria reward platforms correlating resource allocation with real-time grid carbon intensity data. Paris-based enterprises pursue hybrid cloud configurations to maintain workload portability while satisfying sovereign requirements.
Japan
Tokyo enterprises adopt eBPF kernel instrumentation for agentless visibility into container runtime behavior. METI industrial digitization programs accelerate edge-to-cloud continuity monitoring adoption for manufacturing supply chains. Osaka-based platform engineering teams construct formal SLO frameworks as DevOps practices mature.
Cloud Performance Management Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the analytics-optimization stack, with predictive failure detection commanding superior positioning against mature monitoring modules. The vendor base organizes into three tiers: hyperscale-integrated platforms, standalone observability specialists, and legacy APM incumbents adapting cloud-native telemetry pipelines. Consolidation pressure intensifies as consumption-based pricing models favor scale economics. M&A activity targets eBPF instrumentation capabilities and carbon-aware workload scheduling algorithms.
Within the full-stack observability tier, Dynatrace and Datadog exemplify platform stickiness strategies through automated root-cause analysis and extensive SaaS monitoring integrations respectively. IBM Turbonomic anchors hybrid cloud optimization positioning through AI-driven resource allocation algorithms. These three vendors occupy distinct archetype positions: Dynatrace competes on automated diagnostics depth, Datadog leverages ecosystem breadth, and IBM Turbonomic focuses on hybrid environment optimization.
| Leading Market Players |
|---|
| Datadog |
| Flexera |
| IBM Turbonomic |
| Morpheus Data |
| Apptio |
| Nutanix Cloud Platform |
| CloudHealth |
| CloudBolt |
| Dynatrace |
| Others |
Supply Flow & Price Mechanics
Consumption-based procurement preferences among US federal contractors and Nordic SaaS enterprises are compressing traditional per-host licensing models, forcing vendors to restructure commercial terms around telemetry volume indexing and elastic usage thresholds.
Pricing Analysis
Outcome-linked pricing anchors cloud performance management commercial structures, with enterprise buyers negotiating contracts tied to application uptime guarantees and latency SLA achievement rather than provisioned infrastructure counts. Three-tier pricing structure across premium analytics, standard monitoring, and economy observability tiers separates predictive failure detection capabilities from commodity telemetry collection. Pricing pressure stems from hyperscale cloud providers bundling baseline monitoring into compute contracts, squeezing standalone vendor margins. SMB segments exhibit highest price sensitivity and rely on managed service intermediaries, while financial services firms in Frankfurt and New York demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for cloud performance platforms, supplemented by systems integrator partnerships for mid-market deployment complexity. Engineering talent concentrates in the United States, Germany, and Japan, with platform development anchored in Silicon Valley, Berlin, and Tokyo metropolitan corridors. Component dependencies include eBPF kernel instrumentation libraries, OpenTelemetry standard implementations, and AI/ML training infrastructure for optimization algorithms. Supply chain risk centers on single-source vulnerability for specialized observability engineering expertise clustered in DevOps hub cities. Distribution runs through cloud marketplaces, direct sales organizations, and channel partner networks serving regulated industry verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity props pricing power for vendors possessing certified implementation capabilities, constraining supply expansion and sustaining premium positioning for explainable optimization engines.
For Market Incumbents: Cement platform stickiness through deeper OpenTelemetry standard integration and eBPF instrumentation capability acquisition, defending against hyperscale cloud providers bundling baseline monitoring into compute contracts. Expand ISO 27001 certification scope to accelerate procurement cycles for risk-averse regulated buyers in Germany and France. Prioritize carbon-aware workload scheduling R&D to capture EU Green Deal procurement criteria. For New Entrants and Emerging Players: Managed service providers represent the most accessible channel partner type for penetrating mid-market segments lacking internal platform engineering expertise. Target sovereign cloud fragmentation in emerging EU member states where jurisdiction-specific performance benchmarks remain undefined. Pursue edge-to-cloud continuity monitoring white space in Baden-Württemberg manufacturing clusters and Osaka industrial supply chains. For Investors and Strategic Acquirers: The window for entry favors eBPF instrumentation specialists and carbon-aware optimization algorithm developers ahead of EU AI Act transparency mandate enforcement. Long-term viability hinges on differentiation from hyperscale bundled offerings through predictive analytics depth. Watch for inflection signals in sovereign cloud procurement volume across France, Germany, and Switzerland.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenTelemetry consolidation reduces instrumentation lock-in across multi-cloud deployments. |
| Acquisition of Specialist Firm | eBPF capability acquisition accelerates agentless container runtime visibility development. |
| Geographic Expansion | Frankfurt and Amsterdam data center presence satisfies EU AI Act algorithmic transparency requirements. |
| Product Launch | Carbon-aware workload scheduling aligns with EU Green Deal procurement criteria adoption. |
| Strategic Partnership | SAP S/4HANA migration alliances capture German enterprise hyperscale transition demand. |
Methodological Framework
Document review covered hyperscaler capex disclosures, SEC filings from publicly traded observability vendors, EU regulatory filings under AI Act and Green Deal frameworks, and NIST cloud security publications, complemented by interviews with platform engineering directors, DevOps team leads, IT procurement officers at financial services firms, and cloud marketplace operators. Secondary validation drew from App Annie enterprise software adoption data, customs records for data center equipment imports, and hyperscaler infrastructure expansion announcements. Bottom-up telemetry volume modeling triangulated against top-down enterprise IT spend allocation surveys.
Market sizing outputs reflect segment-level modeling across deployment topology, solution type, organizational scale, and application maturity stage throughout the forecast period. CAGR derivation incorporated historical hyperscale migration velocity, SAP S/4HANA cloud transition timelines, and EU regulatory compliance deadline clustering. Industry-specific inputs included financial services latency requirement evolution, eBPF kernel instrumentation adoption curves, and sovereign cloud mandate implementation schedules across European jurisdictions.
Caveats apply where EU AI Act enforcement timing, hyperscale bundling strategy shifts, or platform engineering talent supply constraints could materially shift the outlook. Forecasts embed assumptions regarding OpenTelemetry standard consolidation velocity and carbon intensity data availability for workload scheduling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
BI and Analytics Market
Analytics
India Big Data Technology and Service Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Europe Location Analytics Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Process Analytics Market
Analytics
Service Analytics Market
Analytics
Customer Journey Analytics Market
Analytics
Big Data Analytics in BFSI Market
Analytics
Global Clickstream Analytics Market
Analytics
Multi-Touch Attribution Market
Analytics
Global Industrial Analytics Market
Analytics
Procurement Analytics Market