
 Contactless Ticketing Ics Market | 2026-2036
Contactless Ticketing Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Ticketing Ics Market Outlook
A shift from single-source ASIC procurement to multi-source fabless partnerships is rebalancing supply risk across the contactless ticketing IC value chain. NXP Semiconductors leverages its embedded secure-element portfolio to anchor transit-wallet convergence in European and Asian deployments. Infineon Technologies sustains manufacturing scale through captive fabs serving municipal transit authorities with extended product lifecycles. STMicroelectronics competes on cost-optimized NFC controllers targeting mid-tier transport operators in emerging economies.
Contactless ticketing ICs are semiconductor devices integrating radio-frequency interfaces, cryptographic processors, and non-volatile memory within single-die or system-in-package architectures, typically operating at 13.56 MHz with ISO/IEC 14443 Type A/B protocol compliance to enable tap-to-pay fare validation. These components authenticate passenger credentials, execute transit-specific payment tokens, and resist cloning through hardware-rooted security enclaves. NFC-enabled secure elements lead volume shipments as open-loop transit systems replace closed-loop proprietary cards across major metropolitan networks. Cloud-based deployment architectures are expanding fastest among mid-size transit agencies seeking reduced infrastructure capital. QR-code integration segments remain margin-diluted due to commodity scanner hardware and absence of cryptographic silicon content.
FCC Part 15 rules in the United States constrain RF emission profiles for unlicensed 13.56 MHz operation, directly shaping antenna-design specifications and reader-interference thresholds for transit-system vendors. ETSI EN 300 330 in Europe and India's BIS electromagnetic-compatibility standards add compliance layers that filter non-certified IC suppliers from public-tender participation. Stakeholders must monitor evolving central-bank digital-currency interfaces and biometric-faregate pilots, as these programs threaten to displace card-present authentication architectures before current semiconductor design cycles conclude.
Market Dynamics
Transit authorities are dismantling closed-loop proprietary card systems in favor of open-loop EMV-compliant platforms, forcing semiconductor suppliers to rearchitect secure-element portfolios for multi-application wallet convergence.
Growth Catalysts
- EMV Compliance Mandates:Europay-Mastercard-Visa chip-security standards in Europe and Asia are compelling wholesale replacement of magnetic-stripe infrastructure with contactless-capable terminals.
- India's Urban Metro Expansion:Smart-city transit corridors in Delhi, Mumbai, and Bangalore are procuring NFC-enabled fare gates at scale, concentrating demand for ISO/IEC 14443-compliant ICs.
- Cloud-Native Deployment Architectures:Mid-size municipal agencies are adopting software-as-a-service fare collection to eliminate on-premise server capital, accelerating reader-IC refresh cycles.
Market Restraints
- Silicon Supply Concentration:Advanced secure-element fabrication concentrates among three European and Asian foundry groups, exposing transit agencies to allocation risk during automotive chip demand surges.
- Commodity QR-Code Substitution:Camera-based fare validation eliminates cryptographic silicon content entirely, compressing margins for IC vendors in price-sensitive emerging markets.
- Extended Product Lifecycles:Municipal procurement cycles spanning 10-15 years lock suppliers into legacy node production, preventing migration to cost-optimized process geometries.
Strategic Opportunities
- Central Bank Digital Currency Interfaces:Pilot programs for transit-integrated CBDC wallets in China and India are creating demand for programmable secure elements with offline transaction capability.
- Biometric-Faregate Convergence:Facial-recognition authentication at turnstiles is expanding into Singapore and Dubai, requiring IC vendors to embed match-on-card processors within existing NFC form factors.
- PLI Scheme Tailwinds:India's production-linked incentive scheme for electronics manufacturing is attracting fabless design houses to establish local secure-element packaging and testing operations.
Industry Challenges
- Cryptographic Talent Scarcity:Hardware security module design requires specialized side-channel attack mitigation expertise that concentrates among a small pool of European and Israeli engineering teams.
- Multi-Stakeholder Certification Delays:Transit ICs must sequentially clear EMVCo, PCI PTS, and national transit authority security evaluations, extending time-to-revenue by 18-24 months.
- Legacy System Integration Friction:Backward compatibility with MIFARE Classic and DESFire deployments forces silicon vendors to maintain obsolete protocol stacks alongside modern implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Ticketing Ics Market |
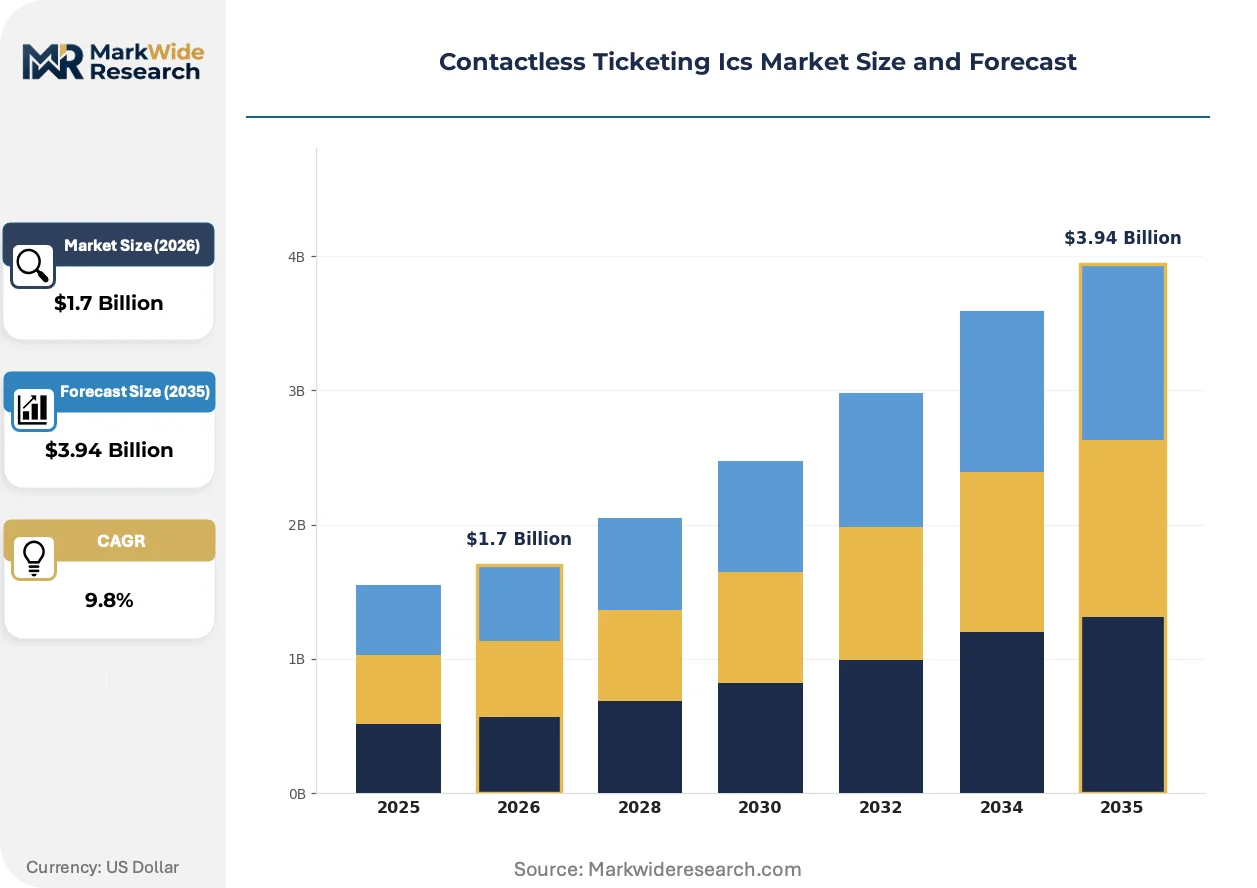
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.94 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, NFC, QR Code, Biometric End User: Transit Authorities, Event Organizers, Sports Venues, Theme Parks Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Integration Level: API, SDK, Direct Integration, Partner Solutions |
| Companies Covered | NXP Semiconductors, Infineon Technologies, ams-OSRAM, Texas Instruments, STMicroelectronics, Rambus, HID Global, Thales Group, Cubic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Ticketing Ics Market Strategic Shifts
Silicon architectures are bifurcating between premium secure-element integration and cost-optimized NFC controller stripped-down variants, with deployment patterns diverging sharply by agency size and geography.
Dual-interface secure elements combining contact and contactless operation are expanding into high-throughput metro environments where fare gates must process peak-hour passenger volumes without latency. Transport for London and Singapore's Land Transport Authority have standardized on these chips for bankcard-accepting gates. The technology is expanding into multimodal account-based ticketing that unifies bus, rail, and micro-mobility payments under single credential management.
ETSI EN 300 330 electromagnetic-compatibility standards in Europe are tightening RF emission thresholds for 13.56 MHz readers, forcing IC vendors to redesign analog front-ends with improved noise rejection. Transit system integrators must now pre-certify antenna modules before public tender submission. This regulatory pressure is compressing supplier margins in Germany and France while filtering Asian module vendors from European procurement.
Account-based ticketing architectures are displacing card-centric stored-value systems across North American transit agencies. Chicago Transit Authority and Metropolitan Transportation Authority have migrated to back-office fare calculation, reducing dependence on card-issued secure elements. This shift is most visible in the United States where open-loop bankcard acceptance has reached critical mass on bus and rail networks.
Contactless Ticketing Ics Market Segmentation
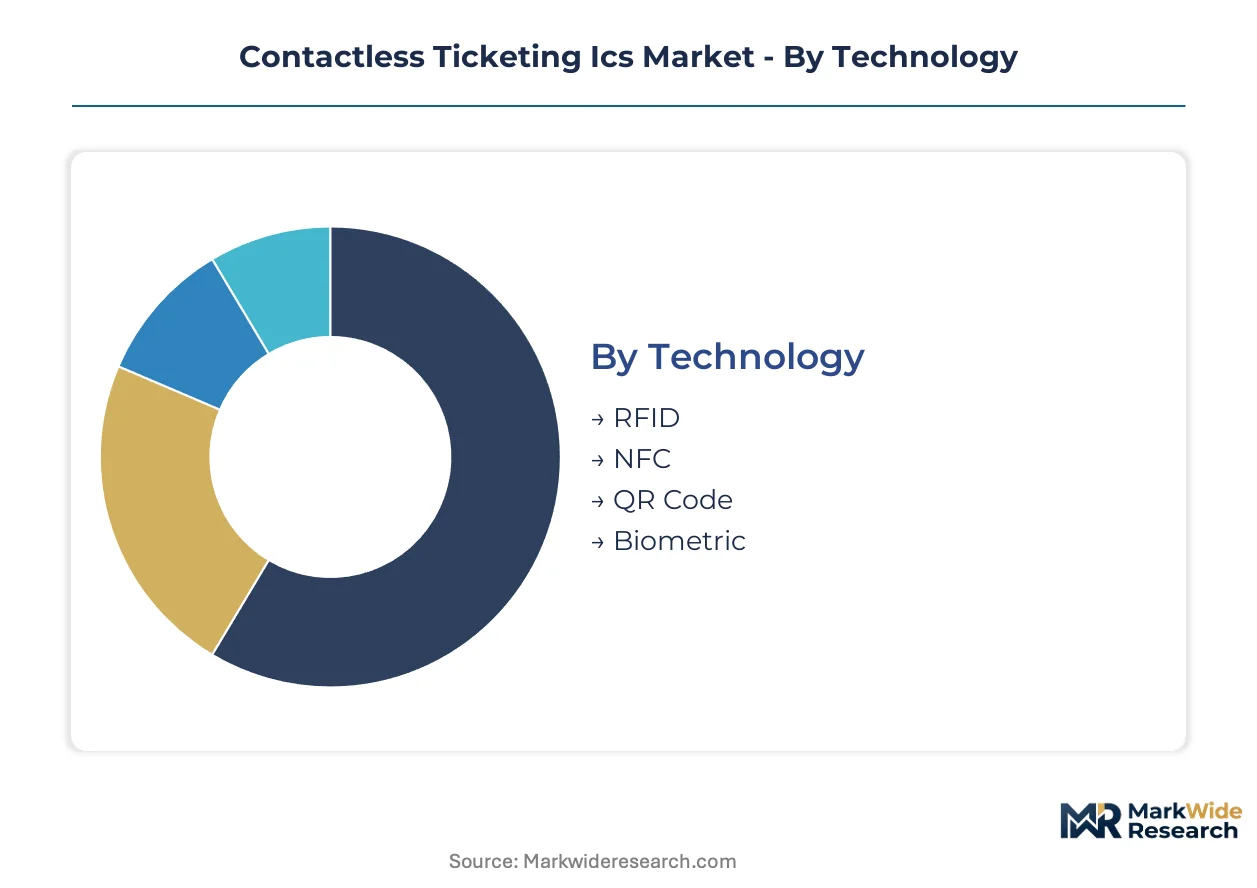
Technology architecture, deployment model, and integration depth determine procurement patterns for contactless ticketing ICs. Transit authorities weigh security certification against total cost of ownership when selecting across these dimensions.
Technology:
Security certification tiers and reader infrastructure compatibility dominate technology selection decisions.
- NFC:ISO/IEC 14443-compliant secure elements operating at 13.56 MHz enable tap-to-pay authentication with hardware-rooted cryptographic protection. Demand concentrates in Delhi, Mumbai, and Bangalore metro corridors where India's smart-city transit networks require EMV-compatible fare gates with offline transaction capability.
- RFID:Legacy 13.56 MHz and UHF passive tags support closed-loop stored-value systems with lower silicon complexity but reduced interoperability. Municipal agencies in Southeast Asia continue deploying these for bus fleet modernization where bankcard acceptance remains secondary.
- QR Code:Camera-based validation eliminates cryptographic silicon entirely, relying on server-side token generation.
- Biometric:Facial-recognition fare gates embedding match-on-card processors within NFC form factors.
NFC leads on scale; Biometric leads on momentum.
End User:
Procurement scale and security requirements diverge sharply across venue types and ridership volumes.
- Transit Authorities:Municipal operators managing multimodal networks with 10-15 year product lifecycles. European deployments under ETSI EN 300 330 compliance mandates drive secure-element refresh cycles.
- Event Organizers:Temporary credential issuance for festival and conference access with cloud-native backend architectures.
- Sports Venues:High-throughput turnstile environments requiring sub-300 millisecond transaction latency.
- Theme Parks:Closed-loop resort ecosystems integrating payment, access, and loyalty functions on single credentials.
Transit Authorities dominate volume; Event Organizers expand most quickly.
Deployment:
Capital availability and IT staffing levels shape cloud-versus-on-premise architecture decisions.
- Cloud-Based:Software-as-a-service fare collection eliminates server capital for mid-size municipal agencies. India's urban metro expansion favors this model for rapid deployment without dedicated data center infrastructure.
- On-Premise:Dedicated server installations serving large authorities with legacy integration requirements.
- Hybrid:Split architectures processing sensitive authentication locally while offloading analytics to cloud instances.
- Mobile:Smartphone-credential systems reducing dependence on physical card issuance.
Cloud-Based captures the steepest expansion trajectory; On-Premise retains the largest installed base.
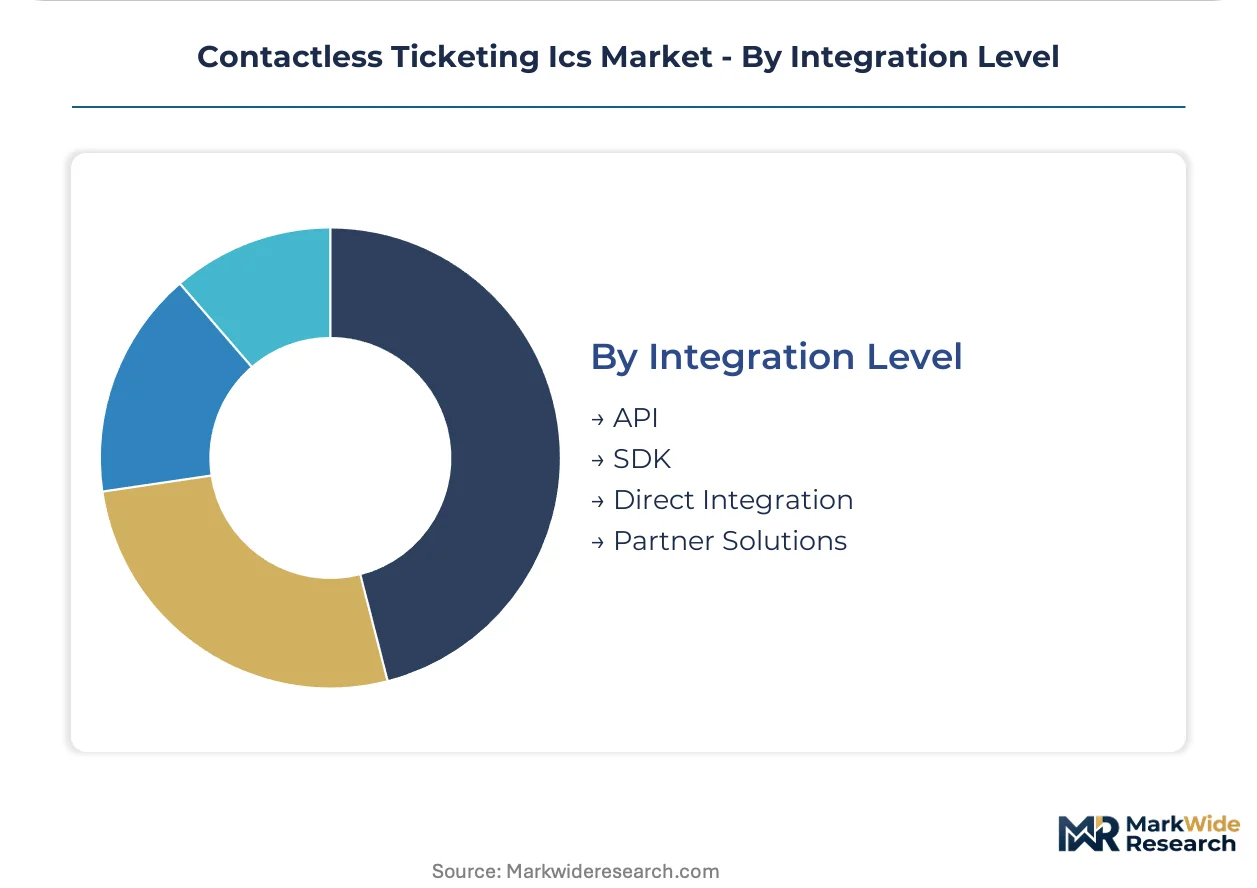
Integration Level:
Internal engineering capacity determines whether agencies adopt standardized interfaces or custom implementations.
- API:RESTful interfaces enabling rapid connection to existing transit management systems without hardware modification.
- SDK:Embedded software development kits for reader firmware customization.
- Direct Integration:Silicon vendor engagement for bespoke secure-element programming.
- Partner Solutions:Pre-certified module assemblies from system integrators.
API approaches gain share fastest; Direct Integration commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban metro corridors anchor near-term demand concentration for EMV-compliant secure elements, while European regulatory tightening and Southeast Asia's infrastructure replacement cycles shape procurement patterns across distinct compliance environments.
India
Delhi Metro Rail Corporation and Mumbai Metro procurement drives volume for ISO/IEC 14443-compliant ICs with offline transaction capability. The national PLI scheme for electronics manufacturing attracts secure-element packaging operations to Gujarat and Karnataka. Bangalore's smart-city transit networks deploy cloud-native fare collection without dedicated data center infrastructure.
Germany
Verkehrsverbund coordination bodies mandate ETSI EN 300 330 electromagnetic-compatibility compliance for 13.56 MHz reader deployments. The BSI federal information security office evaluates transit-wallet convergence architectures. Munich and Berlin transit authorities standardize on dual-interface secure elements for bankcard-accepting fare gates.
Singapore
Land Transport Authority pilots facial-recognition fare gates embedding match-on-card processors within NFC form factors. The Infocomm Media Development Authority regulates personal data handling in biometric transit systems. Jurong Lake District and Punggol Digital District serve as testbeds for multimodal account-based ticketing unification.
United States
Chicago Transit Authority and Metropolitan Transportation Authority migrations to back-office fare calculation reduce card-issued secure-element dependence. FCC Part 15 rules constrain RF emission profiles for unlicensed 13.56 MHz operation. New York and Boston transit networks lead open-loop bankcard acceptance scale on bus and rail corridors.
France
Île-de-France Mobilités mandates EMVCo certification for contactless transit-wallet convergence. ANSSI national cybersecurity agency evaluates hardware-rooted security enclave implementations. Paris metro automation programs drive refresh cycles for high-throughput fare gate ICs with sub-300 millisecond transaction latency.
Contactless Ticketing Ics Market Competitive Environment
Global majors compete with regional champions across certification depth and municipal procurement relationships, producing a tiered structure where premium secure-element portfolios command extended evaluation cycles. European and Asian foundry partnerships dominate fabrication capacity for transit-grade hardware security modules. Two archetypes prevail: integrated secure-element vendors with captive cryptographic expertise, and fabless NFC controller specialists optimizing for cost-sensitive emerging markets. Capacity allocation agreements and multi-stakeholder certification pre-qualification represent dominant competitive moves.
Within the integrated secure-element tier, NXP Semiconductors and Infineon Technologies exemplify European-based vendors with embedded hardware security module portfolios. STMicroelectronics occupies a position among cost-optimized NFC controller suppliers targeting mid-tier transport operators. These three anchors represent distinct strategic postures across premium certification depth, manufacturing scale, and price-positioning vectors.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| ams-OSRAM |
| Texas Instruments |
| STMicroelectronics |
| Rambus |
| HID Global |
| Thales Group |
| Cubic Corporation |
| Others |
Value Chain & Pricing Dynamics
Multi-source fabless partnerships are displacing single-source ASIC procurement, simultaneously compressing unit economics for mid-tier NFC controllers and fragmenting fabrication capacity across European and Asian foundry networks. This restructuring concentrates pricing power among captive-fab operators while eroding margins for cost-optimized entrants competing on volume.
Pricing Analysis
Input-cost pass-through from 200mm wafer constraints and specialty packaging shortages anchors contract-based long-term offtake agreements for transit-grade secure elements. Three-tier pricing structure across premium, standard, and economy levels separates EMVCo-certified dual-interface chips from ISO/IEC 14443 baseline controllers and commodity RFID tags. Cost compression in the economy tier is intensifying because QR-code substitution eliminates cryptographic silicon content entirely. Municipal transit authorities exhibit highest price sensitivity due to 10-15 year procurement cycles, while European rail operators under ETSI EN 300 330 mandates accept premium positioning for pre-certified modules.
Supply Chain Analysis
Photoresist supply and advanced lithography equipment rest on Japanese specialty chemical producers and Dutch equipment manufacturers, creating dependencies for secure-element fabrication at nodes below 40nm. Silicon wafer supply concentrates in Taiwan, South Korea, and Japan, with back-end packaging and testing gravitating toward Malaysia and Vietnam. Single-source vulnerability in EUV lithography systems exposes fabless design houses to allocation risk during automotive chip demand surges. Distribution runs through authorized semiconductor distributors serving tier-one transit system integrators with extended payment terms and technical support obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in contactless ticketing ICs rests on the shift toward cloud-native deployment architectures, which accelerates reader-IC refresh cycles and reduces customer concentration risk for semiconductor vendors.
For Market Incumbents: Lock in multi-year capacity reservation agreements with European and Asian foundry partners to defend against allocation risk during automotive demand surges. Deepen certification pre-qualification with EMVCo and national transit authorities to extend time-to-revenue barriers for emerging competitors. Prioritize backward integration into specialty packaging operations in India under PLI scheme incentives. For New Entrants and Emerging Players: Enter via India's urban metro corridors, where cloud-native fare collection architectures and PLI scheme tailwinds reduce capital barriers for secure-element testing and packaging operations. Target mid-tier municipal agencies in Southeast Asia seeking cost-optimized NFC controllers without EMVCo premium certification. Pursue white-label partnerships with established system integrators to bypass 18-24 month multi-stakeholder certification delays. For Investors and Strategic Acquirers: Roll-up economics work for fabless design houses with captive cryptographic expertise because hardware security module talent concentrates among a small pool of European and Israeli engineering teams, creating scarcity value. Focus acquisition screening on firms with pre-qualified EMVCo certifications and active transit authority relationships. Watch central bank digital currency pilot programs in China and India as inflection indicators for programmable secure-element demand.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | Secures wafer allocation from TSMC and GlobalFoundries during automotive demand peaks. |
| EMVCo Pre-Certification Investment | Compresses time-to-revenue by 12-18 months for dual-interface secure element launches. |
| Backward Integration into Packaging | Captures PLI scheme subsidies in Gujarat and Karnataka while reducing test-cycle latency. |
| Biometric-Faregate Partnership | Positions match-on-card processors for Singapore Land Transport Authority pilot expansions. |
| Cloud-Native SDK Development | Enables rapid deployment for mid-size municipal agencies adopting SaaS fare collection. |
Study Parameters
Direct dialogue with transit authority procurement officers, semiconductor vendor product managers, fare system integrators, and regulatory compliance specialists grounded this analysis in operational realities across European, Asian, and North American deployment environments. Secondary validation drew from EMVCo certification registries, FCC Part 15 equipment authorization databases, ETSI EN 300 330 compliance filings, and municipal tender documentation. Bottom-up unit shipment estimates triangulated against top-down semiconductor industry revenue allocations.
Segmented outputs across the projection horizon reflect technology architecture, deployment model, and integration depth as primary modeling dimensions, with regional regulatory cluster and agency size tier as secondary stratifiers. CAGRs were derived from logistic diffusion curves fitted to transit infrastructure replacement cycles and EMV compliance mandate schedules. Industry-specific inputs included fare gate installation timelines, secure-element design cycle durations, and foundry capacity allocation patterns.
Inputs from transit authority procurement databases and semiconductor distributor sell-through reports were available through the study window; gaps in biometric-faregate pilot deployment data and CBDC interface specifications introduce uncertainty bands around forward estimates. Forecasts reflect documented assumptions regarding EMV compliance adoption curves and cloud-native architecture penetration rates. Supply allocation disruptions, regulatory timeline accelerations, and biometric authentication substitution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Legal Technology Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Product Information Management Market
Digital Solutions
Service Mesh Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Digital Signature Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Mainframe Modernization Services Market