
 Synthetic Polyisoprene Rubber Market | 2026-2036
Synthetic Polyisoprene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Polyisoprene Rubber Market Analytics
The EU Green Deal is expanding synthetic polyisoprene demand as tire OEMs face binding sustainable-material quotas. KURARAY CO., LTD. leverages its solution-polymerization expertise to supply medical-grade latex with ultra-low residual-protein levels. Zeon Corporation anchors the Japanese market through captive isoprene monomer supply and tire-industry partnerships. SIBUR competes on feedstock integration from its Siberian petrochemical complex, sustaining cost leadership across Eurasian markets.
Synthetic polyisoprene rubber is a stereoregular elastomer synthesized via anionic or coordination polymerization of isoprene, yielding cis-1,4 content exceeding 96 percent to mirror natural rubber elasticity. Manufacturers employ Ziegler-Natta or rare-earth catalyst systems to achieve the molecular precision required for dynamic applications. Tire applications dominate volume consumption, though medical end users command premium pricing due to stringent biocompatibility certification. Powder product form is gaining traction in compounding operations seeking dust-free handling and faster dispersion.
REACH in Europe, GB standards in China, and FDA biocompatibility requirements in the United States collectively shape formulation chemistry, extractable limits, and market-access pathways for synthetic polyisoprene producers. Tire-labeling regulations in multiple jurisdictions now penalize rolling-resistance performance, pushing compounders toward higher-cis polymer architectures. Stakeholders must monitor catalyst-technology patents and regional carbon-intensity accounting rules to secure feedstock and offtake positioning.
Market Dynamics
Hospital allergy protocols are phasing out natural rubber latex, redirecting procurement budgets toward synthetic polyisoprene with ultra-low residual-protein certification. Tire OEMs simultaneously face binding sustainable-material quotas under the EU Green Deal, compressing formulation timelines and favoring high-cis polymer architectures.
Growth Catalysts
- REACH extractable-protein thresholds:European ECHA enforcement tightens biocompatibility standards, disqualifying natural rubber from medical glove tenders and redirecting hospital procurement toward certified synthetic alternatives.
- China tire capacity expansion:Domestic producers are scaling high-performance passenger vehicle lines, concentrating demand for solution-polymerized grades with dynamic properties matching natural rubber.
- Rare-earth catalyst systems:Advanced coordination polymerization achieves cis-1,4 content exceeding 96 percent, enabling tire compounders to meet rolling-resistance penalties without sacrificing wear characteristics.
Market Restraints
- Isoprene monomer supply concentration:Captive production in Siberian and Japanese petrochemical complexes creates geographic dependency, exposing compounders to feedstock disruption risks.
- Natural rubber price arbitrage:Hevea brasiliensis spot markets periodically undercut synthetic grades by 15-30 percent, pressuring margin structures in commodity tire applications.
- Biocompatibility certification timelines:FDA 510(k) and MDR conformity assessments for medical-grade latex extend 18-36 months, gating new entrants from premium pricing tiers.
Strategic Opportunities
- India domestic manufacturing:PLI scheme incentives for medical device localization create captive demand for latex-grade synthetic polyisoprene as domestic glove production scales.
- Powder product form adoption:Dust-free handling requirements in automated compounding operations favor granular morphologies, commanding technical premiums over bale form.
- Dual carbon goals in China:MEE carbon-intensity accounting rules reward lower-emission polymerization routes, advantaging producers with solution-process energy efficiency.
Industry Challenges
- Rare-earth catalyst expertise scarcity:Coordination chemistry specialization required for high-stereoregularity production concentrates among limited technical workforces, constraining capacity scaling.
- Legacy natural rubber compounder relationships:Tire manufacturers maintain decades-tuned formulation libraries around Hevea feedstock, creating switching friction despite performance parity.
- Cross-border MDR technical documentation:EU notified body capacity constraints delay certificate renewals, forcing medical-grade producers to maintain dual regulatory filing teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Polyisoprene Rubber Market |
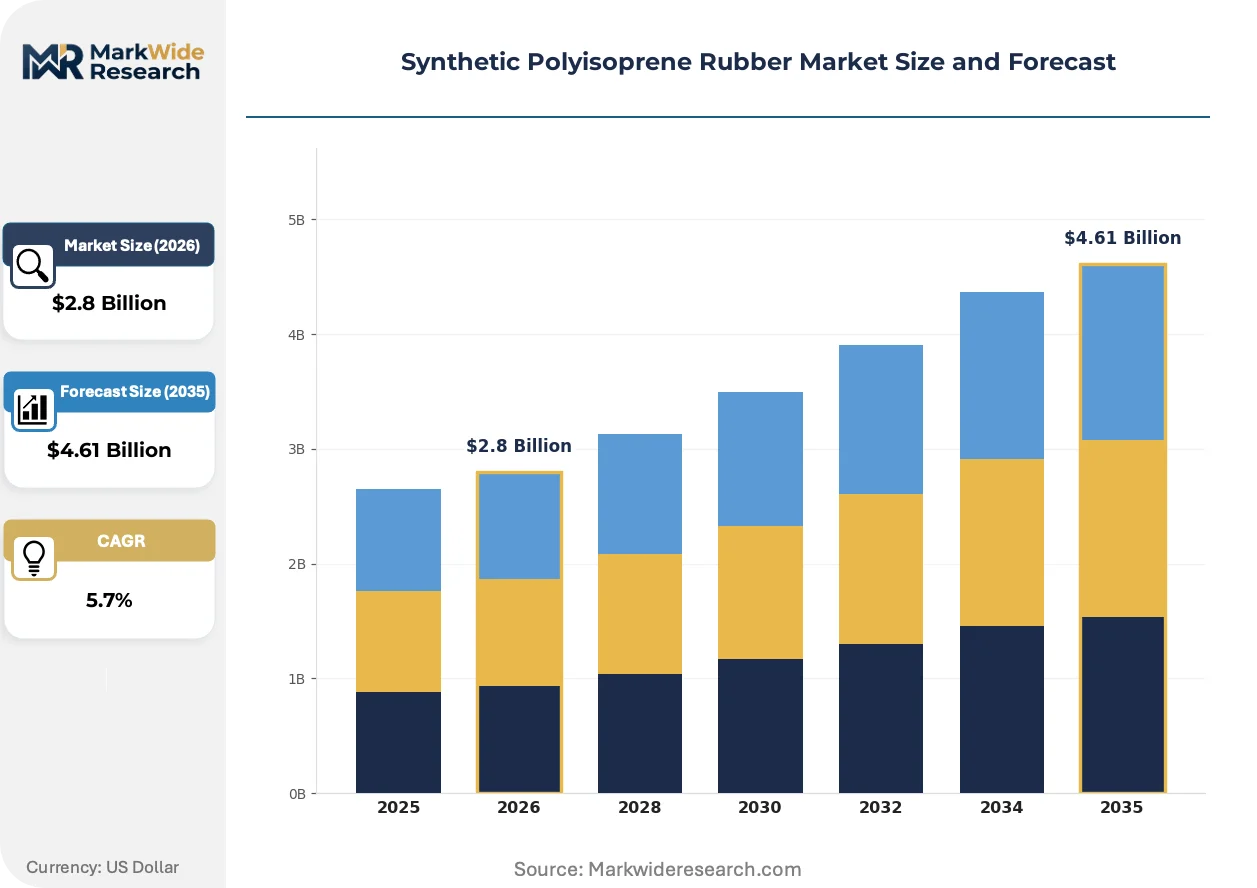
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Tires, Footwear, Seals, Gaskets Product Form: Sheet, Particle, Latex, Powder End User: Automotive, Consumer Goods, Industrial, Medical Distribution Channel: Direct Sale, Online, Retail, Wholesale |
| Companies Covered | Zeon Corporation, SIBUR, Nizhnekamskneftekhim, Goodyear Tire & Rubber Company, Cariflex, KURARAY CO., LTD., Kraton Corporation, TSRC Corporation, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Polyisoprene Rubber Market Evolving Landscape
Polymerization chemistry and regulatory compliance frameworks are converging to redefine specification thresholds across medical and tire applications. Catalyst innovation, extractable-protein measurement protocols, and procurement centralization are the three forces reshaping competitive positioning.
Rare-earth neodymium-based catalyst systems are integrating into commercial production lines, enabling molecular-weight distribution control previously unattainable with Ziegler-Natta alternatives. Tire compounders in Germany and Japan are adopting these grades for ultra-high-performance passenger lines. The technology is integrating rolling-resistance optimization with wear-index targets, compressing the performance gap between synthetic and natural rubber in dynamic applications.
EU MDR Annex I general safety and performance requirements now mandate quantified allergen-risk documentation for implantable and long-term contact devices. Medical glove manufacturers must submit residual-protein test data from ISO 10993-23 validated laboratories. The regulation is accelerating laboratory certification investments among synthetic polyisoprene suppliers, with European notified bodies experiencing 14-month backlog extensions for polymer biocompatibility dossiers.
Hospital procurement consortia are consolidating latex glove purchasing through centralized tender platforms, displacing fragmented distributor networks. Group purchasing organizations in the United States and National Health Service supply chains in the United Kingdom now specify synthetic polyisoprene as the default material class. This concentration is visible most acutely in acute-care networks with established allergy-prevention protocols, where single-source contracts cover 60-80 percent of annual glove volumes.
Synthetic Polyisoprene Rubber Market Segmentation
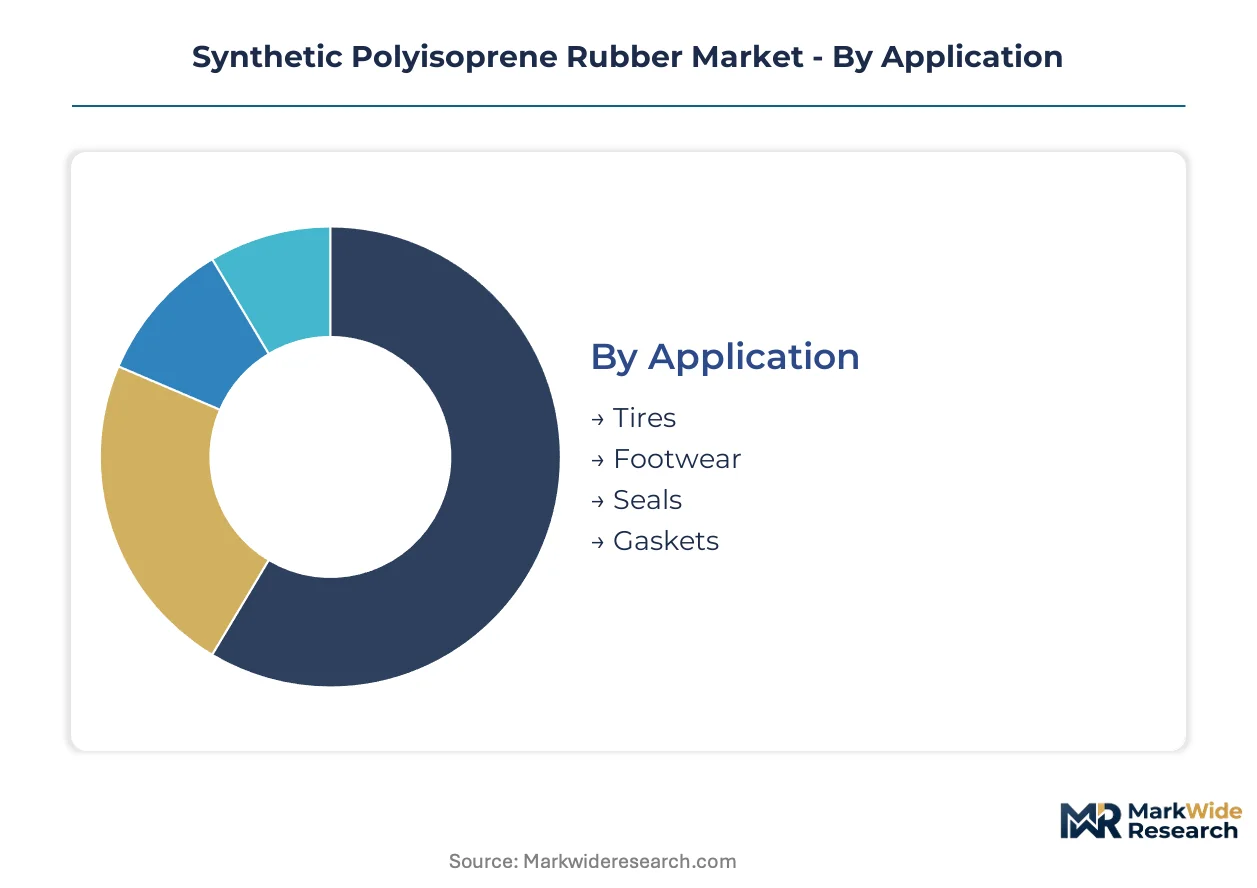
Synthetic polyisoprene rubber exhibits divergent specification requirements across medical certification tiers, tire performance grades, and compounding morphologies. Buyers in each segment prioritize distinct trade-offs between biocompatibility, rolling-resistance metrics, and handling efficiency.
Application:
Automotive OEMs and industrial fabricators diverge sharply in their elasticity, heat-aging, and dynamic-fatigue specifications.
- Tires:High-cis polymer architectures exceeding 96 percent stereoregularity enable compounders to satisfy EU tire-labeling penalties for rolling resistance without sacrificing wear indices. Chinese domestic producers are scaling solution-polymerized grades for high-performance passenger vehicle lines.
- Seals:Compression-set resistance and low-temperature flexibility specifications dominate procurement criteria for hydraulic and pneumatic systems. Industrial automation clusters in Germany and Japan specify rare-earth catalyzed grades for extended service intervals.
- Gaskets:Sheet-form polyisoprene serves flange-sealing applications requiring moderate chemical resistance and conformability to irregular surfaces.
- Footwear:Soling compounds leverage the polymer's rebound characteristics and abrasion resistance in athletic and safety boot segments.
Tires lead volumes today; medical-grade seals are gaining share fastest.
Product Form:
Handling economics and dispersion speed separate compounders selecting among physical morphologies.
- Latex:Aqueous dispersions with controlled particle-size distribution serve dipped-glove manufacturers seeking ultra-low residual-protein certification for hospital allergy protocols. REACH extractable-protein thresholds are disqualifying natural rubber from European medical tenders.
- Powder:Granular morphology eliminates dust exposure in automated weighing operations while accelerating dispersion in internal mixers. Technical premiums over bale form are widening as compounding automation spreads.
- Sheet:Calendered slabs facilitate hand-cutting operations in gasket fabrication and small-batch industrial rubber goods.
- Particle:Intermediate granule size serves specialty adhesive and sealant formulations requiring rapid solvent uptake.
Latex commands the steepest price premiums; powder is climbing the fastest as automation investments accelerate.
End User:
Regulatory exposure and volume contracting patterns distinguish procurement behavior across buyer categories.
- Medical:FDA 510(k) and EU MDR biocompatibility dossiers extend 18-36 months, gating new suppliers from premium tiers. Hospital group purchasing organizations in the United States and NHS supply chains now specify synthetic polyisoprene as default material class.
- Automotive:Tire OEMs face binding sustainable-material quotas under the EU Green Deal, compressing formulation timelines toward high-cis architectures. Domestic Chinese producers are expanding capacity for passenger vehicle lines.
- Industrial:Seals and gasket fabricators prioritize lot-to-lot consistency and compression-set performance over certification burden.
- Consumer Goods:Footwear and sporting goods manufacturers balance rebound characteristics against natural rubber price arbitrage that periodically undercuts synthetic grades.
Automotive absorbs the largest tonnage; medical is expanding most quickly on value terms.
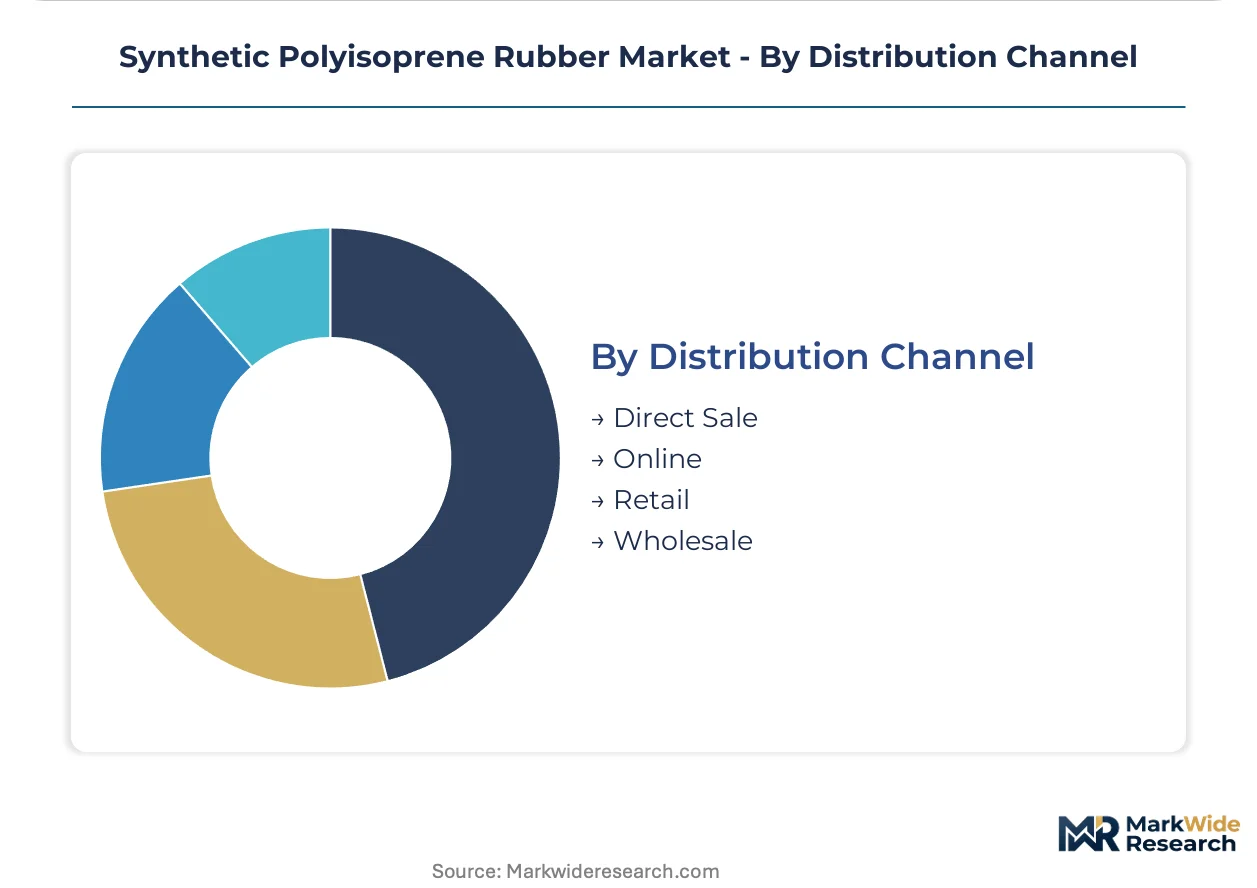
Distribution Channel:
Order scale and technical service intensity determine route selection for compounders and fabricators.
- Direct Sale:Tire OEMs and major medical glove manufacturers negotiate multi-year offtake agreements with producers of certified grades. KURARAY CO., LTD. and Zeon Corporation anchor these relationships through captive technical service teams.
- Wholesale:Regional distributors stock standard bale grades for industrial compounders with predictable consumption patterns.
- Online:Specialty grades and small-lot powder forms migrate toward digital procurement platforms serving mid-tier compounders.
- Retail:Limited to replacement gasket and seal materials through industrial supply houses.
Direct sale dominates value capture; wholesale remains the default for spot-volume fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The synthetic polyisoprene rubber industry traces its commercial origins to post-war Japan and Germany, where coordination polymerization breakthroughs established the first high-cis production platforms. Today manufacturing concentrates in East Asian petrochemical corridors and European specialty chemical clusters.
China
Domestic tire producers are scaling solution-polymerized grades for high-performance passenger vehicle lines. MEE carbon-intensity accounting rules reward lower-emission polymerization routes, advantaging producers with energy-efficient processes. The Yangtze River Delta hosts expanding compounding operations serving automotive OEMs.
Japan
Zeon Corporation anchors domestic supply through captive isoprene monomer production. METI industrial standards enforce rigorous quality specifications for medical-grade exports. The Chubu region around Nagoya maintains concentrated tire-industry partnerships with compounders.
Germany
Tire OEMs face binding sustainable-material quotas under the EU Green Deal, compressing formulation timelines toward high-cis architectures. ECHA REACH enforcement tightens extractable-protein thresholds for medical applications. The Cologne-Düsseldorf chemical corridor hosts major compounding research centers.
United States
Hospital group purchasing organizations now specify synthetic polyisoprene as the default glove material class. FDA 510(k) biocompatibility requirements extend certification timelines for new suppliers. The Gulf Coast petrochemical belt sustains feedstock integration for domestic producers.
India
PLI scheme incentives for medical device localization create captive demand for latex-grade synthetic polyisoprene. CDSCO regulatory pathways are streamlining for domestic manufacturers. Gujarat and Maharashtra are scaling glove production clusters to serve export markets.
Synthetic Polyisoprene Rubber Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and catalyst-technology sophistication. The market structure concentrates around integrated petrochemical groups and specialty polymer houses with rare-earth coordination expertise. Three archetypes dominate: Siberian feedstock-integrated producers, Japanese catalyst-technology specialists, and European medical-grade certification leaders. Competitive moves center on backward integration into isoprene monomer supply and strategic partnerships with tire OEMs for rolling-resistance optimization programs.
Within the catalyst-technology tier, Zeon Corporation and KURARAY CO., LTD. occupy positions defined by solution-polymerization expertise and medical-grade certification depth. SIBUR represents the feedstock-integrated archetype with Siberian petrochemical complex advantages. These three anchors illustrate how geographic concentration of isoprene supply and regulatory proximity to end markets shape competitive positioning across Eurasian and North American markets.
| Leading Market Players |
|---|
| Zeon Corporation |
| SIBUR |
| Nizhnekamskneftekhim |
| Goodyear Tire & Rubber Company |
| Cariflex |
| KURARAY CO., LTD. |
| Kraton Corporation |
| TSRC Corporation |
| JSR Corporation |
| Others |
Value Network & Pricing Analysis
Captive isoprene monomer production in Siberian and Japanese petrochemical corridors anchors both supply security and pricing power for integrated producers serving tire and medical glove manufacturers. This backward integration shields margin structures from feedstock volatility while enabling tiered pricing discrimination across certification grades and end-use segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade latex with FDA 510(k) certification from industrial bale grades and commodity tire compounds. Price differentiation hinges on biocompatibility certification depth and rare-earth catalyst sophistication, with EU MDR compliance timelines adding service premiums. Cost compression in standard tire grades is intensifying because natural rubber spot markets periodically undercut synthetic alternatives. Automotive OEMs exhibit highest price sensitivity due to volume scale and formulation switching costs, while hospital group purchasing organizations accept premium pricing for allergy-protocol compliance.
Supply Chain Analysis
Freight cost differentials between Eurasian production hubs and Asian compounding centers favor regional supply positioning over intercontinental bale shipments. Manufacturing concentrates in Russia, Japan, and Germany, with each cluster drawing from captive naphtha crackers or specialized coordination polymerization units. Raw material dependencies center on isoprene monomer, rare-earth neodymium catalysts, and high-purity solvents for solution processes. Single-source vulnerability runs through Siberian petrochemical complexes supplying SIBUR and Nizhnekamskneftekhim feedstock. Distribution runs through direct sale agreements for certified medical grades and wholesale channels for standard industrial compounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in medical-grade latex tiers where biocompatibility certification scarcity supports pricing power, and in powder-form compounding grades capturing automation-driven technical premiums.
For Market Incumbents: Anticipate regulatory acceleration in EU MDR extractable-protein thresholds by deepening rare-earth catalyst expertise and pre-positioning laboratory certification capacity ahead of notified body backlogs. Defend position against emerging Indian domestic producers by securing multi-year offtake agreements with hospital group purchasing organizations in the United States and NHS supply chains. Prioritize backward integration into isoprene monomer supply where geographic positioning permits. For New Entrants and Emerging Players: Begin with India's PLI scheme medical device localization incentives, where glove production clusters in Gujarat and Maharashtra create captive demand for latex-grade synthetic polyisoprene without requiring immediate FDA 510(k) timelines. Target powder-form compounding grades for automated tire and seal operations in Germany and Japan, where dust-free handling requirements command technical premiums. Pursue toll-manufacturing partnerships with established catalyst-technology holders to bypass rare-earth coordination chemistry expertise scarcity. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale medical-grade certification specialists because EU MDR conformity assessment backlogs create acquisition currency for producers with existing notified body relationships and ISO 10993-23 validated laboratory infrastructure. Long-term viability centers on dual-use production platforms serving both tire OEM sustainable-material quotas and hospital allergy-protocol procurement. Monitor CDSCO regulatory pathway streamlining in India as inflection indicator for geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Monomer | SIBUR's Siberian petrochemical complex sustains cost leadership across Eurasian tire markets. |
| Rare-Earth Catalyst Capacity Expansion | Zeon Corporation's neodymium-based systems enable 96-plus percent cis-1,4 content for rolling-resistance optimization. |
| Medical-Grade Certification Investment | KURARAY CO., LTD.'s ultra-low residual-protein latex captures hospital procurement centralization in the United States. |
| Powder Product Form Manufacturing | Dust-free granular morphologies command technical premiums from automated compounding operations in Germany. |
| Regional Production Footprint in India | PLI scheme incentives attract glove manufacturers to Gujarat and Maharashtra export clusters. |
Research Methodology
Multiple input streams — primary interviews with tire OEM procurement directors, medical glove manufacturing executives, and polymerization R&D leads; secondary validation through customs trade data, SEC filings of listed chemical producers, and ECHA REACH registration databases; plus technical literature on coordination catalyst patents — were reconciled through bottom-up and top-down triangulation. Plant capacity assessments were cross-referenced against downstream offtake agreements and regional compounding operation expansions.
Historical production and consumption patterns were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include application tier, product form morphology, end-user regulatory exposure, and geographic production hub. CAGRs were derived from trend extrapolation moderated by catalyst-technology diffusion curves and hospital procurement centralization rates. Industry-specific forecast inputs incorporated EU tire-labeling penalty schedules and MDR notified body capacity constraints.
Several conditions sit outside the modeled scope, including unscheduled petrochemical complex outages, rare-earth export restriction policies, and natural rubber spot market dislocations. Forecasts reflect assumptions about regulatory enforcement continuity and catalyst-technology licensing availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Wear Liners Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Gum Rosin Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Global Automotive Elastomers Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Reclaimed Rubber Market
Rubber
US Nitrile Gloves Market
Rubber
Rubber Tapes Market
Rubber
Rubber Chemicals Market
Rubber
Rubber Compound Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Cellular Rubber Market
Rubber
Europe Rubber Hose Market
Rubber
Rubber Gloves Market