
 Carrier Infrastructure in Telecom Applications Market | 2026-2036
Carrier Infrastructure in Telecom Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Infrastructure in Telecom Applications Market Outlook
Market Context
The shift from single-source to multi-source equipment procurement is decoupling carrier infrastructure supply chains from traditional vendor lock-in arrangements. Huawei Technologies Co., Ltd. leverages its integrated silicon-to-systems portfolio to sustain pricing leverage in markets where geopolitical restrictions do not apply. Ericsson AB anchors its position through deep R&D commitments to cloud-native core architectures, while Nokia Corporation differentiates via its programmable network processing silicon and fixed-wireless access convergence.
Carrier infrastructure in telecom applications encompasses the physical and virtualized equipment—ranging from packet-optical transport platforms with 400G coherent interfaces to containerized 5G core user plane functions—that enables voice, data, and video traffic aggregation, switching, routing, and delivery across telecommunications networks. This infrastructure operates within stringent latency budgets, often sub-10 milliseconds for edge applications, and serves as the foundational layer for consumer broadband, enterprise connectivity, and mission-critical industrial communications. Within product type segmentation, routers and switches capture the dominant share of capital expenditure as traffic volumes scale, while gateways represent a concentrated margin pool where security and policy enforcement features command premium positioning. Across technology categories, fiber optics deployments lead in absolute investment magnitude, though 5G infrastructure delivers the fastest expansion trajectory as operators densify radio access networks and deploy standalone core networks.
The FCC in the United States enforces supply chain security rules that restrict certain vendor equipment from networks receiving federal Universal Service Fund support, directly reshaping procurement eligible sets for rural carriers. In Europe, the EU Cybersecurity Act and CE marking requirements under the Radio Equipment Directive establish mandatory conformity assessment pathways for network infrastructure placed on the single market. India's TRAI mandates domestic manufacturing-linked incentives through the PLI scheme, conditioning market access for carrier-grade equipment on local value-add thresholds. Stakeholders must monitor how divergent national security certification regimes fragment vendor qualification costs and determine whether to pursue region-specific product variants or absorb compliance overhead through modular platform architectures.
Market Dynamics
The transition from hardware-centric to software-defined networking architectures is fragmenting procurement patterns across carrier infrastructure, as operators decouple control plane intelligence from proprietary silicon to achieve vendor diversification and operational flexibility.
Growth Catalysts
- 5G Standalone Core Mandates:India's TRAI spectrum allocation conditions require operators to deploy cloud-native core networks, accelerating containerized infrastructure procurement cycles.
- Open RAN Interoperability Standards:Germany's BNetzA certification framework for multi-vendor radio access networks is compelling equipment suppliers to publish open interfaces.
- Fiber-to-the-Home Subsidies:The FCC's Rural Digital Opportunity Fund injects capital into last-mile optical deployments, sustaining demand for packet-optical transport platforms.
Market Restraints
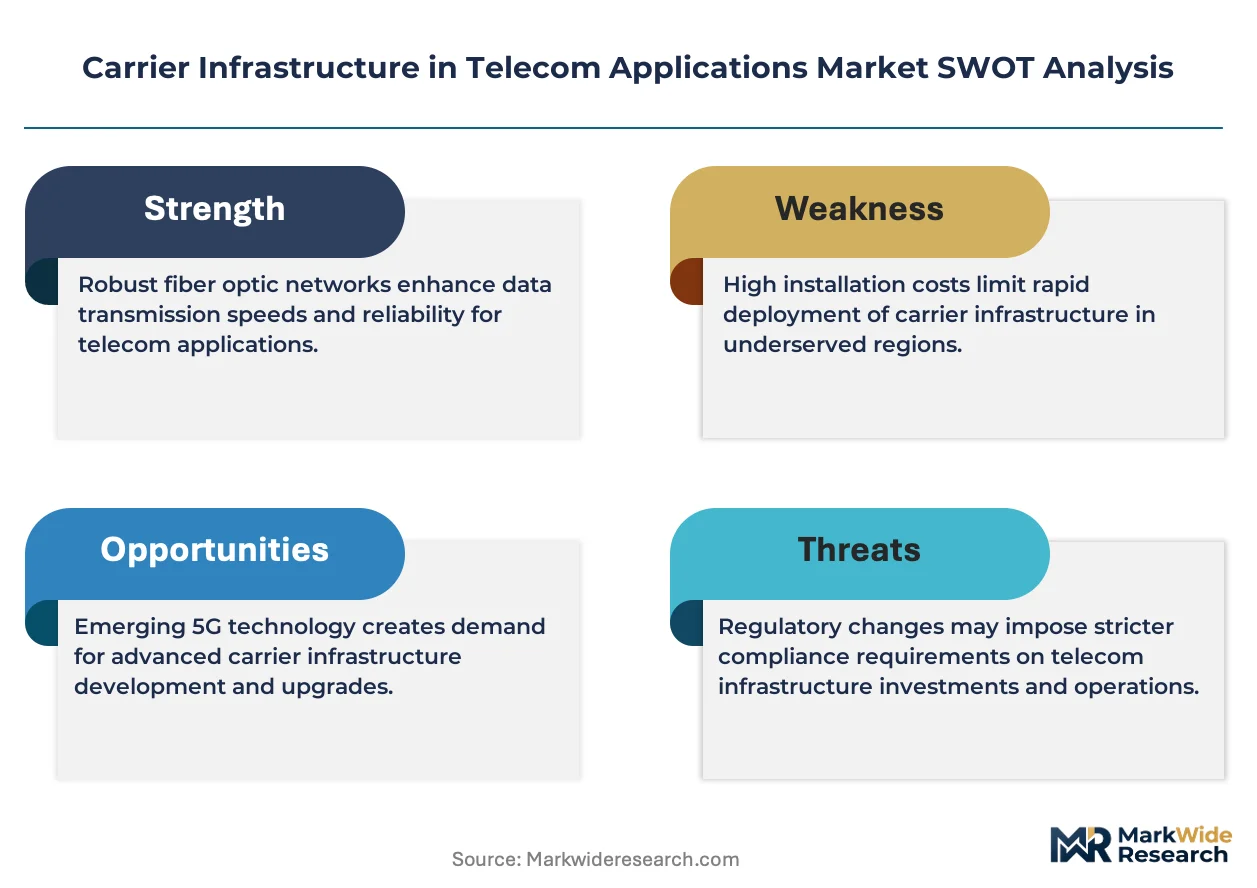
- Advanced Silicon Supply Concentration:Fabrication capacity for 7nm and below network processing chips concentrates among a limited set of foundry operators, creating allocation bottlenecks during demand surges.
- Geopolitical Equipment Bans:The FCC's Covered List and equivalent EU 5G security toolkits exclude certain vendors from networks receiving public funding, compressing eligible supplier pools.
- Optical Component Input Volatility:Erbium-doped fiber amplifiers and coherent DSPs face rare earth element pricing fluctuations that transmit directly to system-level cost structures.
Strategic Opportunities
- Edge Computing Convergence:Integration of radio access networks with distributed cloud infrastructure creates new deployment categories for micro data centers at cell tower sites.
- Domestic Manufacturing Incentives:India's PLI scheme for telecom equipment offers production-linked benefits that reward local assembly of base stations and routers.
- Private Network Verticals:Mining, ports, and manufacturing facilities are procuring dedicated 5G infrastructure outside traditional carrier channels.
Industry Challenges
- Containerized Network Function Integration:Operators struggle to orchestrate legacy physical network elements alongside Kubernetes-managed core functions without service degradation.
- Multi-Vendor Interoperability Testing:Open RAN deployments require extensive system integration validation that extends deployment timelines and strains engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Infrastructure in Telecom Applications Market |
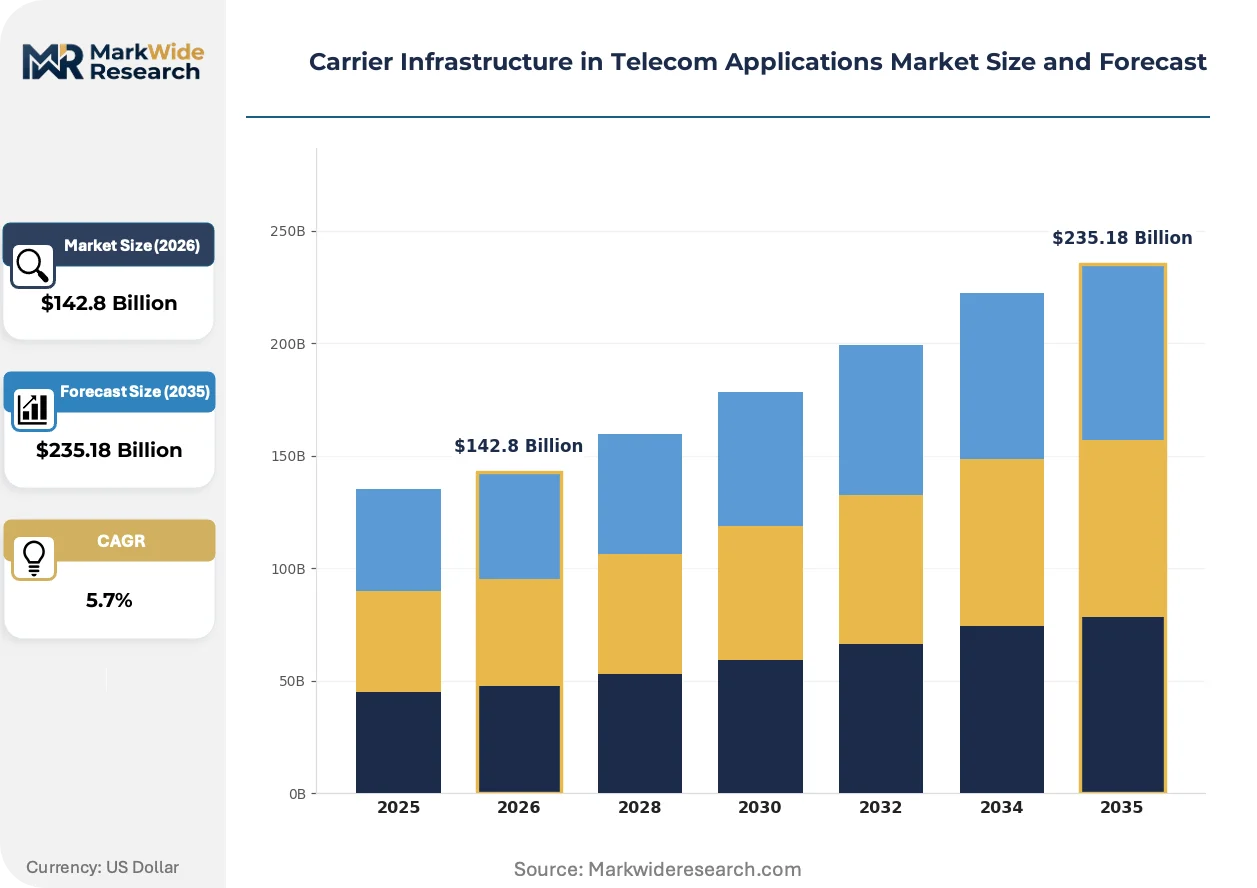
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $235.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Servers, Gateways Technology: 5G, Fiber Optics, VoIP, Microwave End User: Telecom Operators, Enterprises, ISPs, Government Deployment: On-Premise, Cloud-Based, Hybrid, Edge |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson AB, Nokia Corporation, ZTE Corporation, Cisco Systems, Inc., Samsung Electronics Co., Ltd., Qualcomm Technologies, Inc., NEC Corporation, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Infrastructure in Telecom Applications Market Strategic Shifts
Intelligent automation and disaggregated hardware architectures are compressing the traditional equipment refresh cycle while elevating software competency requirements across carrier engineering organizations.
Open RAN is decentralizing radio access network intelligence by separating distributed units, centralized units, and radio units into interoperable components from different suppliers. Tier-one mobile operators in Japan and South Korea are deploying multi-vendor configurations at scale. This architecture is decentralizing supply chain power from integrated equipment vendors toward specialized component suppliers and system integrators.
The EU Cybersecurity Act's Common Criteria certification scheme for network infrastructure is mandating formal security evaluation procedures for equipment placed on the single market. Manufacturers must demonstrate resistance to specified attack vectors through accredited laboratories. Radio access network equipment vendors targeting European deployments are restructuring product development cycles to accommodate certification timelines.
Enterprise self-provisioning of network slices is displacing traditional managed service arrangements for bandwidth-intensive applications. Automotive manufacturers and media broadcasters are contracting directly with infrastructure vendors for guaranteed latency services. This pattern is most pronounced in Germany's industrial corridor, where factory automation requirements exceed standard commercial service level agreements.
Carrier Infrastructure in Telecom Applications Market Segmentation
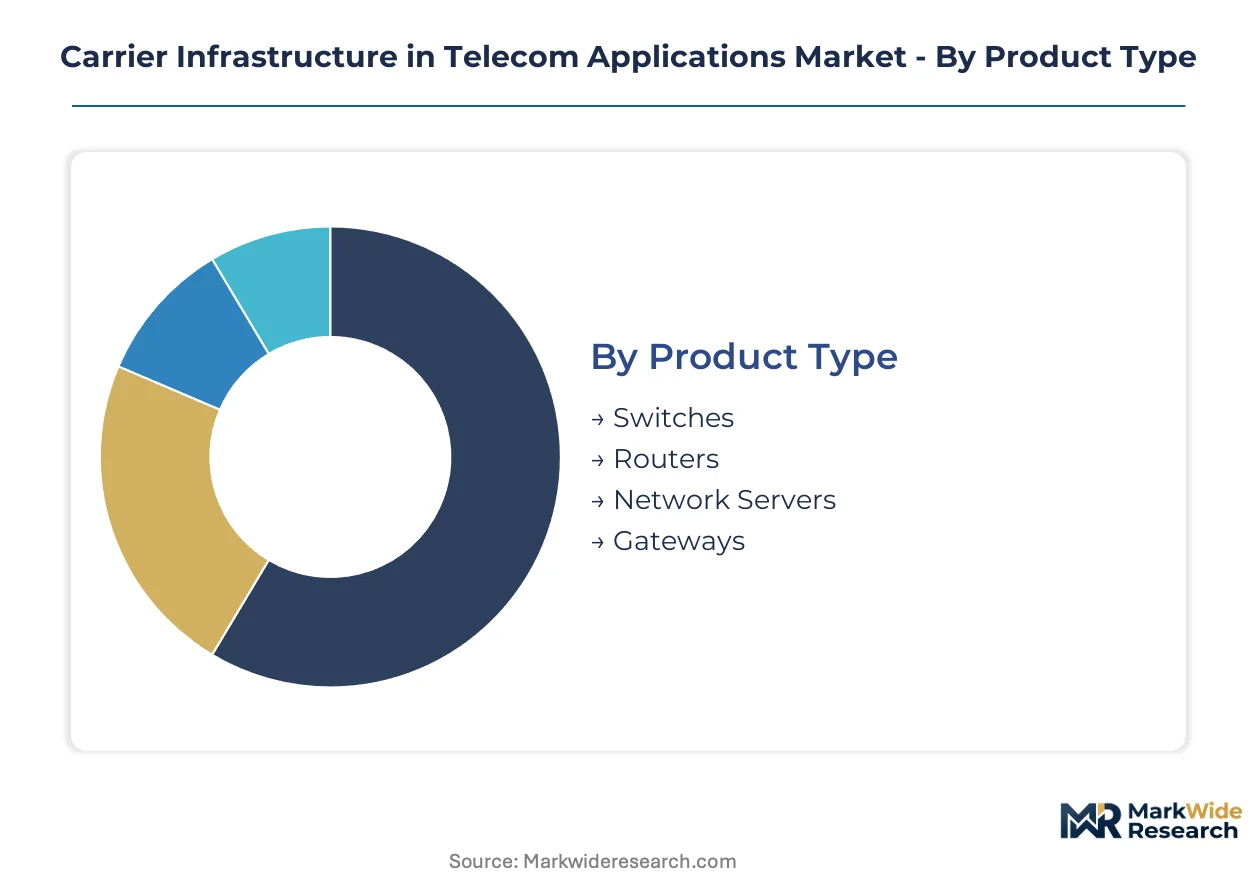
Carrier infrastructure procurement patterns diverge sharply between volume-driven switching hardware and premium-margin gateway systems. Understanding these splits enables vendors to align R&D investment with actual deployment economics across operator, enterprise, and government channels.
Product Type:
Routers and switches dominate capital expenditure volumes, while gateways command concentrated margin pools through embedded security functions.
- Routers:Packet-forwarding platforms with 400G coherent optical interfaces and segment routing capabilities. Demand concentrates among mobile operators densifying 5G transport networks, driven by traffic aggregation requirements at metro core junctions.
- Switches:Ethernet fabric systems spanning access-layer PoE+ units to spine-leaf data center architectures. Enterprise campus refresh cycles in Germany and Japan sustain procurement volumes, constrained by power consumption thresholds in edge deployments.
- Network Servers:Carrier-grade compute nodes hosting virtualized network functions on x86 and ARM architectures.
- Gateways:Policy enforcement points integrating CGNAT, firewall, and SBC functions for traffic handoff.
Mature deployment sits with switches. Newer deployment is concentrated in gateways.
Technology:
Capital allocation tilts toward fiber transport for absolute investment scale, while 5G infrastructure climbs the fastest on standalone core mandates.
- 5G:Radio access networks and cloud-native core systems spanning CU/DU disaggregation and containerized UPF deployment. India's TRAI spectrum conditions accelerate procurement cycles, compelling operators to source open-interface equipment.
- Fiber Optics:DWDM and coherent optical transport platforms with C+L band amplification. Rural broadband subsidies in the United States sustain demand, limited by rare earth element pricing volatility in amplifier supply chains.
- VoIP:Session border controllers and media gateway systems for PSTN transition.
- Microwave:Point-to-point and point-to-multipoint radio links for backhaul in terrain-challenged geographies.
Established infrastructure relies on fiber optics. Accelerating deployment centers on 5G.
End User:
Procurement scale concentrates with telecom operators, though enterprise direct-buy patterns are fragmenting traditional channel structures.
- Telecom Operators:Mobile network operators and fixed-line incumbents building national backbone and access infrastructure. India's BharatNet rural expansion and Germany's 5G densification programs anchor demand, shaped by domestic manufacturing incentive compliance.
- Enterprises:Automotive, mining, and port operators procuring private 5G networks outside carrier channels. Manufacturing automation requirements in Germany's industrial corridor exceed standard commercial SLAs.
- ISPs:Competitive broadband providers overbuilding last-mile infrastructure.
- Government:Defense and public safety networks with classified security certification requirements.
Volume procurement remains with telecom operators. Fastest expansion occurs in enterprise verticals.
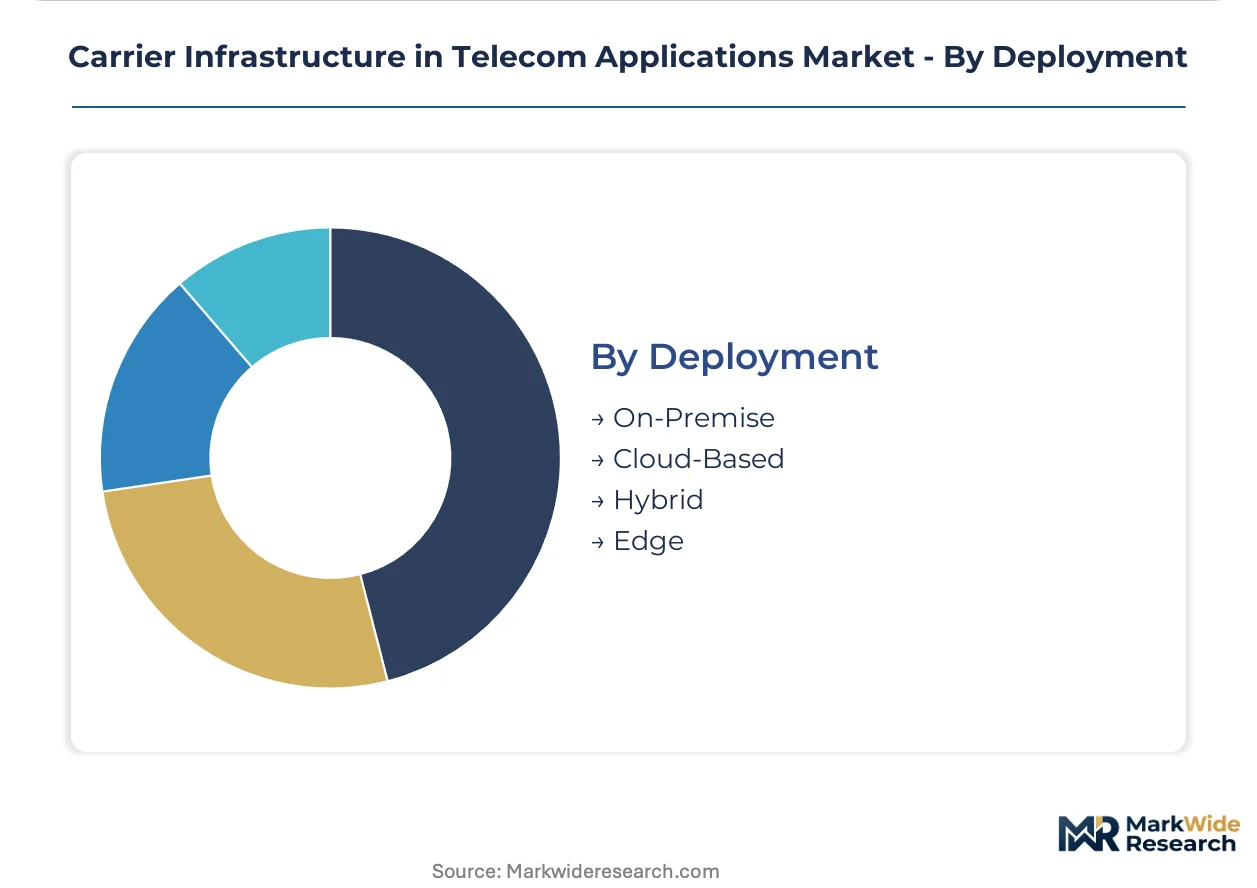
Deployment:
Cloud-native architectures displace hardware-centric models, though hybrid configurations persist for regulatory-sensitive workloads.
- Cloud-Based:Containerized network functions orchestrated via Kubernetes across distributed cloud infrastructure. South Korean operators lead at-scale deployment, constrained by multi-vendor interoperability testing burdens.
- Edge:Micro data centers co-located at cell tower sites converging RAN and compute. Mining and port automation in Australia drives specialized procurement, requiring sub-10 millisecond latency guarantees.
- On-Premise:Dedicated hardware appliances in operator-controlled facilities.
- Hybrid:Split control and user plane architectures spanning private and public cloud domains.
Legacy deployment rests on-premise. Strategic investment flows to edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth element deposits in Inner Mongolia and Jiangxi province supply critical amplifier materials for coherent optical transport systems. This geographic concentration shapes procurement vulnerability for fiber infrastructure vendors worldwide.
United States
Rural broadband subsidies through the FCC's Rural Digital Opportunity Fund drive last-mile fiber deployments. The FCC's Covered List restrictions reshape eligible vendor pools for carriers receiving Universal Service Fund support. Tower densification clusters concentrate in Texas and California metro corridors where operators expand 5G transport backhaul.
Germany
Industrial automation requirements from automotive and manufacturing sectors exceed standard commercial service level agreements. BNetzA certification frameworks for multi-vendor radio access networks compel equipment suppliers to publish open interfaces. The Ruhr industrial corridor and Bavarian manufacturing belt anchor private 5G network procurement outside traditional carrier channels.
India
BharatNet rural fiber expansion accelerates demand for packet-optical transport platforms and domestic assembly of base stations. TRAI spectrum allocation conditions mandate cloud-native core network deployments, conditioning market access on local value-add thresholds through the PLI scheme. Deployment concentrates in Maharashtra and Gujarat where manufacturing incentives attract router and switch assembly operations.
Japan
Multi-vendor Open RAN configurations at scale drive interoperability testing investments from tier-one mobile operators. METI industrial policy supports domestic equipment qualification for cybersecurity resilience. Tokyo-Osaka corridor deployments lead containerized network function integration at cell tower micro data centers.
South Korea
Containerized network functions orchestrated via Kubernetes advance fastest among national operators. Spectrum auction conditions from the Ministry of Science and ICT accelerate standalone 5G core procurement cycles. Seoul Capital Area deployments concentrate edge computing convergence at radio access network sites.
Carrier Infrastructure in Telecom Applications Market Competitive Environment
Global majors compete with regional champions across vendor diversification mandates and domestic manufacturing incentive compliance. The market structure tilts toward consolidated integrated equipment vendors at the high end, with fragmentation among specialized component suppliers serving Open RAN disaggregation. Three archetypes dominate: silicon-to-systems integrated vendors, cloud-native software specialists, and programmable network processing chip designers. Competitive moves center on strategic partnerships for multi-vendor interoperability certification and geographic expansion into PLI-linked manufacturing jurisdictions.
Within the integrated systems tier, Huawei Technologies Co., Ltd. and Ericsson AB occupy positions shaped by divergent geopolitical market access conditions. ZTE Corporation exemplifies the regional champion archetype navigating qualification criteria in markets with domestic manufacturing-linked incentives. Nokia Corporation anchors the programmable silicon differentiation vector where security certification and policy enforcement features command premium positioning.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson AB |
| Nokia Corporation |
| ZTE Corporation |
| Cisco Systems, Inc. |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies, Inc. |
| NEC Corporation |
| Fujitsu Limited |
| Others |
Value Chain & Pricing Dynamics
Rare earth element indices for erbium and ytterbium feed directly into coherent optical amplifier cost structures, cascading through three distinct pricing tiers that separate federally subsidized rural deployments from premium enterprise gateway systems and unbundled component procurement.
Pricing Analysis
Extended warranty and field service bundling separate premium router and switch offerings from standard catalog pricing, with multi-year support contracts commanding 15-25% uplifts over bare equipment transactions. Three-tier pricing structure across premium, standard, and economy levels reflects divergent security certification grades, with Common Criteria EAL4+ equipment targeting government and defense buyers while CE-marked commercial variants serve enterprise campus refresh cycles. Cost compression in the mid-tier switch segment is intensifying because Indian PLI scheme beneficiaries are flooding export markets with locally assembled units. Price sensitivity peaks among competitive ISPs overbuilding last-mile infrastructure, while mining and port operators procuring private 5G networks demonstrate minimal elasticity for sub-10 millisecond latency guarantees.
Supply Chain Analysis
Dual-sourcing mandates from Germany's BNetzA and India's TRAI compel mobile operators to qualify second vendors for radio units and baseband silicon, fragmenting procurement volumes across integrated suppliers and specialized component vendors. Fabrication capacity for 7nm network processing chips concentrates in Taiwan, South Korea, and the United States, while rare earth element refining for optical amplifiers feeds from Chinese Inner Mongolia and Jiangxi province deposits. Single-source vulnerability in coherent DSP supply creates allocation bottlenecks during demand surges, particularly when South Korean operators accelerate standalone 5G core deployments. Distribution runs through direct operator procurement teams for carrier-grade volumes, with systems integrators and value-added resellers handling enterprise private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier infrastructure procurement is consolidating around vendors capable of absorbing compliance overhead across fragmented national security regimes, squeezing mid-tier suppliers lacking modular platform architectures or domestic manufacturing credentials.
For Market Incumbents: Anticipate margin compression from Open RAN disaggregation by deepening programmable silicon differentiation through security certification investments targeting EU Cybersecurity Act pathways. Anchor position in India through PLI-compliant local assembly operations for routers and base stations, defending against ZTE Corporation's regional champion model. Prioritize cloud-native core partnerships with South Korean and Japanese operators leading containerized network function deployment at scale.
For New Entrants and Emerging Players: India's PLI scheme for telecom equipment opens a window for component specialists to capture base station assembly contracts conditioned on local value-add thresholds. Target Germany's industrial corridor for private 5G network opportunities where factory automation requirements exceed standard commercial SLAs and systems integration capabilities command premium positioning. Pursue direct enterprise sales channels bypassing traditional carrier procurement, particularly for mining and port automation verticals in Australia requiring edge computing convergence at cell tower sites.
For Investors and Strategic Acquirers: Distressed-cycle entries favor programmable network processing chip designers with existing security certification portfolios in European and Asia-Pacific jurisdictions. Long-term viability hinges on backward integration into photonic component supply or captive rare earth element sourcing arrangements that insulate against amplifier input volatility. Monitor BNetzA and TRAI interoperability certification timelines as inflection indicators for vendor qualification windows that determine addressable market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | BNetzA and TRAI mandates compel interface publication, reshaping vendor qualification criteria. |
| Domestic Manufacturing Footprint Expansion | India's PLI scheme rewards local assembly with production-linked incentives conditioning market access. |
| Cloud-Native Core Platform Development | Kubernetes-orchestrated network functions displace hardware-centric models in South Korean deployments. |
| Programmable Silicon Security Certification | EU Cybersecurity Act Common Criteria pathways enable premium positioning in European government networks. |
| Edge Computing Convergence Partnership | Micro data center co-location at cell tower sites serves Australian mining automation latency requirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with network engineering directors at tier-one mobile operators, procurement leads at competitive ISPs, regulatory affairs specialists navigating FCC and TRAI compliance, and systems integration managers handling Open RAN deployments. FCC Covered List determinations, EU Cybersecurity Act certification databases, and India's PLI scheme beneficiary disclosures provided vendor eligibility and domestic manufacturing volume benchmarks. Bottom-up equipment shipment tracking across router, switch, and gateway categories reconciled with top-down carrier capital expenditure disclosures from SEC filings and earnings transcripts.
Data-stream reconciliation across operator procurement databases, foundry capacity utilization reports, and rare earth element trade flows enabled segmentation modeling by product type, technology category, deployment architecture, and end-user channel across the projection horizon. 5G standalone core deployment timelines, fiber-to-the-home subsidy disbursement rates, and private network vertical adoption curves served as industry-specific forecast inputs. CAGRs were derived from equipment volume trajectories mapped against spectrum auction schedules and rural broadband program funding cycles.
The model assumes a particular technology adoption path; alternative pathways for Open RAN disaggregation or containerized network function migration would alter the outlook if multi-vendor interoperability testing burdens extend deployment timelines beyond modeled assumptions. Deviation in rare earth element export restrictions or foundry allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Communication Repeater Market