
 Telecom Network Infrastructure Market | 2026-2036
Telecom Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Network Infrastructure Market Analysis
The gap between premium carrier-grade equipment and commodity white-box hardware is recalibrating procurement strategies across tier-one and tier-two operators. Cisco Systems leverages its merchant silicon partnerships to sustain margin structures in enterprise routing. Nokia anchors its position through in-house production of optical line terminals and PON chipsets.
Telecom network infrastructure encompasses the physical and virtualized equipment, transmission media, and management systems that enable voice, data, and video communication across geographic distances, typically operating at latency thresholds below 10 milliseconds for 5G core applications and throughput rates exceeding 100 Gbps per fiber strand. Its primary purpose is to guarantee reliable, scalable connectivity for consumer, enterprise, and machine-to-machine traffic. Fiber optics within the technology dimension leads capital deployment as operators replace legacy copper with GPON and XGS-PON architectures. Cloud-based deployment is expanding fastest among enterprises seeking elastic capacity without dedicated on-premises capital.
The FCC governs spectrum allocation and equipment authorization in the United States, while the ETSI framework shapes interoperability standards across European member states, and India's TRAI regulates tariff structures and quality-of-service mandates. These bodies collectively determine which vendors gain market access and which technical specifications become mandatory for commercial deployment. Stakeholders must track spectrum reallocation timelines and open RAN interoperability certifications to anticipate shifts in supplier competitiveness.
Market Dynamics
The transition from purpose-built hardware to software-defined architectures is compressing vendor margins while expanding deployment velocity for operators managing multi-vendor environments. Open RAN specifications from the O-RAN Alliance are decoupling radio unit hardware from baseband software, forcing incumbent suppliers to defend proprietary ecosystems against merchant silicon alternatives.
Growth Catalysts
- FCC C-band reallocation:Mid-band spectrum releases in the United States are accelerating 5G densification timelines, driving fresh capital deployment for macro and small-cell infrastructure.
- India BharatNet fiber mandate:The Department of Telecommunications is subsidizing rural optical fiber deployment, creating sustained demand for GPON equipment and passive components.
- Cloud provider capacity expansion:Hyperscale data center operators are procuring 400G and 800G optical transceivers at volume, pulling investment into coherent DSP and silicon photonics supply chains.
Market Restraints
- Merchant silicon concentration:Advanced 5nm and 3nm fabrication for networking ASICs concentrates at Taiwan-based foundries, exposing supply continuity to geopolitical friction.
- Copper legacy maintenance burden:Incumbent operators in developed markets face stranded asset costs from decades-old copper plant that cannot be fully depreciated before fiber overbuild.
- Open RAN interoperability gaps:Missing conformance testing for fronthaul timing synchronization creates deployment risk that slows multi-vendor integration timelines.
Strategic Opportunities
- Private 5G enterprise networks:Manufacturing campuses and port logistics operators in India and Germany are deploying localized cellular infrastructure, bypassing public operator dependency.
- XGS-PON upgrade cycles:Cable operators and independent fiber providers are leapfrogging GPON for 10G symmetric architectures, opening replacement revenue for optical line terminal vendors.
- EU Green Deal energy mandates:Network equipment power consumption regulations are creating preference for liquid-cooled routers and energy-efficient optical amplifiers in European procurement specifications.
Industry Challenges
- RF engineer scarcity:mmWave antenna design and massive MIMO beamforming expertise concentrates at a handful of vendors and research institutions, constraining rollout velocity.
- Multi-vendor integration complexity:Operators assembling disaggregated transport networks face protocol mismatch between optical transport, IP routing, and microwave backhaul layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Network Infrastructure Market |
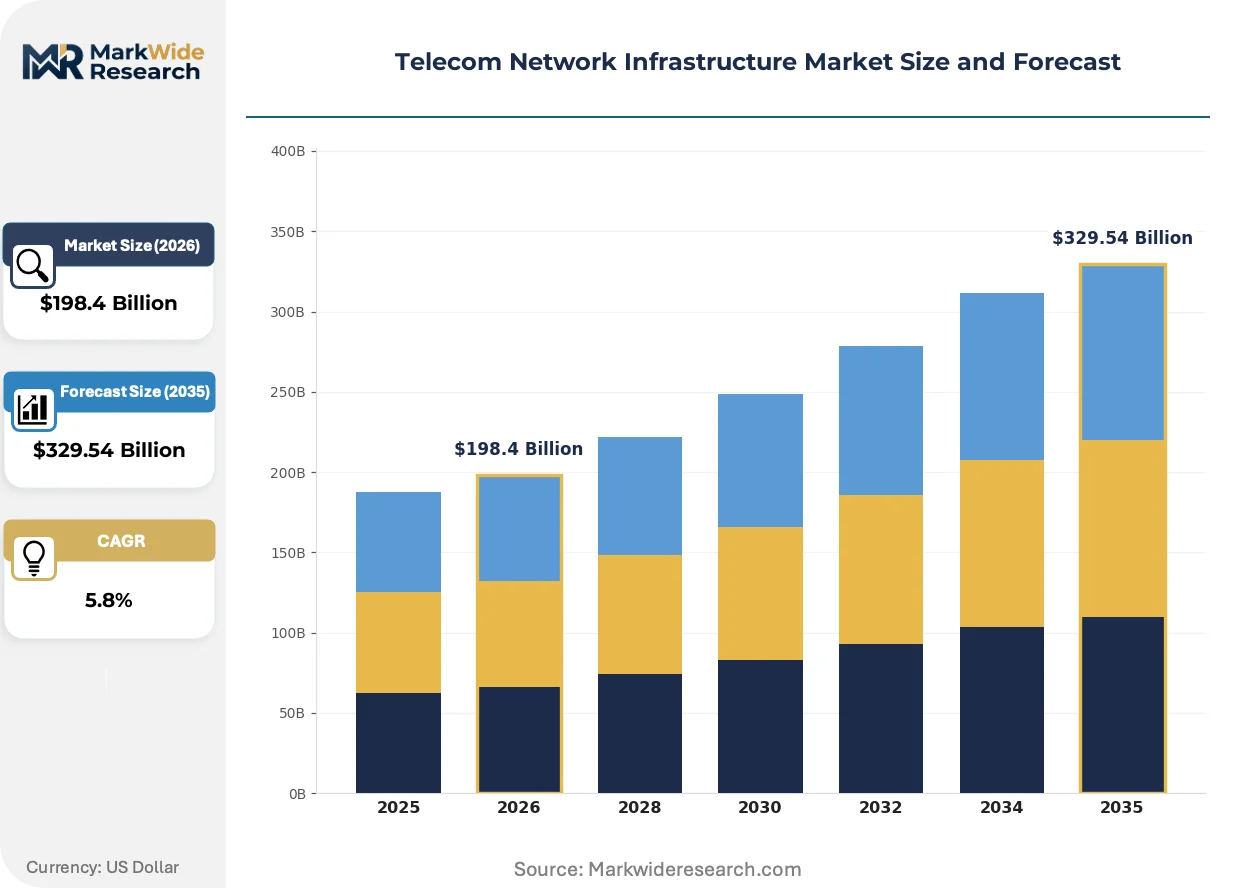
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $329.54 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
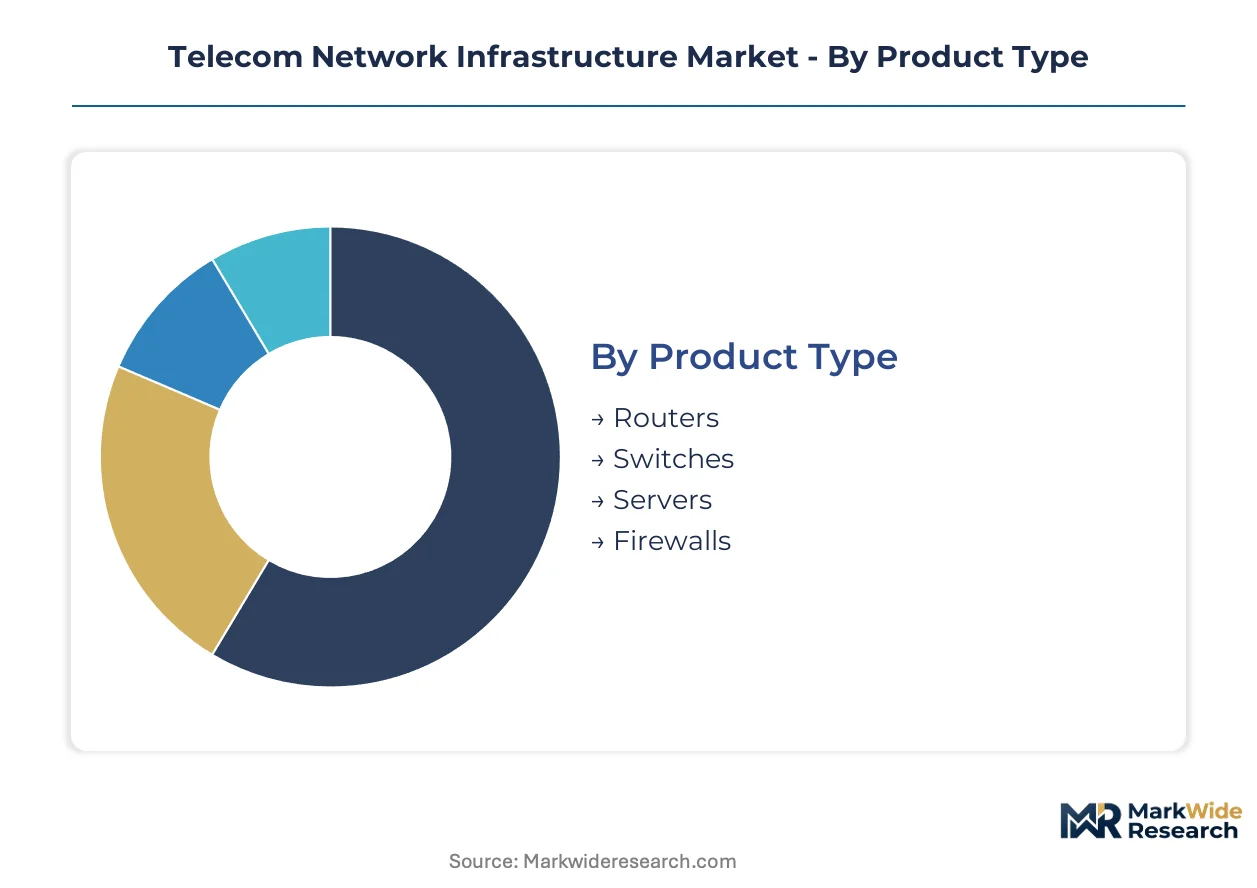
| Segmentation | Product Type: Routers, Switches, Servers, Firewalls Technology: SDN, NFV, 5G, Fiber Optics End User: Telecom Operators, Enterprises, ISPs, Government Deployment: On-premises, Cloud-based, Hybrid, Co-located |
| Companies Covered | Cisco Systems, Samsung Electronics, Huawei Technologies, Intel, Qualcomm, Ericsson, ZTE, Broadcom, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Network Infrastructure Market Emerging Trajectories
Virtualization of network functions is collapsing the traditional boundary between hardware procurement and software licensing, rewriting how operators evaluate total cost of ownership across ten-year asset lifecycles.
Coherent optical technology is absorbing increasing signal processing complexity directly onto pluggable transceiver modules, eliminating discrete DSP shelves in metro aggregation nodes. Cloud operators and content delivery networks are adopting 400G ZR and ZR+ optics at scale for data center interconnect. This compression is absorbing capital that previously flowed to standalone optical transport platforms.
ETSI's F-Gas Regulation is phasing down hydrofluorocarbon use in network equipment cooling systems, accelerating adoption of dielectric fluid immersion and two-phase evaporative cooling in European deployments. Equipment vendors are redesigning thermal architectures to maintain power density without conventional refrigerants. Router and switch manufacturers serving EU markets are requalifying product lines for sealed liquid-cooled enclosures.
Enterprise buyers are consolidating vendor relationships around full-stack infrastructure providers capable of delivering optical transport, routing, and security policy as unified subscriptions. Systems integrators and value-added resellers are losing attach revenue to direct operator-managed service contracts. This concentration is most visible in North American financial services and healthcare verticals where compliance automation requirements favor single-source accountability.
Telecom Network Infrastructure Market Segmentation
Telecom network infrastructure procurement diverges sharply across buyer sophistication and workload requirements. Each segmentation axis reveals distinct margin structures and vendor competitive dynamics.
Product Type:
Standardization dominates at the hardware layer while software-defined control planes enable customization.
- Routers:Carrier-grade chassis systems process traffic at 100+ Tbps aggregate throughput with programmable forwarding ASICs. Tier-one operators in India and Germany are consolidating vendor relationships around full-stack routing platforms to reduce interoperability testing overhead.
- Switches:Data center spine-leaf architectures deploy 400G and 800G port densities with merchant silicon from Broadcom and Marvell. Hyperscale cloud providers drive volume procurement for top-of-rack and aggregation layers, compressing margins for traditional enterprise switch vendors.
- Servers:Telco edge compute nodes combine x86 processing with hardware accelerators for 5G packet core functions.
- Firewalls:Next-generation platforms integrate deep packet inspection with zero-trust policy enforcement at network boundaries.
Leading the category by volume: Switches. Growing fastest: Routers.
Technology:
Deployment maturity separates proven transport layers from emerging virtualization stacks still proving interoperability.
- Fiber Optics:Coherent DSP-enabled transceivers now embed 800G line rates in pluggable QSFP-DD form factors, collapsing standalone optical transport shelf requirements. India's BharatNet rural fiber mandate sustains demand for GPON and XGS-PON optical line terminals.
- 5G:Massive MIMO radio units and distributed unit/baseband unit splits enable open RAN disaggregation. Mid-band spectrum reallocation by the FCC accelerates macro and small-cell densification timelines across United States metropolitan clusters.
- SDN:Centralized controllers separate forwarding hardware from policy logic, enabling multi-vendor transport abstraction.
- NFV:Virtualized network functions replace purpose-built appliances with software running on commodity compute.
Fiber optics commands the largest installed base. NFV exhibits the steepest expansion trajectory as operators virtualize packet core and radio access network functions.
End User:
Procurement scale and technical specification authority vary dramatically across public network operators versus private infrastructure owners.
- Telecom Operators:Incumbent carriers manage multi-generational technology stacks with stringent five-nines reliability requirements. Capital deployment concentrates on 5G core modernization and fiber backhaul densification.
- Enterprises:Manufacturing campuses and logistics hubs in Germany deploy private 5G networks with localized spectrum licenses, bypassing public operator dependency for deterministic latency.
- ISPs:Competitive fiber overbuilders and cable operators upgrade access networks to XGS-PON symmetric architectures.
- Government:Defense and critical infrastructure mandates prioritize supply chain security and domestic sourcing requirements.
Telecom operators lead capital deployment. Enterprises are climbing the fastest as private cellular adoption accelerates.
Deployment:
Control over physical infrastructure versus operational flexibility defines the trade-off matrix for this category.
- Cloud-based:Hyperscale operators provision network functions as elastic services without dedicated capital expenditure. ETSI NFV standards enable portability across cloud provider substrates.
- Hybrid:Sensitive control plane functions remain on-premises while user plane traffic bursts to cloud capacity during peak demand.
- On-premises:Regulated financial services and healthcare verticals mandate dedicated hardware for compliance audit trails.
- Co-located:Equipment resides in carrier-neutral data centers with cross-connect access to multiple network providers.
On-premises retains the largest footprint. Cloud-based deployment is gaining share fastest among mid-market enterprises seeking operational agility.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's Electronics City corridor anchors India's telecom equipment manufacturing and software development clusters, drawing fiber optic component suppliers and 5G baseband developers into concentrated R&D ecosystems. This metropolitan concentration shapes procurement patterns across the broader market.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are deploying 400G and 800G coherent optics at unprecedented density for data center interconnect. The FCC's C-band reallocation has accelerated mid-band 5G densification timelines, with small-cell installations concentrating in Atlanta and Chicago metropolitan corridors where municipal permitting processes have streamlined.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria are procuring private 5G networks for deterministic factory automation, bypassing public operator dependency. The EU Green Deal's energy efficiency mandates are reshaping router procurement specifications toward liquid-cooled architectures. Munich and Stuttgart host concentrated testing facilities for open RAN interoperability certification.
India
The Department of Telecommunications' BharatNet mandate is driving rural optical fiber deployment across Maharashtra and Gujarat, sustaining demand for GPON and XGS-PON optical line terminals. TRAI's quality-of-service regulations enforce latency thresholds that favor domestic equipment sourcing. Chennai's manufacturing corridor is emerging as a hub for passive optical component fabrication.
China
MIIT's 5G base station deployment targets are concentrating capital expenditure in Yangtze River Delta manufacturing zones, particularly Suzhou and Hangzhou, where optical transceiver assembly lines operate at scale. The country's dual carbon goals are accelerating energy-efficient baseband unit designs. Shenzhen's electronics ecosystem supplies merchant silicon for global networking ASIC production.
Japan
METI's Beyond 5G promotion council is funding R&D for 6G precursor technologies in Tokyo and Osaka metropolitan laboratories. KDDI and NTT DoCoMo are densifying millimeter-wave small cells in dense urban corridors ahead of Olympic legacy infrastructure utilization. Yokohama's port logistics operators are piloting private cellular networks for automated container handling.
Telecom Network Infrastructure Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the merchant silicon versus proprietary ASIC divide, with in-house fabrication capabilities commanding pricing power in optical transport. The vendor base stratifies into three tiers: integrated systems houses with end-to-end portfolios, optical component specialists with captive chip design, and white-box assemblers reliant on merchant silicon. Dominant competitive moves include backward integration into semiconductor fabrication and strategic partnerships with hyperscale cloud operators for co-development of data center interconnect standards.
Within the integrated systems tier, Cisco Systems and Nokia exemplify divergent margin architectures—Cisco leveraging merchant silicon partnerships for enterprise routing flexibility, Nokia anchoring position through captive production of optical line terminals and PON chipsets. Ericsson occupies a position between these models, with Samsung Electronics representing the Korean chaebol structure that combines semiconductor fabrication with systems integration. These three entities collectively illustrate how geographic industrial policy shapes competitive positioning in 5G infrastructure procurement cycles.
| Leading Market Players |
|---|
| Cisco Systems |
| Samsung Electronics |
| Huawei Technologies |
| Intel |
| Qualcomm |
| Ericsson |
| ZTE |
| Broadcom |
| Nokia |
| Others |
Supply Flow & Price Mechanics
Carrier-grade certification tiers separate premium optical transport vendors from commodity white-box assemblers, with this bifurcation manifesting in divergent margin architectures and sourcing geographies. TRAI's domestic equipment mandates in India and the EU Green Deal's energy-efficiency procurement rules reshape where vendors establish captive production versus merchant silicon dependency.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for 5G core and optical transport equipment, with Nokia and Cisco commanding premiums for sub-10-millisecond latency SLAs. Price differentiation rests on merchant silicon flexibility versus proprietary ASIC performance, with hyperscale cloud buyers squeezing margins through volume aggregation while government buyers absorb certification premiums. Pricing pressure stems from Open RAN disaggregation commoditizing radio unit hardware. Tier-two operators exhibit highest price sensitivity; defense and critical infrastructure buyers show lowest.
Supply Chain Analysis
India's phased manufacturing program and TRAI local-content requirements are pulling optical line terminal assembly from Taiwan and China into Chennai and Bengaluru corridors. Advanced 5nm and 3nm networking ASIC fabrication concentrates at Taiwan-based foundries, with merchant silicon supply drawing from Broadcom and Marvell design centers in the United States. Single-source vulnerability at TSMC exposes supply continuity to geopolitical friction. Distribution runs through direct hyperscale procurement contracts and tier-one operator framework agreements.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around full-stack infrastructure providers as Open RAN interoperability gaps and merchant silicon concentration squeeze subscale vendors toward exit or acquisition.
For Market Incumbents: Deploy captive optical chipset production to defend margin structures against merchant silicon commoditization. Nokia's in-house PON fabrication and Cisco's merchant silicon partnerships illustrate divergent defensive architectures. Incumbents must absorb stranded copper legacy costs while accelerating XGS-PON upgrade cycles to capture replacement revenue.
For New Entrants and Emerging Players: Begin with private 5G enterprise networks in German manufacturing corridors and Indian port logistics zones, where localized spectrum licenses bypass entrenched operator relationships. White-box optical transceiver assembly for hyperscale data center interconnect offers penetrable volume entry. Channel strategy should prioritize direct cloud provider engineering partnerships over traditional systems integrator routes.
For Investors and Strategic Acquirers: Re-rating potential sits with optical component specialists possessing captive DSP design capabilities given coherent 800G pluggable adoption acceleration. Long-term viability favors vendors with backward integration into silicon photonics and liquid-cooled thermal architectures. Watch FCC C-band auction completion timelines and O-RAN Alliance conformance certification milestones as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Photonics | Captive DSP and coherent transceiver design secures margin control against merchant silicon commoditization. |
| Open RAN Interoperability Certification | O-RAN Alliance conformance testing unlocks multi-vendor procurement frameworks at tier-one operators. |
| Private 5G Enterprise Network Deployment | Localized spectrum licenses in Germany and India bypass public operator dependency for manufacturing campuses. |
| XGS-PON Access Network Upgrade | 10G symmetric fiber architectures leapfrog GPON, opening replacement cycles for optical line terminal vendors. |
| Liquid-Cooled Thermal Architecture Redesign | EU F-Gas Regulation compliance creates procurement preference for dielectric fluid immersion in European deployments. |
Methodological Framework
SEC 10-K filings, hyperscaler capex disclosures, and ETSI standardization documents formed the secondary backbone, supplemented by customs records for optical transceiver trade flows. Primary fieldwork engaged network equipment procurement directors at tier-one operators, optical component R&D leads, and cloud provider infrastructure engineers across the United States, Germany, and India. Bottom-up and top-down triangulation validated vendor shipment data against operator deployment announcements.
Bottom-up modeling aggregated product-level volume assumptions across routers, switches, optical transport, and 5G radio access infrastructure, while top-down analysis cross-checked aggregate expenditure patterns against national broadband subsidy programs. Segmentation dimensions included deployment model, end-user archetype, and technology layer. CAGRs derived from fitted growth curves incorporating FCC spectrum reallocation timelines and BharatNet fiber deployment targets.
Underlying measurement precision varies by segment; hyperscale cloud procurement carries tighter precision than private 5G enterprise estimates due to disclosure transparency differences. Forecasts embed assumptions around O-RAN interoperability maturation and foundry capacity allocation that could shift with regulatory or geopolitical developments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market