
 China Telecom Equipment Market | 2026-2036
China Telecom Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Telecom Equipment Market Insights
Integrated base station and antenna bundling is expanding as state-owned telecom operators consolidate vendor relationships and simplify procurement workflows. Huawei Technologies leverages captive semiconductor fabrication to sustain component supply continuity under trade restrictions. ZTE Corporation anchors domestic 5G rollout contracts through cost-competitive massive MIMO portfolios. Nokia Oyj competes for multinational enterprise accounts by differentiating its cloud-native core platforms.
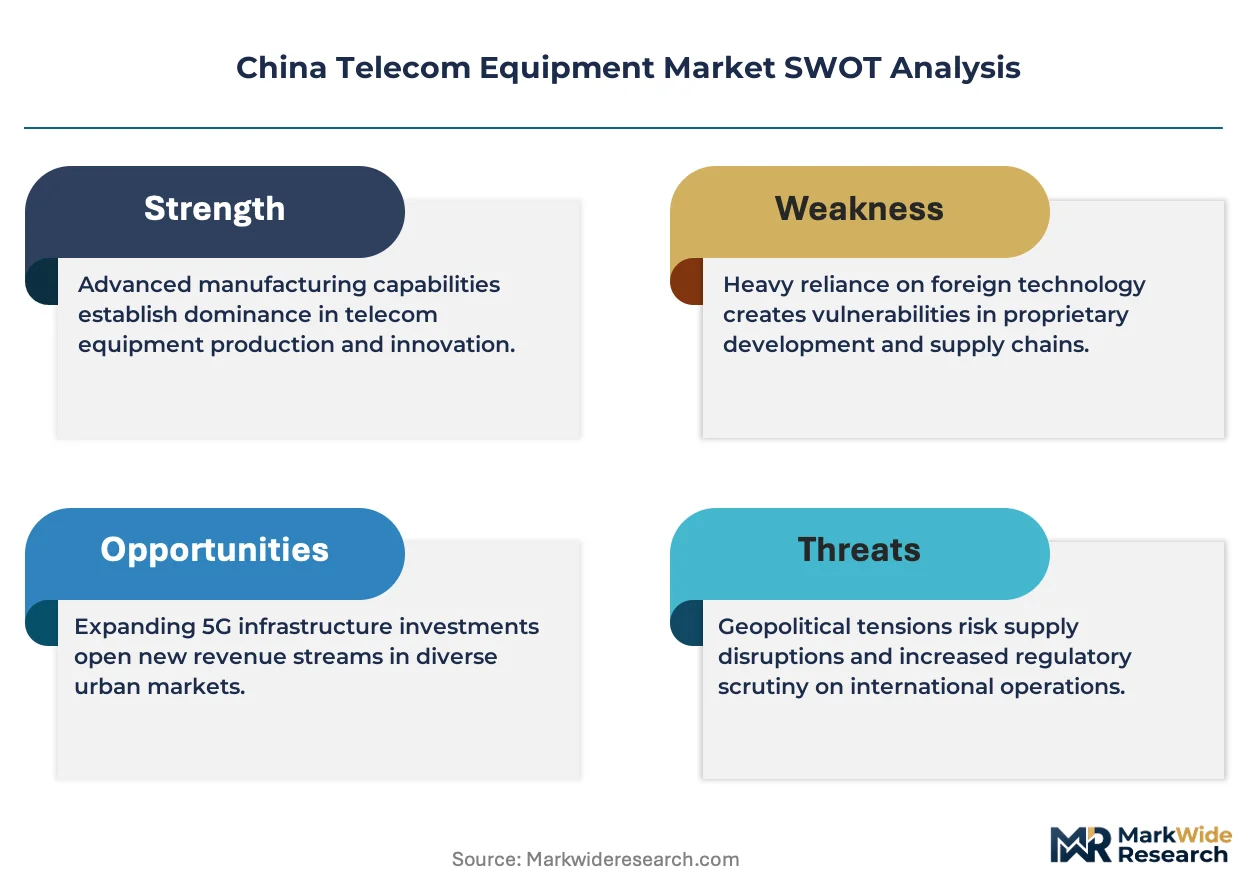
China telecom equipment comprises switching systems, routing platforms, radio access nodes, and transmission infrastructure engineered to operate within 2.6 GHz, 3.5 GHz, and 4.9 GHz 5G NR bands with latency specifications below one millisecond for ultra-reliable low-latency communication scenarios. Switches and routers constitute the mature revenue backbone where margin compression from domestic rivals has intensified, while base stations and antennas capture accelerated investment flows tied to 5G-Advanced network densification mandates. Fiber optics technology leads capital deployment in backbone and metro networks, whereas SDN architectures attract enterprise and ISP migration budgets seeking programmable traffic management.
MIIT enforces GB standards compliance and network access licenses that gate market entry for foreign suppliers, while SAMR monitors anti-competitive conduct among dominant domestic manufacturers. NMPA equipment certification procedures extend testing timelines for imported radio transmission products, effectively tilting procurement toward locally certified vendors. Stakeholders must monitor MIIT's 6G pre-standardization working groups and SAMR pricing investigations to anticipate the next wave of regulatory-driven vendor reshuffling.
Market Dynamics
State-owned operator procurement consolidation is compressing vendor margins while MIIT 5G-Advanced densification mandates accelerate equipment refresh cycles across eastern coastal manufacturing clusters.
Growth Catalysts
- Smart city infrastructure mandates:Guangdong province municipal governments are accelerating integrated 5G procurement for urban IoT backbone networks.
- GB standards localization:Domestic certification requirements under MIIT spectrum reallocations tilt procurement toward locally tested radio transmission equipment.
- Massive MIMO deployment:Base station densification in Shenzhen and Shanghai manufacturing corridors drives sustained capital deployment into radio access infrastructure.
Market Restraints
- Semiconductor supply concentration:Advanced node fabrication dependency creates input cost volatility for baseband processor procurement.
- NMPA certification timelines:Extended testing procedures for imported radio transmission products create regulatory friction for foreign vendor market entry.
- Fiber optic backbone saturation:Mature metro network penetration limits incremental capital allocation to transmission infrastructure upgrades.
Strategic Opportunities
- Western province network extension:Underpenetrated Sichuan and Shaanxi provincial markets offer whitespace for rural 5G coverage expansion.
- Enterprise SDN migration:Programmable traffic management adoption by domestic ISPs creates new revenue pools outside state-owned operator channels.
- Dual carbon energy efficiency mandates:MEE power consumption standards for telecom infrastructure create regulatory tailwind for low-energy base station designs.
Industry Challenges
- Millimeter-wave RF engineering scarcity:Specialized antenna design talent shortages constrain 5G-Advanced product development timelines.
- Legacy 4G infrastructure integration:Non-standalone architecture complexity with existing core networks prolongs deployment testing cycles.
- SAMR pricing investigations:Anti-competitive conduct monitoring of dominant domestic manufacturers creates compliance uncertainty for procurement negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Telecom Equipment Market |
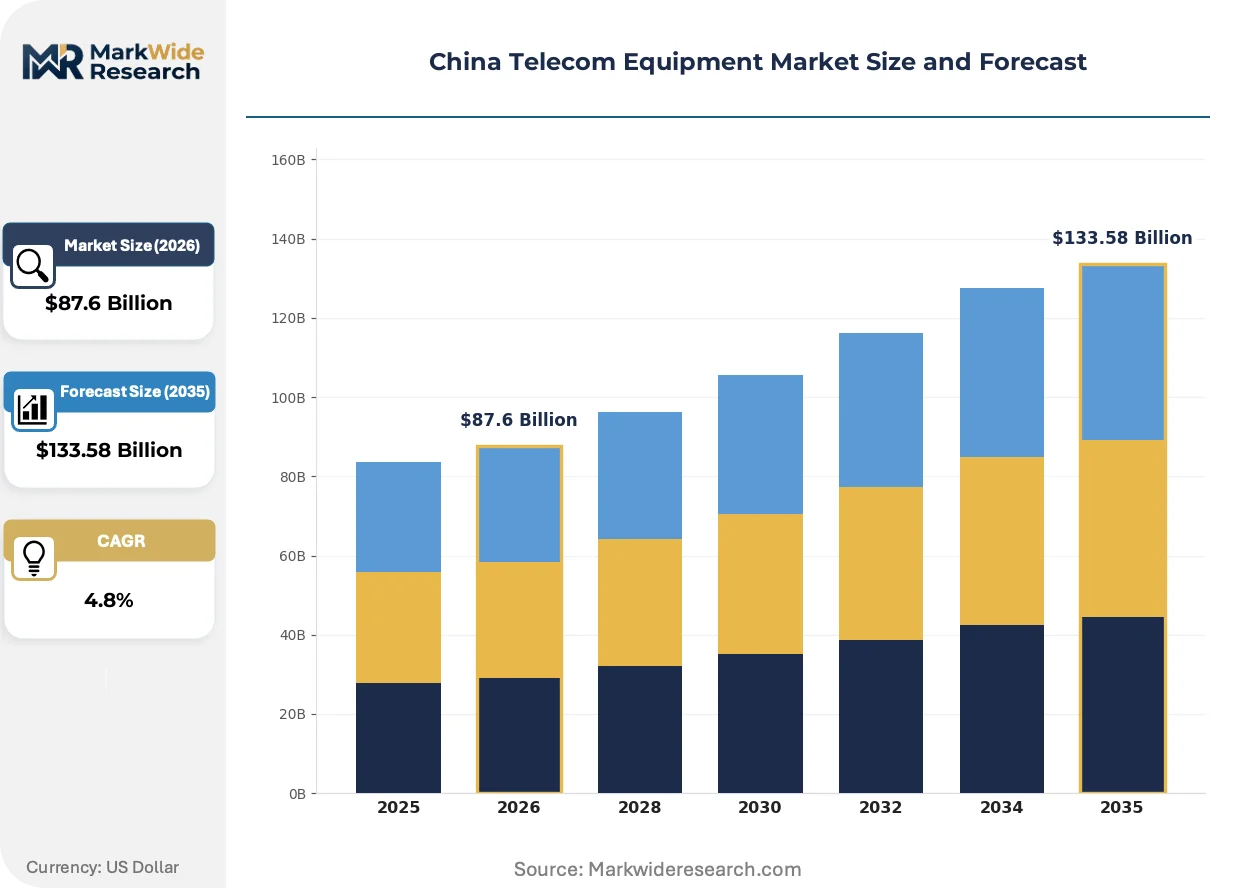
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Base Stations, Antennas Technology: 5G, Fiber Optics, LTE, SDN End User: Telecom Operators, Enterprises, Government, ISP Service Type: Maintenance, Installation, Consulting, Support |
| Companies Covered | Huawei Technologies, ZTE Corporation, Foxconn Industrial Internet, Nokia Oyj, Ericsson, Cisco Systems, Samsung Electronics, Juniper Networks, Alcatel-Lucent Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Telecom Equipment Market Trends and Innovations
Open RAN disaggregation is fragmenting traditional vendor lock-in structures while programmable silicon and cloud-native architectures compress hardware refresh cycles across operator procurement portfolios.
Massive MIMO antenna arrays is modularizing radio access node deployment, allowing municipal operators in Guangdong to phase 5G-Advanced upgrades without full site replacement. State-owned carriers are adopting disaggregated radio units to reduce vendor dependency. This architecture is modularizing supply chain relationships and enabling multi-vendor interoperability at cell tower sites.
MIIT GB standards compliance for network access licenses is tightening product certification requirements, extending testing timelines for imported radio transmission equipment. Domestic manufacturers capture procurement preference through pre-certified product portfolios. Foreign suppliers face compressed addressable market share as SAMR monitors pricing conduct among dominant local vendors.
Integrated base station and antenna bundling is consolidating procurement workflows among state-owned operators, displacing discrete component purchasing. Municipal governments in Shenzhen and Shanghai manufacturing clusters favor single-vendor responsibility models. Eastern coastal demand concentration reinforces vendor relationship consolidation over multi-source technical evaluation.
China Telecom Equipment Market Segmentation
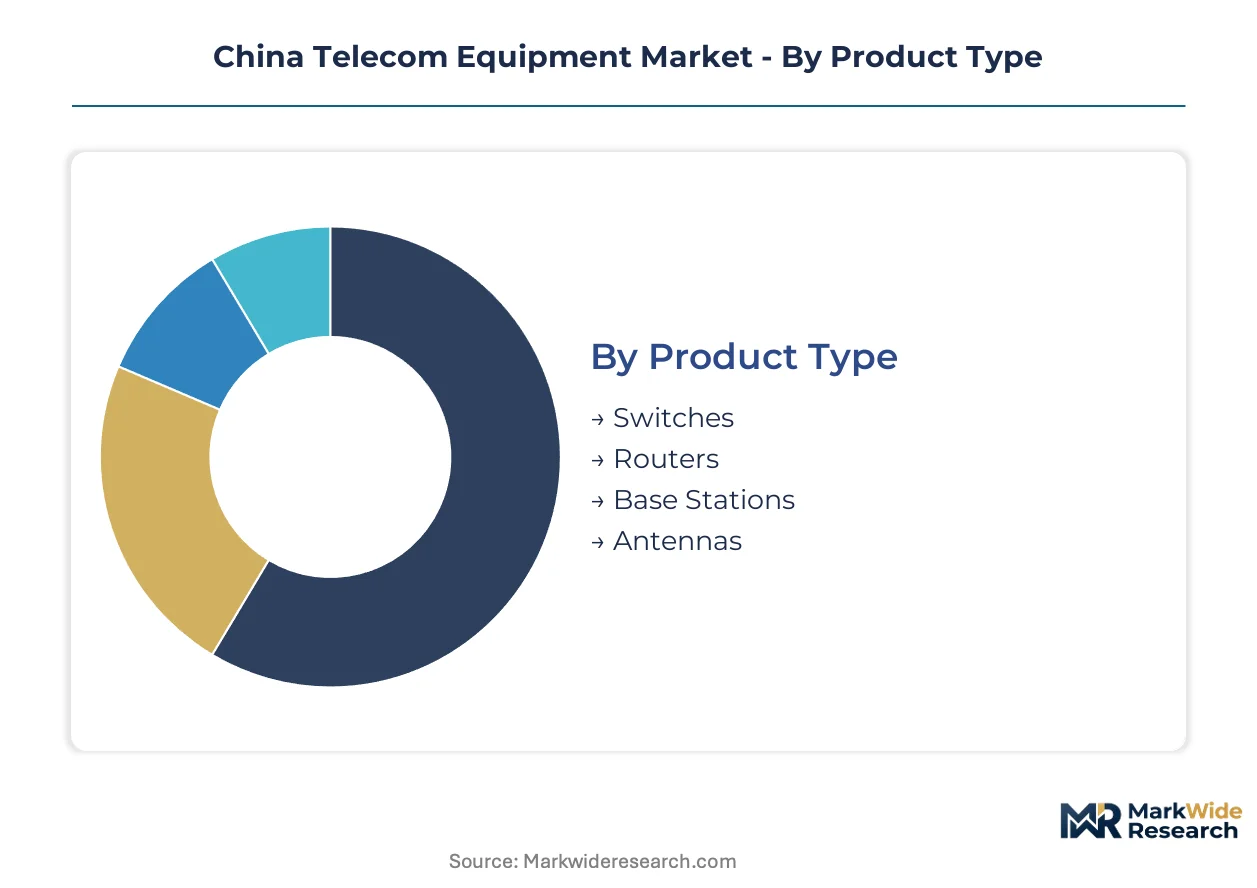
Equipment segmentation in China reveals how capital deployment priorities split between mature infrastructure refresh and next-generation network buildouts. Procurement patterns diverge sharply across product types and end-user channels, with state-owned operators driving volume while enterprise and government verticals reshape technology roadmaps.
Product Type:
Base stations and antenna systems command the heaviest upfront capital commitments, requiring tower real estate, power infrastructure, and spectrum licensing before revenue generation begins.
- Base Stations:Radio access nodes engineered for 2.6 GHz, 3.5 GHz, and 4.9 GHz 5G NR bands with sub-one-millisecond latency specifications. Demand concentrates in Shenzhen and Shanghai manufacturing corridors where MIIT densification mandates accelerate massive MIMO deployment cycles.
- Antennas:Modular massive MIMO arrays enabling phased 5G-Advanced upgrades without full site replacement. Guangdong province municipal governments favor integrated antenna-base station bundling to simplify smart city procurement workflows.
- Switches:Core and edge switching platforms constitute the mature revenue backbone where domestic rival competition has intensified margin compression.
- Routers:IP routing infrastructure for backbone and metro networks facing procurement consolidation as state-owned operators reduce vendor counts.
Most installed capacity flows through base stations. Expansion is steepest in antennas as network densification outpaces macro site deployment.
Technology:
Technology selection tracks directly to application latency requirements and deployment geography, with fiber optics dominating backbone routes while 5G captures mobile access investment.
- 5G:NR infrastructure spanning sub-6 GHz and millimeter-wave spectrum allocations. Eastern coastal clusters anchor deployment volume, though western province extensions into Sichuan and Shaanxi create whitespace for rural coverage expansion.
- Fiber Optics:Backbone and metro transmission infrastructure leads capital deployment in mature markets. MEE dual carbon energy efficiency standards now filter procurement toward low-power optical transport designs.
- SDN:Programmable traffic management architectures attract enterprise and ISP migration budgets seeking operational flexibility outside state-owned operator procurement channels.
- LTE:Legacy 4G infrastructure supporting non-standalone 5G architectures prolongs integration testing cycles but sustains equipment refresh demand in coverage-gap regions.
Fiber optics carries the largest installed base. SDN is climbing the fastest as programmable infrastructure displaces hardware-centric legacy systems.
End User:
End-user segmentation exposes diverging procurement authority structures, with state-owned operators wielding volume leverage while government verticals dictate localization requirements.
- Telecom Operators:China Mobile, China Telecom, and China Unicom dominate equipment procurement through centralized tender processes. Vendor consolidation trends favor integrated solution providers capable of single-source responsibility across radio access and transport layers.
- Government:Municipal authorities in Guangdong province drive smart city infrastructure mandates with accelerated 5G procurement for urban IoT backbone networks. MIIT GB standards compliance requirements tilt procurement toward pre-certified domestic vendors.
- Enterprises:Manufacturing and logistics facilities in Shanghai and Shenzhen manufacturing clusters adopt private 5G networks for ultra-reliable low-latency communication scenarios.
- ISP:Internet service providers represent an emerging channel for SDN and edge routing equipment as programmable traffic management adoption expands.
Telecom operators absorb the majority of installed capacity. Government verticals are gaining share fastest as smart city mandates proliferate across provincial jurisdictions.
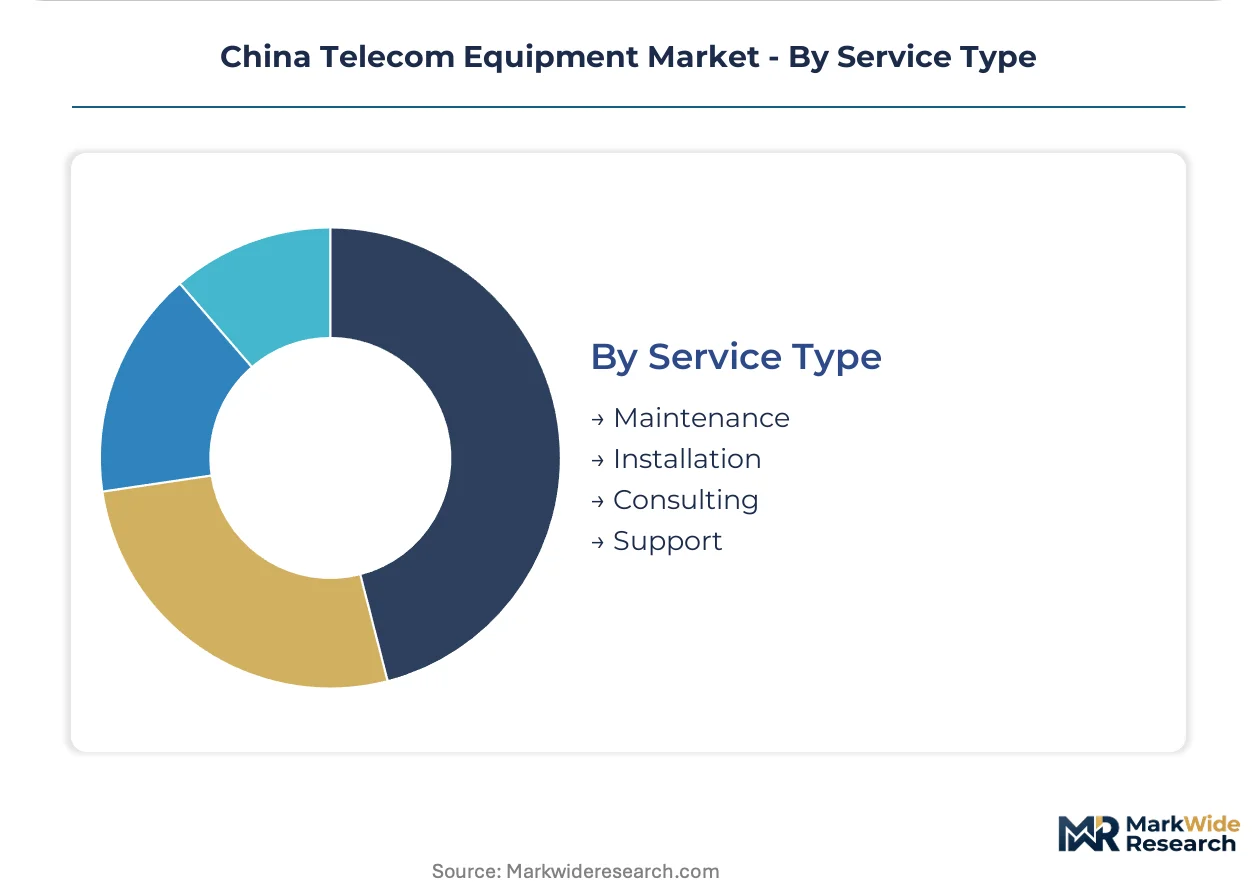
Service Type:
Service segmentation reflects the shift from discrete equipment sales toward lifecycle revenue models, with maintenance contracts capturing recurring value as installation margins compress.
- Maintenance:Preventive and corrective service contracts for radio access and transport infrastructure. State-owned operators increasingly bundle multi-year maintenance into initial procurement tenders to lock in vendor accountability.
- Installation:Site preparation, tower integration, and commissioning services face margin pressure as vendor consolidation reduces competitive tension.
- Consulting:Network planning and optimization advisory for 5G-Advanced migration strategies, particularly in enterprise private network deployments.
- Support:Technical assistance and spare parts logistics sustaining operational continuity under MIIT network access license requirements.
Maintenance commands the largest revenue pool. Consulting is expanding most quickly as 5G-Advanced complexity drives demand for specialized engineering guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's telecom equipment industry traces its modern scale to state-led infrastructure buildouts beginning in the 1990s, when domestic manufacturing clusters in Guangdong and Jiangsu provinces absorbed technology transfer programs and established component ecosystems that persist today.
Guangdong Province
Shenzhen and Guangzhou municipal governments drive smart city infrastructure procurement through integrated 5G backbone mandates for urban IoT networks. MIIT GB standards compliance requirements tilt procurement toward pre-certified domestic vendors with established local testing records. The Pearl River Delta manufacturing corridor concentrates base station and antenna production capacity, with Shenzhen anchoring massive MIMO deployment cycles tied to 5G-Advanced densification timelines.
Shanghai and Jiangsu Province
State-owned operator tender consolidation accelerates equipment refresh cycles across the Yangtze River Delta manufacturing belt. SAMR monitors pricing conduct among dominant domestic manufacturers, creating compliance uncertainty for procurement negotiations. Shanghai's Pudong and Zhangjiang high-tech zones host dense concentrations of semiconductor fabrication and radio frequency engineering talent serving baseband processor supply chains.
Beijing-Tianjin-Hebei
MIIT headquarters proximity shapes regulatory pre-standardization access for vendors participating in 6G working groups. NMPA equipment certification procedures extend testing timelines for imported radio transmission products, reinforcing procurement preference for locally certified portfolios. The Zhongguancun technology corridor anchors state-backed research institutes and operator headquarters driving centralized vendor selection criteria.
Sichuan and Shaanxi Provinces
Western province network extension programs target underpenetrated rural coverage gaps with cost-optimized radio access infrastructure. MEE dual carbon energy efficiency standards filter procurement toward low-power base station designs for grid-constrained deployment zones. Chengdu and Xi'an technology parks attract secondary manufacturing investments as eastern coastal land and labor costs escalate.
Shandong Peninsula
Qingdao and Yantai port cities leverage maritime cable landing infrastructure to anchor submarine transmission equipment maintenance hubs. Provincial industrial policy supports fiber optic backbone manufacturing clusters serving northern China metro network expansion. Local government procurement favors integrated solution providers capable of single-source responsibility across radio access and transport layers.
China Telecom Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and state-owned operator relationship tenure. The vendor base stratifies into three tiers: integrated solution providers with captive semiconductor supply, cost-competitive massive MIMO specialists, and multinational enterprise-focused platform vendors. Consolidation pressures intensify as operator procurement reduces vendor counts. Dominant competitive moves include strategic partnerships with municipal smart city authorities and backward integration into radio frequency component fabrication.
Within the integrated solution tier, Huawei Technologies and ZTE Corporation occupy positions shaped by state-backed infrastructure mandates and GB standards pre-certification advantages. Nokia Oyj exemplifies the multinational enterprise platform archetype competing through cloud-native differentiation. These three anchors demonstrate how vendor archetypes map to distinct procurement channels: state-owned operator volume tenders, municipal government smart city programs, and multinational enterprise private network deployments.
| Leading Market Players |
|---|
| Huawei Technologies |
| ZTE Corporation |
| Foxconn Industrial Internet |
| Nokia Oyj |
| Ericsson |
| Cisco Systems |
| Samsung Electronics |
| Juniper Networks |
| Alcatel-Lucent Enterprise |
| Others |
Pricing and Supply Chain Analysis
State-owned carrier procurement consolidation anchors pricing discipline across vendor tiers, compressing margins for foreign suppliers while captive semiconductor fabrication at Huawei and ZTE insulates domestic players from input cost volatility. MIIT GB standards certification creates procurement preference premiums that separate pre-certified domestic portfolios from extended-timeline imports.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated solution providers with captive chip supply from cost-competitive massive MIMO specialists and multinational enterprise platform vendors. Price differentiation hinges on MIIT certification status and state-owned operator relationship tenure, with foreign vendors facing downward pressure from SAMR pricing investigations and domestic rival competition. Municipal governments in Guangdong exhibit highest price sensitivity for smart city bundles, while enterprise private network deployments show lowest sensitivity to premium positioning.
Supply Chain Analysis
Direct-to-operator channels handle state-owned carrier tender volume, with integrated base station-antenna bundling displacing discrete component procurement workflows. Component sourcing draws from Taiwan for advanced node semiconductors, South Korea for memory and display technologies, and domestic China for passive components and mechanical assemblies. Single-source vulnerability in baseband processor fabrication creates structural risk, particularly under trade restriction exposure for foreign-dependent vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in vendors controlling upstream radio frequency component production and those capturing premium positioning in enterprise SDN migration outside state-owned channels.
For Market Incumbents: Deploy backward integration into radio frequency component fabrication to defend against semiconductor supply concentration risks. Consolidate vendor relationships with municipal smart city authorities in Guangdong to secure recurring maintenance revenue pools. Counter Nokia Oyj cloud-native differentiation by accelerating 5G-Advanced massive MIMO product cycles. For New Entrants and Emerging Players: Enter via western province network extension programs targeting Sichuan and Shaanxi rural coverage gaps with cost-optimized radio access designs. Capture whitespace in enterprise SDN migration for domestic ISPs seeking programmable traffic management outside operator procurement channels. Lead with MEE dual carbon energy efficiency compliance as a procurement door-opener. For Investors and Strategic Acquirers: Valuations sit cheapest among cost-competitive massive MIMO specialists lacking captive semiconductor supply but holding state-owned operator contract tenure. Long-term viability favors integrated solution providers with backward integration depth and GB standards pre-certification advantages. Monitor MIIT 6G pre-standardization working group participation as an inflection signal for next-cycle vendor positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Component Fabrication | Captive semiconductor supply insulates Huawei and ZTE from trade restriction input volatility. |
| MIIT GB Standards Pre-Certification Investment | Accelerated network access licensing tilts procurement toward pre-certified domestic portfolios. |
| Enterprise SDN Platform Development | Programmable traffic management captures ISP budgets outside state-owned operator channels. |
| Western Province Rural Coverage Expansion | Sichuan and Shaanxi whitespace offers volume growth as eastern markets approach saturation. |
| Smart City Authority Partnership Consolidation | Single-vendor responsibility models lock in multi-year maintenance revenue with Guangdong municipalities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with telecom operator procurement directors, MIIT regulatory affairs specialists, municipal smart city project managers, and base station RF engineering leads with secondary validation from MIIT spectrum allocation notices, SAMR pricing investigation disclosures, NMPA equipment certification records, and state-owned carrier tender documentation. Bottom-up equipment shipment modeling and top-down infrastructure capex analysis provided cross-verification.
Historical reference periods anchored the projection framework across the analysis window, with segmentation modeling spanning product type, technology, end user, and service type dimensions alongside MIIT regulatory cluster and provincial deployment geography. CAGRs derived from equipment procurement volume trajectories, adjusted for 5G-Advanced densification mandates and fiber optic backbone saturation effects.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time vendor pricing disclosure introduce uncertainty bands around competitive positioning assessments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Spain Telecom Towers Market