
 Kenya Telecom Tower Market | 2026-2036
Kenya Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Telecom Tower Market Insights
Shared infrastructure bundling is realigning how carriers procure tower access in Kenya. Safaricom PLC leverages its extensive captive tower portfolio to control rollout timelines in dense urban zones. Airtel Kenya Ltd competes through aggressive neutral-host partnerships that reduce capital intensity in secondary cities. Telkom Kenya anchors rural expansion by specializing in microwave-backhaul lattice towers where fiber penetration remains thin.
Kenya telecom towers are steel or concrete structures engineered to support multi-tenant antenna arrays at heights typically ranging from 30 to 120 meters, designed for wind loads exceeding 160 km/h and engineered for rapid co-location of radio equipment from multiple carriers. The primary commercial purpose is to host base transceiver stations that extend mobile voice and data coverage while minimizing redundant capital deployment across overlapping geographies. 4G infrastructure still occupies the dominant revenue share given Kenya's ongoing digital migration timeline, though 5G-ready monopole deployments are gathering momentum in Nairobi and Mombasa. Neutral-host ownership models are capturing margin pools as carriers prioritize operational expenditure over balance-sheet-heavy tower construction.
The Communications Authority of Kenya enforces infrastructure-sharing regulations that compel operators to co-locate on existing structures before greenfield construction, directly compressing carrier-owned deployment rates while elevating tower-company valuations. Kenya Bureau of Standards certification for structural integrity and electromagnetic emissions shapes procurement criteria and disqualifies uncertified imports from Chinese and South Asian suppliers. Stakeholders must monitor spectrum auction timing and rural universal service fund disbursements to anticipate where tower demand will outpace available grid power and diesel-hybrid alternatives.
Market Dynamics
The Communications Authority of Kenya's infrastructure-sharing mandate is compressing carrier-owned tower construction while elevating independent tower company valuations through forced co-location before greenfield permits.
Growth Catalysts
- 4G Rural Coverage Mandates:The Universal Service Fund's disbursement priorities are channeling capital toward underserved counties, accelerating lattice tower deployment in regions where fiber backhaul remains economically unviable.
- Communications Authority Co-location Rules:Regulatory compulsion to exhaust existing structure capacity before new construction is consolidating tenant density per tower and improving independent tower company revenue per site.
- Diesel-Hybrid Power Innovation:Solar-battery hybridization of off-grid tower sites is reducing operational expenditure burdens and extending economically viable coverage into Kenya's northeastern corridor.
Market Restraints
- Steel Input Cost Volatility:Fluctuations in global hot-rolled steel prices are compressing fabrication margins for lattice and monopole structures, forcing procurement hedging through East African regional suppliers.
- Grid Electrification Gaps:Kenya Power's rural distribution limitations necessitate expensive diesel generator backup at 40% of tower sites, inflating lifetime operational costs beyond urban benchmarks.
- Electromagnetic Emissions Certification:Kenya Bureau of Standards compliance timelines for radiation safety testing are extending equipment commissioning cycles and delaying tenant revenue recognition.
Strategic Opportunities
- Turkana and Marsabit County Expansion:Underpenetrated northern territories present first-mover advantages for neutral-host operators willing to absorb higher initial capex for microwave backhaul infrastructure.
- 5G-Ready Monopole Pre-positioning:Nairobi's metropolitan corridor and Mombasa port zone offer concentrated demand for compact multi-tenant structures capable of millimeter-wave antenna accommodation.
- Power Purchase Agreement Aggregation:Bundling rural tower energy demand is unlocking preferential solar-hybrid tariffs from independent power producers under Kenya's feed-in tariff framework.
Industry Challenges
- Structural Engineering Talent Scarcity:Certified tower design specialists capable of Kenya Bureau of Standards wind-load calculations are concentrated in Nairobi, creating project bottlenecks for upcountry deployments.
- Multi-Tenant Integration Complexity:Co-location of incompatible radio equipment from competing carriers demands sophisticated interference mitigation and physical segregation protocols that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Telecom Tower Market |
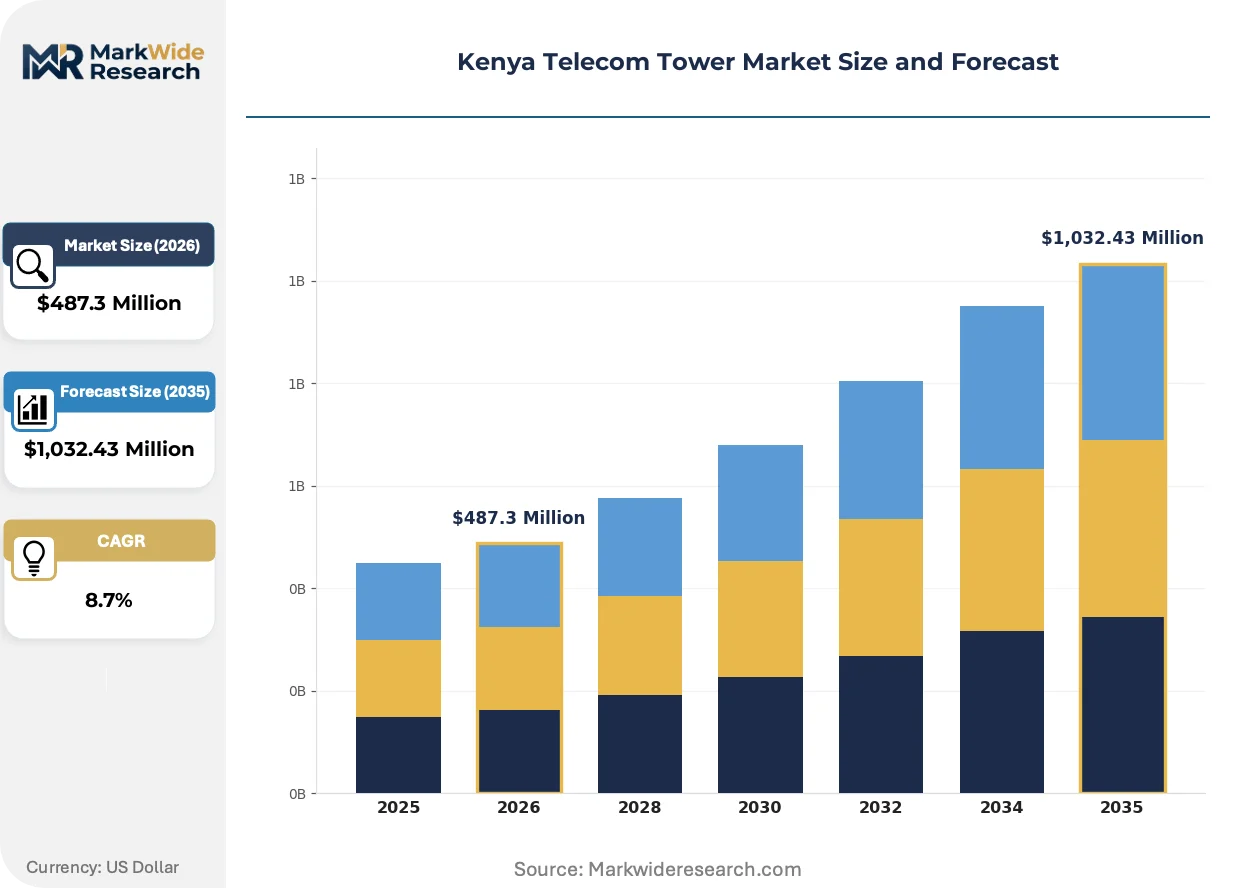
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 4G, 5G, LTE, Microwave Ownership Model: Carrier-Owned, Neutral Host, Tower Company, Shared Deployment Type: Urban, Suburban, Rural, Remote Infrastructure Type: Monopole, Lattice Tower, Rooftop, Micro Tower |
| Companies Covered | Finserve Africa Limited (Equitel), Jamii Telecommunications Limited (Faiba), Safaricom PLC, Axian Telecom, Liquid Home, Telkom Kenya, Wananchi Group, Communications Authority of Kenya, Airtel Kenya Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Telecom Tower Market Trends and Innovations
Steel lattice configurations optimized for microwave backhaul are yielding ground to lighter monopole designs as 5G densification priorities reshape antenna loading requirements across Kenyan urban corridors.
Monopole structures with integrated concealment shrouds are overtaking exposed lattice towers in Nairobi's metropolitan planning zones. Safaricom PLC and Airtel Kenya Ltd are prioritizing these designs for suburban mall and residential cluster deployments where aesthetic compliance accelerates municipal permitting. The shift is compressing demand for traditional four-legged lattice fabrication while elevating specialized monopole engineering capabilities among local steel contractors.
The Communications Authority of Kenya's 2023 infrastructure-sharing enforcement guidelines are mandating technical interoperability standards for multi-tenant access. Tower operators must now pre-certify structural load documentation and power distribution specifications before carrier lease agreements, adding compliance layers that favor established neutral-host portfolios over captive carrier facilities. Secondary cities including Nakuru and Eldoret are experiencing the most acute implementation friction as smaller operators adapt documentation systems.
Carrier procurement departments are consolidating tower access negotiations through master service agreements rather than site-by-site contracting. This behavioral shift concentrates buying power with neutral-host operators possessing standardized national portfolios, marginalizing fragmented regional tower owners in Kisumu and coastal zones. The model is most visible in Safaricom PLC's recent framework agreements that bundle Nairobi metropolitan access with rural county coverage commitments.
Kenya Telecom Tower Market Segmentation

Segmentation in Kenya's telecom tower market reveals how technology choices, ownership structures, and deployment contexts interact to shape procurement economics. Each dimension carries distinct implications for capital intensity, regulatory exposure, and tenant mix optimization.
Technology:
Integration depth varies sharply across radio technologies, with some functioning as standalone coverage layers and others requiring embedded backhaul dependencies.
- 4G:Mature LTE-Advanced infrastructure dominates current tenant revenue across Nairobi's metropolitan corridor and surrounding satellite towns. Universal Service Fund disbursements target 4G rural mandates, sustaining lattice tower demand in counties where fiber backhaul remains economically unviable.
- 5G:Millimeter-wave-ready monopole deployments are gathering momentum in dense urban zones. Communications Authority spectrum auction timing determines rollout velocity, with Nairobi and Mombasa carriers pre-positioning compact multi-tenant structures for antenna densification.
- LTE:Legacy FDD-LTE equipment still anchors voice fallback and IoT connectivity in secondary cities. Network modernization cycles are gradually displacing these assets in favor of 5G-ready hardware.
- Microwave:Point-to-point backhaul links serve as embedded transport layers rather than standalone access technologies. Turkana and Marsabit county expansions depend on microwave relay chains where grid power and fiber penetration are both thin.
4G leads volumes today; 5G is gaining share fastest.
Ownership Model:
Cost tier stratification separates balance-sheet-heavy construction from operational expenditure models, reshaping how carriers manage tower economics.
- Carrier-Owned:Captive portfolios like Safaricom PLC's extensive tower base enable rollout timeline control in dense urban zones. Infrastructure-sharing mandates are compressing greenfield construction rates for this segment.
- Neutral Host:Independent operators capture margin pools as regulatory compulsion elevates co-location density per site. Aggressive partnerships from Airtel Kenya Ltd demonstrate how this model reduces capital intensity in secondary cities.
- Tower Company:Specialized infrastructure firms with standardized national portfolios concentrate buying power through master service agreements. Documentation pre-certification requirements favor established players over fragmented regional owners.
- Shared:Multi-tenant access structures mandated by Communications Authority rules before greenfield permits. Technical interoperability standards add compliance layers that disadvantage smaller operators in Nakuru and Eldoret.
Carrier-owned assets dominate installed base; neutral-host structures are expanding most quickly.
Deployment Type:
Geographic application contexts determine power architecture choices and backhaul technology pairing.
- Urban:Nairobi metropolitan corridor demands aesthetic-compliant monopole designs with integrated concealment shrouds. Municipal permitting accelerates for suburban mall and residential cluster deployments.
- Suburban:Satellite towns surrounding Nairobi concentrate 4G densification activity. Grid electrification availability shapes whether sites rely on Kenya Power distribution or diesel-hybrid backup.
- Rural:Underserved counties channel Universal Service Fund capital toward lattice tower deployment. Solar-battery hybridization reduces operational expenditure burdens and extends economically viable coverage.
- Remote:Kenya's northeastern corridor and northern territories present first-mover opportunities for operators absorbing higher initial capex. Microwave backhaul infrastructure and diesel generators dominate site economics.
Urban sites generate highest revenue per tower; remote deployments are climbing the fastest on universal service obligations.
Infrastructure Type:
Structural form factor selection hinges on wind-load engineering, antenna loading requirements, and municipal aesthetic compliance.
- Monopole:Single-shaft steel designs optimized for 5G densification and millimeter-wave antenna accommodation. Concealment shrouds accelerate permitting in Nairobi's metropolitan planning zones.
- Lattice Tower:Four-legged steel configurations engineered for wind loads exceeding 160 km/h. Traditional fabrication faces demand compression as carriers prioritize lighter monopole alternatives.
- Rooftop:Building-mounted installations in dense urban cores where greenfield construction is restricted. Landlord negotiation complexity and structural load assessments extend deployment timelines.
- Micro Tower:Compact structures for small-cell densification and temporary coverage solutions. Limited penetration in Kenya relative to mature markets due to fiber backhaul prerequisites.
Lattice towers anchor installed capacity; monopole structures show steepest expansion trajectory on 5G readiness.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's telecom tower infrastructure emerged from East Africa's mobile telephony expansion in the 1990s, with Nairobi establishing itself as the regional hub for network equipment deployment and engineering expertise. The market now spans distinct economic corridors shaped by population density, grid availability, and backhaul economics.
Nairobi Metropolitan Corridor
5G densification drives monopole demand across Westlands, Upper Hill, and the emerging Konza Technopolis satellite zone. Nairobi County's aesthetic compliance mandates accelerate concealed-structure permitting for suburban mall deployments. Safaricom PLC anchors tenant concentration in this corridor, with independent tower operators capturing co-location revenue from secondary carriers.
Coastal Zone
Mombasa port infrastructure and Lamu Port-South Sudan-Ethiopia Transport Corridor investments stimulate microwave backhaul tower deployment. Kilifi and Kwale counties attract neutral-host operators serving tourism-dependent mobile data demand. Kenya Power's coastal distribution network reduces diesel dependency relative to northeastern regions, improving site economics for lattice tower configurations.
Rift Valley
Nakuru and Eldoret anchor 4G expansion into agricultural commercial zones where mobile money transaction density justifies infrastructure investment. The Communications Authority's infrastructure-sharing enforcement creates documentation friction for smaller regional operators adapting to pre-certification requirements. Uasin Gishu County's grain trading hubs generate concentrated data demand patterns.
Western Kenya
Kisumu's lake port economy and cross-border traffic to Uganda drive tower deployment along the Northern Corridor. Busia and Malaba border posts require specialized microwave relay infrastructure where fiber penetration remains incomplete. Independent power producers are piloting solar-hybrid aggregation models for rural tower clusters in this region.
Northern Frontier
Turkana and Marsabit counties present first-mover opportunities for operators absorbing elevated capex for microwave backhaul chains. Universal Service Fund disbursements target these underpenetrated territories, though grid electrification gaps necessitate diesel-generator dominance. Security considerations and road infrastructure limitations extend deployment timelines relative to southern counties.
Kenya Telecom Tower Market Competitive Landscape
Premium-margin players sit above commodity-margin players across tenant density and power reliability dimensions. The market exhibits tiered consolidation with captive carrier portfolios, neutral-host specialists, and regional fabricators occupying distinct economic positions. Three archetypes dominate: integrated operators with captive tower assets, independent infrastructure companies with standardized national coverage, and regional contractors serving fragmented secondary markets. Competitive moves concentrate on master service agreement consolidation and solar-hybrid power integration at off-grid sites.
Among Kenya-based integrated operators, Safaricom PLC exemplifies the captive-asset archetype through extensive metropolitan portfolio control. Airtel Kenya Ltd and Telkom Kenya occupy positions within the tenancy-aggregation tier, with the former emphasizing neutral-host partnerships and the latter specializing in rural microwave-backhaul deployment. These three entities anchor the competitive structure while independent tower companies capture regulatory-mandated co-location revenue.
| Leading Market Players |
|---|
| Finserve Africa Limited (Equitel) |
| Jamii Telecommunications Limited (Faiba) |
| Safaricom PLC |
| Axian Telecom |
| Liquid Home |
| Telkom Kenya |
| Wananchi Group |
| Communications Authority of Kenya |
| Airtel Kenya Ltd |
| Others |
Pricing and Supply Chain Analysis
Neutral-host tower operators with standardized national portfolios command master service agreement leverage, anchoring a contract-based long-term offtake model that compresses spot-market exposure for fragmented regional fabricators. The Communications Authority's infrastructure-sharing mandates elevate tenant density premiums while diesel-hybrid power costs stratify pricing between grid-connected urban corridors and off-grid rural deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs tower access economics. Premium tiers attach to 5G-ready monopole sites in Nairobi's metropolitan corridor with aesthetic concealment and guaranteed power reliability; standard tiers capture secondary city 4G lattice towers with grid dependency; economy tiers cover remote diesel-dependent sites in Turkana and Marsabit counties. Price differentiation rests on certification grade from the Kenya Bureau of Standards and power uptime guarantees. Margins are tightening due to steel input cost volatility from East Asian suppliers. Rural universal service fund beneficiaries exhibit highest price sensitivity; Safaricom PLC's captive portfolio demonstrates lowest sensitivity through balance-sheet absorption.
Supply Chain Analysis
Inland freight costs from Mombasa port to upcountry deployment sites add substantial landed cost premiums for lattice and monopole structures. Steel fabrication concentrates in China, India, and South Africa, with hot-rolled coil sourcing exposing tower contractors to commodity price swings. Component dependencies include galvanized steel sections, microwave backhaul equipment, and solar-hybrid power systems. Single-source vulnerability runs through Chinese structural steel suppliers subject to Kenya Bureau of Standards certification delays. Distribution runs through Nairobi-based engineering contractors with regional sub-contracting networks reaching Kisumu, Nakuru, and coastal zones.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kenya's telecom tower market functions as a regulatory compounder where Communications Authority infrastructure-sharing enforcement continuously revalues neutral-host assets above captive carrier portfolios.
For Market Incumbents: Deepen solar-hybrid power integration at off-grid sites to defend margin position against diesel cost volatility. Expand master service agreement bundling to lock in rural coverage commitments alongside metropolitan access, neutralizing emerging neutral-host competitors in secondary cities. Prioritize Kenya Bureau of Standards pre-certification documentation systems to accelerate tenant revenue recognition timelines. For New Entrants and Emerging Players: Independent power producers offer the most penetrable channel partnership for rural tower energy aggregation under feed-in tariff frameworks. Target Turkana and Marsabit county microwave backhaul corridors where first-mover capex absorption deters established operators. Pursue municipal aesthetic compliance specialization for concealed monopole permitting in Nairobi's suburban planning zones. For Investors and Strategic Acquirers: Infrastructure funds with African digital infrastructure mandates are the most active acquirer in this space, prioritizing standardized national portfolios with documented tenant density. Long-term viability hinges on 5G spectrum auction timing and universal service fund disbursement continuity. Watch for Communications Authority rural coverage mandate acceleration as inflection indicator for remote site valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Hybrid Power Integration | Reduces diesel dependency at Kenya Power underserved sites in northeastern corridor. |
| Master Service Agreement Consolidation | Bundles Nairobi metropolitan access with rural county coverage commitments. |
| 5G-Ready Monopole Pre-positioning | Captures millimeter-wave antenna densification demand in Konza Technopolis zone. |
| Kenya Bureau of Standards Pre-certification | Accelerates tenant onboarding timelines before carrier lease negotiations. |
| Microwave Backhaul Infrastructure Buildout | Enables Turkana and Marsabit expansion where fiber penetration remains thin. |
Research Methodology
Multiple input streams — tower engineering specialists, carrier procurement executives, independent power producer developers, and Communications Authority regulatory officers — were reconciled against secondary validation from customs import records, Kenya Power electrification maps, and universal service fund disbursement filings. Primary interviews with neutral-host operators and lattice fabrication contractors informed site economics modeling. Bottom-up tenant revenue projections and top-down infrastructure investment flows were triangulated for consistency.
Historical deployment velocity was cross-referenced against panel input from network planning directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include technology generation, ownership structure, deployment geography, and infrastructure form factor. CAGRs were derived from structural demand drivers including spectrum auction schedules and rural coverage obligations. Steel price indices and diesel supply chain disruptions served as industry-specific sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Communications Authority enforcement intensity and universal service fund allocation continuity. Forecasts reflect documented assumptions about tenant density achievement rates and power reliability improvements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
OTN Equipment Market