
 Thailand Telecom Towers Market | 2026-2036
Thailand Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Telecom Towers Market Insights
The NBTC tower-sharing mandate is recalibrating the cost-of-entry calculus for new market participants. Digital Telecommunications Infrastructure Fund (DIF) leverages its portfolio scale to consolidate tower assets across multiple provinces. Advanced Info Service (AIS) anchors its competitive stance through dense urban 5G deployments in Bangkok and surrounding industrial zones. True Corporation Public Company Limited differentiates by controlling a substantial share of rooftop sites in premium commercial districts.
Thailand telecom towers are steel or concrete structures engineered to support antenna arrays at heights typically ranging from 30 to 120 meters, designed to withstand tropical cyclone wind loads per local engineering codes. Their primary purpose is to provide elevated platforms for radio frequency transmission, enabling mobile voice and data coverage across diverse topography. Lattice towers dominate capital expenditure for greenfield macro sites due to their load-bearing capacity for multi-tenant configurations. Rooftop deployments represent the fastest-growing structural category in Bangkok's constrained urban core where ground space commands premium lease rates.
The NBTC enforces electromagnetic field emission standards and structural safety certifications that dictate tower design specifications and siting approvals. The Telecommunications Business Act, administered by the NBTC alongside Ministry of Digital Economy and Society guidelines, shapes market access through licensing requirements and infrastructure-sharing obligations. Stakeholders must monitor how evolving 5G spectrum allocation rules and proposed amendments to the Telecom Business Act will alter tenancy pricing frameworks and co-location obligations.
Market Dynamics
The NBTC tower-sharing mandate is compressing tenancy margins while forcing asset-light strategies across Thailand's mobile operator landscape. This regulatory pressure is redistributing capital deployment from build-own-operate models toward lease-back arrangements with infrastructure funds.
Growth Catalysts
- 5G spectrum allocation:The NBTC's mid-band spectrum releases are accelerating macro site densification requirements across Bangkok's industrial corridors and the Eastern Economic Corridor.
- Fiber-microwave convergence:Backhaul infrastructure integration is enabling multi-tenant tower economics in central provinces where fiber routes intersect with existing microwave relay networks.
- National broadband policy:Thailand's universal service obligation frameworks are redirecting subsidy flows toward rural tower deployments in previously underserved northern and northeastern provinces.
Market Restraints
- Steel price volatility:Lattice tower fabrication costs fluctuate with global hot-rolled coil indices, compressing greenfield project returns during input spikes.
- Land lease concentration:Prime rooftop sites in Bangkok's central business district are controlled by a limited pool of commercial real estate developers, inflating site acquisition premiums.
- Electromagnetic field compliance:NBTC emission thresholds restrict tower siting near schools and hospitals, eliminating otherwise viable locations in dense urban precincts.
Strategic Opportunities
- Edge computing co-location:Tower base shelters are being repurposed for micro data center hosting, creating incremental revenue streams from cloud service providers.
- Renewable energy integration:Solar panel arrays on tower compounds are reducing diesel generator dependency and aligning with Thailand's carbon neutrality commitments.
- Small cell overlay:Existing macro tower portfolios provide mounting infrastructure for 5G small cell backhaul, capturing millimeter-wave densification demand.
Industry Challenges
- Structural engineering talent scarcity:Certified tower designers familiar with tropical cyclone load calculations are concentrated in Bangkok, constraining provincial deployment timelines.
- Legacy 2G/3G decommissioning coordination:Multi-tenant sites require synchronized equipment removal across operators, complicating tenancy transitions and site reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Telecom Towers Market |
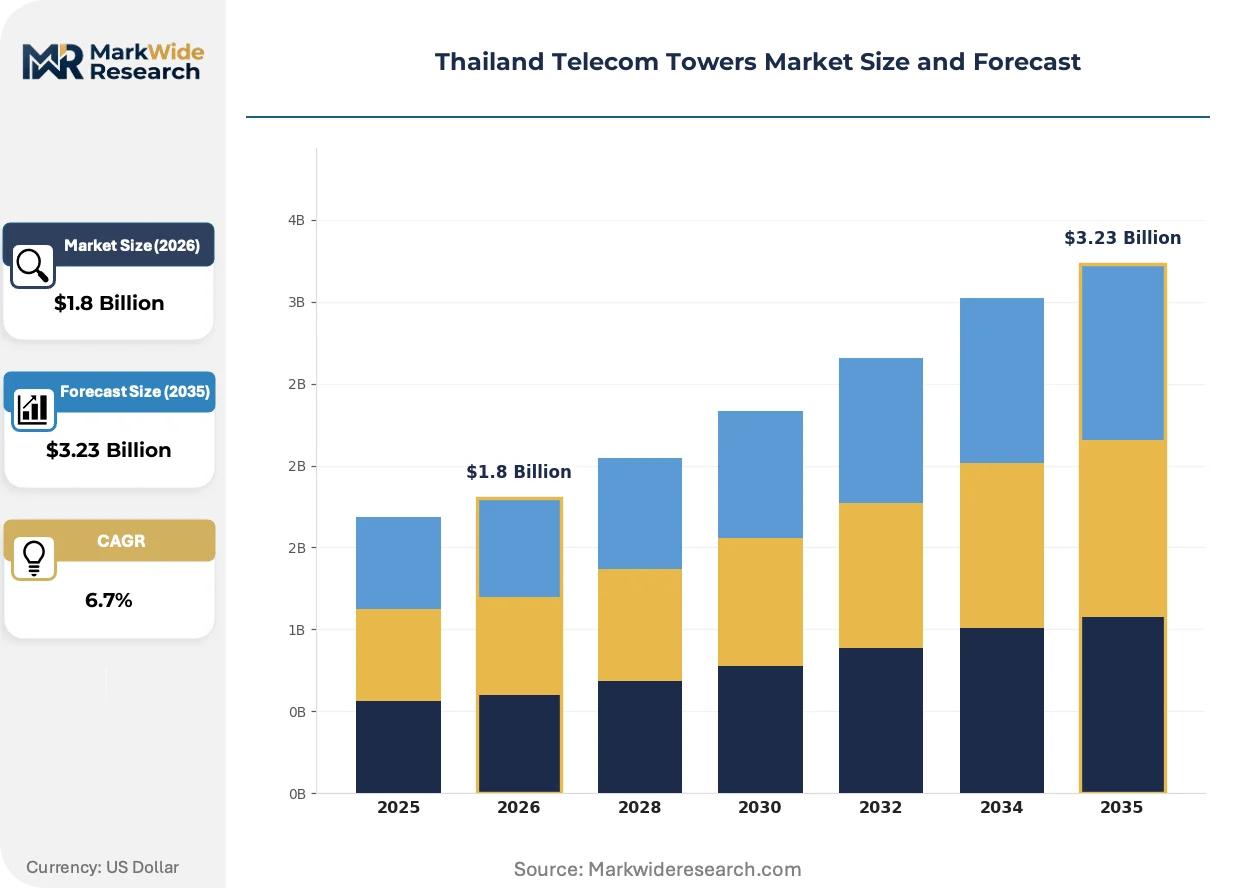
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Guyed, Rooftop Technology: 4G LTE, 5G NR, Microwave, Fiber Optics End User: Mobile Operators, ISPs, Government, Enterprises Deployment: Urban, Suburban, Rural, Remote |
| Companies Covered | Digital Telecommunications Infrastructure Fund (DIF), OCK Group Berhad, Advanced Info Service (AIS), True Corporation Public Company Limited, National Telecom (NT), Total Access Communication (Dtac), TOT Public Company Limited, TT&T, 3BB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Telecom Towers Market Trends and Innovations
Thailand's telecom tower sector is experiencing a hardware architecture revolution as multi-tenant configurations demand standardized, interchangeable components. This shift is compressing deployment timelines while forcing suppliers toward platform-based product strategies.
Modular tower systems with bolt-together lattice sections are modularizing site construction workflows across Thailand's macro deployment programs. Rural network builders are adopting these prefabricated structures to bypass on-site welding requirements and accelerate permitting cycles. The technology is modularizing the traditional tower erection sequence, compressing project timelines from months to weeks.
The NBTC's proposed amendments to the Telecommunications Business Act are tightening infrastructure-sharing enforcement mechanisms and standardizing co-location pricing formulas. Mobile operators must now disclose tower utilization rates to regulators, increasing transparency in tenancy negotiations. This regulatory tightening is most acute in Bangkok, where operators are pre-emptively restructuring lease agreements to avoid compliance penalties.
Enterprise buyers are consolidating tower access contracts through managed infrastructure services rather than direct site leasing. Industrial conglomerates in the Eastern Economic Corridor are outsourcing entire connectivity stacks to tower companies, bundling site access with maintenance and power guarantees. This purchasing consolidation is most visible in automotive and electronics manufacturing zones where uptime requirements exceed standard commercial terms.
Thailand Telecom Towers Market Segmentation
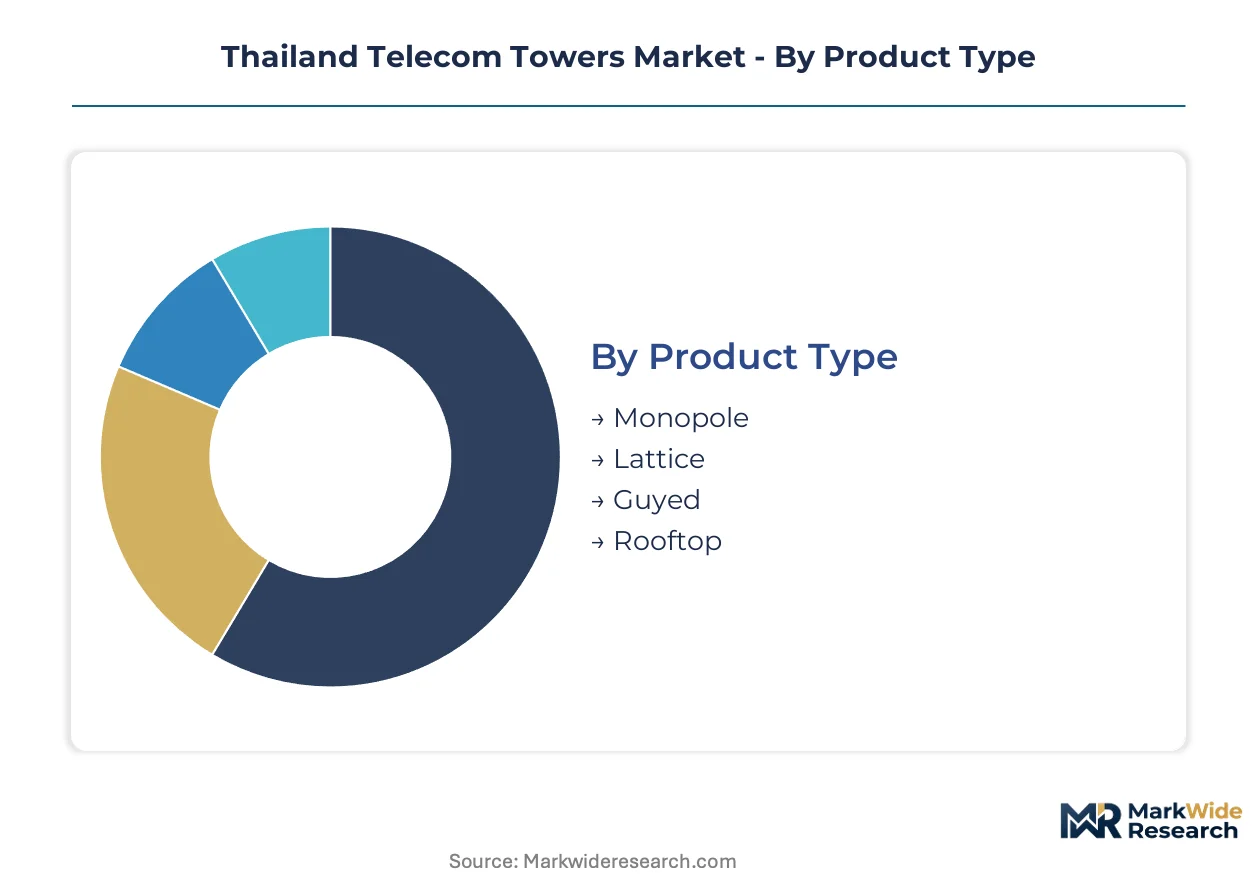
Thailand's telecom tower segmentation reveals how regulatory mandates and deployment economics fragment infrastructure procurement across distinct technical and geographic profiles. Each segment carries specific NBTC certification burdens and tenancy obligations that reshape capital allocation strategies.
Product Type:
Lattice towers demand the most intensive structural safety certifications from NBTC engineers, while rooftop installations face electromagnetic field compliance reviews through Bangkok municipal authorities.
- Monopole:Single-pole steel structures with tapered tubular construction support single-tenant configurations in suburban corridors. Demand concentrates in Bangkok's peripheral industrial zones where ground lease availability exceeds central business district premiums. Monopole installations face streamlined permitting under NBTC fast-track guidelines for 5G densification corridors.
- Lattice:Triangular or square-section steel frameworks engineered for multi-tenant load distributions up to 120 meters height. Lattice towers anchor macro site deployments across the Eastern Economic Corridor where fiber-microwave convergence enables shared backhaul economics. These structures require the most rigorous tropical cyclone load certifications per Thai engineering codes.
- Guyed:Masted structures stabilized by tensioned cable arrays reduce steel tonnage for rural coverage extensions. Guyed towers serve remote northern provinces under national broadband subsidy frameworks.
- Rooftop:Building-integrated antenna mounting systems bypass ground space constraints. Rooftop deployments accelerate across Bangkok's central business district where premium commercial developers control site access.
Lattice towers sit at the top of the volume ranking, with rooftop installations climbing the fastest.
Technology:
Technology segmentation tracks how spectrum allocation waves reconfigure tenancy revenue per site, with 5G NR deployments commanding premium lease rates against legacy 4G infrastructure.
- 4G LTE:Mature radio access technology dominating existing tenancy contracts across provincial Thailand. 4G LTE infrastructure generates baseline revenue streams while operators defer 5G migration in cost-sensitive rural markets.
- 5G NR:Next-generation radio equipment operating in NBTC-allocated mid-band spectrum. 5G NR deployments concentrate in Bangkok and the Eastern Economic Corridor where manufacturing automation drives ultra-reliable low-latency demand. These installations trigger mandatory infrastructure-sharing disclosures under proposed Telecom Business Act amendments.
- Microwave:Point-to-point radio backhaul bridging fiber gaps in mountainous terrain. Microwave relay towers serve as interim solutions in northern provinces pending terrestrial fiber extension.
- Fiber Optics:Terrestrial cable infrastructure enabling tower base station connectivity. Fiber-fed towers command tenancy premiums in central provinces where route density permits multi-tenant economics.
4G LTE maintains the largest installed base, though 5G NR is gaining share fastest among new deployments.
End User:
End user categories reflect diverging procurement sophistication, with mobile operators leveraging scale for lease-back structures while government buyers navigate public procurement regulations.
- Mobile Operators:AIS, True Corporation, and NT anchor tenancy demand through long-term lease agreements. Mobile operators are restructuring toward asset-light models under NBTC tower-sharing mandates, outsourcing ownership to infrastructure funds.
- ISPs:Fixed broadband providers lease tower space for wireless last-mile extensions. ISP demand concentrates in suburban Bangkok where fiber-to-the-home buildouts require wireless backup paths.
- Government:Universal service obligation programs subsidize rural tower construction in northern and northeastern provinces. Government procurement follows Ministry of Finance competitive bidding rules with local content requirements.
- Enterprises:Industrial conglomerates in the Eastern Economic Corridor purchase managed infrastructure services bundling tower access with uptime guarantees. Enterprise contracts specify 99.99% availability thresholds exceeding standard commercial terms.
Mobile operators dominate tenancy volumes, with enterprise contracts expanding most quickly through manufacturing zone outsourcing.
Deployment:
Deployment geography determines site economics through land lease gradients and backhaul availability, with urban premiums funding cross-subsidized rural obligations.
- Urban:Dense Bangkok deployments face the steepest site acquisition costs and strictest electromagnetic field siting restrictions. Urban towers achieve multi-tenant utilization rates above provincial averages through 5G small cell overlay opportunities.
- Suburban:Peripheral metropolitan zones balance accessibility with lower lease rates. Suburban corridors along motorway networks prioritize monopole and guyed structures for rapid coverage extension.
- Rural:Agricultural provinces require lattice and guyed towers for wide-area coverage. Rural deployments depend on national broadband subsidies and extended payback periods.
- Remote:Border and island territories utilize solar-powered microwave relay towers. Remote sites face the highest logistics costs and longest permitting timelines.
Urban deployments generate the highest revenue per site, while rural construction shows the steepest expansion trajectory under universal service commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified tower designers familiar with tropical cyclone load calculations concentrate in Bangkok, constraining provincial deployment timelines and creating talent arbitrage opportunities for regional hubs.
Central Plains
Bangkok's industrial corridors and the Eastern Economic Corridor drive 5G macro site densification under NBTC mid-band spectrum allocations. The National Broadcasting and Telecommunications Commission enforces electromagnetic field emission standards that restrict siting near schools and hospitals. Manufacturing automation in Chonburi and Rayong provinces commands ultra-reliable low-latency connectivity from fiber-microwave converged towers.
Northern Region
Chiang Mai and Chiang Rai provinces depend on national broadband subsidy frameworks for rural lattice and guyed tower deployments. The Ministry of Digital Economy and Society redirects universal service obligation flows toward previously underserved mountainous terrain. Border territories utilize solar-powered microwave relay towers pending terrestrial fiber extension from central provinces.
Northeastern Region
Khon Kaen and Udon Thani anchor agricultural zone coverage extensions through extended payback period structures. The Telecommunications Business Act shapes market access through infrastructure-sharing obligations that compress tenancy margins. Provincial deployment timelines lag due to structural engineering talent scarcity outside Bangkok.
Southern Region
Songkhla and Phuket face tropical cyclone engineering code requirements that intensify lattice tower certification burdens. The NBTC structural safety certifications dictate design specifications for coastal installations. Island territories require remote logistics solutions and longest permitting timelines for solar-powered relay infrastructure.
Thailand Telecom Towers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Thailand's tower infrastructure landscape. The market structure tilts toward consolidation as infrastructure funds absorb operator-owned assets under regulatory pressure. Three archetypes dominate: state-linked universal service providers, mobile operator lease-back entities, and independent tower companies. M&A activity concentrates on portfolio aggregation while strategic partnerships address fiber-microwave convergence requirements.
Among Thailand-based infrastructure funds, Digital Telecommunications Infrastructure Fund (DIF) exemplifies scale-driven portfolio consolidation across multiple provinces. Advanced Info Service (AIS) and True Corporation Public Company Limited represent mobile operator archetypes restructuring toward asset-light models under NBTC tower-sharing mandates. These entities occupy positions at opposite ends of the ownership spectrum, with DIF capturing lease-back flows while AIS and True Corporation retain operational control through tenancy arrangements.
| Leading Market Players |
|---|
| Digital Telecommunications Infrastructure Fund (DIF) |
| OCK Group Berhad |
| Advanced Info Service (AIS) |
| True Corporation Public Company Limited |
| National Telecom (NT) |
| Total Access Communication (Dtac) |
| TOT Public Company Limited |
| TT&T |
| 3BB |
| Others |
Pricing and Supply Chain Analysis
Modular tower systems with bolt-together lattice sections are compressing both fabrication timelines and supplier concentration across Thailand's telecom infrastructure sector. This prefabrication shift simultaneously lowers per-site capital requirements and rewards steel fabricators with standardized production platforms, redistributing pricing power toward scale-efficient domestic suppliers.
Pricing Analysis
Bundled managed infrastructure services versus unbundled site leasing defines the pricing architecture across Thailand's tower market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by uptime guarantee thresholds and fiber backhaul availability. Cost compression in standard-tier contracts is intensifying because mobile operators are consolidating tenancy volumes under infrastructure fund lease-back arrangements. Enterprise buyers in the Eastern Economic Corridor exhibit the least price sensitivity due to manufacturing automation uptime requirements, while rural government procurement under universal service obligations faces the tightest budget constraints.
Supply Chain Analysis
Local-content requirements under Thailand's national broadband subsidy frameworks are reshaping sourcing patterns for lattice tower fabrication and on-site assembly services. Steel supply draws from China, South Korea, and domestic Thai mills, with hot-rolled coil volatility feeding directly into project return calculations. Solar panel arrays, diesel generators, and microwave relay equipment constitute critical component dependencies. Single-source vulnerability concentrates in certified structural engineering talent for tropical cyclone load calculations. Distribution runs through infrastructure funds and mobile operator procurement consortiums rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's telecom tower sector offers margin expansion pathways through renewable energy integration at tower compounds and premium-tier managed service bundling. The shift from diesel generator dependency to solar-hybrid power systems compresses operating expenditures while enabling carbon neutrality premium positioning.
For Market Incumbents: Deploy tower base shelter repurposing for edge computing co-location to capture incremental revenue from cloud service providers. Consolidate rooftop site portfolios in Bangkok's central business district through long-term lease agreements with commercial real estate developers before proposed Telecom Business Act amendments tighten co-location pricing transparency. This defensive positioning counters emerging independent tower companies seeking urban multi-tenant density.
For New Entrants and Emerging Players: The gap between premium enterprise managed services and economy-tier rural subsidy deployments creates entry space for specialized regional infrastructure funds. Target northeastern provinces where national broadband obligations exceed incumbent deployment capacity, leveraging modular tower systems to bypass Bangkok-centric engineering talent scarcity. A go-to-market angle bundling solar power integration with tower access addresses Thailand's carbon neutrality commitments while differentiating from legacy diesel-dependent operators.
For Investors and Strategic Acquirers: Valuations sit cheapest among provincial-focused tower portfolios with concentrated government tenancy exposure and limited fiber backhaul connectivity. Long-term viability hinges on 5G small cell overlay revenue capture and edge computing co-location uptake. The signal to watch is NBTC enforcement intensity on infrastructure-sharing disclosures, which would accelerate lease-back restructuring among mobile operators and expand addressable acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Integration | Solar-hybrid tower compounds reduce diesel dependency and align with Thailand's carbon neutrality commitments. |
| Edge Computing Co-location | Tower base shelter repurposing captures micro data center demand from cloud service providers in Bangkok. |
| Modular Tower Deployment | Prefabricated bolt-together systems compress rural permitting timelines and bypass on-site welding requirements. |
| Infrastructure Fund Consolidation | Portfolio aggregation under NBTC lease-back mandates captures mobile operator asset-light restructuring flows. |
| Fiber-Microwave Convergence | Backhaul integration enables multi-tenant economics across the Eastern Economic Corridor manufacturing zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply-side intelligence. Primary engagement captured tower company executives, mobile operator network planning directors, NBTC regulatory affairs specialists, and commercial real estate developers controlling rooftop access. Secondary validation drew from NBTC spectrum auction disclosures, Ministry of Digital Economy and Society policy circulars, infrastructure fund prospectus filings, and Thai engineering code documentation. Bottom-up tenancy volume modeling and top-down national broadband obligation tracking were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across product type, technology generation, end user category, and deployment geography dimensions. CAGRs were derived from tenancy contract renewal trajectories, 5G densification corridor buildout schedules, and subsidy flow allocations across the projection horizon. Industry-specific inputs included tropical cyclone load certification timelines, electromagnetic field compliance siting restrictions, and fiber route intersection density metrics.
Caveats apply where steel price volatility, NBTC regulatory amendment timing, or mobile operator consolidation decisions could materially shift the outlook. Forecasts reflect assumptions regarding infrastructure-sharing enforcement intensity and universal service obligation funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
China Telecom Towers Market