
 United Kingdom Telecom Towers Market | 2026-2036
United Kingdom Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Telecom Towers Market Insights
Passive infrastructure monetisation is reshaping capital allocation across the United Kingdom telecom towers landscape. Cellnex UK leverages its European portfolio scale to compete for anchor tenant contracts with major mobile operators. Cornerstone sustains market presence through its extensive shared network footprint with EE and Vodafone. Arqiva Group differentiates via its broadcast-to-telecom tower conversion capabilities and deep site access rights.
United Kingdom telecom towers are steel or composite structures engineered to heights between 15 and 60 metres, designed to host multiple antenna arrays, remote radio heads, and power systems while withstanding wind loads specified under British Standard EN 1993. These structures enable wireless signal propagation for cellular, microwave backhaul, and emergency services networks. Tower deployment type shows structural divergence: monopole installations dominate suburban and highway corridors for their minimal footprint, while rooftop sites capture premium urban positions where ground space is constrained. Shared ownership models are expanding fastest as Ofcom-promoted infrastructure competition pushes carriers toward tenancy rather than capital ownership.
Ofcom enforces coverage obligations and spectrum licence conditions that directly mandate rural 4G and 5G rollout timelines, compelling operators to secure tower access rather than build greenfield assets. The UK Electronic Communications Code governs site agreements and wayleave terms, altering negotiation leverage between landowners and infrastructure providers. Building Regulations and Health and Safety Executive guidelines impose structural load and climbing-access standards that filter equipment vendors and maintenance contractors. Stakeholders must monitor upcoming spectrum auction conditions and potential code amendments that could reset tenancy pricing mechanics.
Market Dynamics
Ofcom's infrastructure sharing mandates are compressing carrier capital deployment cycles, forcing mobile operators toward tenancy models rather than greenfield tower construction across England's urban corridors.
Growth Catalysts
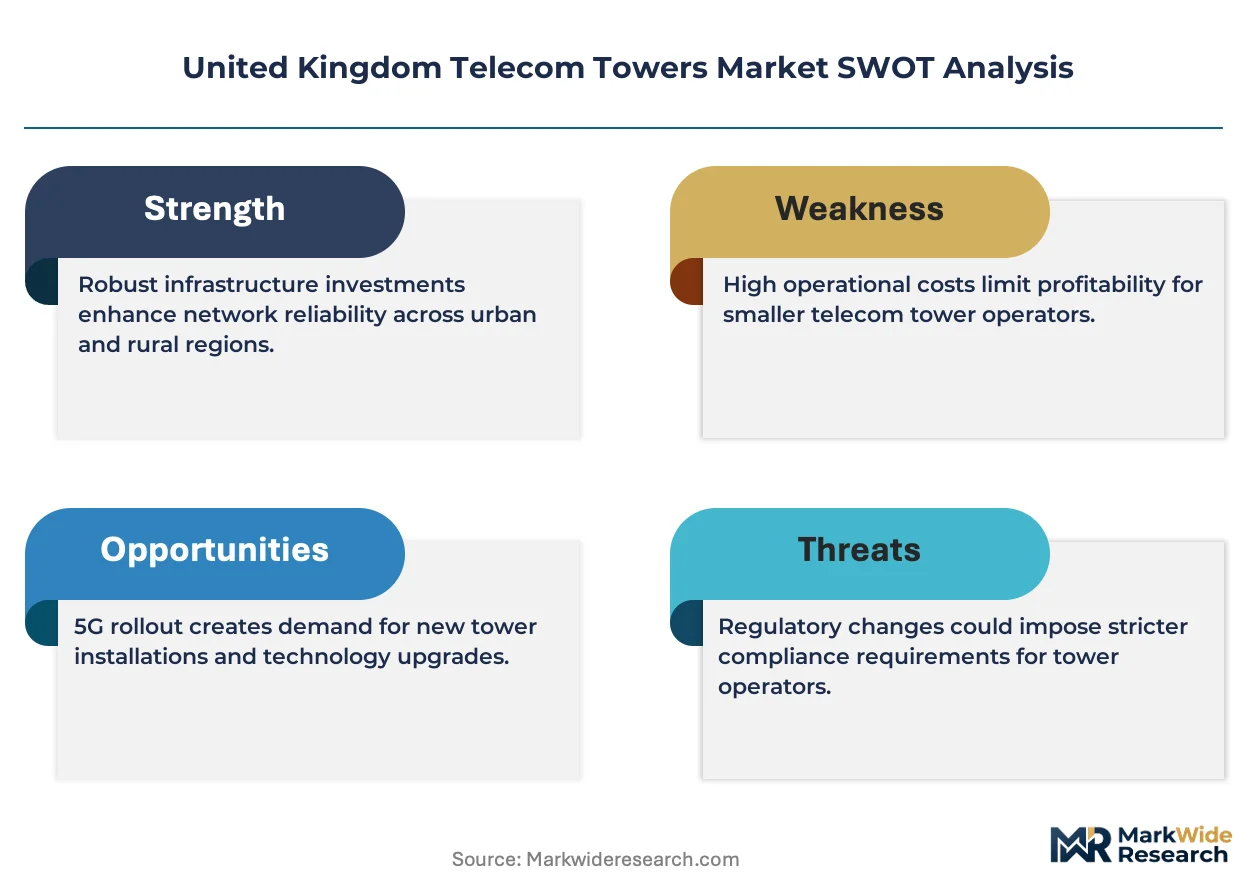
- 5G Network Densification:Mobile operators require 3-4x more site density for mid-band coverage, accelerating demand for multi-tenant steel structures in Greater London and the West Midlands.
- Electronic Communications Code:The UK's revised code strengthens infrastructure providers' site access rights, reducing wayleave negotiation timelines and enabling faster rural rollout.
- Broadcast-to-Telecom Conversion:Arqiva's deep portfolio of broadcast towers offers pre-permitted sites with established power and backhaul, cutting deployment lead times for 5G overlay.
Market Restraints
- Steel Input Volatility:Tower fabrication costs fluctuate with UK steel import pricing, compressing margins for domestic structure fabricators serving the 15-60 metre segment.
- Site Access Concentration:A limited pool of accredited climbing contractors certified under Health and Safety Executive guidelines creates maintenance bottlenecks during peak upgrade cycles.
- Landowner Negotiation Leverage:Prime rooftop positions in central London command premium rents, inflating tenancy costs for operators seeking urban small-cell densification.
Strategic Opportunities
- Rural Coverage Obligations:Ofcom's mandated 4G and 5G rollout timelines for remote Scottish Highlands and Welsh valleys create captive demand for shared infrastructure in underpenetrated terrain.
- Edge Computing Collocation:Tower base shelters offer unmetered power and fibre access, positioning steel structures as aggregation points for low-latency compute nodes serving autonomous vehicle corridors.
- Emergency Services Modernisation:The Home Office's Emergency Services Network migration from TETRA to LTE creates dedicated tenancy demand with long-term contract structures.
Industry Challenges
- Structural Engineering Talent Scarcity:British Standard EN 1993 compliance for wind load calculations requires specialised civil engineers, creating recruitment friction for tower design consultancies.
- Legacy Site Integration Complexity:Rooftop installations in historic London boroughs face conservation area restrictions, forcing bespoke mounting solutions that delay equipment commissioning.
- Power System Retrofit Costs:Existing tower estates require battery backup upgrades to meet resilience standards, demanding capital deployment without immediate revenue uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Telecom Towers Market |
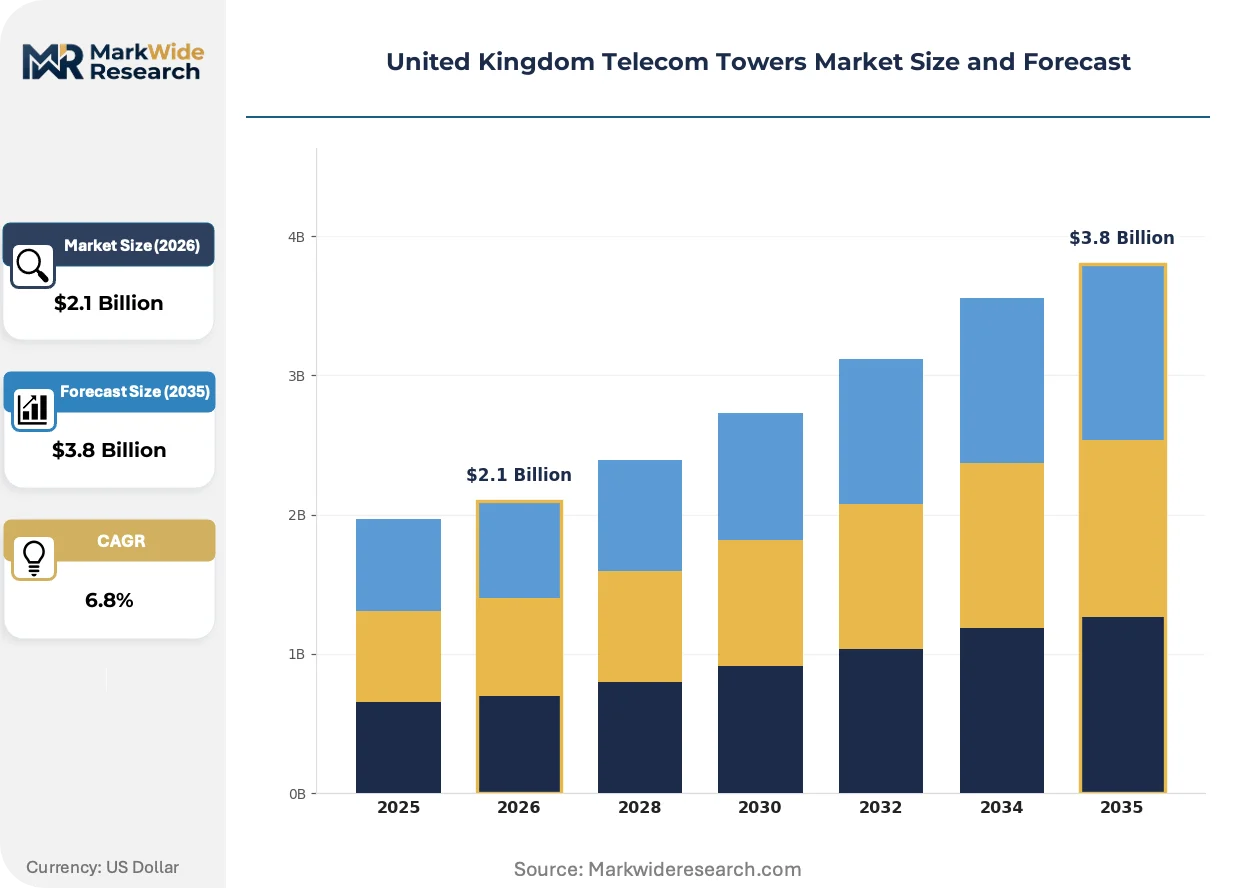
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
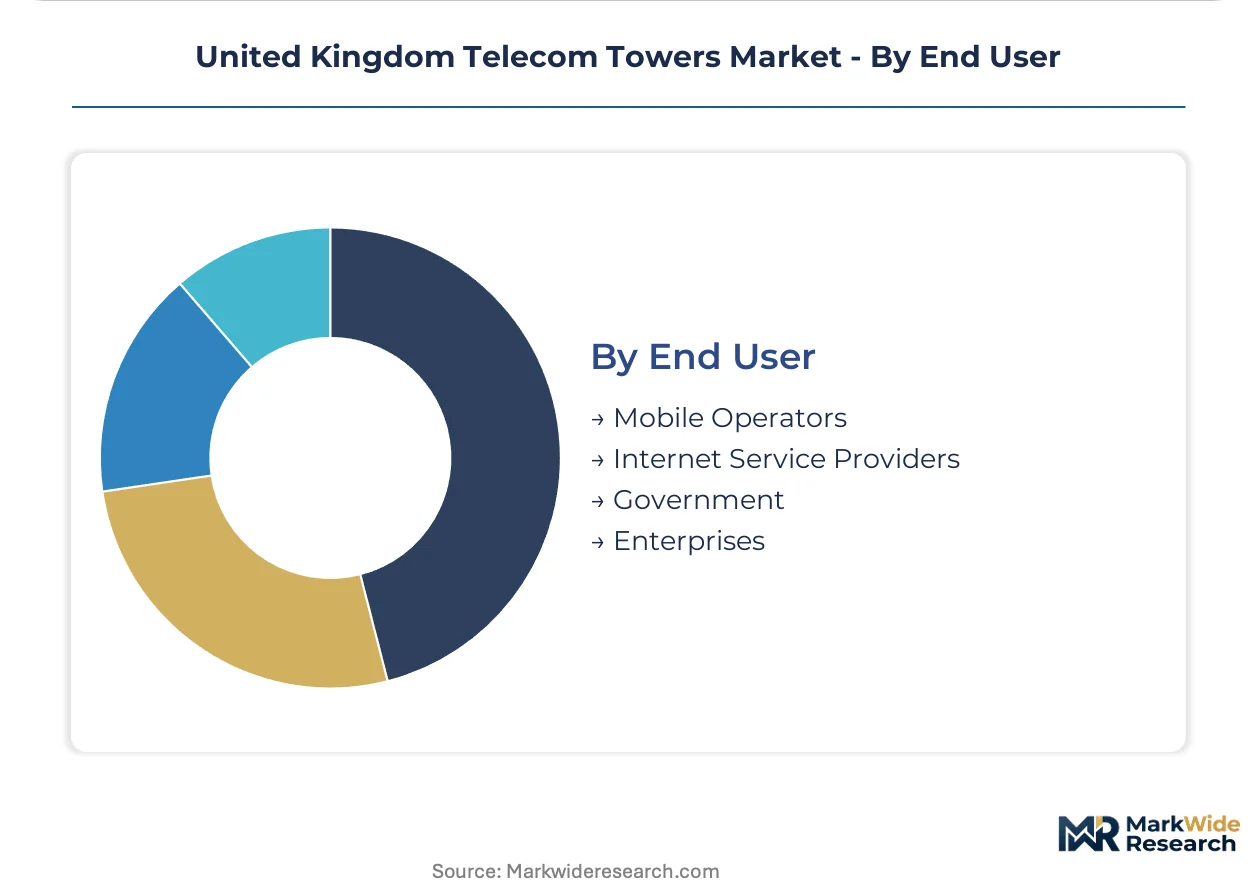
| Segmentation | Technology: 5G, 4G, 3G, Microwave Deployment: Monopole, Lattice, Smart, Rooftop Ownership Model: Carrier-Owned, Independent, Lease, Shared End User: Mobile Operators, Internet Service Providers, Government, Enterprises |
| Companies Covered | Cornerstone, Mobile Broadband Network Ltd (MBNL), Cellnex UK, Wireless Infrastructure Group (WIG), Arqiva Group, Helios Towers, EE, Vodafone, Virgin Media O2, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Telecom Towers Market Trends and Innovations
Steel-composite hybrid structures and tenancy model innovation are compressing deployment economics while Ofcom's regulatory pressure accelerates infrastructure consolidation across England's mobile networks.
Advanced composite materials are hybridizing traditional steel lattice designs, embedding carbon-fibre reinforced polymer sections in high-stress joints to reduce weight by 20-30% without sacrificing wind-load tolerance. Rural network builders in Cornwall and Cumbria are specifying these hybrid towers for helicopter-lift installations where road access is restricted. The structural shift is compressing transport and foundation costs for remote 5G rollout.
Ofcom's 2023 spectrum auction conditions embedded coverage milestones that trigger licence revocation, binding operators to published rural deployment timelines. The regulatory pressure is forcing Vodafone and EE to accelerate shared tenancy negotiations with Cornerstone rather than pursue independent site builds. Scottish Highlands operators are responding by pooling wayleave negotiations to reduce landowner friction.
Mobile operators are unbundling tower tenancy from managed service contracts, separating passive infrastructure access from active equipment maintenance. This procurement split is displacing single-vendor relationships in favour of direct tower company negotiations, particularly visible in West Midlands urban corridors where Cellnex UK competes for anchor tenant positions against Cornerstone's established EE-Vodafone footprint.
United Kingdom Telecom Towers Market Segmentation
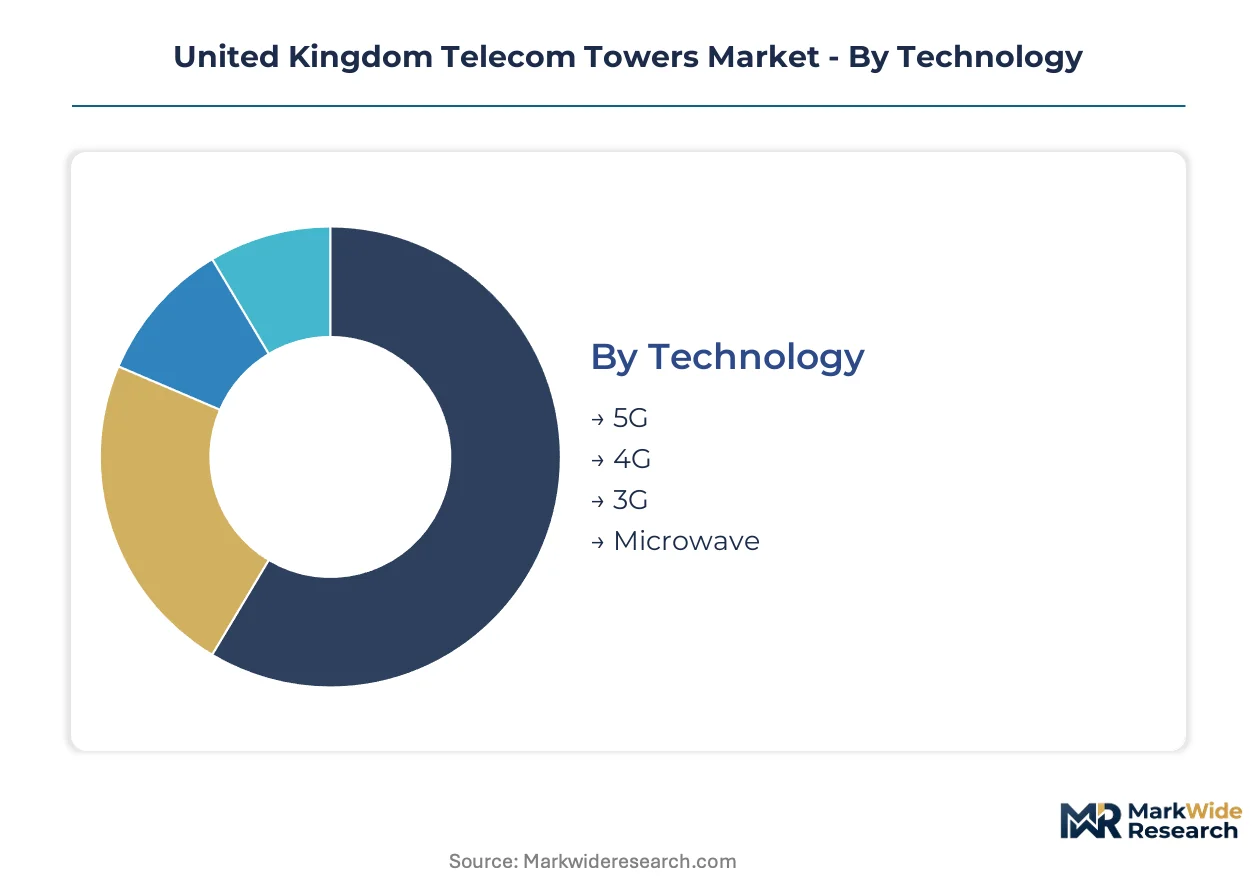
United Kingdom telecom tower segmentation reveals how technology transitions, ownership restructuring, and deployment constraints reshape procurement patterns. Understanding these intersecting dimensions clarifies where infrastructure providers compete for tenancy contracts and where carriers retain capital deployment control.
Technology:
Mature cellular generations coexist with emerging microwave backhaul architectures across the United Kingdom deployment base.
- 5G:Mid-band macro sites and small-cell overlays demand 3-4x densification versus 4G equivalents. Greater London and West Midlands corridors concentrate initial buildout as EE and Vodafone pursue Ofcom-mandated coverage milestones.
- 4G:Rural obligation extensions sustain incremental antenna additions on existing structures. Scottish Highlands and Welsh valleys drive residual demand as operators fill coverage gaps ahead of 5G overlay.
- 3G:Spectrum re-farming accelerates site decommissioning. Legacy equipment removal frees tower capacity for 5G radio heads in England's secondary urban markets.
- Microwave:Point-to-point links bridge fibre gaps in Cumbria and Cornwall where trenching costs prohibit fixed-line backhaul. Arqiva's broadcast tower portfolio offers pre-elevated mounting positions for relay chains.
5G retains volume leadership; microwave backhaul holds the steepest expansion curve as fibre-alternative demand intensifies in remote terrain.
Deployment:
Structural typology selection hinges on footprint constraints, wind-load engineering, and helicopter-access logistics across United Kingdom geographies.
- Monopole:Tapered steel tubes with concealed antenna shrouds dominate suburban corridors and motorway-adjacent sites. Minimal ground footprint satisfies planning restrictions in Greater London's outer boroughs while supporting 15-30 metre elevation.
- Lattice:Triangular or square-section steel frameworks withstand higher wind loads per British Standard EN 1993. Rural Scotland and Northern England specify lattice for guyed installations where soil conditions limit monopole foundation depth.
- Smart:Integrated structures embed environmental sensors, CCTV, and LED lighting alongside antenna arrays. Smart city pilots in Birmingham and Manchester test multi-service revenue stacking beyond pure telecom tenancy.
- Rooftop:Building-mounted installations capture premium urban positions where street-level construction is prohibited. Central London's conservation areas force bespoke mounting engineering that extends commissioning timelines.
Monopole deployments dominate installation counts; rooftop positions command the steepest expansion curve as urban densification accelerates.
Ownership Model:
Capital allocation strategies diverge between balance-sheet retention and tenancy outsourcing as Ofcom's infrastructure sharing mandates reshape operator economics.
- Carrier-Owned:BT/EE and Vodafone retain strategic sites with unique coverage or backhaul characteristics. Ownership concentration in legacy 2G-era positions now faces pressure to monetise via sale-leaseback structures.
- Independent:Cellnex UK and Cornerstone operate pure-play tower portfolios without retail subscriber businesses. Independence enables multi-tenant neutrality that accelerates sharing negotiations under Ofcom's competitive framework.
- Lease:Short-term site agreements dominate provisional 5G overlay positions where permanent structural investment awaits demand confirmation. Lease structures predominate in trial corridors along England's A-road networks.
- Shared:Joint venture ownership between operators consolidates overlapping coverage footprints. Cornerstone's EE-Vodafone partnership exemplifies shared models that eliminate redundant urban construction.
Independent ownership captures volume leadership; shared structures are expanding most quickly as consolidation mandates compress carrier capital cycles.
End User:
Demand composition stretches beyond mobile operators toward public safety and enterprise verticals with diverging contract tenors and resilience specifications.
- Mobile Operators:EE, Vodafone, O2, and Three drive core tenancy demand through 5G densification and rural obligation compliance. Their procurement splits increasingly separate passive infrastructure access from active equipment maintenance.
- Internet Service Providers:Fixed-wireless access providers lease tower positions for point-to-multipoint distribution in fibre-competitive markets. WISP demand concentrates in semi-rural England where trenching economics remain unfavourable.
- Government:The Home Office's Emergency Services Network migration from TETRA to LTE creates dedicated tenancy demand with decade-long contract structures. Public safety specifications exceed commercial resilience standards.
- Enterprises:Private 5G network builders in manufacturing and logistics seek tower access for campus coverage extensions. Port of Felixstowe and automotive plants in West Midlands pilot enterprise-specific overlay structures.
Mobile operators retain volume leadership; government tenancy shows the steepest expansion curve as public safety modernisation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the United Kingdom. Urban corridors in Greater London show price-insensitive procurement driven by coverage mandates, while rural Scotland and Wales exhibit acute cost sensitivity where tenancy economics determine deployment viability.
Greater London and the South East
5G densification drives the steepest tenancy demand in Europe's densest mobile market. Ofcom's coverage obligations bind EE and Vodafone to urban small-cell timelines. The West End and Canary Wharf clusters concentrate rooftop negotiations where site access premiums exceed national averages.
West Midlands
Automotive and logistics corridors generate enterprise 5G demand alongside consumer coverage. Birmingham's smart city pilots embed multi-service towers with environmental sensors. Coventry's automotive testing facilities anchor private network overlay structures serving autonomous vehicle development.
Scottish Highlands
Remote terrain elevates total cost of ownership for infrastructure providers. Ofcom's rural 4G and 5G rollout mandates compel shared tenancy models to distribute landowner negotiation costs. Helicopter-accessible hybrid towers in Cumbria-style configurations address roadless valleys.
Wales
Mountainous topography and dispersed population compress carrier return-on-investment calculations. The Welsh Government's digital infrastructure programs supplement commercial deployment in underpenetrated valleys. Swansea and Cardiff corridors concentrate initial 5G buildout before terrain-constrained western expansion.
Northern England
Industrial legacy cities and rural hinterlands create bifurcated demand patterns. Manchester and Leeds drive urban densification comparable to Midlands corridors. Northumberland and Cumbria present rural economics similar to Scottish Highlands, favoring lattice structures over monopole foundations.
United Kingdom Telecom Towers Market Competitive Landscape
Independent tower companies and carrier-shared joint ventures split the United Kingdom market. Consolidation pressure from Ofcom's infrastructure sharing mandates compresses the viable operator set toward tenancy-specialist archetypes. Three strategic archetypes dominate: European-scale independents with portfolio leverage, domestic shared-infrastructure joint ventures, and broadcast-to-telecom converters with deep site access rights. Competitive moves concentrate on anchor tenant contract capture and rural wayleave portfolio assembly.
Among independent infrastructure specialists, Cellnex UK occupies a position exemplifying European portfolio scale applied to domestic tenancy competition. Cornerstone and Arqiva Group sit within the shared-infrastructure and site-access archetypes respectively, representing alternative pathways to tenancy revenue without retail subscriber operations. These three entities anchor the competitive structure through which Ofcom's regulatory pressure channels carrier capital away from greenfield construction.
| Leading Market Players |
|---|
| Cornerstone |
| Mobile Broadband Network Ltd (MBNL) |
| Cellnex UK |
| Wireless Infrastructure Group (WIG) |
| Arqiva Group |
| Helios Towers |
| EE |
| Vodafone |
| Virgin Media O2 |
| Others |
Pricing and Supply Chain Analysis
Sheffield's steel fabrication corridor anchors tower manufacturing capacity for the United Kingdom market, with mill output fluctuations transmitting directly into tenancy pricing power for infrastructure providers serving Greater London and West Midlands corridors. Domestic fabrication concentration compresses margins when import pricing volatility disrupts input costs, forcing tower companies to renegotiate long-term operator contracts or absorb temporary losses.
Pricing Analysis
After-sales service revenue from maintenance contracts and equipment upgrade cycles drives lifetime value for United Kingdom tower providers beyond initial tenancy agreements. Pricing stratifies across anchor tenant, secondary carrier, and emergency services tiers, with differentiation resting on site exclusivity rights and power resilience specifications. Cost compression in steel-intensive fabrication is intensifying because Sheffield mill output fluctuates with energy pricing, pressuring domestic fabricators serving the 15-60 metre segment. Mobile operators exhibit acute price sensitivity in rural Scottish Highlands and Welsh valleys where coverage obligation economics strain return thresholds, while Greater London anchor tenants accept premium positioning with minimal negotiation leverage.
Supply Chain Analysis
United Kingdom export-control alignment with EU dual-use technology restrictions limits flows of advanced composite materials and precision antenna components from non-aligned manufacturing jurisdictions. Tower fabrication draws from domestic Sheffield steel mills, German precision engineering for remote radio heads, and Chinese-manufactured power system components. Single-source vulnerability concentrates in carbon-fibre reinforced polymer supply for hybrid tower joints, where helicopter-accessible rural installations depend on consistent material availability. Distribution runs through specialist infrastructure contractors certified under Health and Safety Executive guidelines, with accredited climbing crews and structural engineers forming the final delivery bottleneck.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among four mobile operators as Ofcom's infrastructure sharing mandates eliminate redundant greenfield construction, compressing the viable supplier set toward tenancy-specialist archetypes with scale or site access advantages.
For Market Incumbents: Harden rural wayleave portfolios through pooled negotiation structures that distribute landowner friction across shared infrastructure joint ventures. Acquire broadcast-to-telecom conversion capabilities to preempt Arqiva's site access differentiation, while securing Health and Safety Executive-accredited maintenance contractor relationships to remove peak-upgrade bottlenecks. Vertical integration into hybrid composite manufacturing reduces exposure to German and Chinese input volatility. For New Entrants and Emerging Players: Mid-band small-cell overlay positions in West Midlands automotive corridors represent the most penetrable entry point, with autonomous vehicle testing facilities generating enterprise-specific demand outside incumbent anchor tenant relationships. Scottish Highlands helicopter-accessible sites offer secondary white-space where shared tenancy models distribute uneconomic landowner negotiations. A go-to-market angle through Emergency Services Network migration contracts provides decade-long revenue visibility with public safety resilience specifications that exceed commercial standards. For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility-arbitrage play because Ofcom's coverage obligations create captive demand with mandated deployment timelines that insulate contracted cash flows from demand cyclicality. Acquisition targets should cluster around independent tower portfolios with concentrated rural wayleave positions in Welsh valleys or Northern England terrain where geographic barriers limit competitive entry. The signal to watch is spectrum auction condition amendments that reset tenancy pricing mechanics or alter infrastructure sharing mandate enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Broadcast-to-Telecom Tower Conversion | Arqiva's deep site access rights accelerate 5G overlay deployment in pre-permitted positions with established power infrastructure. |
| Hybrid Composite Manufacturing Scale-Up | Domestic carbon-fibre reinforced polymer production reduces transport costs for helicopter-lift installations in roadless Scottish valleys. |
| Emergency Services Network Tenancy Capture | Home Office LTE migration contracts provide decade-long revenue visibility with resilience specifications exceeding commercial standards. |
| Rural Wayleave Portfolio Assembly | Pooled landowner negotiations in Welsh and Scottish terrain distribute friction costs across shared infrastructure joint ventures. |
| Health and Safety Executive Contractor Certification | Accredited climbing crew relationships remove maintenance bottlenecks during peak 5G upgrade cycles in urban corridors. |
Research Methodology
A spread of perspectives from tower company operations directors, mobile network infrastructure procurement leads, Health and Safety Executive compliance officers, and rural landowner negotiation specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Ofcom spectrum licence condition documents, UK Electronic Communications Code amendments, British Standard EN 1993 wind load engineering specifications, and Sheffield steel mill output customs records. Bottom-up tenancy contract analysis across Greater London, West Midlands, and Scottish Highlands deployments triangulated against top-down infrastructure investment disclosures from EE, Vodafone, and independent tower operators.
Demand-supply balance across the analysis window reflects 5G densification requirements against steel fabrication capacity constraints and accredited contractor availability. Segmentation modeling incorporated technology generation, structural deployment typology, ownership model restructuring, and end-user vertical with geographic terrain complexity as an industry-specific dimension. CAGRs derived from carrier-reported capital deployment intentions, Ofcom-mandated coverage milestone timelines, and tenancy pricing trajectory indicators from independent infrastructure providers. Forecast inputs included helicopter-access logistics costs for remote terrain and Emergency Services Network migration contract award schedules.
Practitioners should monitor Ofcom spectrum auction condition amendments, UK Electronic Communications Code revisions, and Sheffield steel input pricing volatility for early signals requiring forecast reassessment. Material shifts in infrastructure sharing mandate enforcement intensity or hybrid composite material export-control alignment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
China Telecom Towers Market