
 Saudi Arabia Telecom Towers Market | 2026-2036
Saudi Arabia Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Telecom Towers Market Insights
Open RAN and virtualized baseband architectures are reshaping how telecom infrastructure is deployed across Saudi Arabia. TAWAL leverages its tower portfolio to anchor shared-network agreements with multiple mobile operators. Mobily Tower Assets competes through specialized urban micro-site solutions in dense metropolitan zones. Saudi Telecom Company dominates the wholesale tower segment with extensive macro-tower coverage across the Kingdom's desert corridors.
Saudi Arabia telecom towers are steel, concrete, composite, or aluminum structures engineered to support antenna arrays, transmission equipment, and power systems at heights ranging from below 60 meters to above 150 meters, designed to withstand regional wind loads and seismic conditions while ensuring uninterrupted microwave and radio frequency propagation. These structures serve as the physical backbone for mobile broadband, fixed wireless access, and emergency communications networks. Steel towers occupy the largest share of installed base due to cost efficiency and structural adaptability for monopole and lattice configurations, while composite materials represent the fastest-growing material segment as operators seek reduced weight and corrosion resistance for rooftop and on-building installations in coastal environments. Shared ownership models are expanding fastest as CST regulations incentivize infrastructure neutrality and tenancy ratios improve across independent tower portfolios.
The Communications, Space and Technology Commission enforces infrastructure-sharing mandates and electromagnetic emission standards that directly shape tower siting density and co-location economics. SAMR oversees steel quality certifications and structural safety protocols under GB-influenced standards adapted for Gulf environmental conditions. Tower operators must navigate municipal permitting frameworks that vary across Saudi Arabia's regions, with Riyadh Municipality maintaining stricter aesthetic and zoning controls than emerging economic zones. Stakeholders should monitor how NEOM's integrated digital infrastructure plans and the Kingdom's giga-project pipeline redefine traditional tower economics toward fiber-integrated small-cell densification.
Market Dynamics
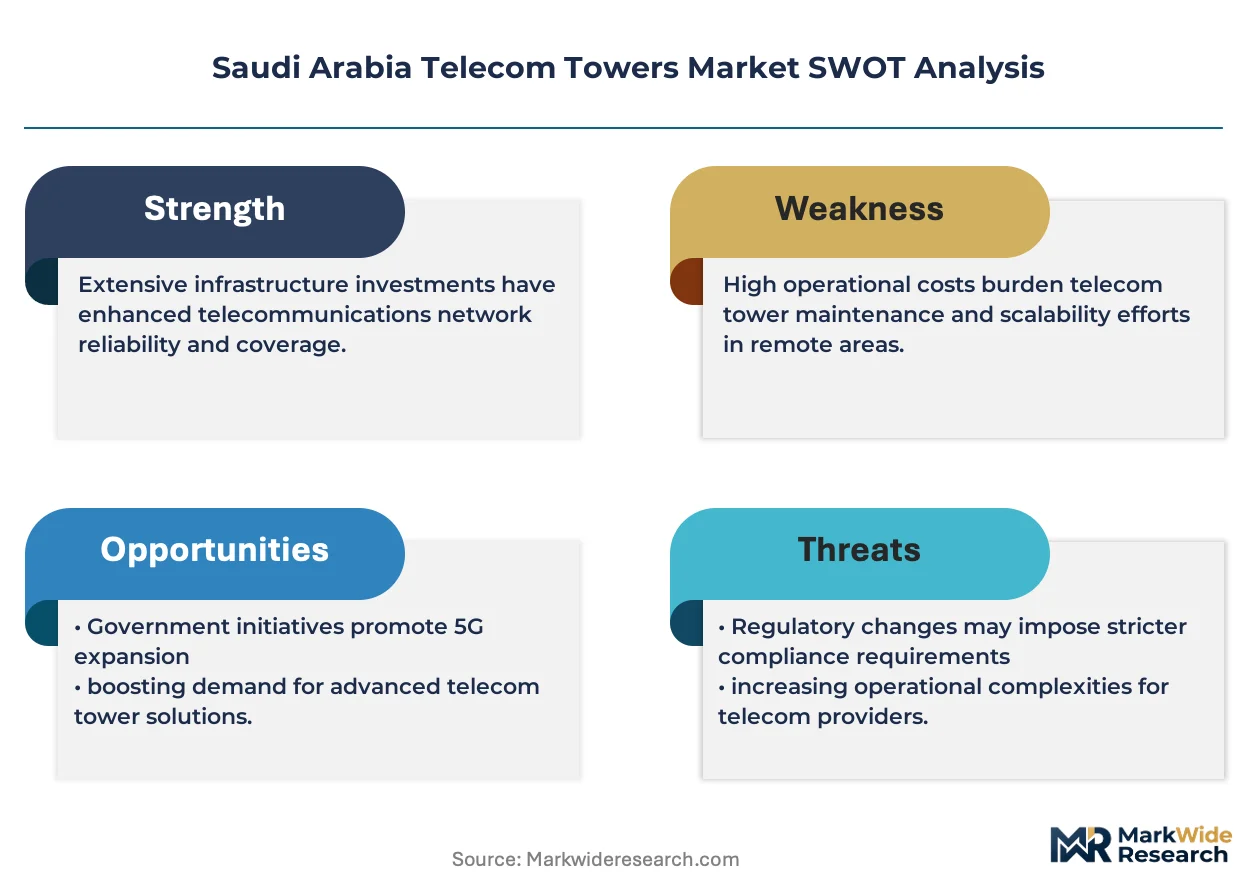
The CST infrastructure-sharing mandate is compressing tower economics by forcing co-location over greenfield builds, while NEOM's fiber-integrated small-cell architecture threatens to bypass traditional macro-tower models entirely.
Growth Catalysts
- 5G spectrum allocation:CST release of mid-band and mmWave frequencies accelerates dense antenna deployment across Riyadh and Eastern Province industrial corridors.
- Giga-project pipeline:NEOM, Red Sea Project, and Qiddiya generate concentrated demand for neutral-host infrastructure in greenfield developments.
- Shared-network agreements:TAWAL's multi-tenant model reduces per-operator capex and accelerates rural coverage obligations.
Market Restraints
- Steel price volatility:SAMR-certified structural steel imports face fluctuating global commodity costs that compress tower fabrication margins.
- Municipal permitting fragmentation:Riyadh Municipality's aesthetic zoning conflicts with CST deployment timelines, creating siting bottlenecks.
- Fiber-to-the-premises substitution:Saudi Telecom Company's FTTH expansion in urban cores reduces fixed wireless access demand for rooftop micro-cells.
Strategic Opportunities
- Coastal composite adoption:Red Sea and Arabian Gulf corrosion environments favor fiberglass-reinforced polymer towers for offshore and maritime connectivity.
- Edge computing convergence:Tower shelters integrating micro data centers serve NEOM's autonomous vehicle and smart city latency requirements.
- Renewable energy pairing:Solar-hybrid power systems at remote desert sites reduce diesel generator dependency and operational expenditure.
Industry Challenges
- Structural engineering talent scarcity:GB-adapted seismic and wind-load certification programs produce fewer qualified designers than deployment timelines demand.
- Legacy microwave backhaul integration:Existing point-to-point links require complex retrofitting to accommodate 5G massive MIMO antenna configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Telecom Towers Market |
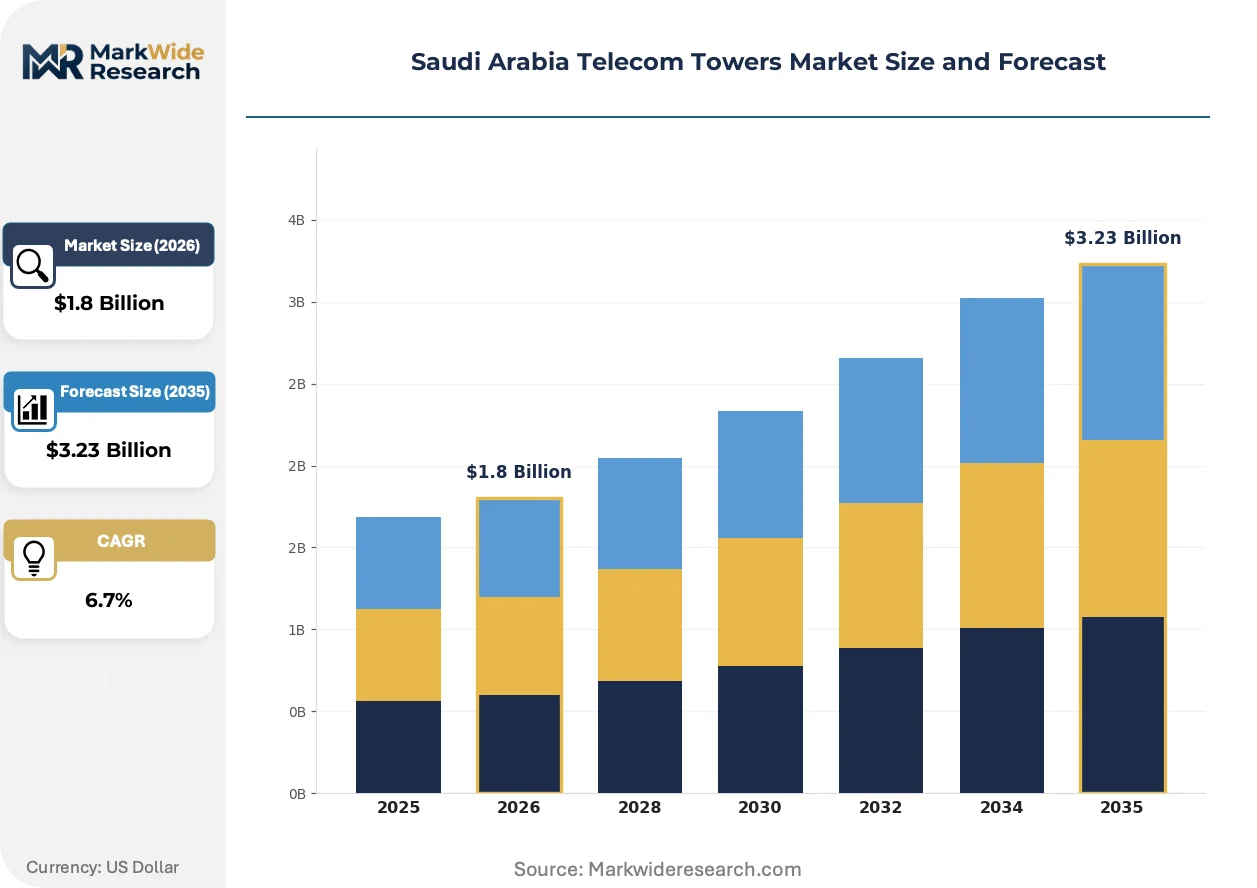
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: On-Building, Off-Building, Rooftop, Monopole Material: Steel, Concrete, Composite, Aluminum Ownership: Private, Government, Shared, Independent Height Category: Below 60m, 60-100m, 100-150m, Above 150m |
| Companies Covered | Golden Lattice Investment Co. (GLIC), TAWAL, Mobily Tower Assets, Etihad Salam Telecom Company, IHS Towers, Saudi Telecom Company (STC), Zain Saudi Arabia, Integrated Telecom Company (ITC), TASC Tower Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Telecom Towers Market Trends and Innovations
Open RAN architectures are fragmenting traditional vendor lock-ins and forcing tower operators to redesign power and space specifications for multi-vendor equipment coexistence.
Composite tower materials are hybridizing antenna support structures by combining pultruded fiberglass with steel cores to cut weight by forty percent while maintaining GB-standard wind ratings. Mobily Tower Assets deploys these configurations across Jeddah rooftop installations where structural load limits constrain conventional steel. This hybridization enables co-location of four operators where legacy designs supported two.
CST electromagnetic emission standards now mandate cumulative field strength modeling before multi-tenant activation, extending pre-deployment validation timelines. The regulation compresses tenancy revenue recognition cycles and forces portfolio operators to invest in predictive RF simulation software. Eastern Province oil and gas facilities face the strictest enforcement due to hazardous area classification overlaps.
Neutral-host procurement now dominates enterprise and venue connectivity contracts, displacing single-operator exclusive agreements. Stadiums, hospitals, and shopping malls in Riyadh and Dammam now specify infrastructure-as-a-service terms with guaranteed coverage SLAs. This shift concentrates buying power among real estate developers and facility managers rather than mobile network operators.
Saudi Arabia Telecom Towers Market Segmentation
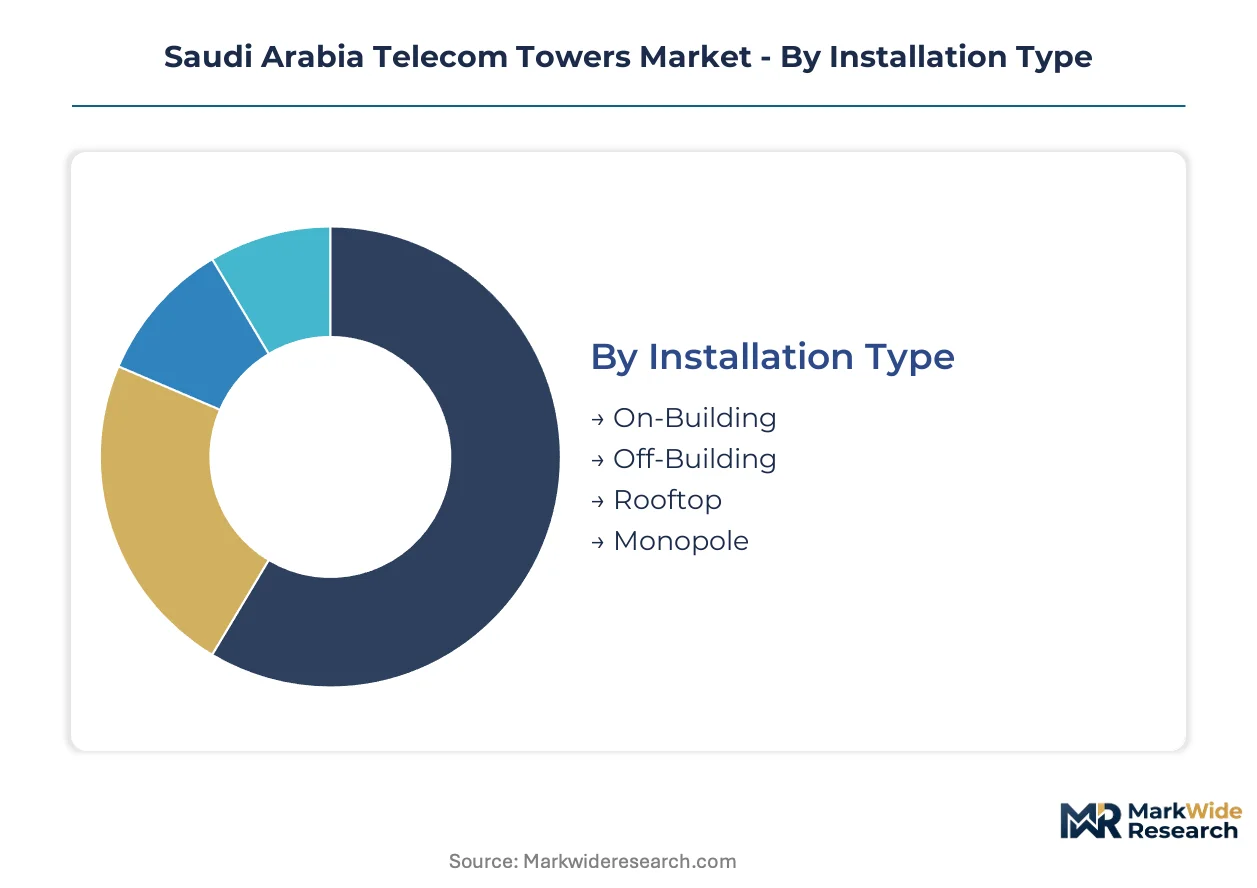
Tower deployment patterns across Saudi Arabia diverge sharply between dense urban corridors and remote industrial zones. Material selection and ownership structures shift with CST co-location mandates and NEOM's fiber-integrated infrastructure requirements.
Installation Type:
Deployment configurations span concealed urban integration to exposed macro structures across the Kingdom's varied topography.
- Rooftop:Low-profile antenna arrays mount on commercial and residential buildings in Riyadh's central business district. Municipal aesthetic codes restrict visual impact, pushing operators toward compact, camouflaged enclosures.
- Monopole:Single-shaft steel structures dominate highway corridors and suburban expansion zones. Eastern Province industrial clusters favor these for rapid deployment and minimal land footprint.
- On-Building:Facade-mounted systems serve historic districts where freestanding towers face preservation restrictions. Jeddah's Al-Balad district requires specialized mounting brackets.
- Off-Building:Ground-based lattice and guyed masts cover rural coverage obligations and desert pipeline routes. Remote sites integrate solar-hybrid power to offset diesel logistics.
Established volume favors monopole deployments; emerging adoption favors rooftop concealment.
Material:
Structural composition trades fabrication cost against environmental durability and load-bearing requirements.
- Steel:Carbon and high-strength low-alloy grades constitute the bulk of macro-tower fabrication. SAMR-certified mills supply lattice frameworks for CST-mandated infrastructure sharing.
- Composite:Fiberglass-reinforced polymer structures cut weight by forty percent versus steel equivalents. Red Sea coastal projects specify these for corrosion immunity in maritime atmospheres.
- Concrete:Reinforced precast shafts anchor high-load broadcast and emergency communications towers. Seismic zones in Asir Province require enhanced foundation specifications.
- Aluminum:Lightweight alloy masts serve temporary event coverage and rapid-deployment military applications. Premium cost limits widespread adoption.
Steel retains dominant share; composite materials are climbing the fastest.
Ownership:
Asset control models determine capital efficiency and regulatory compliance pathways.
- Shared:Multi-tenant infrastructure pools capex across mobile network operators. CST guidelines mandate this model for all greenfield deployments in Riyadh and Dammam metropolitan areas.
- Independent:Neutral-host specialists like TAWAL aggregate portfolios for wholesale lease to operators. Tenancy ratio improvements drive margin expansion.
- Government:State entities retain strategic towers for sovereign communications and emergency services. Defense and interior ministry networks operate outside commercial sharing frameworks.
- Private:Single-operator captive structures persist in legacy rural deployments. CST pressure accelerates divestment to shared or independent models.
Shared ownership gains regulatory backing; independent portfolios attract capital inflows.
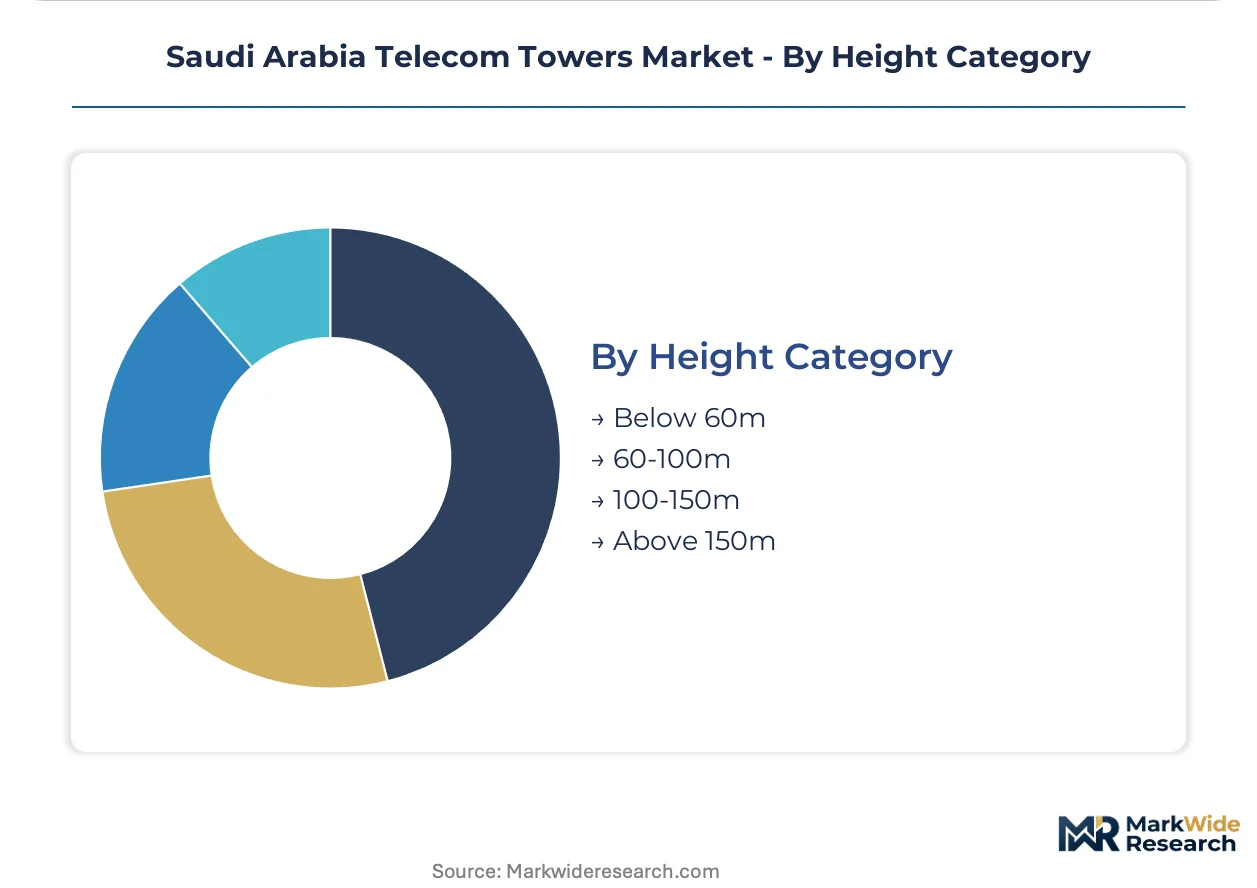
Height Category:
Vertical reach correlates directly with coverage radius, spectrum propagation characteristics, and structural engineering complexity.
- Below 60m:Compact monopoles and rooftop poles serve dense urban micro-cell grids. Riyadh Municipality height restrictions favor this tier for central district deployments.
- 60-100m:Mid-range macro towers balance coverage footprint with aviation clearance requirements. This tier dominates suburban 5G mid-band rollout.
- 100-150m:Elevated lattice structures penetrate terrain shadows in Asir and Tabuk mountain provinces. Microwave backhaul integration requires specialized platform engineering.
- Above 150m:Broadcast-grade towers and long-haul microwave relays span desert plains. Limited inventory concentrates with Saudi Telecom Company's wholesale infrastructure.
60-100m structures anchor current deployment; below-60m installations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile network operators and independent tower companies concentrate procurement decisions in four sub-regions where CST infrastructure-sharing mandates intersect with giga-project development timelines and population density gradients.
Riyadh
The capital's central business district drives concealed rooftop deployment as municipal aesthetic codes restrict visual impact. CST mandates multi-tenant infrastructure for all greenfield builds in metropolitan boundaries. King Abdullah Financial District anchors neutral-host contracts with guaranteed coverage SLAs.
Eastern Province
Industrial corridors around Dammam and Jubail generate concentrated co-location demand from oil and gas facilities with hazardous area classifications. SAMR enforces stricter electromagnetic emission standards here than elsewhere in the Kingdom. Ras Al-Khair Minerals Industrial City attracts fiber-integrated small-cell densification.
Western Region
Jeddah's Al-Balad historic district requires specialized facade-mounted systems where preservation restrictions block freestanding towers. Red Sea coastal corrosion environments accelerate composite material adoption for maritime connectivity. King Abdullah Economic City anchors enterprise neutral-host procurement.
NEOM Northwest
The giga-project's integrated digital infrastructure plans bypass traditional macro-tower economics entirely. Edge computing convergence drives tower shelters with micro data centers for autonomous vehicle latency requirements. THE LINE's linear city architecture demands vertical infrastructure integration unprecedented in Saudi deployment history.
Saudi Arabia Telecom Towers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The wholesale tower segment concentrates around state-affiliated entities with extensive macro-tower coverage, while independent neutral-host specialists aggregate portfolios for multi-tenant lease arrangements. Urban micro-site specialists target dense metropolitan zones with concealed installations. Competitive moves center on tenancy ratio improvement through portfolio aggregation and fiber-integrated infrastructure partnerships for giga-project participation.
Within the state-affiliated tier, Saudi Telecom Company and TAWAL occupy positions defined by legacy macro-tower inventory and shared-network agreement anchoring respectively. Mobily Tower Assets exemplifies the urban specialist archetype through concentrated metropolitan deployment. These three entities represent the dominant competitive anchors as CST regulations accelerate infrastructure neutrality and tenancy economics reshape capital allocation across the Kingdom.
| Leading Market Players |
|---|
| Golden Lattice Investment Co. (GLIC) |
| TAWAL |
| Mobily Tower Assets |
| Etihad Salam Telecom Company |
| IHS Towers |
| Saudi Telecom Company (STC) |
| Zain Saudi Arabia |
| Integrated Telecom Company (ITC) |
| TASC Tower Company |
| Others |
Pricing and Supply Chain Analysis
Eastern Province industrial clusters anchor Saudi Arabia's steel tower fabrication capacity, and their output fluctuations directly transmit into lease rate negotiations between TAWAL and mobile network operators seeking co-location tenancy.
Pricing Analysis
Cost-plus contracts with SAMR-certified steel indexation dominate tower lease agreements between independent operators and mobile network operators. Price differentiation rests on tenancy ratio and fiber backhaul availability rather than structural height or material grade. Pricing pressure stems from CST-mandated infrastructure sharing that compresses per-tenant revenue while extending amortization timelines. Rural coverage obligations show highest price sensitivity; NEOM giga-project deployments show lowest due to sovereign funding guarantees.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia dominates structural steel input costs for lattice tower fabrication. SAMR-certified mills in the Kingdom, South Korea, and Turkey supply high-strength low-alloy grades for macro-tower construction. Tower production draws from galvanized steel coil, composite resin systems, and microwave backhaul equipment. Single-source vulnerability concentrates in GB-adapted seismic certification programs. Distribution runs through tower company direct procurement with Saudi Telecom Company and TAWAL maintaining captive supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across Saudi Arabia's telecom towers landscape as CST infrastructure-sharing mandates splinter legacy single-operator deployments into multi-tenant neutral-host configurations.
For Market Incumbents: Build regulatory moat through preemptive CST compliance certification for all greenfield portfolios. Deepen backward integration into SAMR-certified steel fabrication to offset commodity volatility. Anchor shared-network agreements with sovereign wealth-backed giga-projects before fiber-integrated small-cell architectures bypass macro-tower economics entirely. For New Entrants and Emerging Players: Coastal composite tower installations for Red Sea maritime connectivity represent the most penetrable entry point given corrosion-driven material substitution. Rooftop concealment specialists in Riyadh's aesthetic-restricted central business district offer second white-space target. Go-to-market through real estate developer partnerships rather than mobile operator direct sales accelerates neutral-host contract capture. For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because tenancy ratio improvements generate annuity-like cash flows under CST-mandated sharing frameworks. Target acquisition archetype: independent tower portfolios with sub-1.5 tenancy ratios in Eastern Province industrial corridors. Watch NEOM fiber-to-the-premises penetration rates as signal for traditional macro-tower demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Transition | Fiberglass-reinforced polymer adoption cuts coastal tower weight by forty percent while satisfying SAMR wind-load requirements. |
| Edge Computing Integration | Tower shelters with micro data centers address NEOM autonomous vehicle latency requirements outside traditional telecom scope. |
| Shared-Network Agreement Expansion | Multi-tenant contracts with CST-mandated terms reduce per-operator capex and accelerate rural coverage obligations. |
| Renewable Energy Pairing | Solar-hybrid power systems at remote desert sites reduce diesel logistics costs and operational expenditure. |
| Neutral-Host Procurement Capture | Infrastructure-as-a-service contracts with real estate developers displace single-operator exclusive agreements in Riyadh and Dammam. |
Research Methodology
A spread of perspectives from tower portfolio managers, CST regulatory affairs officers, SAMR certification engineers, and mobile network operator procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through CST infrastructure-sharing guidelines, SAMR steel quality protocols, and municipal permitting databases from Riyadh Municipality and Eastern Province economic zones. Bottom-up tower deployment counts triangulated against top-down mobile operator capex disclosures.
Demand-supply balance modeling anchored the forecast framework across the analysis window. Segmentation dimensions included installation type, material composition, ownership structure, and height category alongside regional deployment intensity. CAGRs derived from tenancy ratio improvement curves and giga-project pipeline acceleration. Key inputs encompassed CST electromagnetic emission standard enforcement timelines and NEOM fiber-integrated infrastructure substitution rates.
Macroeconomic conditions sit as an overlay; deviation in steel commodity indices or sovereign giga-project funding commitments would shift the trajectory. Forecasts reflect documented assumptions about CST regulatory continuity and SAMR certification program stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Chile Telecom Tower Market