
 ESR Analyzer Market | 2026-2036
ESR Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
ESR Analyzer Market Analysis
The gap between premium fully automated systems and entry-level semi-automated units is rebalancing as hospital procurement committees tighten capital budgets while diagnostic laboratories prioritize throughput accuracy. Alifax leverages proprietary microsedimentation technology to sustain margin pools in high-volume European reference labs. Streck competes on reagent standardization, while Thermo Fisher Scientific anchors its position through distribution scale across North American health systems.
An ESR analyzer measures erythrocyte sedimentation rate, the distance red blood cells descend in anticoagulated blood over one hour, typically reporting results in millimeters per hour to flag inflammatory conditions. Fully automated optical systems now dominate installed bases in hospitals, while portable ultrasonic designs represent the fastest-growing configuration for point-of-care clinics where space constraints and rapid turnaround override throughput needs. Electrochemical technology occupies a narrower niche in research institutions seeking multiplexed inflammatory biomarker correlation.
The FDA enforces quality system regulation and in vitro diagnostic device standards that shape validation timelines for new ESR analyzer submissions, while the EU MDR and IVDR frameworks in Europe impose stricter clinical evidence requirements for automated systems. ISO 15189 accreditation standards for medical laboratories directly influence instrument specification priorities. Stakeholders must monitor how evolving regulatory divergence between US and European conformity pathways affects platform development roadmaps and geographic launch sequencing.
Market Dynamics
Hospital procurement committees are compressing capital equipment approval timelines while demanding higher throughput accuracy from automated ESR systems, forcing manufacturers to rebalance feature sets against price positioning.
Growth Catalysts
- EU IVDR compliance deadlines:Medical laboratories across Germany and France are accelerating instrument replacement cycles to meet stricter clinical evidence requirements for automated diagnostic devices.
- Point-of-care expansion:Ultrasonic portable analyzers are penetrating rural clinic networks where space constraints and rapid turnaround requirements override centralized laboratory throughput priorities.
- Diagnostic laboratory consolidation:Hospital network mergers in North America are creating volume concentration that favors high-capacity optical sedimentation systems with integrated quality control.
Market Restraints
- Optical component supply concentration:Precision photodetectors and laser modules for fully automated systems depend heavily on specialized Japanese and German component suppliers, creating vulnerability to regional production disruptions.
- Reagent standardization friction:Variability in anticoagulant formulations and tube specifications across health systems complicates cross-platform result comparability and regulatory submissions.
- Manual method persistence:Westergren manual reference methods retain regulatory acceptance in emerging markets, delaying automated system penetration where labor costs suppress replacement economics.
Strategic Opportunities
- Indian diagnostic infrastructure buildout:CDSCO streamlined pathways for Class B in vitro diagnostic devices are shortening validation timelines for semi-automated ESR analyzers targeting tier-2 and tier-3 cities.
- Multiplexed inflammatory panels:Electrochemical sensor platforms capable of correlating ESR with C-reactive protein and procalcitonin are opening research institution contracts previously served by discrete analyzers.
- Cloud-connected service models:Remote calibration and predictive maintenance subscriptions are displacing traditional break-fix service contracts in European reference laboratories seeking operational expenditure predictability.
Industry Challenges
- ISO 15189 accreditation complexity:Medical laboratories require extensive documentation of traceability and measurement uncertainty, extending sales cycles and demanding specialized field application support.
- Legacy LIS integration:Hospital information systems with proprietary data formats create middleware development burdens that fragment engineering resources across customer-specific implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESR Analyzer Market |
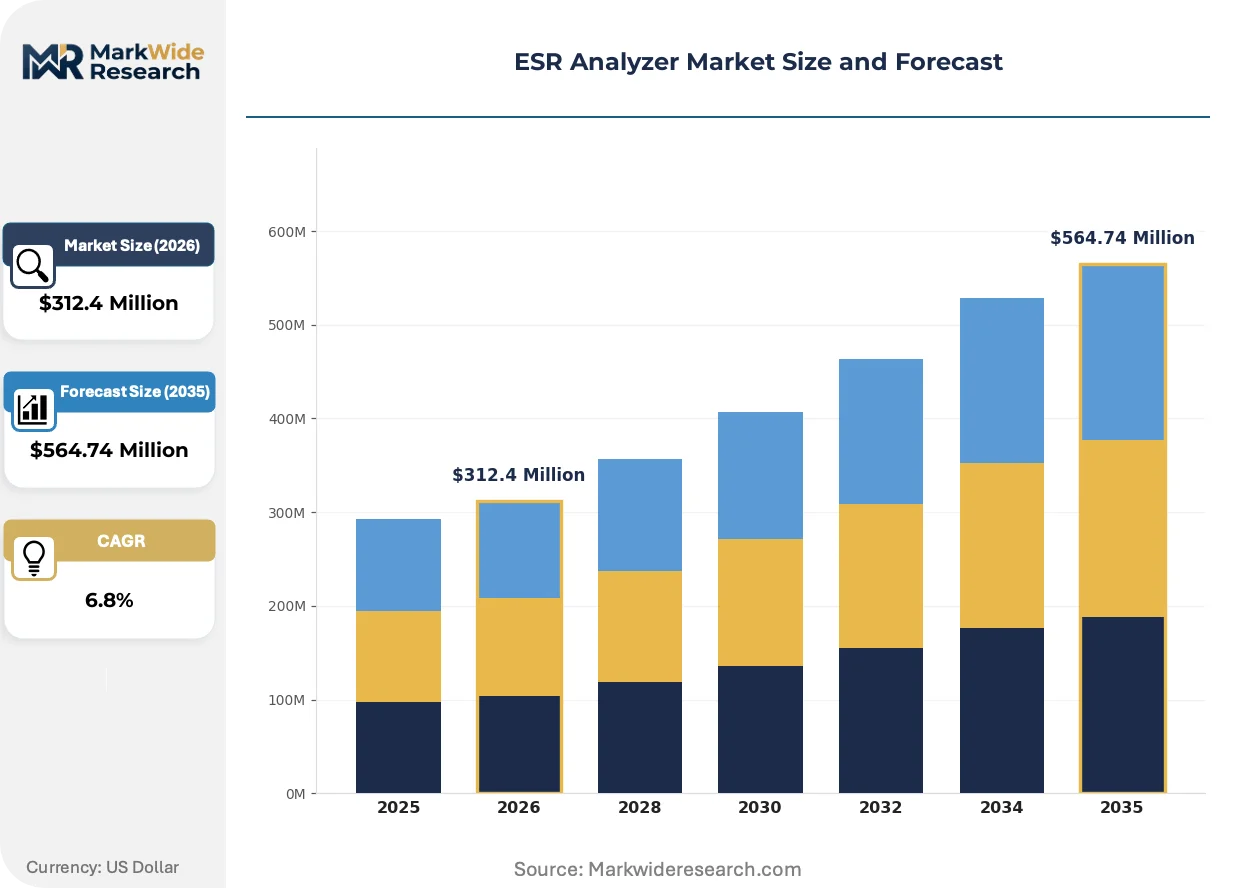
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi-Automated, Manual, Portable End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Optical, Electrochemical, Magnetic, Ultrasonic Application: Rheumatology, Oncology, Infectious Diseases, General Health |
| Companies Covered | ALCOR Scientific, Diesse Diagnostica Senese, Alifax, JOKOH, Sarstedt, Streck, RR Mechatronics, Thermo Fisher Scientific, ELITechGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESR Analyzer Market Emerging Trajectories
Digital sedimentation imaging and artificial intelligence-assisted result interpretation are compressing analytical turnaround times while reducing operator-dependent variability in high-volume testing environments.
Microfluidic sample handling technology is integrating precision flow control with miniaturized optical detection to enable cartridge-based ESR testing at point-of-care sites. Urgent care clinics and physician office laboratories are adopting these systems to eliminate sample transport delays. The technology is integrating hematocrit correction algorithms directly into result generation, removing manual calculation steps that previously introduced transcription errors.
EU MDR recertification requirements for legacy automated analyzers are forcing manufacturers to regenerate clinical performance data under stricter post-market surveillance obligations. Device establishments must now maintain systematic literature review processes and periodic safety update reports that extend regulatory affairs staffing requirements. High-volume German and French reference laboratories are prioritizing platforms with established IVDR technical documentation to avoid service interruptions during transition periods.
Buying committees are unbundling analyzer hardware from reagent supply agreements that previously locked laboratories into multi-year consumable commitments. Independent service organizations are capturing maintenance contracts previously held by original equipment manufacturers, particularly in North American health systems with centralized biomedical engineering departments. This disintermediation is most pronounced in California and Texas hospital networks where group purchasing organizations have negotiated direct reagent sourcing arrangements.
ESR Analyzer Market Segmentation
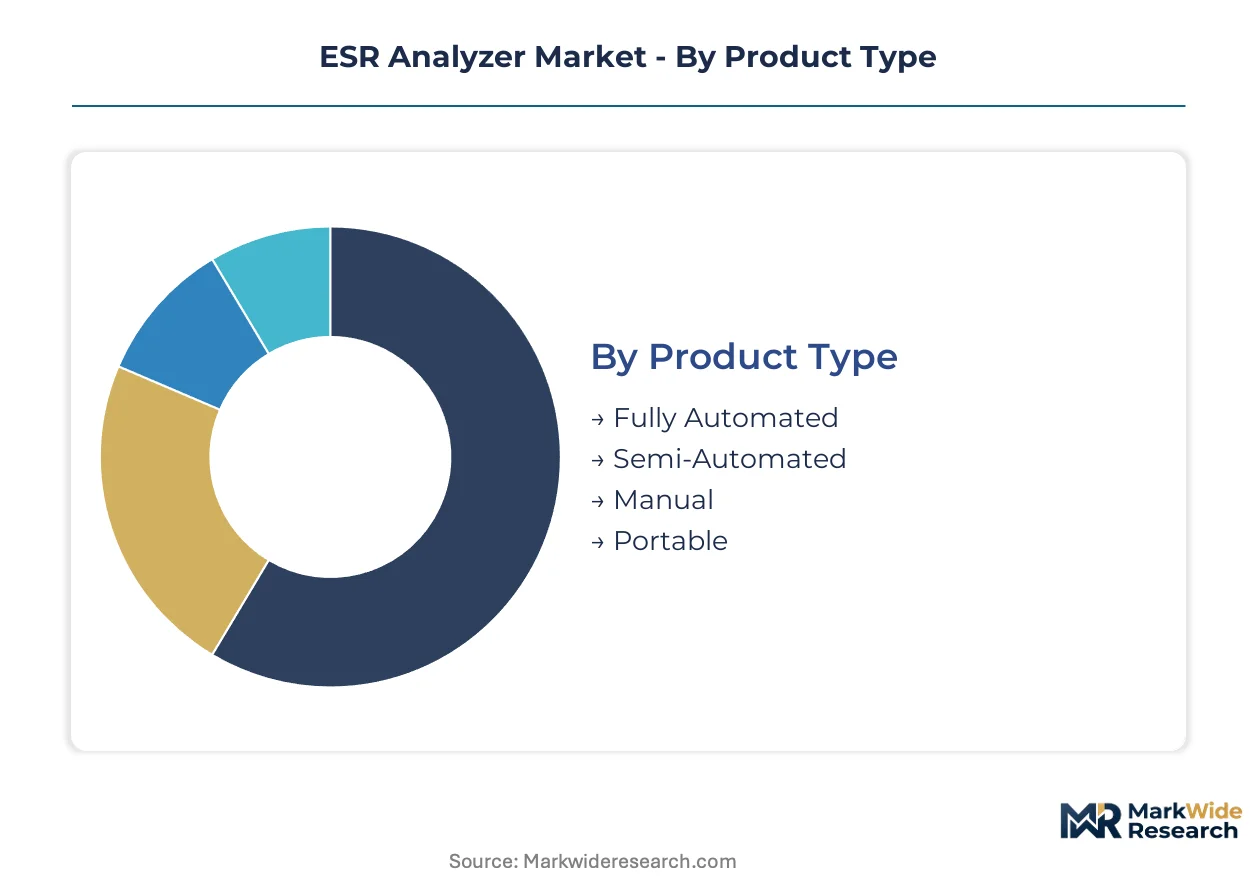
ESR analyzer procurement patterns diverge sharply across facility types, with hospital networks prioritizing throughput integration while point-of-care sites trade capacity for portability. Technology selection directly constrains reagent standardization and regulatory compliance pathways.
Product Type:
Customization intensity spans from closed-system fully automated platforms to configurable manual workstations that accommodate diverse anticoagulant protocols.
- Fully Automated:Closed-system optical sedimentation platforms integrate sample handling, imaging detection, and LIS connectivity for high-throughput hospital laboratories. Demand concentrates in German and French reference laboratories replacing legacy systems ahead of EU IVDR deadlines.
- Semi-Automated:Modular designs permit partial operator intervention for sample preparation while automating sedimentation measurement and result calculation. North American diagnostic laboratory consolidations favor these units for mid-volume satellite facilities seeking capital efficiency.
- Portable:Battery-powered ultrasonic analyzers with cartridge-based sample handling address space-constrained urgent care clinics and rural physician offices.
- Manual:Westergren-method glass tube systems persist in emerging market laboratories where labor cost structures delay automation economics.
Leading the category by volume: Fully Automated. Expanding most quickly: Portable.
End User:
Procurement authority and reimbursement pathways reshape specification priorities across facility categories with divergent capital cycles.
- Hospitals:Integrated health system laboratories demand analyzers with embedded quality control, bidirectional LIS connectivity, and predictive maintenance telemetry. US hospital procurement committees compress approval timelines while demanding throughput guarantees.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated central labs prioritize reagent standardization and cross-platform result traceability. German laboratory consolidation accelerates instrument replacement cycles.
- Clinics:Urgent care and physician office laboratories favor rapid-turnaround portable systems with minimal operator training requirements.
- Research Institutions:Academic medical centers and contract research organizations seek electrochemical platforms capable of multiplexed inflammatory biomarker correlation.
Dominant procurement volume: Hospitals. Steepest expansion trajectory: Clinics.
Technology:
Detection modality determines precision specifications, maintenance burden, and regulatory validation complexity across installation environments.
- Optical:Laser-photodetector systems measuring sedimentation rate through transmittance or imaging capture dominate hospital installed bases. Precision photodetectors from Japanese and German suppliers create supply concentration risk.
- Ultrasonic:Acoustic impedance measurement enables miniaturization for point-of-care deployment without centrifugation or anticoagulant-dependent calibration. Rural clinic networks in India and Texas health systems drive adoption.
- Electrochemical:Sensor arrays correlating erythrocyte aggregation with impedance changes occupy research niches seeking C-reactive protein and procalcitonin multiplexing.
- Magnetic:Magnetic field gradient systems for enhanced sedimentation control remain limited to specialized research applications.
Widest installed base: Optical. Gaining share fastest: Ultrasonic.
Application:
Clinical indication shapes test frequency, turnaround requirements, and reimbursement coding that influence analyzer specification.
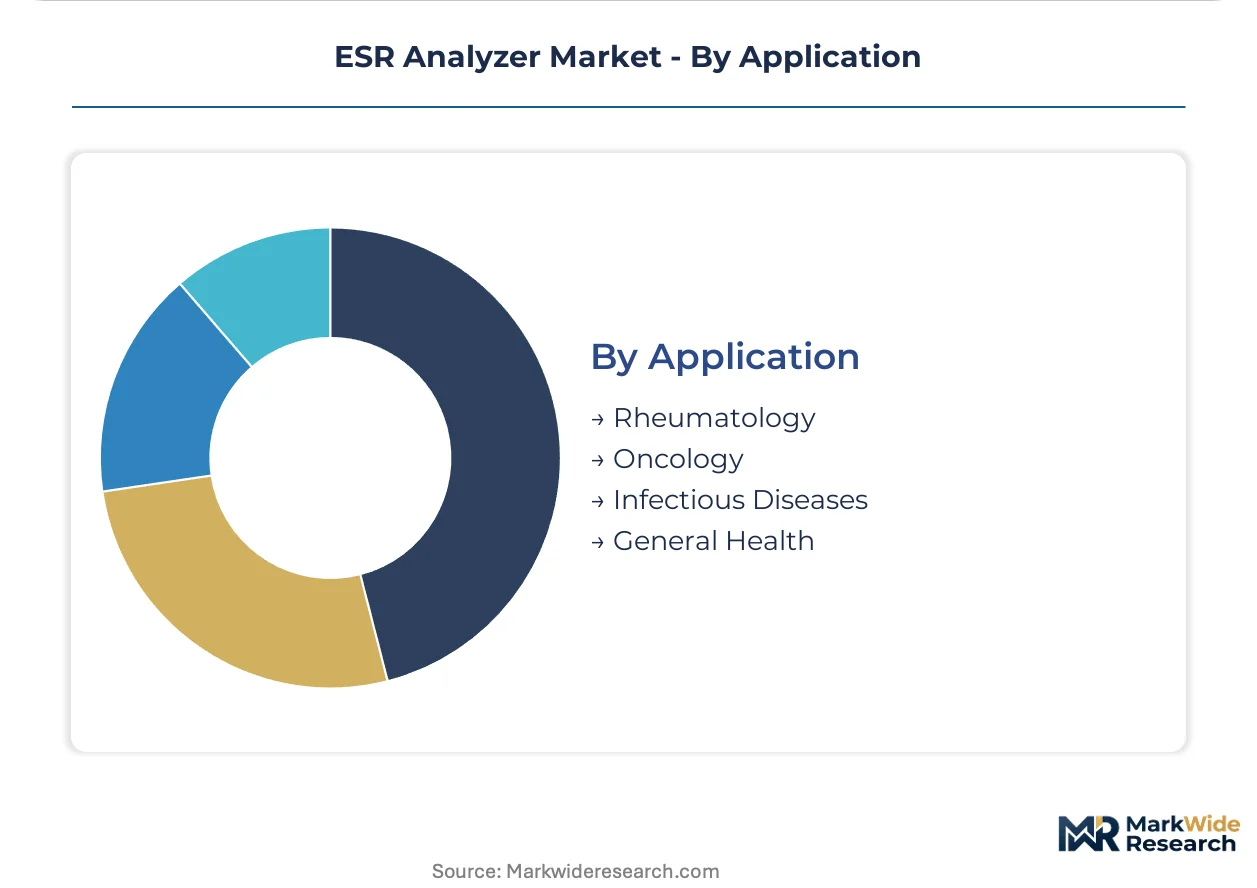
- Rheumatology:Systemic lupus erythematosus and rheumatoid arthritis monitoring generates recurring ESR orders requiring high-precision trending. Hospital rheumatology departments prioritize platforms with automated delta-check flagging.
- Infectious Diseases:Sepsis workups and post-operative infection surveillance demand rapid turnaround that point-of-care ultrasonic systems address. US urgent care chains specify sub-15-minute result generation.
- Oncology:Cancer-related inflammation monitoring and chemotherapy response assessment requires integration with tumor marker panels in comprehensive cancer centers.
- General Health:Routine wellness screening and pre-surgical baseline testing in primary care settings tolerates longer turnaround times.
Highest test volume: Rheumatology. Climbing the fastest: Infectious Diseases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's diagnostic corridor anchors European ESR analyzer demand as hospital networks consolidate laboratory infrastructure ahead of regulatory deadlines.
United States
Texas and California hospital systems drive procurement of high-throughput optical platforms as group purchasing organizations negotiate direct reagent sourcing. FDA quality system regulation updates reshape validation timelines for new device submissions. The Southeast urgent care corridor from Atlanta to Dallas adopts portable ultrasonic systems for sub-15-minute turnaround requirements.
Germany
Diagnostic laboratory consolidation in North Rhine-Westphalia and Bavaria accelerates replacement cycles for legacy automated systems. EU IVDR compliance deadlines force reference laboratories to prioritize platforms with established technical documentation. Berlin-Brandenburg medical centers demand integrated quality control and predictive maintenance telemetry.
India
Tier-2 and tier-3 city diagnostic buildout creates demand for semi-automated ESR analyzers as CDSCO streamlined pathways shorten validation timelines. The country's national pharmaceutical regulator enforces Class B in vitro diagnostic device standards for imported systems. Maharashtra's Mumbai-Pune pharmaceutical corridor hosts expanding reference laboratory networks.
Japan
Precision photodetector supply concentration in Osaka-Kobe industrial zones creates vulnerability for optical system manufacturers dependent on specialized components. PMDA medical device review standards influence regional validation requirements for automated sedimentation platforms. Tokyo's university hospital networks prioritize platforms with embedded hematocrit correction algorithms.
France
EU MDR recertification requirements force Paris and Lyon reference laboratories to regenerate clinical performance data under stricter post-market surveillance. ANSM national health product safety agency guidelines shape procurement specifications for inflammatory biomarker testing. The Île-de-France hospital network consolidates purchasing authority across 39 public institutions.
ESR Analyzer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as fully automated optical platform development demands specialized photonics engineering while portable ultrasonic configurations enable modular assembly partnerships. The vendor base separates into three tiers: integrated diagnostics conglomerates with distribution scale, regional specialists with proprietary detection technologies, and contract manufacturers serving private-label programs. Consolidation pressures concentrate among mid-scale European reference laboratory suppliers. Dominant competitive moves include technology licensing agreements for microfluidic sample handling and strategic partnerships with Japanese photodetector foundries.
Among Italian diagnostic specialists, Diesse Diagnostica Senese and Alifax occupy positions defined by proprietary sedimentation methodologies and sustained relationships with high-volume European reference laboratories. Streck represents the reagent standardization archetype through its consumables-focused positioning. Thermo Fisher Scientific anchors the scale-driven tier through distribution infrastructure across North American health systems. These three exemplify how competitive positioning separates hardware-integrated platforms from consumables-recurring models.
| Leading Market Players |
|---|
| ALCOR Scientific |
| Diesse Diagnostica Senese |
| Alifax |
| JOKOH |
| Sarstedt |
| Streck |
| RR Mechatronics |
| Thermo Fisher Scientific |
| ELITechGroup |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees and diagnostic laboratory consolidators anchor pricing power in the ESR analyzer market, forcing manufacturers toward throughput-guarantee contracts and reagent-bundled service models that shift capital expenditure into operational expenditure streams.
Pricing Analysis
Throughput-based pricing anchors value capture for fully automated optical systems, with German and French reference laboratories paying premium rates for platforms guaranteeing specimen-per-hour minimums and predictive maintenance uptime commitments. Price differentiation rests on IVDR technical documentation completeness and integrated LIS connectivity depth, with FDA-cleared systems commanding modest premiums in North American health systems. Cost compression in semi-automated tiers intensifies as Indian tier-2 city laboratories demand stripped-down configurations. Research institutions show least price sensitivity for electrochemical multiplexing platforms, while urgent care chains in Texas and California drive hardest bargains on portable ultrasonic units.
Supply Chain Analysis
Photonics engineering workforce availability in Osaka-Kobe industrial zones and Munich's precision manufacturing corridor concentrates specialized talent for optical system production. Precision photodetectors and laser modules draw from Japanese and German component suppliers, while microfluidic cartridge manufacturing sources from Taiwanese polymer molding specialists. Single-source vulnerability in photodetector supply creates exposure to regional production disruptions. Distribution runs through hospital group purchasing organizations in North America and direct tender processes in European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESR analyzer market operates as a vertical-integration race, with players pursuing backward control over precision photodetector supply and forward capture of cloud-connected service revenue to defend margin pools.
For Market Incumbents: Acquire Japanese photodetector foundry capacity or exclusive supply agreements to secure optical system component access against emerging entrant cost pressure. Strengthen IVDR technical documentation for legacy platforms ahead of EU compliance deadlines. Expand predictive maintenance telemetry subscriptions to displace independent service organizations capturing European reference laboratory contracts. For New Entrants and Emerging Players: Enter via CDSCO-streamlined Class B pathways for semi-automated ESR analyzers targeting Maharashtra's Mumbai-Pune diagnostic corridor and tier-3 Indian cities where manual Westergren methods persist. Prioritize ultrasonic portable configurations for Texas and Southeast US urgent care chains demanding sub-15-minute turnaround. Pursue modular assembly partnerships with Taiwanese microfluidic cartridge specialists to bypass capital-heavy optical platform development. For Investors and Strategic Acquirers: The window for entry favors asset-light portable system designers with established regulatory pathways in India and US urgent care penetration. Long-term viability hinges on cloud-connected service model traction and reagent standardization lock-in. Watch IVDR transition completion rates in German reference laboratories as inflection indicator for platform replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Photodetector Supply Agreement | Secures precision component access against Osaka-Kobe production concentration risk. |
| IVDR Technical Documentation Investment | Enables uninterrupted service in EU reference laboratories facing recertification deadlines. |
| Cloud-Connected Service Launch | Captures operational expenditure shift in European laboratories seeking predictability. |
| Microfluidic Cartridge Partnership | Accelerates point-of-care portable system development without captive polymer molding. |
| CDSCO Regulatory Pathway Navigation | Unlocks tier-2 and tier-3 Indian city diagnostic infrastructure buildout opportunities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineering directors, diagnostic laboratory managers, GPO contracts specialists, and IVD regulatory affairs leads. FDA 510(k) submissions, EU MDR/IVDR notified body opinions, CDSCO import registration databases, and hospital procurement system records provided validation triangulation. Bottom-up instrument shipment analysis and top-down healthcare expenditure allocation modeling were reconciled.
Data-stream reconciliation across product type, end user facility category, detection technology modality, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle analysis and point-of-care penetration trajectory assessment. Forecast inputs incorporated EU IVDR compliance deadline pacing, Indian diagnostic infrastructure investment flows, and ultrasonic portable system adoption curves in US urgent care networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under photodetector supply disruption scenarios or IVDR transition deadline extensions. Forecasts reflect documented assumptions regarding laboratory consolidation pacing and point-of-care reimbursement stability. Material deviation in FDA quality system regulation update timing or CDSCO pathway modification warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Microplate Instrumentation and Systems Market