
 Global Digital Business Card Market | 2026-2036
Global Digital Business Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Business Card Market Foresight
Mobile-first sales talent is reorganizing how professional identity travels across digital channels, forcing platforms to embed CRM sync and analytics natively. Sansan leverages its enterprise footprint across Japanese corporations to anchor recurring revenue from large account deployments. HiHello Inc. competes through freemium-to-enterprise conversion mechanics that sustain viral user acquisition loops. Mobilo Inc. differentiates by embedding lead capture forms directly into NFC tap flows, occupying a functional niche between contact exchange and pipeline generation.
A digital business card is an electronic credential that transmits contact and professional identity data through near-field communication chips, QR code matrices, Bluetooth Low Energy beacons, or cloud-hosted profiles accessible via mobile applications, typically encoding vCard formats or proprietary schemas with real-time update capability. Its primary commercial purpose is to eliminate friction in professional networking while enabling trackable engagement analytics and automated CRM ingestion. NFC cards dominate premium deployments where tactile exchange rituals persist, while SaaS delivery models capture the fastest expansion as IT departments centralize vendor management and security review. Corporate Enterprises represent the deepest margin pool due to bulk licensing and API integration requirements, though Freelancers and Consultants drive organic platform growth through individual subscription tiers.
FDA oversight of software-as-medical-device claims intersects with FCC regulations governing NFC and Bluetooth radio transmissions in the United States, creating a dual compliance threshold for vendors pitching healthcare-adjacent use cases. The EU AI Act and GDPR impose automated decision-making transparency and data residency constraints that reshape product architecture for European deployments. Stakeholders must monitor how ISO standards for digital identity interoperability crystallize, as compliance alignment will determine which platforms gain procurement eligibility in regulated industries.
Market Dynamics
The EU AI Act and GDPR compliance requirements are compressing vendor architectures toward privacy-first designs, forcing platforms to rebuild data handling pipelines and residency controls from the ground up.
Growth Catalysts
- NFC Hardware Miniaturization:Japanese semiconductor fabs have reduced NFC chip form factors below 2mm², enabling embeddability in jewelry and wearables for executive networking segments.
- GDPR Article 17 Mandates:Right-to-erasure provisions accelerate enterprise procurement of digital card platforms with automated data deletion workflows, particularly among German automotive suppliers.
- CRM Native Integration:Salesforce and HubSpot API ecosystems now treat contact exchange as a first-class data object, pulling digital business cards into pipeline automation without middleware.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundries fabricate over 80% of NFC controller chips, exposing vendors to geopolitical disruption in the Taiwan Strait.
- Bluetooth LE Interference:Dense urban RF environments in Manhattan and Tokyo degrade tap-to-connect reliability, forcing fallback to QR codes and degrading perceived premium value.
- FCC Equipment Authorization:Part 15 certification timelines for custom NFC antenna designs extend 8-14 months, delaying product launches for hardware-centric entrants.
Strategic Opportunities
- Indian SME Formalization:India's PLI scheme for electronics manufacturing creates localized NFC card production capacity, cutting landed costs for domestic SaaS vendors by 40-60%.
- Healthcare Adjacency:HIPAA-compliant digital credentials for pharmaceutical reps accessing restricted hospital zones represent an unserved vertical with annual contract values 3-4x standard enterprise tiers.
- Web3 Identity Convergence:Ethereum Name Service and verifiable credential standards enable wallet-based professional identity, opening decentralized architecture partnerships for incumbent platforms.
Industry Challenges
- vCard Schema Fragmentation:Apple, Google, and Microsoft implement incompatible contact field extensions, forcing vendors to maintain 6-8 parsing pipelines and degrading sync reliability.
- Enterprise Security Review Cycles:SOC 2 Type II and ISO 27001 certification requirements extend sales cycles 4-7 months at Fortune 500 accounts, compressing cash conversion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Business Card Market |
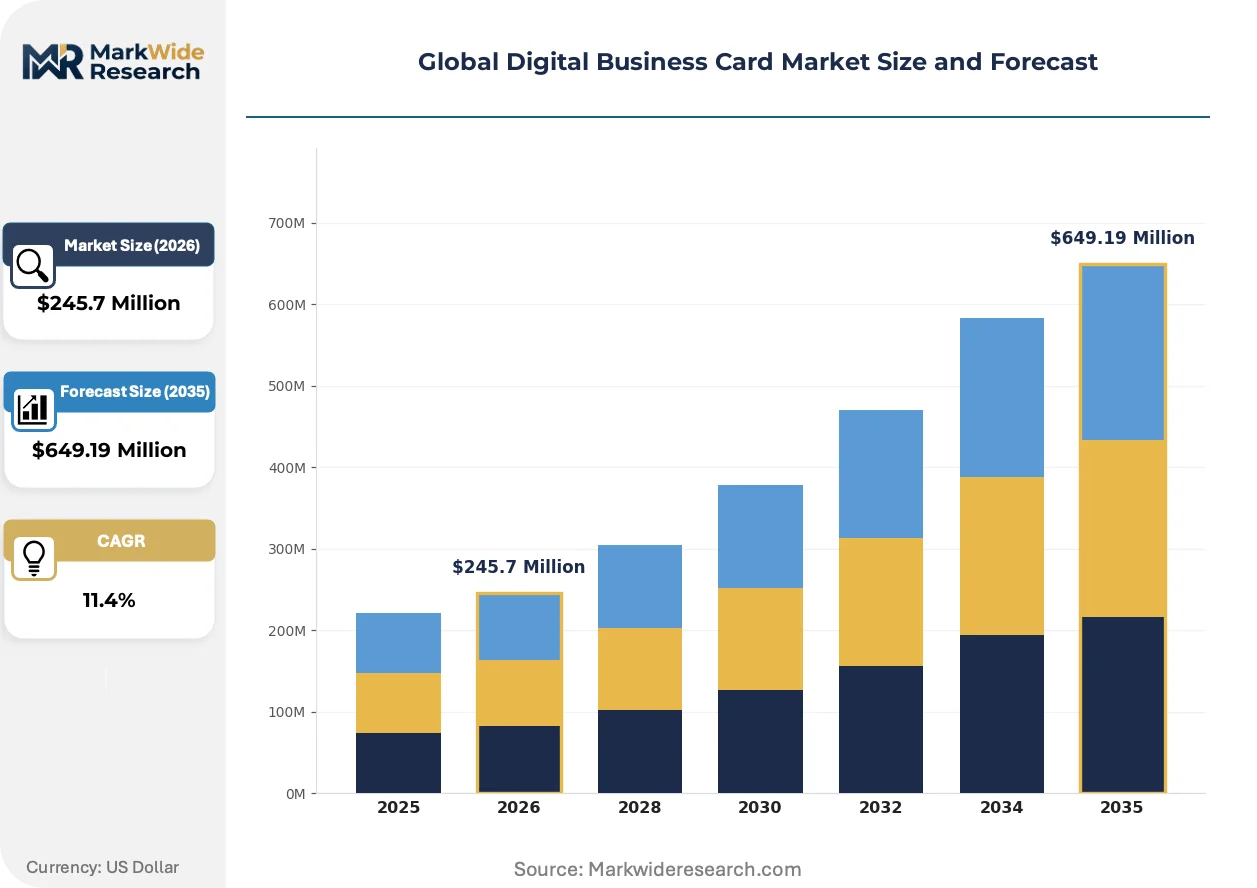
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $649.19 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near Field Communication Cards, QR Code Cards, Bluetooth Cards, Mobile App Cards, Cloud-Based Cards Deployment: Cloud, On-Premises, Hybrid, Web-Based, SaaS Application: Networking Events, Corporate Branding, Client Management, Contact Sharing, Business Promotion End User: Startups, Freelancers, Consultants, SMEs, Corporate Enterprises |
| Companies Covered | Popl Inc., Sansan, HiHello Inc., Inigo, Haystack, Mobilo Inc., Blinq Technologies, Switchit, CamCard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Business Card Market Shifts & Advancements
Platform architectures are bifurcating between hardware-anchored NFC experiences and pure SaaS delivery, with the boundary between them dissolving through embedded SIM and eSIM technologies.
Dynamic QR codes with embedded analytics tokens are supplanting static vCard downloads in mid-market deployments. SaaS vendors serving freelance consultants and boutique agencies have adopted these as default delivery mechanisms, compressing time-to-value from days to minutes while sacrificing the tactile ritual that NFC preserves for executive buyers.
EU AI Act Article 52 mandates disclosure of automated decision-making in profiling systems, directly affecting digital business card platforms with AI-powered lead scoring. Vendors deploying predictive engagement ranking must now surface algorithmic logic to end-users, imposing frontend engineering costs and favoring European providers with pre-built transparency interfaces.
Enterprise procurement teams now unbundle contact exchange from CRM licensing, treating digital business cards as standalone SaaS categories with dedicated budget lines. This shift concentrates buying authority in IT security functions rather than sales operations, elevating vendor evaluation criteria around data residency and encryption standards above feature breadth.
Global Digital Business Card Market Segmentation
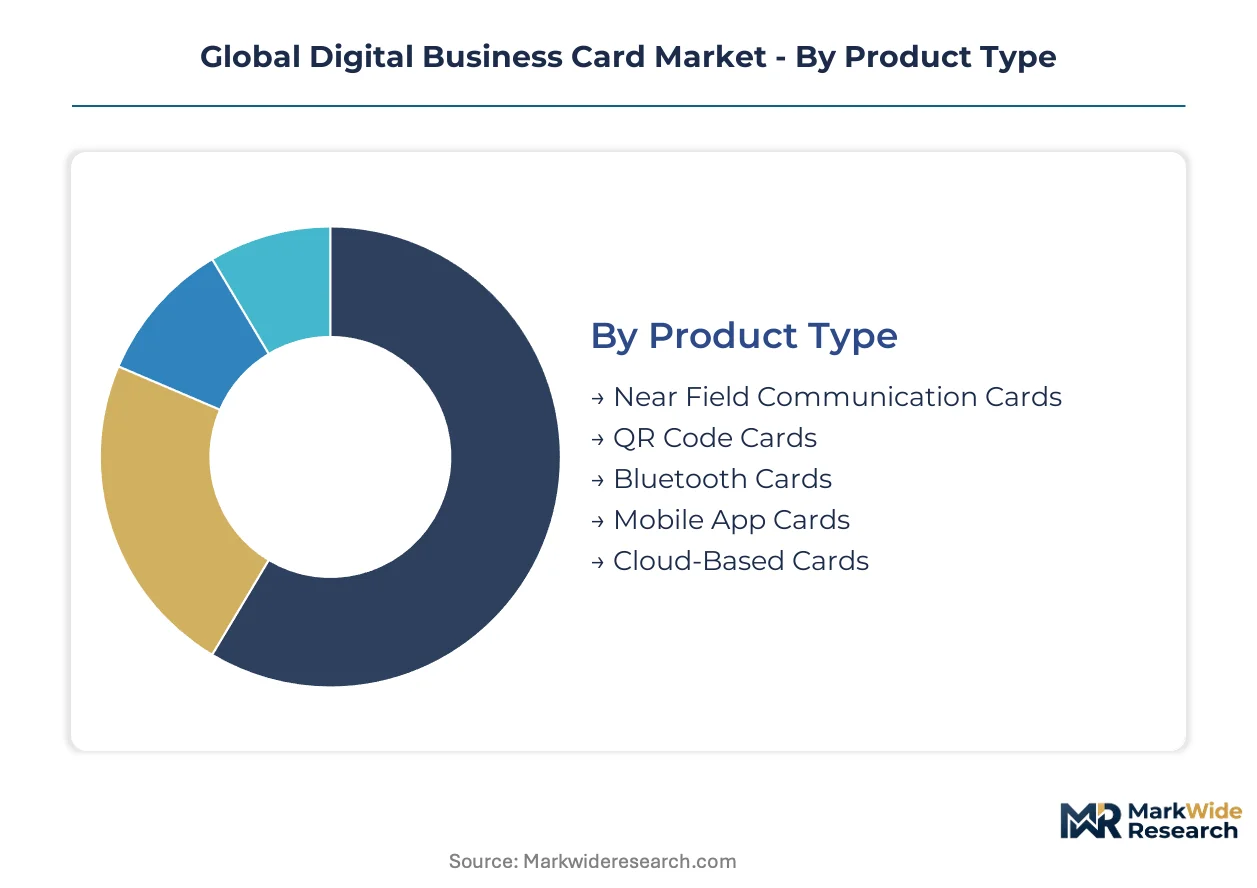
Segmentation in the digital business card market reveals how technology choices and deployment models map to distinct buyer risk tolerances and integration requirements. Product type and deployment architecture determine whether vendors compete on hardware margins or recurring software revenue.
Product Type:
NFC cards concentrate manufacturing in Taiwanese semiconductor fabs and Japanese precision component suppliers, while QR code and mobile-first alternatives scale through domestic software development centers across India, Poland, and the United States.
- Near Field Communication Cards:Embedded NFC chips transmit vCard data through 13.56 MHz radio frequency protocols with tap-to-exchange latency under 200 milliseconds. German automotive suppliers and Japanese financial institutions dominate procurement, driven by tactile ritual persistence in executive relationship-building contexts. FCC Part 15 certification timelines extend hardware launch cycles.
- QR Code Cards:Dynamic matrix barcodes encode profile URLs with embedded analytics tokens for engagement tracking. Freelancers in the United States and consultants in the United Kingdom adopt these for zero-hardware onboarding speed, though dense urban RF interference in Manhattan and Tokyo forces fallback reliance that degrades premium positioning.
- Bluetooth Cards:BLE beacons broadcast encrypted identifiers to paired devices within 10-meter ranges. Battery life constraints and cross-platform pairing friction limit commercial traction.
- Mobile App Cards:Native iOS and Android applications host cloud-synced profiles with real-time update capability. India's SME formalization wave drives volume through low-friction distribution.
- Cloud-Based Cards:Browser-accessible profiles eliminate app installation requirements. GDPR Article 17 right-to-erasure compliance becomes the primary procurement filter in European deployments.
NFC cards command the established base. The steepest expansion runs through mobile app cards.
Deployment:
Cost tier stratification separates enterprise-grade security investments from self-serve subscription tiers, with hybrid architectures capturing mid-market buyers seeking data residency control without full infrastructure ownership.
- Cloud:Multi-tenant SaaS delivery with automatic scaling and API-first integration architectures. Salesforce and HubSpot native sync requirements pull this model into Fortune 500 procurement pipelines, though SOC 2 Type II certification extends sales cycles.
- On-Premises:Single-tenant installations behind customer firewall perimeters with dedicated database instances. German automotive suppliers and French pharmaceutical manufacturers mandate this for GDPR data residency and HIPAA-adjacent healthcare credentialing use cases.
- Hybrid:Edge caching of profile data with cloud-hosted management planes. Japanese corporations with distributed sales forces favor this for latency performance across metropolitan and rural territories.
- Web-Based:Browser-rendered profiles without native application dependencies. Consultants and boutique agencies in the United States and United Kingdom prioritize speed-to-deployment over feature depth.
- SaaS:Subscription licensing with tiered feature gates and usage-based scaling. IT department centralization of vendor management elevates security review criteria above sales operations feature requests.
Cloud deployments capture volume leadership. Hybrid architectures gain share fastest among regulated verticals.
Application:
Customer type differentiation separates transactional contact exchange from sustained relationship management workflows, with corporate branding applications commanding annual contract values multiple times standard networking use cases.
- Networking Events:Temporary activation licenses for trade shows and conferences with lead capture analytics. Event organizers in the United States and Germany bundle these into sponsorship packages, with EU AI Act Article 52 disclosure requirements affecting AI-powered engagement scoring features.
- Corporate Branding:Custom-designed card templates with locked visual identity standards and administrative governance controls. Pharmaceutical and professional services sectors in Switzerland and the United Kingdom drive premium pricing through compliance-adjacent credentialing needs.
- Client Management:CRM-integrated contact synchronization with pipeline stage tracking. Salesforce API ecosystem native treatment of contact exchange as first-class data objects accelerates procurement velocity.
- Contact Sharing:Basic profile transmission without analytics or automation hooks. Individual freelancers and startup founders in India and Brazil populate this entry tier.
- Business Promotion:Embedded multimedia content and call-to-action buttons driving traffic to owned properties. Marketing agencies in Australia and Canada experiment with these for campaign attribution.
Corporate branding anchors premium revenue. Client management applications expand most quickly through CRM ecosystem integration.
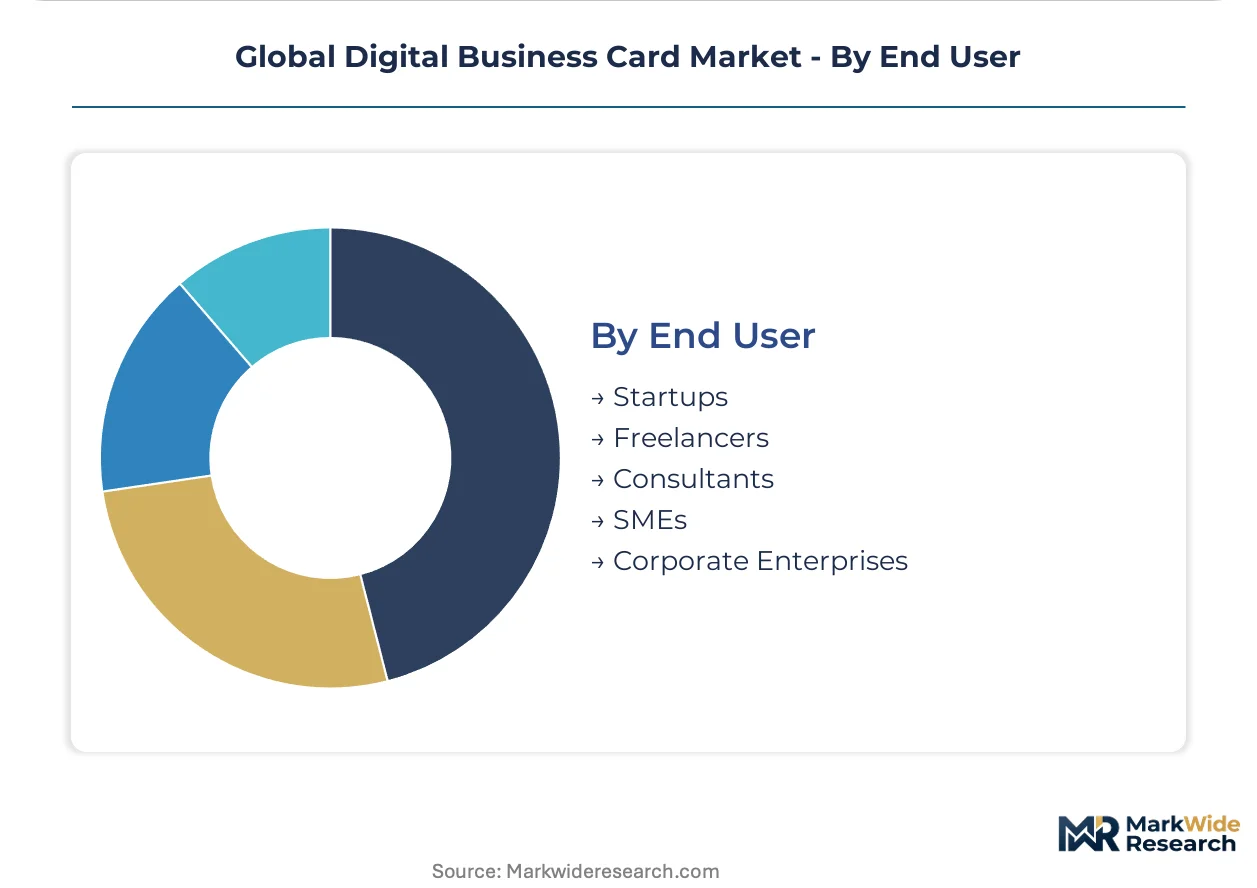
End User:
Volume-maturity tradeoffs concentrate platform engineering investment toward enterprise API requirements while viral acquisition mechanics target individual professionals for organic growth foundation.
- Corporate Enterprises:Bulk licensing agreements with SSO integration, custom SLA terms, and dedicated customer success coverage. Annual contract values run 3-4x standard tiers due to security review and compliance documentation requirements.
- SMEs:Department-level purchases with centralized billing and moderate customization needs. India's electronics manufacturing PLI scheme reduces landed NFC card costs for domestic SaaS vendors serving this segment.
- Freelancers:Individual subscription tiers with self-service onboarding and community support channels. Freemium conversion mechanics sustain viral loops that populate platform network effects.
- Consultants:Boutique professional services buyers prioritizing brand differentiation and referral tracking. HIPAA-compliant credentialing for pharmaceutical rep hospital access represents unserved vertical expansion potential.
- Startups:Founding team bundles with equity-sensitive pricing and rapid scaling terms. Y Combinator and Techstars portfolio companies in the United States drive concentrated early-stage adoption patterns.
Corporate enterprises dominate revenue concentration. Freelancers populate the fastest-climbing user acquisition trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, Japan, and the United States consume digital business cards through fundamentally different deployment architectures, with German automotive suppliers mandating on-premises installations while Japanese financial institutions favor hybrid edge-caching and US SaaS vendors push pure cloud delivery.
United States
Salesforce and HubSpot API ecosystems drive enterprise procurement velocity for cloud-native digital card platforms. FCC Part 15 certification timelines for custom NFC antenna designs extend hardware launch cycles 8-14 months. Manhattan's dense RF environment degrades Bluetooth LE reliability, forcing QR code fallbacks that compress perceived premium value.
Germany
GDPR Article 17 right-to-erasure mandates accelerate procurement of platforms with automated data deletion workflows among automotive suppliers. BSI technical standards and KBA regulatory frameworks shape data residency requirements. Stuttgart and Munich industrial clusters concentrate pharmaceutical and automotive procurement authority for HIPAA-adjacent credentialing use cases.
Japan
METI industrial policy supports NFC hardware miniaturization below 2mm² at domestic semiconductor fabs, enabling jewelry and wearable embeddability. JIS standards govern digital identity interoperability. Tokyo and Osaka financial institutions anchor recurring revenue through large account deployments with tactile ritual persistence in executive networking.
India
PLI scheme incentives for electronics manufacturing create localized NFC card production capacity, cutting landed costs for domestic SaaS vendors by 40-60%. TRAI digital infrastructure guidelines accelerate SME formalization. Bangalore and Hyderabad technology corridors populate fastest-climbing user acquisition trajectories through mobile-first distribution.
United Kingdom
Consultants in London and boutique agencies prioritize brand differentiation and referral tracking through web-based deployment speed. Information Commissioner's Office enforcement patterns elevate vendor evaluation criteria around encryption standards. Canary Wharf financial services clusters unbundle contact exchange from CRM licensing into standalone SaaS budget lines.
Global Digital Business Card Market Competitive Landscape
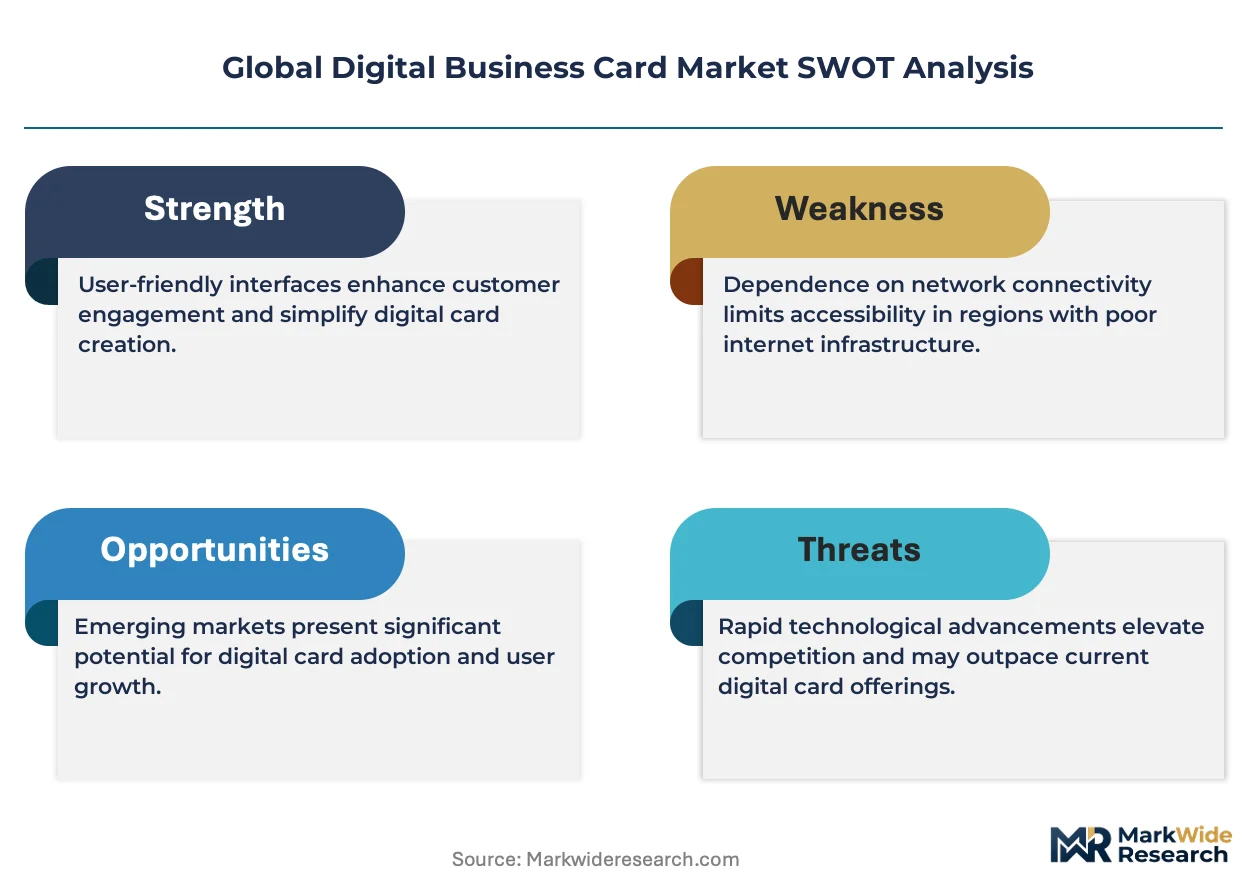
A small set of integrated leaders sits above a broader specialist tier, with enterprise-grade platforms commanding annual contract values 3-4x standard tiers through SSO integration and custom SLA terms. The middle layer fragments across freemium-to-enterprise conversion mechanics, hardware-anchored NFC experiences, and lead-capture functional niches. Two dominant competitive moves reshape positioning: native CRM ecosystem integration that eliminates middleware dependencies, and privacy-first architecture rebuilds that satisfy EU AI Act Article 52 disclosure mandates for automated decision-making transparency.
Within the enterprise-anchored tier, Sansan exemplifies recurring revenue concentration through large account deployments, while HiHello Inc. occupies a position defined by viral user acquisition loops and freemium conversion mechanics. Mobilo Inc. represents the functional specialist archetype, embedding lead capture forms directly into NFC tap flows to bridge contact exchange and pipeline generation. These three patterns—enterprise footprint, viral growth mechanics, and workflow integration—illustrate how platform differentiation crystallizes across buyer segments.
| Leading Market Players |
|---|
| Popl Inc. |
| Sansan |
| HiHello Inc. |
| Inigo |
| Haystack |
| Mobilo Inc. |
| Blinq Technologies |
| Switchit |
| CamCard |
| Others |
Supply & Pricing Matrix
QR code substitution for NFC hardware is compressing landed costs for SaaS vendors while redistributing manufacturing gravity toward Indian electronics clusters and Polish software development centers. This displacement simultaneously erodes premium pricing power for tactile card producers and opens margin expansion for cloud-native platforms.
Pricing Analysis
Long-term enterprise offtake agreements dominate corporate procurement, with annual subscriptions locking in 3-4x standard tier pricing through SSO integration and custom SLA terms. Price differentiation hinges on ISO 27001 certification status and data residency control levels, with German automotive buyers paying premiums for on-premises deployment. Cost compression in the freelancer tier is intensifying because Indian PLI scheme subsidies cut NFC card production costs by 40-60%. Individual consultants exhibit highest price sensitivity, while Fortune 500 IT security functions prioritize compliance documentation over feature breadth.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes NFC controller chip supply, with over 80% fabrication concentrated at Taiwanese foundries. Semiconductor wafers, precision antenna components, and embedded firmware draw from Japan, South Korea, and domestic Indian assembly under PLI incentives. Single-source vulnerability at the controller level creates disruption exposure from geopolitical friction. Distribution runs through direct enterprise sales for large accounts and self-serve SaaS portals for individual tier acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act Article 52 disclosure mandates are accelerating platform architecture rebuilds, creating a regulatory inflection that favors privacy-first vendors with pre-built transparency interfaces over feature-heavy incumbents.
For Market Incumbents: Fortify enterprise moats through native Salesforce and HubSpot API integration that eliminates middleware dependencies. Pursue backward integration into NFC semiconductor sourcing to mitigate Taiwan Strait exposure. Certification investment in SOC 2 Type II and ISO 27001 defends against emerging pure-SaaS competitors with faster security review cycles. For New Entrants and Emerging Players: GDPR Article 17 compliance fast-tracks unlock German automotive and French pharmaceutical procurement pipelines currently underserved by US-centric platforms. Healthcare-adjacent credentialing for pharmaceutical rep hospital access represents the most penetrable vertical, with annual contract values 3-4x standard enterprise tiers. Channel partnership with event management platforms accelerates temporary activation license traction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with native CRM ecosystem integration and automated data deletion workflows. Long-term viability over a 5-10 year window rests on vertical integration into privacy-first architecture rather than hardware margin capture. Watch ISO standards for digital identity interoperability crystallization as the signal for procurement eligibility shifts in regulated industries.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-First Architecture Rebuild | EU AI Act Article 52 compliance opens German automotive procurement pipelines. |
| Native CRM Ecosystem Integration | Salesforce API first-class contact objects eliminate middleware dependencies for enterprise buyers. |
| Healthcare Credentialing Expansion | HIPAA-compliant digital cards access pharmaceutical rep hospital zones with 3-4x contract values. |
| NFC Hardware Miniaturization | METI-supported Japanese fabs enable jewelry and wearable embeddability for executive segments. |
| Indian Manufacturing Localization | PLI scheme subsidies cut landed costs 40-60% for domestic SaaS vendor competitive positioning. |
Research Methodology
A standing panel of SaaS platform CTOs, enterprise IT procurement officers, NFC hardware engineering leads, and CRM integration specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, FCC Part 15 equipment authorization databases, EU AI Act regulatory text, and METI industrial policy announcements. Bottom-up deployment model sizing and top-down addressable market triangulation anchored volume estimates.
Consistency checks against external benchmarks validated cloud-native versus hardware-anchored platform revenue splits across the projection horizon. Segmentation modeling covered product type, deployment architecture, application use case, and end-user organization size. CAGRs derived from historical adoption curve analysis and CRM ecosystem penetration rates. Industry-specific inputs included GDPR enforcement pattern data and PLI scheme utilization rates.
Underlying assumptions cover sustained EU AI Act enforcement intensity and Taiwan semiconductor supply continuity, with deviation risk concentrated in geopolitical disruption and ISO standard crystallization timing. Practitioners should keep alternative scenarios live as regulatory disclosure requirements and hardware supply geography evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Master Data Management Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Dataops Platform Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Data Broker Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Global Corporate Volunteering Platform Market