
 Social Computing Market | 2026-2036
Social Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Social Computing Market Analysis
Generative AI integration into social platforms is rewriting how user interfaces, content moderation, and recommendation engines are architected. Microsoft leverages its Azure cloud backbone to embed AI copilots across enterprise collaboration suites. Meta Platforms anchors consumer social networking through heavy investment in mixed-reality interfaces and AI-driven feed algorithms. Salesforce differentiates by weaving social listening tools directly into customer relationship management workflows for B2B clients.
Social computing encompasses the design, deployment, and operation of networked digital environments that enable collective interaction, content co-creation, and relationship formation across distributed user bases, typically requiring sub-100 millisecond latency for real-time responsiveness and elastic scaling to millions of concurrent sessions. Its primary commercial purpose is to convert attention and behavioral data into monetizable engagement through advertising, subscription, or transaction models. Cloud-based deployment leads infrastructure spending as enterprises prioritize elastic capacity over fixed data center commitments. AI integration represents the fastest-expanding technology layer, attracting disproportionate R&D allocation as platforms compete on personalization precision. Collaboration tools command the strongest margin pools in the B2B channel, where annual contract values and switching costs exceed consumer equivalents.
The EU AI Act imposes transparency obligations on algorithmic recommendation systems, while the FDA and FCC in the United States respectively scrutinize digital therapeutics delivered through social platforms and spectrum allocation for mobile social applications. China's SAMR enforces antitrust and data localization rules that constrain cross-border platform operations. ISO standards for information security management shape enterprise procurement checklists across all three jurisdictions. Stakeholders must monitor how divergent regulatory timelines for AI governance create compliance fragmentation that favors regionally specialized platform providers over uniform global rollouts.
Market Dynamics
Generative AI copilots are compressing feature development cycles across enterprise collaboration suites, forcing platform providers to rearchitect recommendation engines and content moderation pipelines around real-time inference workloads rather than batch-processed analytics.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements are accelerating procurement of explainable AI tooling by European enterprises, creating upgrade cycles for compliance-ready platforms.
- Hybrid work stabilization:Persistent distributed workforce models are sustaining demand for synchronous collaboration infrastructure with sub-100 millisecond latency guarantees.
- Edge computing densification:Micro-datacenter deployment across Germany, the United States, and China is reducing round-trip latency for real-time social computing workloads.
Market Restraints
- GPU supply concentration:Training and inference hardware dependencies on Taiwan-based foundry capacity create procurement bottlenecks for AI-enabled platform features.
- Data localization requirements:China's SAMR cross-border transfer rules fragment user data architectures, raising operational complexity for multinational platform operators.
- Energy cost volatility:European electricity price spikes are compressing margins for cloud-hosted inference services with 24/7 availability requirements.
Strategic Opportunities
- Digital therapeutics integration:FDA's expanding oversight of software-as-medical-device creates white space for clinically validated social platforms in mental health and chronic disease management.
- Industrial metaverse convergence:Mixed-reality interfaces combined with digital twin architectures are opening manufacturing and logistics training applications previously served by physical simulation.
- Smallholder agriculture connectivity:Underpenetrated rural markets in India present channel innovation potential through mobile-first cooperative platforms with offline synchronization.
Industry Challenges
- MLops talent scarcity:Pipeline engineering and model governance expertise remains concentrated at hyperscaler employers, constraining mid-tier platform development velocity.
- Legacy system integration:Enterprise clients demand bidirectional synchronization with decades-old ERP and CRM databases, extending implementation timelines.
- Cross-jurisdictional certification:ISO 27001, SOC 2 Type II, and sector-specific healthcare or financial services audits impose overlapping compliance burdens without mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Computing Market |
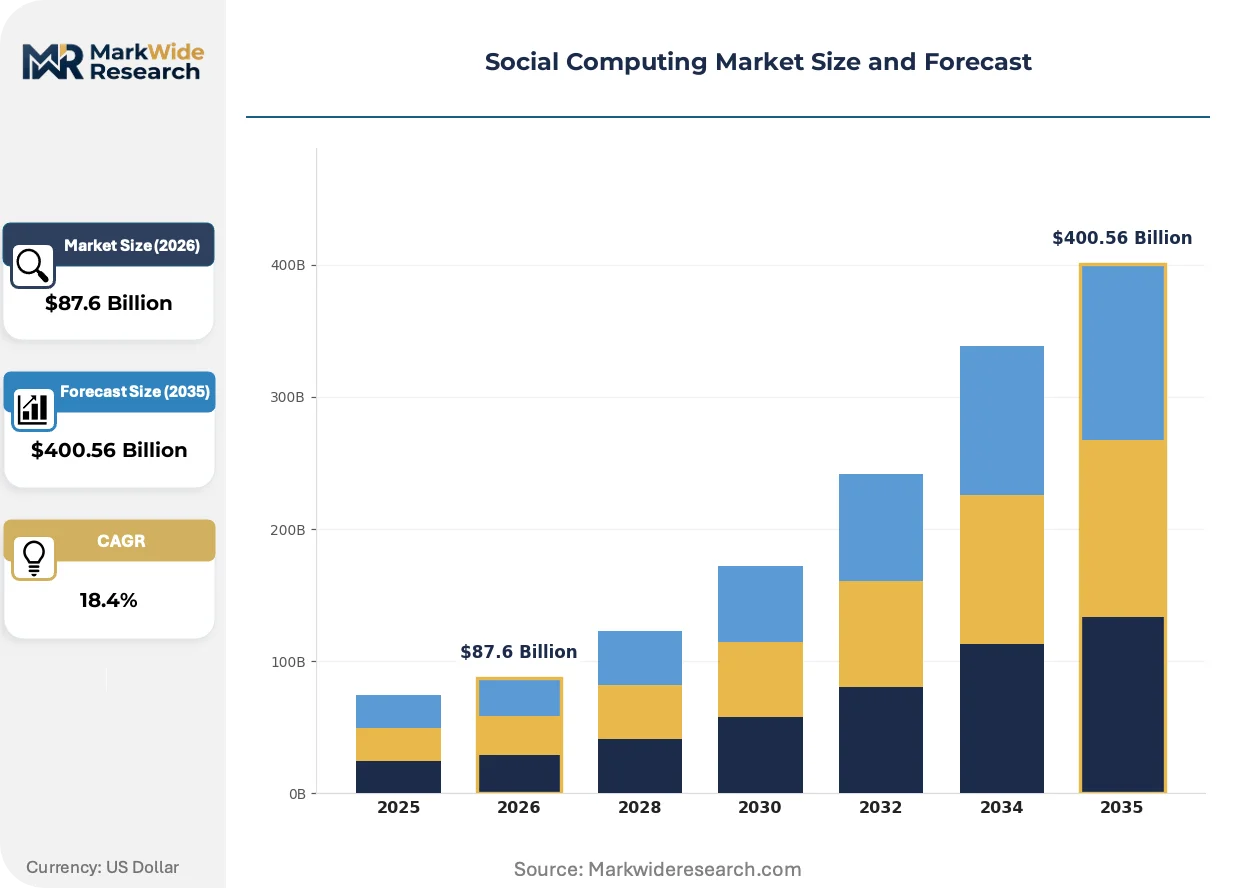
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
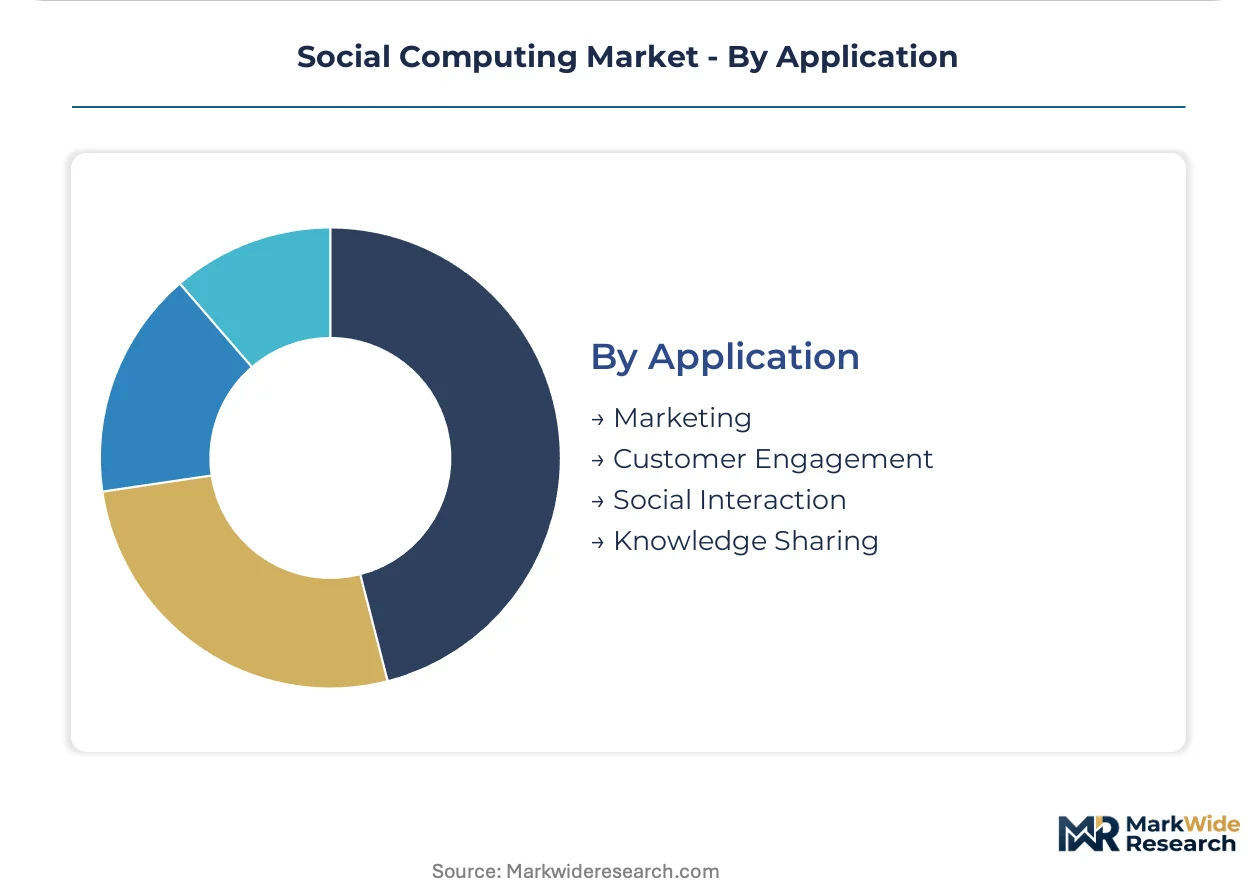
| Segmentation | Product Type: Social Networking, Online Communities, Collaboration Tools, Gaming Platforms Technology: Cloud-Based, Mobile Apps, AI Integration, Data Analytics User Type: Individuals, Businesses, Educational Institutions, Non-Profits Application: Marketing, Customer Engagement, Social Interaction, Knowledge Sharing |
| Companies Covered | Apple, Salesforce, Meta Platforms, SAP, IBM, Alphabet, Oracle, Tencent, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Computing Market Emerging Trajectories
Foundation model integration is restructuring competitive advantage around inference cost efficiency and personalization precision rather than raw user scale or network effects alone.
Retrieval-augmented generation architectures are rendering obsolete static knowledge bases and rule-based chatbot implementations across customer service and internal helpdesk functions. Mid-market enterprises with 500-5,000 employees are adopting these systems fastest, compressing vendor selection cycles from 18 months to 90 days. The structural consequence is collapsing margins for legacy conversational AI providers unable to embed live document retrieval.
The EU AI Act's risk classification framework is forcing platform operators to maintain audit trails for high-risk recommendation systems, including content ranking and friend suggestion algorithms. Industrial consequence includes mandatory human-in-the-loop review processes and third-party conformity assessments before deployment. Consumer social networking platforms with EU user bases exceeding 45 million are restructuring product development workflows to embed compliance checkpoints at the design stage.
Enterprise buyers are consolidating vendor relationships around integrated suites rather than best-of-breed point solutions, compressing the addressable market for standalone video conferencing or task management tools. IT procurement teams at Fortune 500 manufacturers are replacing three to five discrete subscriptions with single-platform contracts spanning messaging, document collaboration, and workflow automation. This concentration is most visible in the United States and Germany, where CIO mandates prioritize interoperability over specialized functionality.
Social Computing Market Segmentation
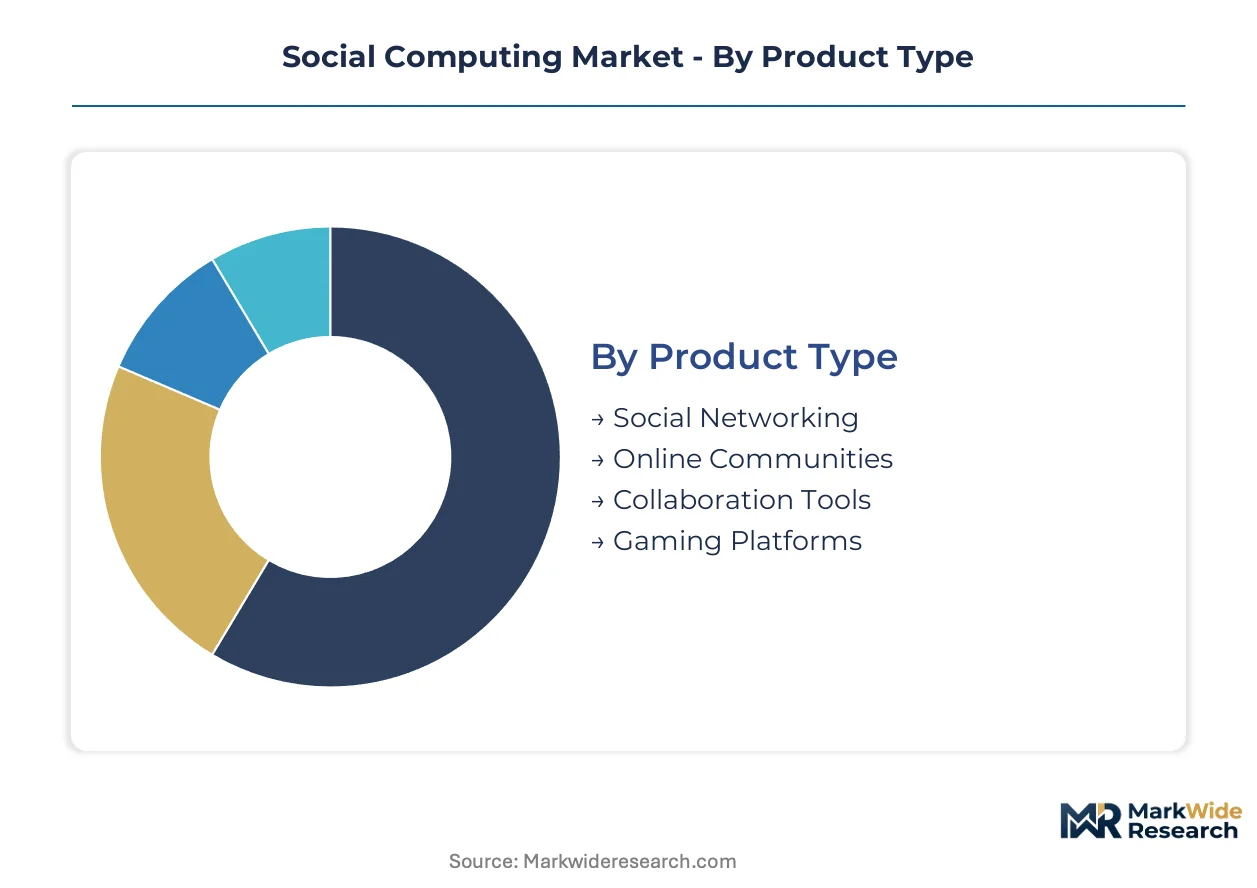
Segmentation in social computing reveals how infrastructure choices, user workflows, and regulatory exposure create divergent margin structures across product categories. Understanding these fault lines helps vendors allocate R&D resources and identify which technology layers command pricing power.
Product Type:
Mature enterprise collaboration suites coexist with emerging mixed-reality interfaces, creating a bifurcated investment landscape where incumbents defend installed base while challengers bet on immersive hardware cycles.
- Social Networking:Consumer-facing platforms monetize through advertising auctions and behavioral data licensing, with Meta Platforms and ByteDance setting the latency and personalization benchmarks that constrain competitor architectures. Regulatory pressure from the EU AI Act and China's SAMR is forcing algorithmic transparency investments that compress margins for second-tier operators.
- Online Communities:Niche interest aggregation platforms with governance token mechanisms and creator revenue splits are gaining traction in developer tools, wellness, and financial education verticals. Demand concentrates in Germany and the United States where subscription tolerance exceeds emerging market equivalents.
- Collaboration Tools:Enterprise synchronous and asynchronous work suites with SLA-backed latency guarantees.
- Gaming Platforms:Social worlds with user-generated content economies and live service monetization.
Collaboration tools handle the majority of throughput; gaming platforms are expanding most quickly on share as mixed-reality hardware penetration accelerates.
Technology:
Cost tier segmentation separates capital-intensive infrastructure plays from lightweight application layers, with cloud hyperscalers capturing value upstream of specialized tooling vendors.
- Cloud-Based:Elastic compute and storage architectures delivered through AWS, Azure, or GCP contracts with reserved instance pricing and egress fee structures that lock in multi-year commitments. European enterprises under CSRD reporting mandates are prioritizing carbon-aware region selection, reshaping procurement criteria beyond raw cost per compute hour.
- Mobile Apps:Native iOS and Android applications with offline synchronization, push notification orchestration, and app store commission exposure. India's rural connectivity gaps are driving demand for lightweight APKs with progressive web app fallbacks and mesh networking protocols.
- AI Integration:Foundation model embeddings for content generation, moderation, and recommendation with inference cost optimization.
- Data Analytics:Behavioral telemetry pipelines and real-time dashboards for engagement optimization.
Cloud-based deployments dominate current infrastructure spend; AI integration is gaining share fastest as inference costs decline and personalization precision becomes the primary competitive differentiator.
User Type:
Customer type segmentation maps to contract value and switching cost heterogeneity, with institutional buyers demanding compliance certifications that consumer segments ignore.
- Individuals:Ad-supported or freemium personal accounts with minimal data portability and high churn tolerance. Privacy-conscious segments in Germany and California are migrating toward subscription models that eliminate behavioral tracking, fragmenting monetization architectures.
- Businesses:Enterprise licenses with SSO integration, audit logging, and custom data retention policies. Fortune 500 manufacturers in the United States are consolidating vendor relationships around integrated suites, compressing the addressable market for standalone point solutions.
- Educational Institutions:Federated identity deployments with FERPA compliance and classroom management integrations.
- Non-Profits:Discounted or donated licenses with grant-funded implementation support and volunteer onboarding workflows.
Businesses contribute the majority of recurring revenue; educational institutions are climbing the fastest on share as hybrid learning infrastructure becomes permanent.
Application:
Application segmentation tracks how social computing migrates from attention monetization toward outcome-based pricing models in regulated verticals.
- Marketing:Influencer campaign management, social listening, and programmatic ad buying with attribution modeling. B2B software vendors in the United States are shifting spend toward first-party data activation as third-party cookie deprecation forces channel mix reallocation.
- Customer Engagement:Support ticket deflection, community-driven troubleshooting, and loyalty program integration. European banks under DORA operational resilience requirements are scrutinizing vendor redundancy architectures before contract renewal.
- Social Interaction:Peer-to-peer messaging, interest-based matching, and event coordination with end-to-end encryption.
- Knowledge Sharing:Enterprise wikis, expert identification systems, and structured documentation repositories.
Marketing applications handle the majority of platform transaction volume; customer engagement is gaining share fastest as subscription businesses prioritize retention economics over acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States, Germany, and China drive the majority of platform infrastructure investment, with compliance mandates and hybrid work stabilization reshaping regional demand patterns.
United States
Fortune 500 manufacturers consolidate vendor relationships around integrated collaboration suites, prioritizing SSO integration and audit logging capabilities. The FDA scrutinizes digital therapeutics delivered through social platforms, creating compliance checkpoints for health-adjacent applications. Silicon Valley and Seattle metro areas concentrate hyperscaler engineering talent and venture deployment for AI-enabled platform features.
Germany
Industrial conglomerates demand sub-100 millisecond latency guarantees for synchronous collaboration tools serving distributed engineering teams. The EU AI Act imposes transparency obligations on algorithmic recommendation systems, forcing audit trail investments. Munich and Stuttgart clusters anchor enterprise software procurement decisions for automotive and machinery verticals.
China
Mobile-first user bases and super-app integration drive platform architecture decisions toward lightweight APKs with progressive web app fallbacks. SAMR enforces antitrust and data localization rules that fragment cross-border user data architectures. Beijing and Shenzhen metros concentrate mixed-reality hardware development and AI inference optimization engineering.
India
Rural connectivity gaps propel demand for offline-synchronization capabilities and mesh networking protocols in agricultural cooperative platforms. TRAI spectrum allocation decisions shape mobile social application performance benchmarks. Bangalore and Hyderabad clusters host engineering centers for global platform providers seeking cost-optimized development velocity.
Japan
Enterprise buyers prioritize interoperability certifications and legacy ERP synchronization for collaboration tool procurement. METI industrial policy encourages digital twin and metaverse convergence for manufacturing training applications. Tokyo and Osaka metros concentrate R&D investment for human-in-the-loop AI review processes.
Social Computing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where hyperscaler cloud backbones anchor the upstream layer and application-layer vendors compete on workflow integration depth. The market exhibits consolidation pressure as enterprise buyers reduce vendor counts from five to one integrated suite. Three archetypes dominate: cloud infrastructure owners embedding AI copilots, enterprise software incumbents weaving social listening into CRM workflows, and consumer platforms investing in mixed-reality interfaces. Competitive moves center on M&A for talent acquisition in MLOps pipeline engineering and strategic partnerships for edge computing densification.
Within the cloud infrastructure tier, Microsoft and Alphabet occupy positions defined by elastic compute ownership and foundation model access. Salesforce exemplifies the enterprise application archetype through CRM-integrated social listening positioning. Meta Platforms anchors consumer-facing network effects with heavy allocation toward immersive hardware cycles and feed algorithm development. Tencent represents the super-app consolidation model with embedded mini-program ecosystems spanning messaging, payments, and content distribution.
| Leading Market Players |
|---|
| Apple |
| Salesforce |
| Meta Platforms |
| SAP |
| IBM |
| Alphabet |
| Oracle |
| Tencent |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
GPU supply concentration in Taiwan-based foundry capacity creates procurement bottlenecks that compress margins for AI-enabled platform features while simultaneously widening pricing spreads between latency-guaranteed enterprise tiers and consumer-grade alternatives.
Pricing Analysis
Cost-plus contracts with GPU spot-price indexation dominate infrastructure procurement for cloud-hosted inference services. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 manufacturers demanding sub-100 millisecond SLA guarantees from mid-market enterprises with relaxed latency requirements. Pricing pressure stems from European electricity cost volatility eroding margins for 24/7 availability commitments. Educational institutions exhibit highest price sensitivity due to grant-funded budget constraints, while industrial conglomerates in Germany demonstrate lowest sensitivity when procurement criteria prioritize compliance certification over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from hyperscaler cloud providers are squeezing mid-tier platform vendors with weaker balance sheets. Hardware dependencies concentrate in Taiwan, South Korea, and the United States for GPU and specialized AI accelerators. Software layer inputs draw from open-source foundation model repositories and proprietary training datasets. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct enterprise sales teams for large accounts and self-serve digital channels for individual and small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MLOps pipeline engineering expertise remains anchored at hyperscaler employers, constraining development velocity for mid-tier platform providers and fragmenting competitive positioning across capability tiers.
For Market Incumbents: Pre-empt margin erosion in enterprise collaboration suites by embedding AI copilots across workflow automation layers before challenger platforms achieve feature parity. Acquire specialist firms with ISO 27001 certification infrastructure to accelerate compliance-ready positioning for EU AI Act mandates. Consolidate channel relationships through reserved instance pricing and egress fee structures that extend multi-year cloud commitments. For New Entrants and Emerging Players: Agricultural cooperative platforms with offline synchronization capabilities in rural India represent the most penetrable entry point given underdeveloped incumbent presence and TRAI spectrum decisions favoring mesh networking protocols. Digital therapeutics applications under FDA software-as-medical-device pathways offer white space with outcome-based pricing models. Partner with regional system integrators possessing existing hospital procurement relationships to bypass direct enterprise sales infrastructure requirements. For Investors and Strategic Acquirers: Edge computing densification specialists with micro-datacenter deployments across Germany, the United States, and China offer acquisition targets with infrastructure assets critical to latency-sensitive workloads. Long-term viability hinges on inference cost efficiency rather than raw user scale as foundation model integration commoditizes personalization precision. Monitor GPU spot-price volatility and foundry capacity announcements as inflection indicators for platform margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding AI copilots across Microsoft Azure enterprise collaboration suites compresses competitor development cycles. |
| Acquisition of Specialist Firm | Purchasing MLOps pipeline engineering teams accelerates model governance capabilities for EU AI Act compliance. |
| Strategic Partnership | Edge computing densification agreements with micro-datacenter operators reduce round-trip latency for real-time workloads. |
| Geographic Expansion | Rural India channel development for offline-synchronized agricultural platforms captures underpenetrated cooperative demand. |
| Product Launch | FDA-validated digital therapeutics applications create clinically defensible pricing premiums in mental health verticals. |
Methodological Framework
The analysis maps enterprise collaboration suites, consumer social networking platforms, mixed-reality interfaces, and AI integration layers, each validated through primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary triangulation against SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory filings. Bottom-up sizing of individual product categories and top-down cross-checks against aggregate cloud infrastructure spend ensure methodological consistency.
Assumptions held fixed include hybrid work stabilization sustaining synchronous collaboration demand and EU AI Act transparency mandates accelerating explainable AI procurement; variables tested include GPU supply disruption scenarios and electricity cost volatility across European hosting regions. Segmentation dimensions modeled span deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from elasticity-adjusted demand curves and technology substitution rates, with inference cost decline curves and personalization precision benchmarks as industry-specific forecast inputs.
Practitioners should monitor GPU foundry capacity announcements, EU AI Act enforcement timelines, and European electricity price trajectories for early signals of margin compression or procurement acceleration. Macroeconomic deviation, regulatory enforcement intensity variation, or foundation model capability breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Smart Government Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Database Management Platform Market