
 Commercial Cleaning Service Market | 2026-2036
Commercial Cleaning Service Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Cleaning Service Market Insights
The gap between premium disinfection protocols and commodity surface wiping is realigning contract structures across the industry. Jani-King leverages its franchise network to anchor recurring revenue in multi-site commercial portfolios. ServiceMaster Clean differentiates through specialized healthcare sanitation expertise and certified technician training programs. ABM Industries controls large-scale integrated facility contracts that bundle cleaning with maintenance and security services.
Commercial cleaning services encompass scheduled sanitation, disinfection, and maintenance of non-residential buildings using EPA-registered chemicals, HEPA filtration equipment, and standardized protocols measured by ATP bioluminescence testing to verify surface hygiene levels. These operations preserve occupant health, extend asset lifecycles, and ensure regulatory compliance across high-traffic environments. Office cleaning remains the mature revenue base with thin margins, while industrial cleaning captures premium pricing due to hazardous material handling certifications and specialized equipment requirements. Eco-friendly cleaning methods are gaining fastest among educational institutions and corporate headquarters seeking LEED alignment and Scope 3 emissions reductions.
OSHA mandates exposure control plans for bloodborne pathogens, while EPA regulates antimicrobial product claims and disinfectant efficacy standards in the United States. These frameworks elevate liability for non-compliant operators and create procurement preference for certified service providers. Stakeholders must monitor evolving green chemistry regulations and building wellness certifications that will reshape supplier qualification criteria and contract renewal terms.
Market Dynamics
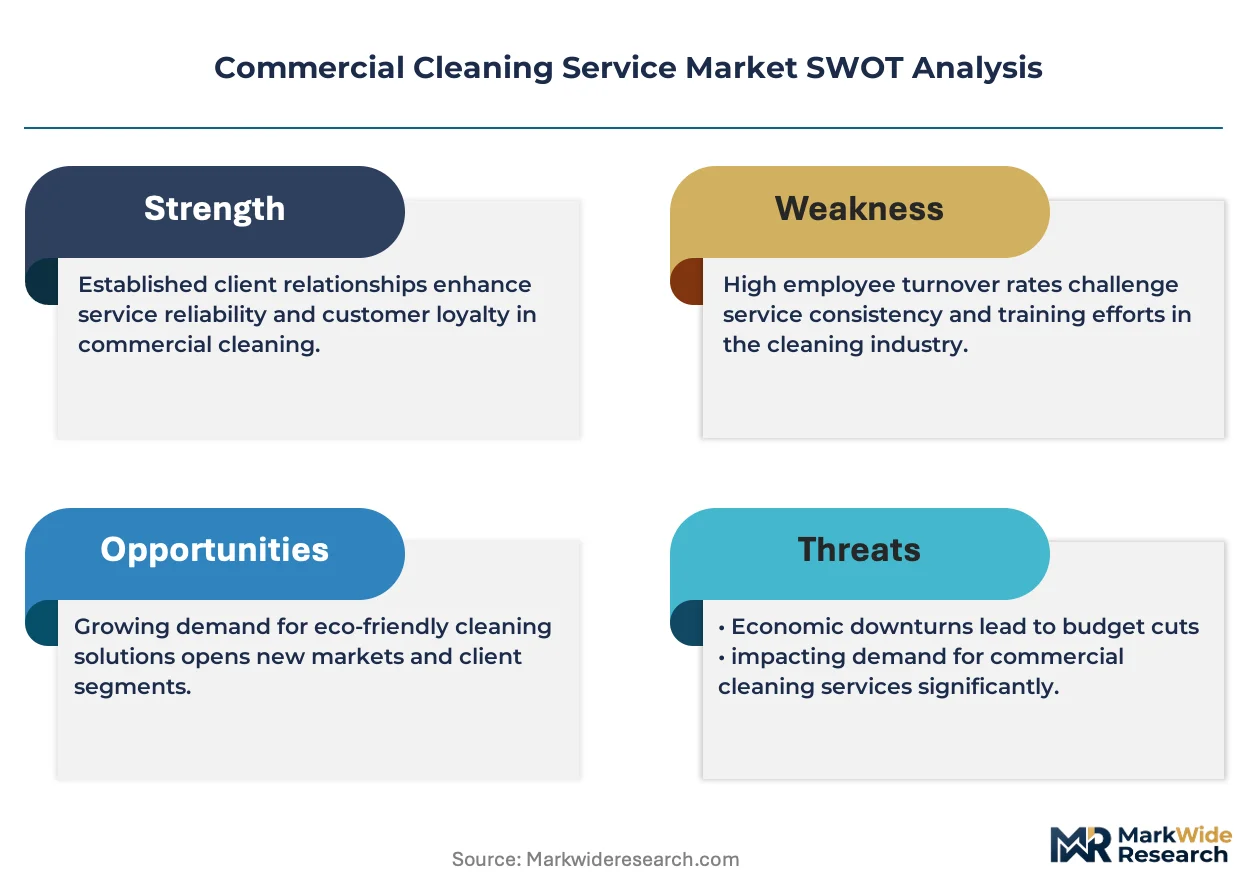
Healthcare-associated infection liability and EPA-registered disinfectant mandates are compressing contract renewal cycles toward certified providers with verifiable ATP testing protocols.
Growth Catalysts
- OSHA Bloodborne Pathogen Standards:Mandatory exposure control plans in US healthcare facilities elevate demand for certified technicians with documented training records.
- Educational Institutions:LEED alignment requirements and Scope 3 emissions targets drive adoption of green chemistry cleaning protocols across university and K-12 campuses.
- HEPA Filtration Equipment:Post-pandemic indoor air quality standards in Germany and Japan sustain capital investment in integrated HVAC-cleaning service bundles.
Market Restraints
- Labor Cost Volatility:Minimum wage compression and immigration policy friction in the United States constrain franchise operator margin stability.
- Disinfectant Supply Concentration:EPA-registered active ingredient manufacturing clusters in China create procurement vulnerability for North American service providers.
- Electrostatic Sprayer Substitution:In-house equipment purchases by large facility managers threaten recurring disinfection contract retention.
Strategic Opportunities
- Industrial Hazardous Cleaning:Specialized certifications for chemical spill response and confined space entry command premium pricing in manufacturing corridors.
- EU Green Deal Chemistry Mandates:Biodegradable surfactant requirements create first-mover advantage for reformulated product portfolios ahead of 2030 enforcement.
- Sensor-Enabled Verification:IoT-enabled ATP monitoring systems allow real-time hygiene dashboards that lock in multi-year enterprise contracts.
Industry Challenges
- Technician Certification Backlogs:OSHA 10-hour and bloodborne pathogen credentialing delays constrain workforce scaling for rapid contract onboarding.
- Legacy Equipment Integration:Robotic floor scrubber deployment requires retrofitting existing client facilities with charging infrastructure and route mapping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Cleaning Service Market |
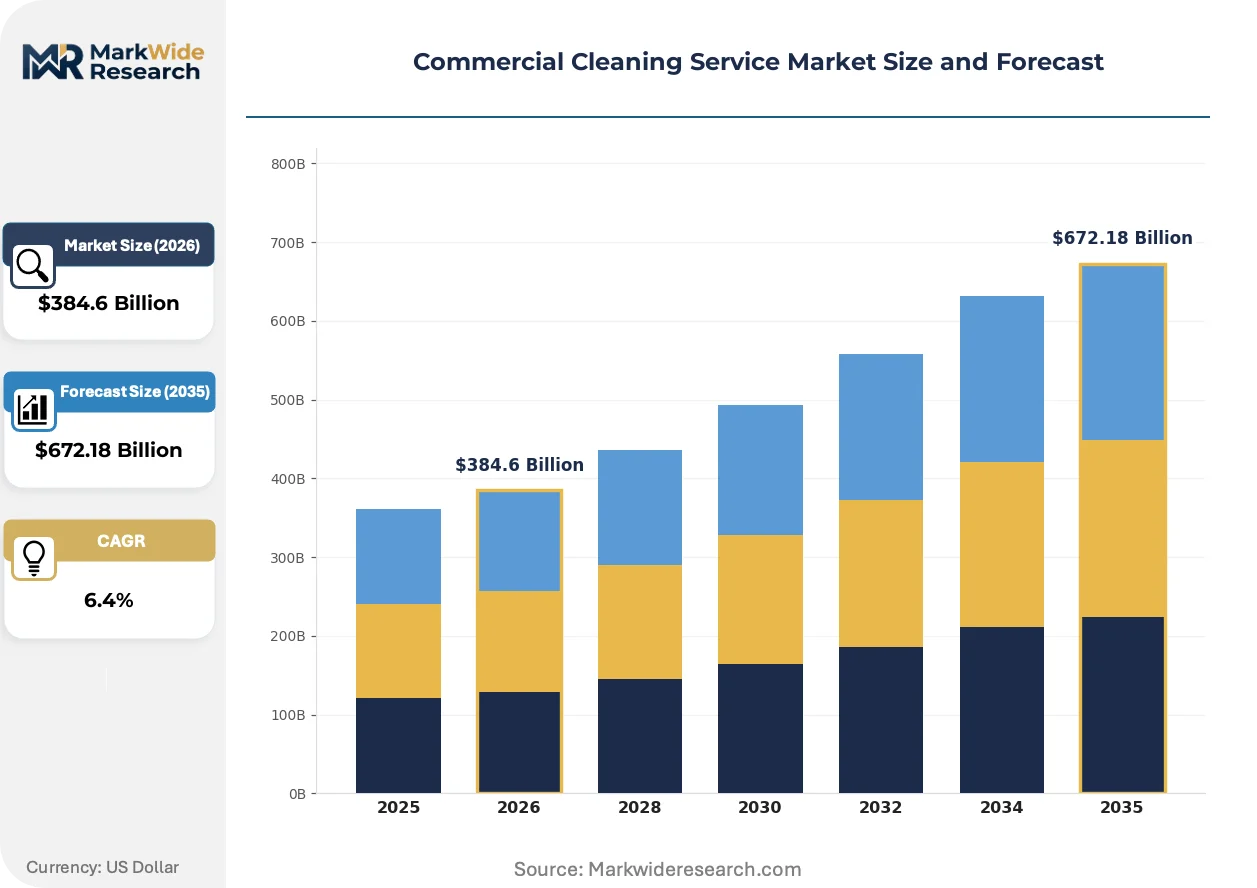
| Market Size in 2026 | $384.6 Billion |
| Market Size in 2035 | $672.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Office Cleaning, Industrial Cleaning, Window Washing, Floor Care Client Type: Commercial Offices, Retail Spaces, Educational Institutions, Healthcare Facilities Cleaning Method: Steam Cleaning, Disinfection, Eco-Friendly Cleaning, Deep Cleaning Frequency: Daily, Weekly, Monthly, One-Time |
| Companies Covered | Jani-King, City Wide Facility Solutions, CleanNet USA, ServiceMaster Clean, Coverall Commercial Cleaning, Anago Cleaning Systems, Stratus Building Solutions, ABM Industries, Jan-Pro Cleaning Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Cleaning Service Market Trends and Innovations
Autonomous cleaning equipment and real-time verification sensors are compressing the gap between scheduled service and continuous hygiene maintenance across high-traffic commercial environments.
Electrostatic spray disinfection is decentralizing service delivery models by enabling smaller crews to cover larger footprints with consistent chemical coverage. Regional hospital systems in Texas and Florida are deploying portable units for same-day terminal cleaning of isolation rooms. This compression of labor-to-square-foot ratios threatens traditional time-and-materials billing structures.
REACH regulation amendments on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of stain-resistant carpet treatments and floor finishes used in European commercial contracts. German facility managers are accelerating procurement of fluorine-free alternatives ahead of 2025 restriction deadlines. The transition elevates R&D costs for chemical suppliers while creating specification advantages for early compliant service providers.
Performance-based contract structures with penalty clauses for ATP test failures are displacing fixed-fee arrangements in corporate headquarters and aviation facilities. Procurement teams in Singapore and Dubai now mandate quarterly third-party hygiene audits with published scorecards. This shift concentrates volume with operators capable of consistent documentation and rapid corrective response protocols.
Commercial Cleaning Service Market Segmentation
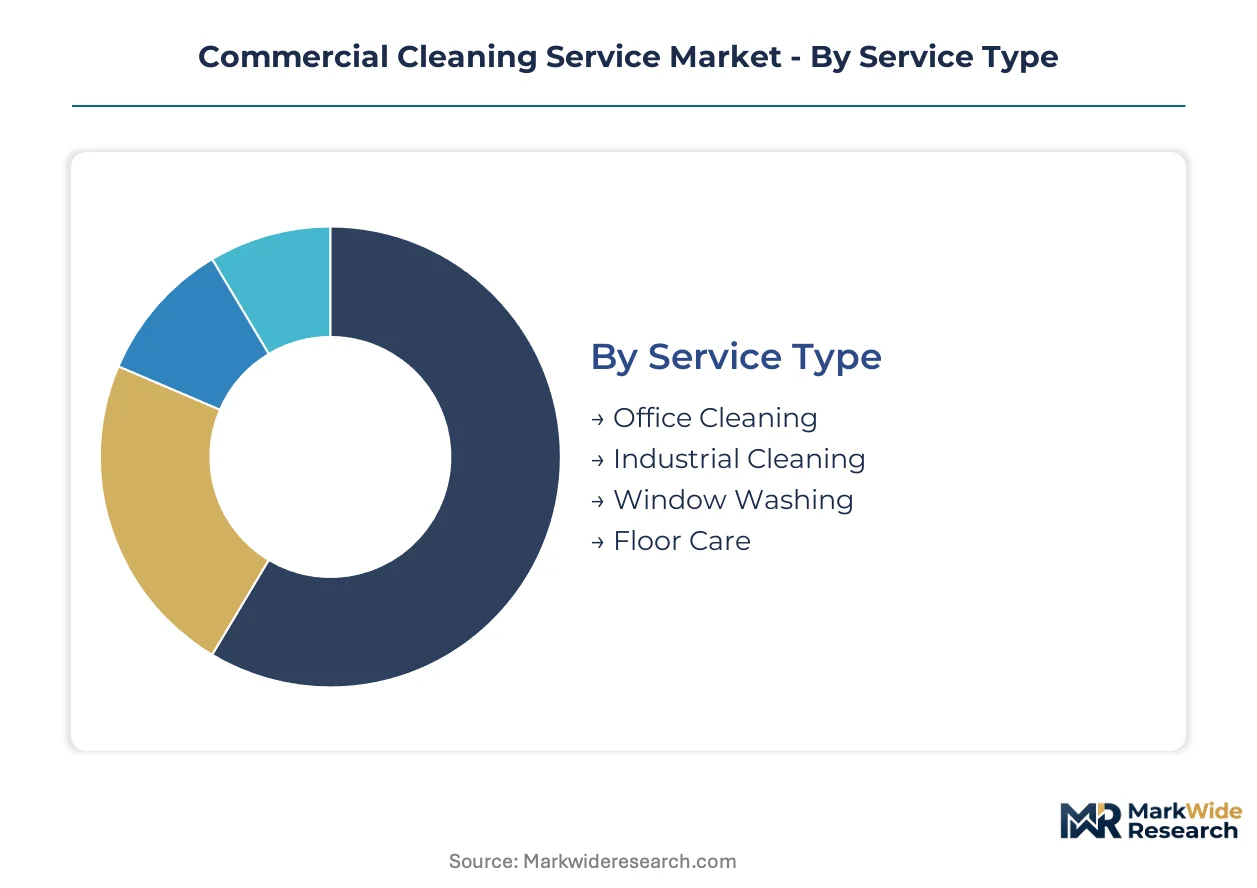
Commercial cleaning service providers configure operations around facility risk profiles, regulatory exposure, and contract renewal economics. Each segmentation dimension reveals distinct margin structures and capability requirements that shape competitive positioning.
Service Type:
Standardization dominates low-complexity surface maintenance, while hazardous material protocols and specialized equipment create defensible premium tiers.
- Office Cleaning:Scheduled dusting, vacuuming, and restroom sanitation using HEPA filtration equipment and EPA-registered surface disinfectants. Demand concentrates in urban commercial corridors of the United States and Germany where facility density sustains recurring contract volumes despite compressed margins.
- Industrial Cleaning:Chemical spill response, confined space entry, and hazardous material handling requiring OSHA-certified technicians and specialized PPE. Manufacturing corridors in Germany and Japan command premium pricing due to liability exposure and certification scarcity.
- Window Washing:Exterior facade maintenance using suspended platforms and water-fed pole systems for high-rise commercial structures.
- Floor Care:Stripping, sealing, and refinishing of hard surface flooring across retail and aviation facilities.
Most installed capacity flows through Office Cleaning. Expansion is steepest in Industrial Cleaning.
Client Type:
Contract value scales with regulatory scrutiny and infection liability exposure across end-use verticals.
- Healthcare Facilities:Terminal cleaning of isolation rooms, surgical suite turnover, and ATP-verified disinfection protocols using EPA-registered antimicrobials. North American hospital systems and Western European clinics are expanding contracted sanitation protocols due to healthcare-associated infection liability.
- Educational Institutions:LEED-aligned green chemistry protocols and Scope 3 emissions tracking across university and K-12 campuses. Corporate headquarters in Japan and Germany are adopting similar sustainability specifications.
- Commercial Offices:Routine maintenance of workstations, meeting rooms, and common areas with thin margins and high contract churn.
- Retail Spaces:High-frequency surface wiping and floor maintenance tied to foot traffic patterns and seasonal volume spikes.
Healthcare Facilities capture the highest contract values per square foot. Educational Institutions are gaining share fastest.
Cleaning Method:
Technology intensity separates commodity labor deployment from certified protocol execution.
- Disinfection:Electrostatic spray application and ATP bioluminescence verification for regulatory compliance in aviation and healthcare environments. Post-pandemic indoor air quality standards in Germany sustain integrated HVAC-cleaning service bundles.
- Eco-Friendly Cleaning:Biodegradable surfactant formulations and fluorine-free floor finishes ahead of EU Green Deal enforcement deadlines. German facility managers are accelerating procurement of REACH-compliant alternatives.
- Steam Cleaning:High-temperature sanitization without chemical residues for food service and childcare facilities.
- Deep Cleaning:Intensive restoration protocols for move-in/move-out and post-construction environments.
Disinfection commands the highest technician certification requirements. Eco-Friendly Cleaning shows the steepest specification upgrade trajectory.
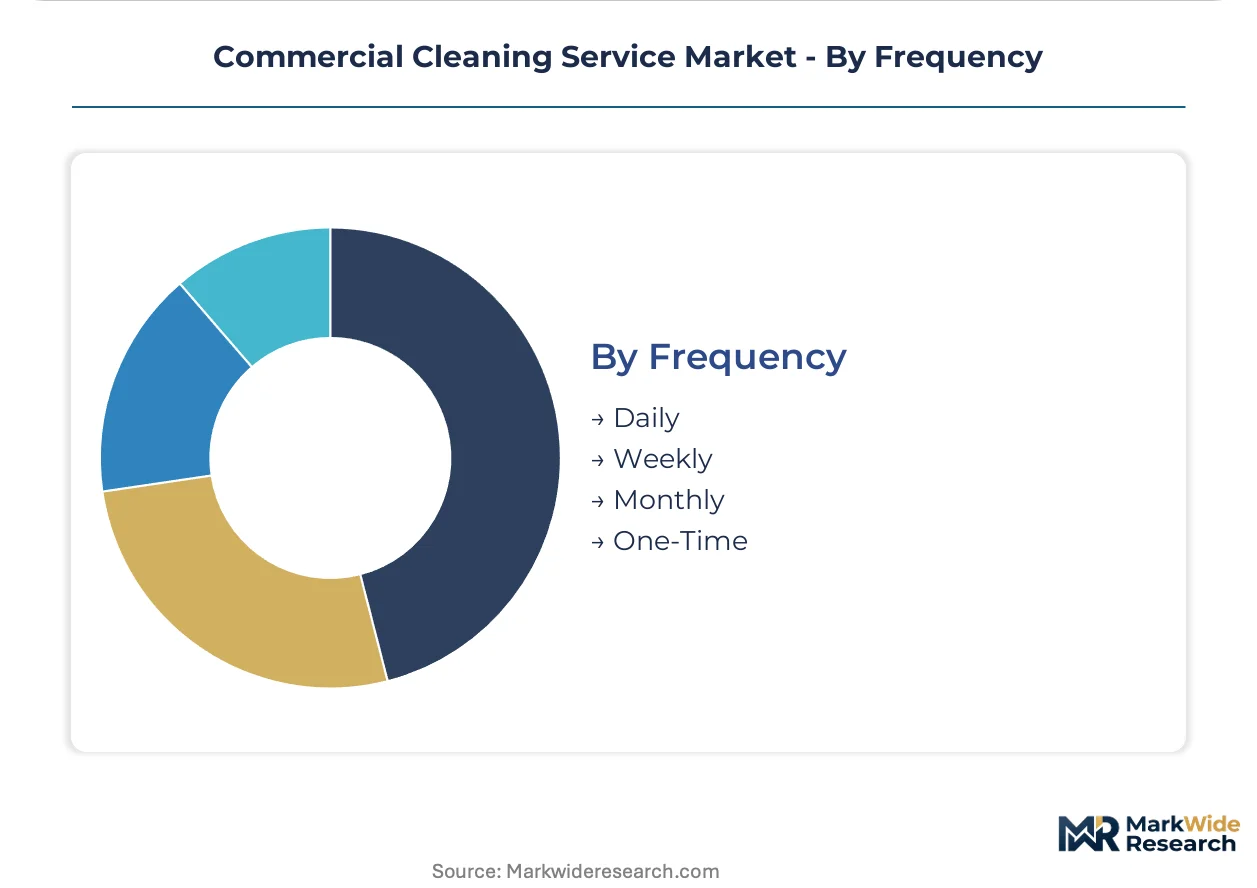
Frequency:
Contract structure determines working capital intensity and crew utilization rates.
- Daily:Continuous presence models for high-traffic corporate headquarters and healthcare facilities with penalty clauses for ATP test failures.
- Weekly:Recurring maintenance cycles for standard commercial offices balancing service levels against budget constraints.
- Monthly:Periodic deep cleaning and floor care for lower-occupancy facilities.
- One-Time:Event-driven restoration and post-construction cleanup with volatile demand patterns.
Daily contracts lock in the highest retention rates. One-Time services exhibit the most seasonal volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility density and regulatory stringency diverge sharply between mature Western markets and emerging service corridors. Germany enforces REACH-compliant chemistry mandates that elevate procurement standards across Central Europe. The United States concentrates contract volume through OSHA-mandated healthcare protocols that compress renewal cycles toward certified operators.
United States
Urban commercial corridors in New York, Chicago, and Los Angeles sustain recurring contract volumes through high facility density. OSHA bloodborne pathogen standards mandate exposure control plans that elevate demand for certified technicians with documented training records. Hospital systems in Texas and Florida are deploying portable electrostatic units for same-day terminal cleaning of isolation rooms.
Germany
Post-pandemic indoor air quality standards sustain capital investment in integrated HVAC-cleaning service bundles across industrial zones. REACH regulation amendments on PFAS are forcing reformulation of stain-resistant carpet treatments and floor finishes ahead of 2025 restriction deadlines. Facility managers in Munich and Frankfurt are accelerating procurement of fluorine-free alternatives.
Japan
Corporate headquarters in Tokyo and Osaka are adopting sustainability specifications aligned with LEED protocols and Scope 3 emissions tracking. METI guidelines on indoor environmental quality drive specification upgrades for HEPA filtration equipment in commercial buildings. Manufacturing corridors in Nagoya command premium pricing for industrial cleaning due to certification scarcity.
United Kingdom
Educational institutions across London and the Southeast are driving adoption of green chemistry cleaning protocols for emissions reduction targets. The country's building wellness certification frameworks reshape supplier qualification criteria for contract renewal terms. Aviation facilities at Heathrow mandate quarterly third-party hygiene audits with published scorecards.
Canada
Healthcare-associated infection liability is expanding contracted sanitation protocols across Ontario and Quebec hospital networks. Health Canada regulations on antimicrobial product claims elevate procurement preference for certified service providers. Toronto's commercial office density sustains thin-margin recurring contracts despite high contract churn rates.
Commercial Cleaning Service Market Competitive Landscape
Top-tier vendors anchor multi-site integrated facility contracts, while mid-tier franchise networks compete on geographic coverage and rapid deployment capability. The vendor base stratifies across three tiers: national integrated facility managers, regional franchise operators, and specialized industrial cleaning contractors. Two strategic archetypes dominate competitive positioning—franchise-based scale players leveraging recurring revenue anchoring, and specialized healthcare/industrial operators commanding premium pricing through certification scarcity. Consolidation pressure concentrates through M&A activity targeting regional operators with healthcare credentials, while technology licensing partnerships accelerate sensor-enabled verification deployment.
Within the franchise-operator tier, Jani-King and Anago Cleaning Systems exemplify network-based scale models that prioritize recurring contract retention across dispersed geographic footprints. ServiceMaster Clean occupies a position representing specialized healthcare sanitation expertise and certified technician training programs. ABM Industries anchors the integrated-facility archetype, bundling cleaning with maintenance and security services under large-scale enterprise contracts. These three patterns—franchise network density, healthcare specialization, and integrated facility bundling—capture the essential competitive vectors shaping procurement decisions across end-use verticals.
| Leading Market Players |
|---|
| Jani-King |
| City Wide Facility Solutions |
| CleanNet USA |
| ServiceMaster Clean |
| Coverall Commercial Cleaning |
| Anago Cleaning Systems |
| Stratus Building Solutions |
| ABM Industries |
| Jan-Pro Cleaning Services |
| Others |
Pricing and Supply Chain Analysis
Healthcare facility procurement teams in the United States and Germany anchor contract volumes through multi-year bundled service agreements that blend disinfection protocols with HVAC maintenance and compliance documentation. This buyer concentration elevates pricing power for certified operators while compressing margins for commodity surface-cleaning providers lacking ATP verification capabilities.
Pricing Analysis
Bundled integrated facility contracts command premium pricing against unbundled spot-cleaning arrangements. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-certified disinfection from routine office maintenance and one-time restoration services. Price differentiation rests on OSHA bloodborne pathogen certification tiers and EPA-registered disinfectant verification protocols. Cost compression in standard office cleaning is intensifying because franchise operators face minimum wage pressure in dense urban corridors. Educational institutions exhibit highest price sensitivity due to constrained public budgets, while aviation and healthcare facilities show lowest sensitivity given liability exposure.
Supply Chain Analysis
Reverse-logistics flows for HEPA filtration equipment and electrostatic sprayer refurbishment create secondary revenue streams for service providers with in-house technical capabilities. Active ingredient manufacturing for EPA-registered disinfectants concentrates in China, with formulation and packaging distributed across the United States and Germany. Raw material dependencies include quaternary ammonium compounds, hydrogen peroxide concentrates, and specialized microfiber textiles. Single-source vulnerability in Chinese active ingredient supply elevates procurement risk for North American operators. Distribution runs through regional chemical distributors and direct manufacturer relationships serving franchise networks and integrated facility managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial cleaning service market functions as a stable compounder underpinned by regulatory mandates that embed recurring compliance spending into facility operating budgets.
For Market Incumbents: Hedge against electrostatic sprayer substitution by embedding IoT-enabled ATP monitoring into multi-year enterprise contracts with penalty clauses for hygiene failures. Franchise operators should secure backward integration into EPA-registered chemical formulation to defend margin position against supply concentration in China.
For New Entrants and Emerging Players: Mid-sized manufacturing corridors in Japan's Nagoya region present underserved demand for industrial hazardous cleaning certifications with premium pricing power. New entrants should target educational institutions in the United Kingdom seeking LEED-aligned green chemistry protocols, deploying sustainability-focused go-to-market positioning that emphasizes Scope 3 emissions tracking.
For Investors and Strategic Acquirers: Integrated facility management conglomerates are the most active acquirer in this space, consolidating regional operators with healthcare credentials and certified technician pipelines. Long-term viability centers on recurring revenue durability and regulatory compliance moats. Acquisition target archetypes include franchise networks with dense urban footprints and specialized industrial contractors with confined-space entry certifications. Practitioners should monitor EPA disinfectant efficacy standard revisions and EU Green Deal enforcement timelines for early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | OSHA bloodborne pathogen and EPA disinfectant credentials lock in healthcare contract renewals. |
| Sensor-Enabled Verification | IoT ATP monitoring systems create real-time hygiene dashboards that secure multi-year enterprise agreements. |
| Green Chemistry Reformulation | REACH-compliant fluorine-free alternatives ahead of EU deadlines capture specification advantages. |
| Franchise Network Expansion | Dense geographic coverage in urban commercial corridors sustains recurring contract volumes. |
| Integrated Facility Bundling | Cleaning-maintenance-security combinations reduce procurement friction for large-scale corporate portfolios. |
Research Methodology
Bottom-up facility-type modeling reconciled against top-down service-provider capacity tracking forms the analytical core of this study. Primary interviews with franchise operations directors, healthcare facility procurement managers, EPA compliance officers, and industrial plant maintenance heads combined with secondary validation from OSHA enforcement databases, EPA registered pesticide product listings, and customs trade data on chemical imports. Cross-referencing contract value disclosures from publicly traded integrated facility managers against franchise royalty reporting enables triangulation between demand-side spending and supply-side revenue capture.
Historical trendline analysis of contract renewal rates, pricing trajectories, and certification penetration across service types, client verticals, cleaning methods, and frequency tiers informs the projection framework. Segmentation dimensions modeled include service complexity tier, regulatory exposure level, technology intensity, and geographic facility density cluster. CAGRs derive from fitted growth curves adjusted for enforcement timeline shifts in EPA and REACH regulations. Forecast inputs incorporate labor cost inflation assumptions and green chemistry specification upgrade velocities across educational and corporate end-uses.
Underlying measurement precision varies by segment; healthcare disinfection and industrial hazardous cleaning carry tighter precision than commodity office maintenance due to documented contract value disclosures. Forecasts reflect assumptions regarding regulatory enforcement continuity and supply chain stability that could revise under tariff escalation or active ingredient shortage scenarios. Practitioners should monitor OSHA standard revision announcements and EU Green Deal implementation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Cleaning Trolleys Market