
 Vacuum Cleaner Filter Market | 2026-2036
Vacuum Cleaner Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Cleaner Filter Market Analytics
China is narrowing the gap with Western filter manufacturing through expanded nonwoven production corridors in Zhejiang and Jiangsu provinces. Dyson leverages captive R&D facilities in Singapore and Malaysia to sustain premium HEPA membrane performance. Electrolux anchors European replacement cycles through dense service-part distribution across Nordic and German retail networks. Miele differentiates via proprietary AirClean filter assemblies that command loyalty in high-end residential channels.
A vacuum cleaner filter is a porous media assembly, typically constructed from pleated glass microfiber, melt-blown polypropylene, or bonded cellulose matrices, engineered to capture particulate matter down to 0.3 microns while maintaining rated airflow resistance measured in pascals of pressure drop; its primary commercial purpose is to protect vacuum motor assemblies from debris abrasion and to prevent respirable dust recirculation in enclosed indoor environments. HEPA filter types occupy the dominant margin pool due to certification complexity and replacement stickiness, while activated carbon inserts represent the fastest-growing configuration as odor-neutralization features penetrate mid-tier residential units. Foam and cyclone segments function as gateway technologies in emerging-market price tiers where disposable income constraints limit upgrade velocity to certified media.
The U.S. EPA Energy Star program and OSHA indoor air quality guidelines jointly elevate filtration efficiency benchmarks in commercial and institutional procurement specifications. The EU Ecodesign Directive and REACH chemical compliance frameworks restrict certain synthetic binder chemistries, forcing material reformulation across import-dependent supply chains. Stakeholders must monitor evolving interoperability standards between proprietary filter cartridges and third-party replacement suppliers, as platform lock-in strategies become a decisive battleground for recurring revenue capture.
Market Dynamics
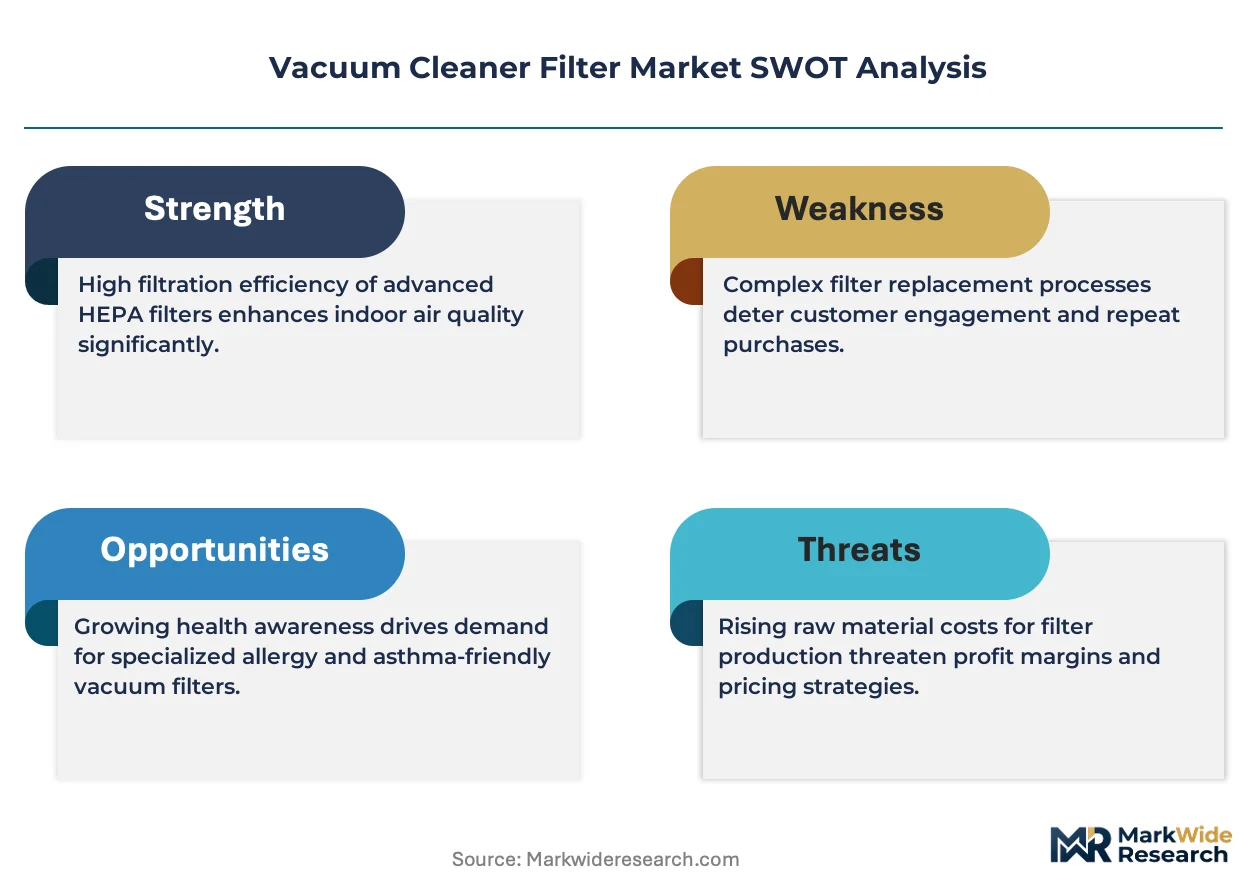
Replacement filter procurement is tightening around proprietary cartridge architectures as manufacturers deploy platform lock-in to capture recurring revenue streams. This structural pivot from commodity media sales toward captive aftermarket ecosystems reconfigures competitive stakes across residential and commercial channels.
Growth Catalysts
- EU Ecodesign Directive:Tightening efficiency standards across member states compel filter redesign toward lower pressure-drop architectures, accelerating upgrade cycles in German and Nordic replacement markets.
- HEPA certification complexity:The technical barrier of 0.3-micron capture validation at rated airflow creates replacement stickiness, locking residential owners into branded consumable ecosystems.
- Activated carbon odor neutralization:Penetration of carbon-insert configurations into mid-tier residential units expands average revenue per filter assembly beyond particulate-only media.
Market Restraints
- Glass microfiber supply concentration:Pleated HEPA media production clusters in Zhejiang and Jiangsu provinces expose downstream assemblers to single-region logistics disruption.
- REACH chemical compliance:Restrictions on synthetic binder chemistries force material reformulation across import-dependent European supply chains, extending qualification timelines.
- Cyclone pre-separation:Centrifugal debris removal in emerging-market price tiers delays upgrade velocity to certified disposable media, compressing addressable volume in disposable-constrained segments.
Strategic Opportunities
- Smart home integration:IoT-enabled filter-life monitoring embedded in connected vacuum architectures creates predictive replacement triggers, tightening manufacturer-customer data loops.
- Commercial indoor air quality mandates:OSHA guidelines elevating filtration benchmarks in institutional procurement specifications open specification-grade filter assemblies to facility managers.
- India residential electrification:Expanding appliance penetration in urbanizing tier-2 cities builds installed bases requiring future HEPA upgrade paths as income thresholds cross.
Industry Challenges
- Interoperability standardization delays:Absence of unified cartridge-interface specifications fragments third-party replacement markets, forcing reverse-engineering investments.
- Multi-material bonding expertise:Lamination of melt-blown polypropylene to activated carbon layers demands specialized thermal-welding talent scarce in contract manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Cleaner Filter Market |
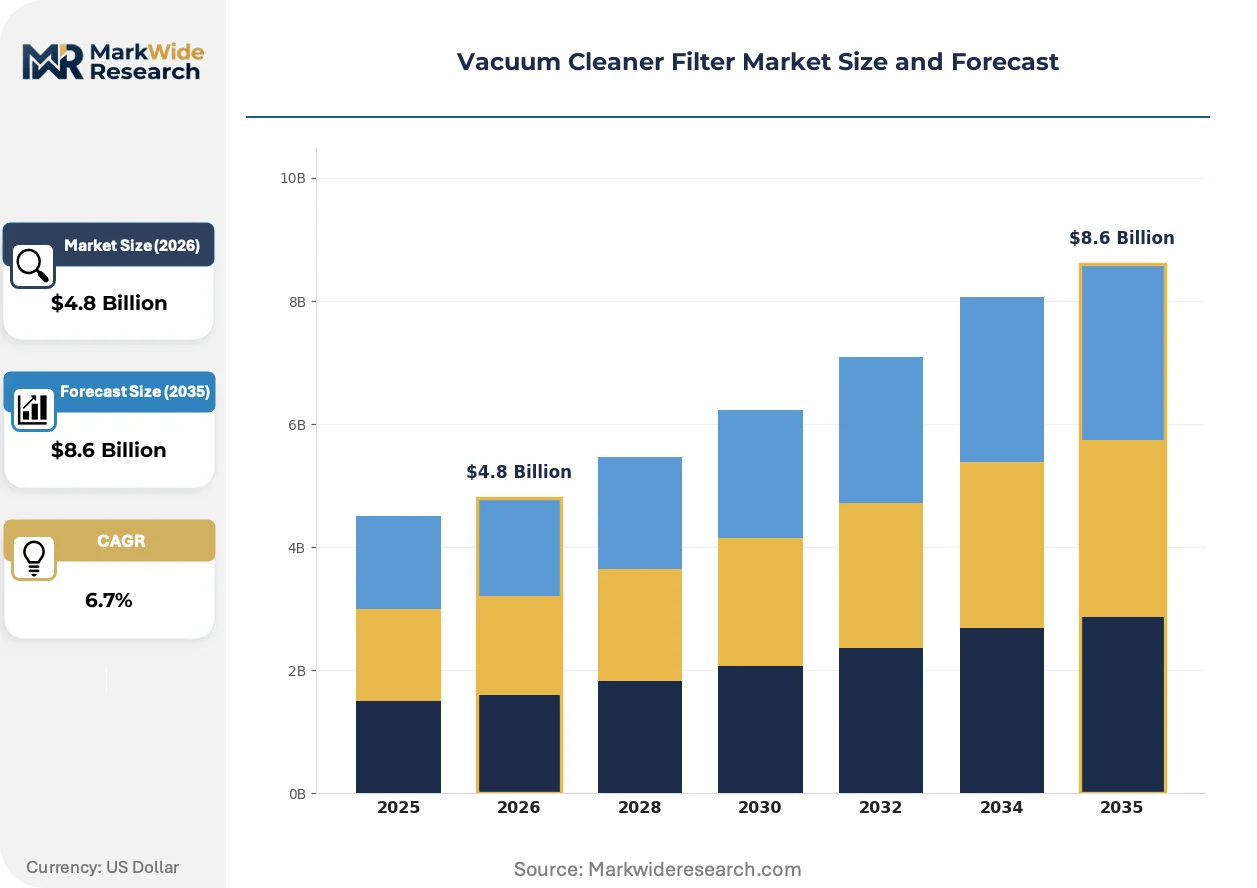
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: HEPA, Activated Carbon, Foam, Cyclone Material: Plastic, Metal, Paper, Fiberglass Application: Residential, Commercial, Industrial, Automotive End User: Homeowners, Cleaning Services, Manufacturers, Retail Businesses |
| Companies Covered | Dyson, SharkNinja, Bissell, Electrolux, Miele, Hoover, LG Electronics, Samsung Electronics, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Cleaner Filter Market Evolving Landscape
Filter media architectures are converging with sensor-enabled predictive maintenance, transforming passive consumables into data-generating system components. This integration redefines value capture from physical replacement toward software-mediated service relationships.
Pleated glass microfiber HEPA assemblies are migrating from standalone particulate capture toward hybrid configurations incorporating electret-charged synthetic layers. Premium residential buyers in North American and German markets are adopting these composite media at accelerated replacement frequencies. The technology is migrating from certification-focused performance marketing toward total cost-of-ownership positioning that compresses price competition on raw capture efficiency alone.
REACH chemical compliance frameworks are restricting perfluorinated binder chemistries previously standard in wet-laid glass microfiber production. Industrial consequence includes forced qualification of bio-based acrylic alternatives with inferior tensile strength under humid storage. Filter assemblers serving EU-bound product lines are most affected, responding with dual-track material inventories segregated by destination market.
Residential buyers are compressing replacement decision cycles through mobile-app-enabled filter-life tracking bundled with connected vacuum hardware. The traditional retail channel of periodic in-store repurchase is yielding to direct-to-consumer subscription models with automated replenishment triggers. This behavioral shift is most visible in US and UK metropolitan markets where smart appliance penetration exceeds national averages.
Vacuum Cleaner Filter Market Segmentation
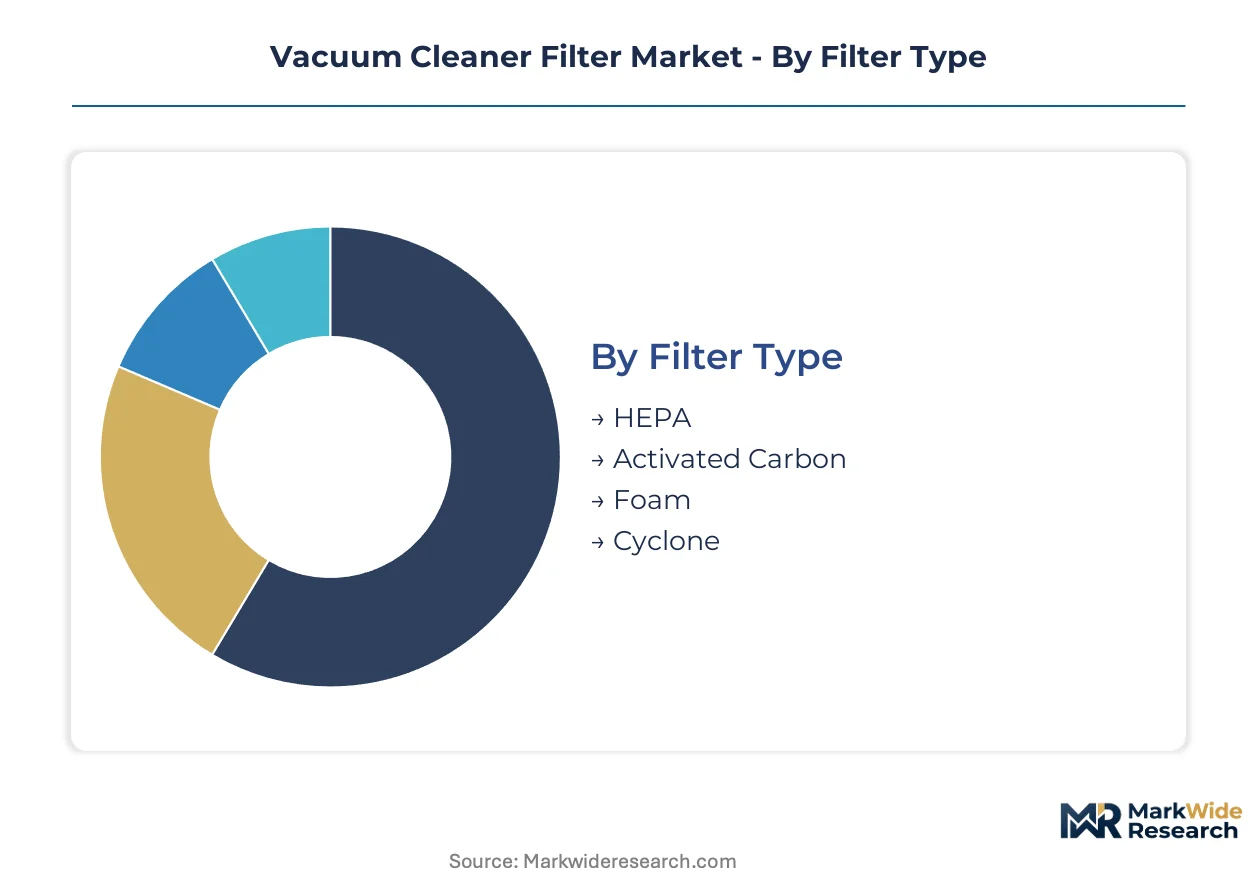
Filter segmentation in this market maps directly to performance certification tiers, material cost structures, and replacement frequency economics. Each dimension reveals distinct margin profiles and competitive intensity patterns that shape manufacturer portfolio strategy.
Filter Type:
Mature HEPA configurations anchor premium replacement revenue while emerging cyclone architectures reshape entry-level procurement patterns across price-sensitive geographies.
- HEPA:Pleated glass microfiber assemblies certified to 0.3-micron capture thresholds command the dominant margin pool in Germany and US residential channels. Replacement stickiness intensifies as homeowners invest in allergen-sensitive indoor environments, locking consumable demand into branded ecosystems with proprietary cartridge interfaces.
- Activated Carbon:Hybrid inserts combining particulate capture with odor-neutralization chemistry penetrate mid-tier residential units at accelerating velocity. Demand concentrates in North American metropolitan markets where pet ownership rates and open-plan living configurations elevate malodor sensitivity among replacement purchasers.
- Foam:Open-cell polyurethane matrices serve as washable pre-filtration stages in emerging-market appliance tiers where disposable income constraints delay HEPA upgrade paths.
- Cyclone:Centrifugal debris separation chambers function as gateway technologies in price-compressed segments, postponing certified media adoption until income thresholds cross.
HEPA retains volume leadership in value terms; activated carbon holds the steepest expansion curve as odor-neutralization features migrate downmarket.
Material:
Cost tier stratification separates commodity substrates from performance-optimized matrices, with supply concentration in Chinese manufacturing corridors driving procurement geography decisions.
- Plastic:Injection-molded polypropylene housings and structural frames dominate mass-market cartridge production due to thermal-welding compatibility with nonwoven media layers.
- Metal:Stainless-steel support grids and retention springs anchor industrial-grade filter assemblies subjected to high-velocity airflow and mechanical stress cycles in commercial cleaning equipment.
- Paper:Cellulose-based pleated media serve cost-optimized residential segments where capture efficiency requirements remain below HEPA thresholds and replacement frequency is compressed.
- Fiberglass:Wet-laid borosilicate microfiber matrices constitute the functional core of certified HEPA assemblies, with production gravity centering on Zhejiang and Jiangsu province corridors.
Plastic dominates unit volume across all price tiers; fiberglass commands the highest per-unit material cost and tightest supply concentration.
Application:
Customer type divergence separates episodic residential purchasers from contract-bound institutional procurement, with specification-grade requirements fragmenting competitive dynamics across end-use contexts.
- Residential:Homeowner-driven replacement cycles exhibit high brand loyalty and sensitivity to certification labeling, with German and US markets showing strongest adherence to OEM-branded consumables.
- Commercial:Facility management procurement governed by OSHA indoor air quality guidelines elevates filtration benchmarks in US institutional specifications, opening dedicated sales channels for validated filter assemblies.
- Industrial:Heavy-debris environments in manufacturing and logistics operations demand reinforced cartridge architectures with extended service intervals and bulk procurement economics.
- Automotive:Cabin air filtration and specialized detailing equipment create niche demand for compact-form-factor media with vibration-resistant mounting interfaces.
Residential captures the widest installed base; commercial exhibits the most structured procurement specifications and recurring contract value.
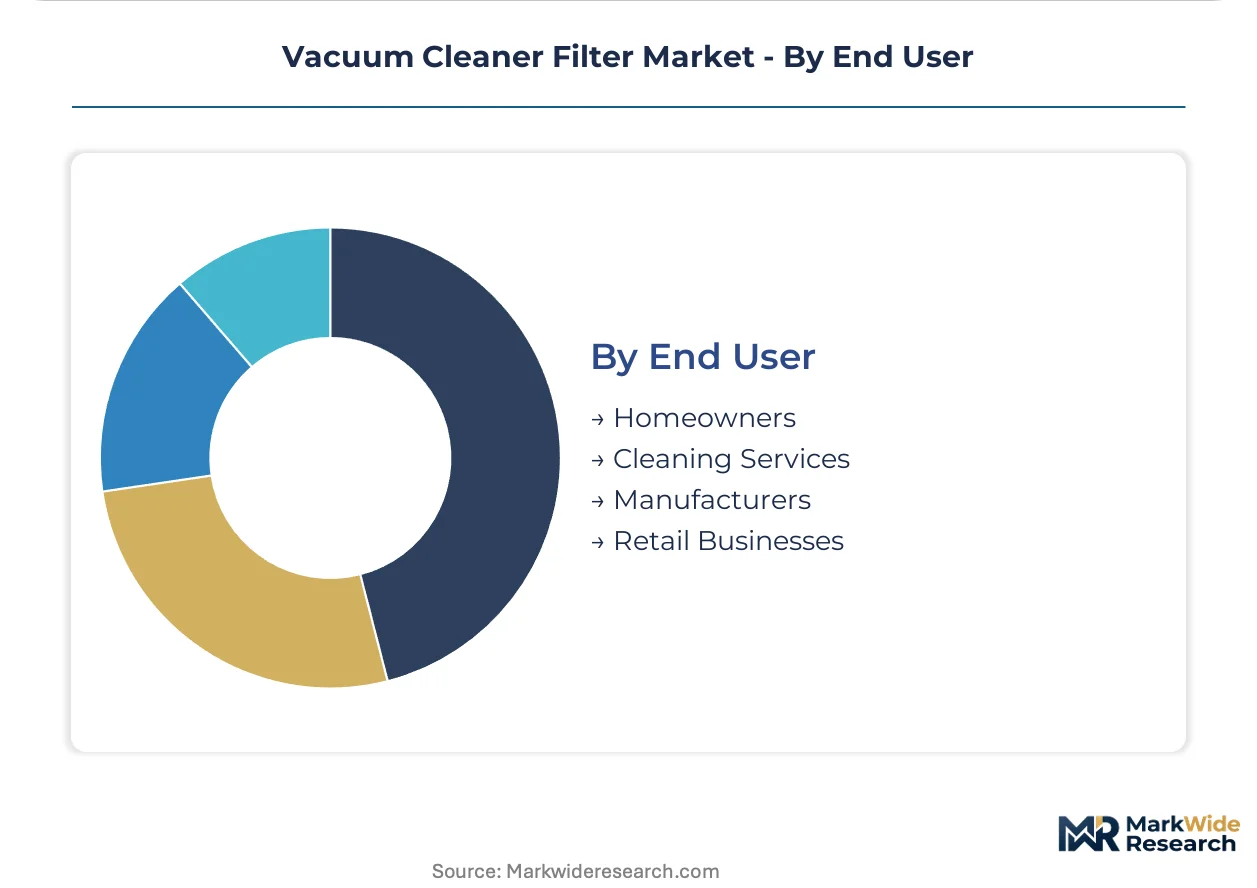
End User:
Procurement authority fragmentation separates individual decision-makers from organizational purchasing departments, with channel strategy diverging accordingly across direct-to-consumer and B2B service routes.
- Homeowners:Individual replacement purchasers respond to mobile-app-enabled filter-life tracking and subscription replenishment models, with adoption clustering in UK and US metropolitan smart-appliance penetration zones.
- Cleaning Services:Contract cleaning operators prioritize total cost-of-ownership calculations and bulk procurement terms, driving volume concentration through specialized distribution channels serving professional equipment fleets.
- Manufacturers:Original equipment producers source filter assemblies as integrated subsystems, with platform lock-in strategies capturing captive aftermarket revenue through proprietary cartridge architectures.
- Retail Businesses:Electronics and appliance retailers manage replacement inventory as attachment-sale opportunities, with shelf-space allocation favoring branded consumables with recognized certification marks.
Homeowners represent the most dispersed demand base; manufacturers control the tightest vertical integration into captive aftermarket ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass microfiber pleating operations cluster in Zhejiang and Jiangsu provinces, exposing downstream assemblers to concentrated supply risk. German and US residential channels anchor replacement demand through OEM-branded consumable ecosystems.
Germany
Homeowners in Bavaria and North Rhine-Westphalia drive HEPA-certified replacement cycles through Miele and Electrolux service networks. The EU Ecodesign Directive compels filter redesign toward lower pressure-drop architectures across German manufacturing bases. Stuttgart and Mannheim host dense distribution corridors for premium residential consumables.
United States
Metropolitan homeowners in California and New York Metro adopt smart-appliance-enabled filter subscriptions at accelerating velocity. The EPA Energy Star program elevates filtration benchmarks in institutional procurement specifications. Chicago and Dallas anchor bulk replacement inventory for commercial cleaning fleets.
China
Tier-2 city electrification in Jiangsu and Zhejiang builds installed bases requiring future HEPA upgrade paths. The MIIT enforces GB standards for appliance energy efficiency that indirectly shape filter specification requirements. Suzhou and Ningbo concentrate wet-laid borosilicate microfiber production corridors serving export-bound assemblies.
India
Urbanizing households in Maharashtra and Karnataka delay certified media adoption due to disposable income constraints favoring cyclone pre-separation. The BIS mandates appliance safety standards that filter imports must satisfy for market access. Mumbai and Bangalore represent emerging demand nodes as income thresholds approach HEPA crossover points.
United Kingdom
London and Southeast England exhibit strongest adherence to mobile-app-enabled filter-life tracking bundled with connected vacuum hardware. The UK Environment Agency enforces REACH-aligned chemical compliance on import-dependent supply chains. Birmingham and Manchester retail networks manage replacement inventory as attachment-sale opportunities.
Vacuum Cleaner Filter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in media fabrication. The vendor base stratifies between captive aftermarket ecosystems and third-party replacement suppliers. Two archetypes dominate: vertically integrated appliance OEMs with proprietary cartridge architectures, and independent filter fabricators serving cross-brand aftermarket channels. Competitive moves concentrate on platform lock-in enforcement and smart-home integration partnerships.
Among vertically integrated appliance OEMs, Dyson, Electrolux, and Miele exemplify distinct strategic positioning within the premium residential tier. Dyson anchors Singapore and Malaysia-based R&D corridors for HEPA membrane performance. Electrolux occupies a position within European replacement cycle management through Nordic and German retail density. Miele represents proprietary AirClean filter assembly differentiation in high-end residential channels. These three entities collectively illustrate how captive aftermarket ecosystems reconfigure competitive stakes away from commodity media sales.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Bissell |
| Electrolux |
| Miele |
| Hoover |
| LG Electronics |
| Samsung Electronics |
| Philips |
| Others |
Value Network & Pricing Analysis
Zhejiang and Jiangsu province microfiber corridors concentrate wet-laid borosilicate production capacity, granting upstream suppliers outsized leverage over downstream filter assemblers competing on capture efficiency certification. This geographic clustering translates directly into tiered pricing power where OEM-branded HEPA cartridges command substantial premiums over third-party alternatives.
Pricing Analysis
EU Ecodesign Directive dictates the pricing tier structure across European-bound product lines, forcing material reformulation costs that compress margins in the standard tier while amplifying premiums for certified low-pressure-drop architectures. Three-tier pricing structure across premium, standard, and economy levels separates proprietary AirClean assemblies from private-label HEPA media from washable foam pre-filters. Cost compression in economy tiers is intensifying because REACH compliance extends qualification timelines for bio-based acrylic binders. Residential homeowners in Germany and the United States exhibit lowest price sensitivity due to allergen-driven replacement stickiness, while emerging-market cyclone-dependent buyers remain most elastic.
Supply Chain Analysis
Contract manufacturers in Suzhou and Ningbo hold dominant wet-laid glass microfiber capacity, with secondary concentration in Malaysian thermoforming operations serving Dyson's Singapore R&D corridor. Raw material dependencies center on borosilicate glass fiber from Chinese state-owned suppliers, polypropylene resin from Sinopec corridors, and activated carbon from coconut-shell processors in Southeast Asia. Single-source vulnerability in Zhejiang-Jiangsu logistics exposes downstream assemblers to regional disruption from energy rationing or port congestion. Distribution runs through Nordic and German retail networks for Electrolux-branded consumables, direct-to-consumer subscription channels for smart-appliance bundles in UK and US metropolitan zones, and specialized aftermarket distributors serving commercial cleaning fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclone pre-separation technologies in emerging markets threaten to delay HEPA upgrade velocity indefinitely, compressing the addressable base for certified media unless incumbents accelerate income-threshold crossover strategies.
For Market Incumbents: Insulate proprietary cartridge ecosystems through deeper backward integration into Zhejiang microfiber corridors, securing captive supply of borosilicate matrices against logistics disruption. Invest in IoT-enabled filter-life monitoring to tighten manufacturer-customer data loops and preempt third-party replacement encroachment. Defend against cyclone substitution by bundling predictive maintenance software with hardware sales in tier-2 Indian cities approaching HEPA crossover income levels. For New Entrants and Emerging Players: Mid-market commercial cleaning services in US metropolitan zones represent the most penetrable entry point, as OSHA indoor air quality guidelines elevate filtration benchmarks without locking incumbents into branded ecosystems. Tier-2 Chinese cities with expanding residential electrification but limited OEM service networks offer white-space for private-label HEPA assemblies. Pursue direct-to-consumer subscription models with automated replenishment triggers, mirroring the channel shift visible in London and Southeast England smart-appliance penetration zones. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance OEMs with undermonetized aftermarket filter businesses and stagnant R&D investment in smart-home integration. Long-term viability hinges on platform lock-in enforcement capability across the projection horizon. Watch for inflection in India residential income distribution curves, as Maharashtra and Karnataka households crossing HEPA affordability thresholds signal replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microfiber Production | Captive supply of Zhejiang-sourced borosilicate matrices reduces REACH compliance timeline exposure. |
| Smart-Home Platform Integration | IoT-enabled filter-life monitoring in connected Dyson and Miele architectures tightens recurring revenue capture. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models bypass retail shelf-space competition in UK and US metropolitan markets. |
| REACH-Compliant Material Reformulation | Bio-based acrylic binder qualification opens sustained EU market access against restricted perfluorinated chemistries. |
| Commercial Indoor Air Quality Certification | OSHA-aligned specification-grade assemblies unlock facility management procurement in US institutional channels. |
Research Methodology
Desk research of customs trade filings, MIIT GB standard disclosures, and EU Ecodesign regulatory texts preceded structured interviews with filter media plant managers, appliance OEM procurement directors, commercial cleaning fleet operators, and Nordic retail category buyers. Primary fieldwork across Zhejiang manufacturing corridors and German distribution networks combined with secondary validation from SEC 10-K filings and appliance energy efficiency databases. Bottom-up unit economics triangulated against top-down market sizing across filter type, material, and application dimensions.
Fixed assumptions held regulatory enforcement timelines and income elasticity parameters constant across the modeling period, while varying smart-appliance penetration rates and REACH compliance cost pass-through scenarios. Segmentation modeling incorporated filter certification tier, end-use application, procurement channel structure, and regional regulatory cluster. CAGRs derived from replacement frequency economics and installed base expansion curves, with cross-checks against historical HEPA upgrade velocity in comparable appliance categories.
Macroeconomic conditions sit as an overlay; deviation in residential disposable income trajectories or energy input costs would shift the trajectory of emerging-market upgrade timing. Forecasts reflect documented assumptions regarding interoperability standardization delays and synthetic binder chemistry availability. Quarterly review of EU Ecodesign amendment proposals and India BIS appliance safety standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Carpet Extraction Cleaner Market