
 Countertop Spray Market | 2026-2036
Countertop Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Spray Market Outlook
Market Context
North American contract manufacturers is consolidating production capacity around concentrated surfactant blends and refill-compatible packaging systems. Reckitt Benckiser Group plc leverages its European R&D footprint to sustain antimicrobial efficacy claims across multiple regulatory jurisdictions. The Clorox Company anchors its position through backward integration into bleach precursor supply chains. Procter & Gamble Company differentiates via fragrance technology partnerships and dosing precision in trigger-spray mechanisms.
Technical Definition and Segment Structure
Countertop spray denotes a liquid cleaning formulation delivered through a mechanical trigger or aerosol actuator, typically containing surfactants, solvents, chelating agents, and functional additives at pH ranges of 3.0 to 11.5 depending on intended substrate compatibility. These products serve to remove soils, sanitize food-contact surfaces, and maintain aesthetic finish on laminate, stone, stainless steel, and sealed wood countertops in residential and commercial environments. All-purpose formulations occupy the largest volume position due to their cross-substrate utility, while antimicrobial variants command premium positioning in healthcare-adjacent food service settings. Pouch and concentrate refill packaging is gaining traction fastest among sustainability-oriented household buyers, though bottles retain dominance in restaurant procurement channels where immediate-use convenience governs purchasing decisions.
Regulatory Frame and Outlook
The EPA regulates antimicrobial claims under FIFRA, requiring registration and efficacy substantiation that shapes product development timelines and label positioning. California Air Resources Board VOC limits and OSHA hazard communication standards further constrain solvent selection and workplace use protocols for commercial accounts. ECHA REACH compliance requirements affect formulation chemistry for suppliers serving European export channels. Stakeholders must monitor evolving state-level chemical disclosure mandates and bio-based content procurement preferences among institutional buyers.
Market Dynamics
Concentrated surfactant chemistry and refill-compatible packaging systems are compressing traditional bottle supply chains while EPA Safer Choice and California VOC restrictions force simultaneous reformulation across antimicrobial and degreaser lines.
Growth Catalysts
- California VOC restrictions:State-level limits on volatile organic compounds are accelerating low-emission solvent adoption and creating first-mover advantages for compliant formulators.
- Healthcare-adjacent food service:Hospital cafeterias and medical office break rooms are expanding procurement of antimicrobial countertop sprays beyond traditional hospitality channels.
- Pouch concentrate systems:Refill technology is electrifying sustainability-oriented household purchasing and reducing per-use plastic intensity.
Market Restraints
- Petrochemical surfactant volatility:Linear alkylbenzene sulfonate and alcohol ethoxylate feedstock costs fluctuate with crude oil indices, squeezing margin stability for mid-tier producers.
- Bleach precursor concentration:Backward-integrated supply chains among top-tier manufacturers create sourcing bottlenecks for non-integrated competitors.
- Substrate compatibility limits:pH constraints between 3.0 and 11.5 restrict universal formulation claims and force SKU proliferation.
Strategic Opportunities
- Bio-based content mandates:Institutional buyers in federal and state procurement are establishing minimum renewable content thresholds, favoring suppliers with verified bio-surfactant supply.
- Stone and quartz countertop penetration:Premium residential renovation segments present underexploited demand for pH-neutral formulations compatible with engineered stone sealants.
- Direct-to-foodservice distribution:Bypassing traditional janitorial supply houses through specialized e-commerce platforms is compressing channel margins and capturing operator data.
Industry Challenges
- FIFRA registration timelines:EPA antimicrobial claim approvals extend product development cycles by 18-36 months, delaying revenue recognition for novel actives.
- Fragrance-chemistry expertise scarcity:Formulators struggle to recruit perfumery talent capable of masking base odors in reduced-VOC solvent systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Spray Market |
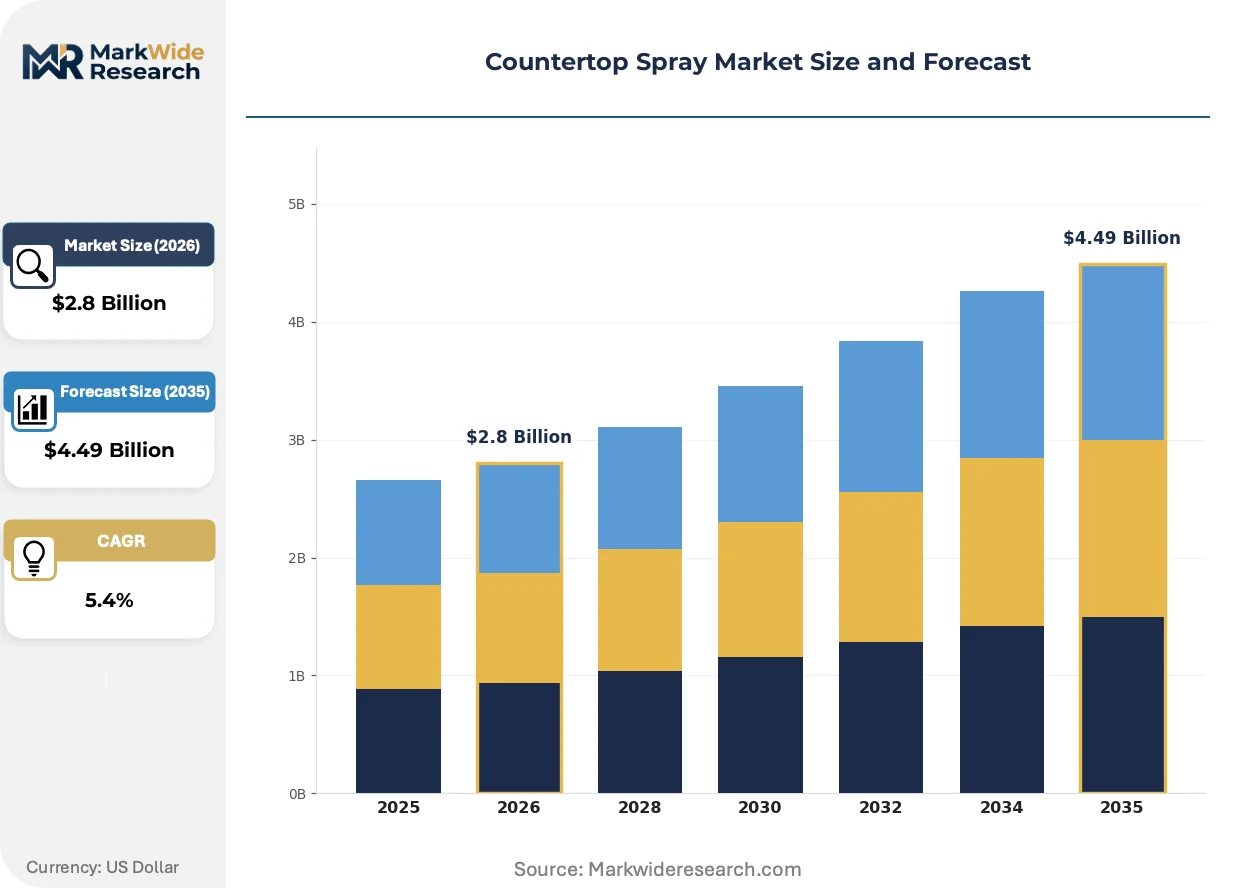
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial, Degreaser, All-Purpose, Glass Cleaner End User: Households, Restaurants, Hotels, Offices Packaging Type: Bottles, Spray Cans, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Reckitt Benckiser Group plc, The Clorox Company, Procter & Gamble Company, S.C. Johnson & Son, Inc., Henkel AG & Co. KGaA, Ecolab Inc., Werner & Mertz GmbH, Gold Eagle Co., Caldrea Company, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Spray Market Strategic Shifts
Trigger-spray dosing precision and fragrance encapsulation technologies are elevating product differentiation beyond cleaning efficacy alone, while regulatory disclosure mandates push transparency into supply chain chemistry.
Electrochemical activation devices for on-site generation of hypochlorous acid and other sanitizers are electrifying commercial kitchen procurement in California and Texas metropolitan clusters. Large-scale restaurant operators are piloting these systems to eliminate shipping costs and shelf-life constraints of pre-formulated liquids. The technology is compressing demand for conventional bottled countertop sprays in high-volume accounts while creating aftermarket concentrate cartridge revenue streams.
REACH compliance requirements from ECHA are restricting quaternary ammonium compound concentrations in formulations destined for European export channels. Manufacturers serving dual US-EU markets are bifurcating product lines rather than pursuing lowest-common-denominator chemistry. Antimicrobial variants with elevated cationic surfactant loads face reformulation pressure, while all-purpose segments adapt more readily to cross-jurisdictional standards.
Subscription-based replenishment models are displacing retail impulse purchasing among dual-income households with consistent cleaning routines. Direct-to-consumer brands are capturing this behavioral shift through mobile-optimized reordering interfaces and predictive shipping algorithms. Urban coastal markets in the United States show the highest subscription penetration, with metropolitan food service clusters slower to abandon traditional distributor relationships.
Countertop Spray Market Segmentation
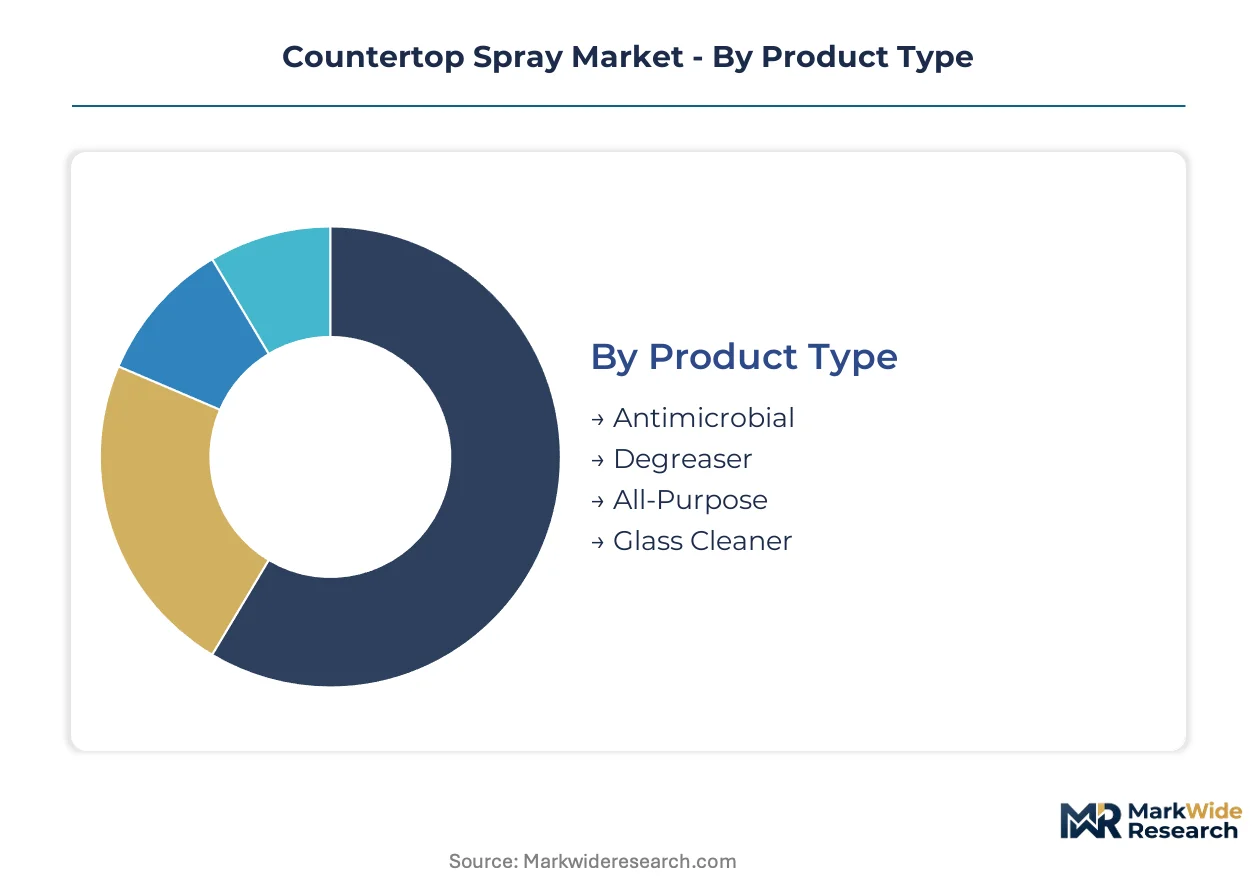
Countertop spray purchasing decisions fragment sharply across use environment, packaging economics, and regulatory exposure. Each segmentation dimension reveals distinct margin structures and formulation requirements that shape supplier strategy.
Product Type:
Buyers in this category separate by surface sensitivity and pathogen exposure risk rather than price alone.
- All-Purpose:Formulations span pH 6.0-9.0 with amphoteric surfactant systems compatible with laminate, sealed wood, and stone substrates. Demand concentrates in residential renovation corridors across California and Texas where multi-surface convenience governs purchasing. SKU proliferation pressure rises as stone and quartz countertop penetration forces pH-neutral line extensions.
- Antimicrobial:EPA FIFRA-registered formulations incorporate quaternary ammonium compounds or hypochlorous acid precursors at concentrations requiring efficacy substantiation. Healthcare-adjacent food service in hospital cafeterias and medical office break rooms drives procurement beyond traditional hospitality channels. ECHA REACH compliance forces bifurcation for suppliers serving European export markets.
- Degreaser:Alkaline formulations with pH 10.0-11.5 deploy solvent blends and chelating agents for protein and lipid soil removal on stainless steel commercial surfaces.
- Glass Cleaner:Ammonia-free variants with isopropanol and glycol ether solvents target streak-free aesthetic maintenance on display surfaces and food shields.
Volume sits with All-Purpose; growth tilts toward Antimicrobial.
End User:
Procurement authority in this category divides between centralized institutional buyers and dispersed household decision-makers with divergent sustainability priorities.
- Households:Subscription-based replenishment models capture dual-income households with consistent cleaning routines, particularly in urban coastal markets. Pouch concentrate systems reduce per-use plastic intensity and electrify sustainability-oriented purchasing through mobile-optimized reordering interfaces.
- Restaurants:Immediate-use convenience governs purchasing in restaurant procurement channels where distributor relationships dominate and electrochemical activation devices are compressing demand for conventional bottled sprays in high-volume accounts. California metropolitan food service clusters show fastest pilot adoption of on-site generation systems.
- Hotels:Brand-standard compliance requirements drive specification of fragrance-profiled formulations with consistent guest experience across property portfolios.
- Offices:Facility management contractors prioritize cost-per-use metrics and bulk procurement compatibility over formulation sophistication.
Restaurants command the largest transaction values; households are expanding most quickly.
Packaging Type:
Cost-per-ounce economics and waste reduction mandates create tension between convenience and circularity in this category.
- Bottles:PET and HDPE containers with mechanical trigger sprayers retain dominance in commercial channels where durability and immediate-use convenience govern purchasing decisions. Backward-integrated supply chains among top-tier manufacturers create sourcing bottlenecks for non-integrated competitors seeking bleach precursor compatibility.
- Pouches:Flexible film concentrate systems require consumer dilution and refill-compatible bottle reuse, gaining traction fastest among sustainability-oriented household buyers in subscription models. California and New York metropolitan areas show highest penetration.
- Spray Cans:Aerosol actuators with hydrocarbon propellants face California Air Resources Board VOC limit constraints and workplace use protocol restrictions under OSHA hazard communication standards.
- Bulk Containers:5-gallon and drum formats serve institutional accounts with captive dispensing systems and trained handling protocols.
Bottles hold the volume base; pouches show the steepest expansion trajectory.
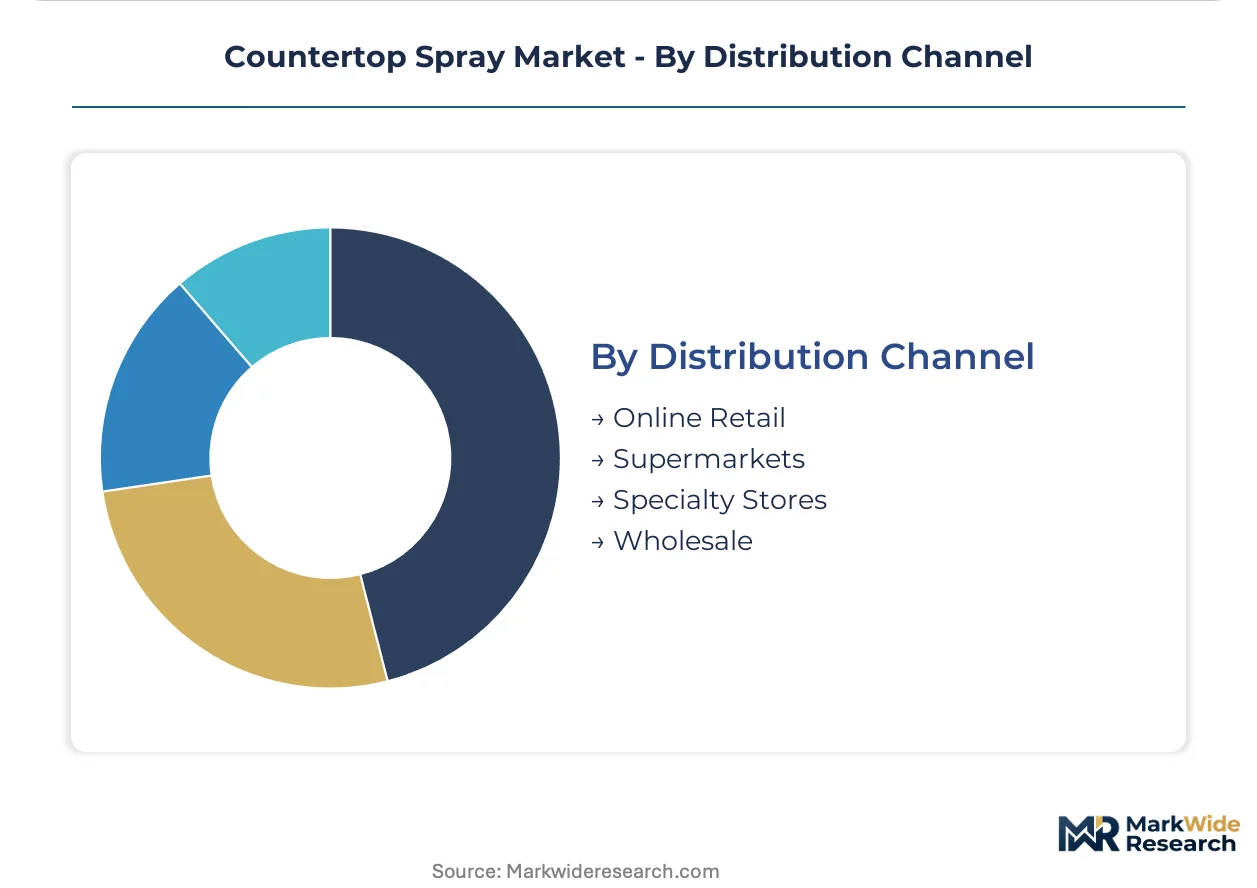
Distribution Channel:
Channel selection in this category determines margin capture and data access for formulation optimization.
- Online Retail:Direct-to-consumer platforms bypass traditional retail markups and capture operator data through predictive shipping algorithms. Specialized e-commerce platforms for foodservice are compressing channel margins while enabling direct-to-foodservice distribution.
- Supermarkets:Impulse purchasing and brand visibility drive placement economics for all-purpose and glass cleaner variants in mass-market formulations.
- Specialty Stores:Home improvement and kitchen design retailers capture premium renovation segments with pH-neutral stone-compatible formulations and fragrance technology differentiation.
- Wholesale:Janitorial supply houses maintain restaurant and hotel relationships through consolidated procurement and technical service support.
Wholesale retains the volume anchor; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Linear alkylbenzene sulfonate feedstock availability from Gulf Coast petrochemical complexes anchors North American formulation capacity. European bio-surfactant fermentation infrastructure is expanding around rapeseed and palm oil derivatives. Asian manufacturing concentrates on cost-optimized alcohol ethoxylate production for export markets.
United States
Metropolitan food service clusters in California, Texas, and New York drive concentrated demand for antimicrobial and degreaser formulations. The EPA's Safer Choice program and California Air Resources Board VOC limits constrain solvent selection for products sold in Western states. Dallas-Fort Worth and Houston anchor commercial kitchen supply chains where electrochemical activation devices are displacing conventional bottled sprays in high-volume restaurant accounts.
Germany
Institutional procurement in federal and state facilities is establishing minimum bio-based content thresholds for cleaning products. ECHA REACH compliance requirements restrict quaternary ammonium compound concentrations in formulations destined for domestic use and re-export. The Rhine-Ruhr industrial corridor hosts concentrated surfactant manufacturing capacity serving pan-European distribution networks.
China
Rapid urbanization and expanding middle-class households are amplifying demand for multi-surface convenience cleaners in tier-one and tier-two cities. The Ministry of Ecology and Environment is tightening discharge standards for surfactant manufacturing facilities along the Yangtze River. Shanghai and the Yangtze River Delta concentrate domestic formulation capacity and e-commerce distribution infrastructure for direct-to-consumer brands.
India
Rising dual-income urban households are adopting subscription-based replenishment models for household cleaning products. The Bureau of Indian Standards is developing voluntary standards for surface cleaner efficacy claims and ingredient disclosure. Mumbai and Delhi-NCR represent the deepest penetration of pouch concentrate systems and mobile-optimized reordering platforms among sustainability-oriented buyers.
Brazil
Expanding hospitality and food service sectors in São Paulo and Rio de Janeiro are driving procurement of specialized degreaser formulations for commercial kitchens. ANVISA regulates antimicrobial claims and ingredient safety for surface cleaning products with increasing stringency. The São Paulo metropolitan area anchors both manufacturing capacity and distributor networks serving the Mercosur trade bloc.
Countertop Spray Market Competitive Environment
Global majors compete with regional champions across formulation chemistry, regulatory compliance, and distribution channel access. The vendor base organizes around three tiers: multinational consumer goods conglomerates with backward-integrated supply chains, mid-sized specialty chemical firms with regional formulation expertise, and direct-to-consumer brands leveraging subscription economics. Dominant competitive moves include captive supply of bleach precursors and fragrance technology partnerships.
Within the multinational tier, Reckitt Benckiser Group plc, The Clorox Company, and Procter & Gamble Company exemplify divergent strategic archetypes. Reckitt Benckiser occupies a position emphasizing antimicrobial efficacy claims across multiple regulatory jurisdictions. The Clorox Company anchors its competitive stance through upstream control over bleach precursor supply chains. Procter & Gamble sits within the fragrance-differentiation vector, leveraging dosing precision in trigger-spray mechanisms and sensory technology partnerships. These three entities collectively represent the scale-driven, integration-heavy, and sensory-engineering archetypes that define competitive positioning in developed markets.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| The Clorox Company |
| Procter & Gamble Company |
| S.C. Johnson & Son, Inc. |
| Henkel AG & Co. KGaA |
| Ecolab Inc. |
| Werner & Mertz GmbH |
| Gold Eagle Co. |
| Caldrea Company, LLC |
| Others |
Value Chain & Pricing Dynamics
Linear alkylbenzene sulfonate spot prices on the Gulf Coast petrochemical index cascade through three pricing tiers, compressing margins for non-integrated formulators while rewarding backward-integrated majors with captive surfactant production.
Pricing Analysis
Service bundling separates EPA FIFRA registration support from unbundled commodity formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and fragrance technology sophistication. Price erosion runs through the economy tier as private-label pouch concentrates flood subscription channels. Quick-service restaurant procurement teams exhibit highest price sensitivity, while hospital facility managers prioritize efficacy substantiation over per-ounce cost.
Supply Chain Analysis
Single-source vulnerability sits with Louisiana and Texas linear alkylbenzene sulfonate production clusters. Formulation chemistry draws from Gulf Coast petrochemical complexes, European bio-surfactant fermentation infrastructure, and Asian alcohol ethoxylate manufacturing. Tariff exposure on palm oil derivatives threatens bio-based content compliance for institutional buyers. Distribution runs through janitorial supply houses for commercial accounts and direct-to-consumer platforms for household subscription segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical activation devices are displacing conventional bottled sprays in high-volume restaurant accounts, compressing demand for legacy pre-formulated liquids while creating aftermarket concentrate cartridge revenue streams.
For Market Incumbents: Deepen captive supply of bleach precursors and fragrance encapsulation technology partnerships to defend against pouch concentrate entrants and on-site generation system vendors. Expand California production capacity to minimize cross-state VOC compliance costs and capture metropolitan food service cluster demand. For New Entrants and Emerging Players: Specialty e-commerce platforms for foodservice represent the most penetrable channel, bypassing entrenched janitorial supply house relationships. Target pH-neutral stone-compatible formulations for premium residential renovation segments in California and Texas where incumbent SKU proliferation lags countertop material innovation. Lead with mobile-optimized subscription interfaces to capture dual-income household replenishment behavior. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier regional formulators with EPA FIFRA registrations and established California distribution in the United States. Long-term viability hinges on bio-surfactant supply chain verification and electrochemical activation device compatibility. Watch California Air Resources Board VOC limit expansion timelines as the inflection signal for accelerated low-emission solvent adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Precursors | Gulf Coast petrochemical capacity secures margin stability against linear alkylbenzene sulfonate price volatility. |
| Direct-to-Foodservice E-commerce Launch | Specialized platforms compress channel margins while capturing operator data for formulation optimization. |
| Bio-based Content Certification Program | Verified renewable surfactant supply meets federal and state procurement mandates for institutional buyers. |
| Electrochemical Activation Compatibility | Aftermarket concentrate cartridges align with on-site generation pilots in Dallas-Fort Worth and Houston. |
| Fragrance Technology Partnership | Encapsulation expertise masks base odors in reduced-VOC solvent systems for California compliance. |
Study Parameters
Trade journals, customs records, and EPA FIFRA registration databases formed the secondary backbone, supplemented by primary interviews with formulation chemists, restaurant procurement directors, and janitorial supply house category managers. Bottom-up volume estimates from packaging format and end-use segmentation triangulated against top-down value projections derived from surfactant feedstock cost structures.
Historical trendline analysis across the analysis window identified inflection points in pouch concentrate adoption and electrochemical activation device penetration. The modeling framework incorporated product type, packaging format, end-use environment, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth rates across segment-level demand drivers, with California VOC compliance timelines and bio-based procurement mandates serving as key forecast inputs.
Caveats apply where EPA Safer Choice program expansion or ECHA REACH quaternary ammonium compound restriction tightening could materially shift the outlook for antimicrobial formulation viability. Forecasts reflect assumptions about subscription model retention rates and restaurant operator technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Laundry Detergent Market